
 Saphenous Vein Grafts Market | 2026-2036
Saphenous Vein Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Saphenous Vein Grafts Market Analytics
Hospital procurement networks are reconfiguring around value-based cardiac care bundles, shifting how saphenous vein graft suppliers engage with purchasing committees. Medtronic leverages its integrated cardiovascular portfolio to sustain dominant positions in conduit supply chains across integrated delivery networks. Abbott competes through specialized endovascular platforms that complement graft deployment workflows in hybrid procedure suites. Terumo Corporation anchors its presence in Japan through direct hospital partnerships and localized manufacturing of vascular access devices.
Saphenous vein grafts are autologous or processed vascular conduits, typically 2-4 mm in diameter, harvested from the greater saphenous vein and prepared for coronary or peripheral arterial bypass; they function as biological bridges restoring perfusion to ischemic myocardium or limb tissue. Modifier grafts and composite grafts occupy the premium tier where surgeons demand customized lengths and diameters for complex multi-vessel revascularization. Conduit grafts dominate hospital volume purchasing through standardized configurations that reduce operative preparation time. Applications in coronary bypass procedures generate the deepest margin pools, while hybrid procedures represent the fastest-growing segment as catheter-based techniques merge with open surgical grafting.
FDA quality system regulations and EMA medical device directives enforce biocompatibility, endothelial preservation, and sterility benchmarks that determine market access for processed allografts and synthetic alternatives. ISO 13485 certification requirements shape supplier qualification processes, particularly for bovine-derived and synthetic graft materials entering regulated markets. Stakeholders must monitor evolving MDR compliance timelines in Europe and CMS reimbursement adjustments for coronary artery bypass procedures in the United States.
Market Dynamics
Cardiac surgery programs are consolidating purchasing authority through integrated delivery networks, forcing saphenous vein graft suppliers to restructure their hospital engagement models around value-based care bundles rather than individual product transactions.
Growth Catalysts
- MDR Compliance Timelines:EMA's Medical Device Regulation implementation is accelerating hospital qualification of certified conduit suppliers, filtering out non-compliant manufacturers and concentrating procurement among validated vendors.
- Hybrid Procedure Suites:Cardiac catheterization labs are expanding surgical capabilities, creating demand for grafts compatible with both open and endovascular techniques in single-procedure settings.
- Aging Demographics in Japan:METI healthcare infrastructure investments are expanding tertiary cardiac capacity to address coronary artery disease prevalence among the elderly population.
Market Restraints
- Bovine-Derived Material Volatility:Input costs for biological scaffolds fluctuate with livestock supply chains and zoonotic disease screening requirements, compressing margins on processed allografts.
- Single-Source Concentration:Harvested autologous vein supply depends on individual patient anatomy, creating batch-to-batch variability that limits standardization in high-volume manufacturing.
- Synthetic Polymer Substitution:Expanded polytetrafluoroethylene and polyurethane alternatives are capturing peripheral bypass indications where long-term patency requirements are less stringent.
Strategic Opportunities
- India's Tertiary Expansion:CDSCO streamlined medical device registration pathways are enabling first-mover positioning in cardiac centers emerging in Mumbai, Delhi, and Bangalore.
- Endothelial Seeding Convergence:Bioreactor cell culture systems combined with decellularization protocols are enabling off-the-shelf living grafts with reduced thrombogenicity.
- CMS Bundled Payment Models:United States reimbursement incentives for episode-based cardiac care are rewarding suppliers who demonstrate graft patency outcomes across 90-day postoperative windows.
Industry Challenges
- Microsurgical Anastomosis Training:Declining open-chest procedure volumes in training programs are reducing surgeon proficiency with hand-sewn distal anastomosis techniques essential for graft success.
- ISO 13485 Certification Timelines:Quality system audits for processed biological products require 18-24 month validation cycles that delay market entry for novel conduit formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saphenous Vein Grafts Market |
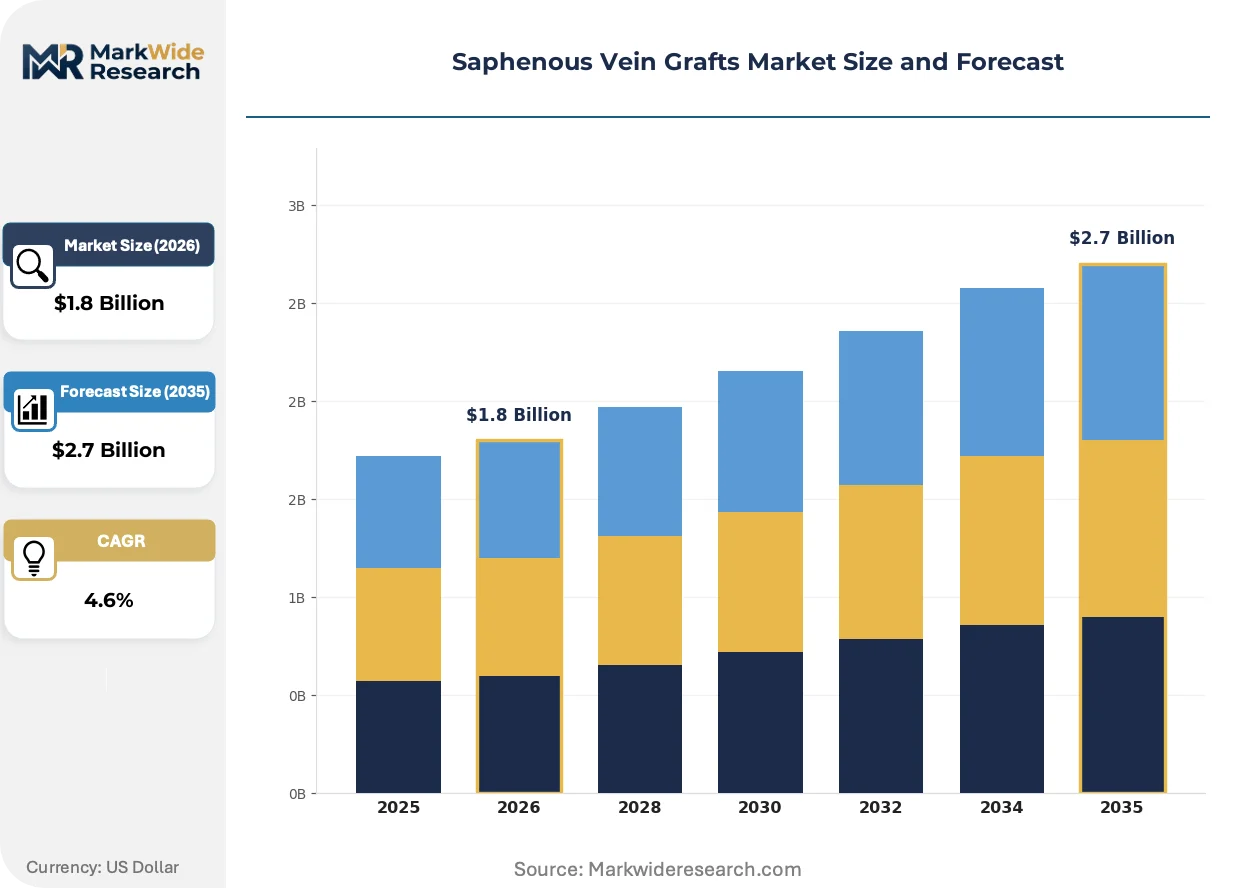
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modifier Grafts, Composite Grafts, Conduit Grafts, Pseudo-Grafts Application: Coronary Bypass, Peripheral Bypass, Endovascular Repair, Hybrid Procedures End User: Hospitals, Surgical Centers, Outpatient Facilities, Academic Institutions Material: Bovine Grafts, Synthetic Grafts, Allografts, Others |
| Companies Covered | LeMaitre Vascular, Abbott, Boston Scientific Corporation, Terumo Corporation, Getinge AB, Medtronic, CryoLife, LifeNet Health, Hancock Jaffe Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saphenous Vein Grafts Market Evolving Landscape
Digital preoperative planning platforms are restructuring how cardiac surgeons select and size conduits, shifting competitive advantage from physical inventory breadth toward integrated workflow software.
Computational fluid dynamics modeling is virtualizing graft selection decisions before incision. Tertiary hospitals in Germany and the United States are deploying patient-specific hemodynamic simulations to predict patency outcomes across multiple conduit options. This capability is virtualizing the traditional reliance on surgeon experience and standardized sizing charts, compressing operative decision time while elevating evidence-based selection criteria.
EMA's MDR Article 10 clinical evidence requirements are mandating post-market surveillance systems for biological vascular grafts. Manufacturers must now maintain active implant registries tracking patency and adverse events across European hospital networks. Processed allograft suppliers with limited historical data are investing in retrospective clinical studies to meet notified body expectations for renewed CE marking.
Hospital value analysis committees are consolidating supplier relationships around outcome guarantees rather than unit pricing. Integrated delivery networks in the United States are negotiating multi-year contracts tying graft procurement payments to documented 12-month patency rates. This restructuring is most visible in Medicare Advantage–dominated markets where providers bear full financial risk for coronary revascularization episodes.
Saphenous Vein Grafts Market Segmentation
Saphenous vein graft procurement cycles vary dramatically across product configurations, with standardized conduits turning over monthly while customized composite grafts move through quarterly planning cycles. Hospital value analysis committees weight these velocity differences heavily when structuring supplier contracts and safety stock levels.
Product Type:
Inventory velocity separates commodity conduit formats from engineered graft systems, with cycle times ranging from two-week replenishment for standard SKUs to twelve-week lead times for patient-matched configurations.
- Modifier Grafts:These adjustable-diameter conduits incorporate telescoping segments or diameter-transition zones that accommodate anatomical variations without operative tailoring. Demand clusters at Cleveland Clinic and German Heart Center Berlin where complex multi-vessel cases require intraoperative flexibility. Surgeon preference for reduced anastomosis count drives procurement despite 40% price premiums over standard conduits.
- Composite Grafts:Multi-segment constructs combining arterial and venous sections or synthetic-venous hybrids address sequential bypass requirements in diffuse coronary disease. Massachusetts General Hospital and Tokyo University Hospital have established dedicated composite graft programs. Manufacturing complexity limits supplier pool to three FDA-cleared vendors, creating procurement concentration risk.
- Conduit Grafts:Single-lumen standardized configurations dominate hospital purchasing through high-volume, low-variability supply agreements.
- Pseudo-Grafts:Tissue-engineered scaffolds with decellularized matrices serve research applications and compassionate-use protocols.
Conduit grafts anchor the volume base while composite grafts gain share at the steepest rate.
Application:
Reimbursement intensity varies threefold across clinical settings, with coronary indications commanding the highest episode payments and peripheral bypass operating on compressed margins.
- Coronary Bypass:Revascularization of ischemic myocardium through aortocoronary anastomosis generates the deepest margin pools and most stringent patency requirements. NewYork-Presbyterian and Mayo Clinic Rochester drive demand for premium graft configurations. CMS bundled payment models reward suppliers demonstrating 90-day outcome metrics.
- Hybrid Procedures:Combined catheter-based intervention and surgical grafting in single-episode settings represent the most rapidly expanding application segment. Johns Hopkins Hospital and Charité Berlin have deployed dedicated hybrid suites requiring graft compatibility with fluoroscopic imaging and endovascular delivery systems. Workflow integration requirements favor suppliers with integrated device portfolios.
- Peripheral Bypass:Lower-extremity revascularization for critical limb ischemia utilizes grafts with reduced long-term patency specifications.
- Endovascular Repair:Aneurysm exclusion procedures incorporate grafts delivered through transfemoral access routes.
Coronary bypass procedures command the revenue concentration while hybrid procedures climb the fastest.
End User:
Capital intensity and case complexity stratify purchasing authority across facility types, with academic medical centers maintaining distinct technical specifications from ambulatory settings.
- Hospitals:Tertiary cardiac centers with open-heart surgery programs constitute the primary demand channel for all graft categories. Cedars-Sinai Medical Center and Osaka University Hospital maintain direct supplier relationships bypassing distributor markups. Value-based care contracts increasingly tie procurement payments to outcome documentation.
- Surgical Centers:Ambulatory facilities with limited cardiac capabilities concentrate on peripheral bypass applications.
- Outpatient Facilities:Same-day discharge settings utilize grafts for venous access and dialysis shunt procedures.
- Academic Institutions:Research hospitals and training programs drive demand for experimental graft configurations and investigator-initiated studies.
Hospitals retain the procurement volume leadership while surgical centers expand most quickly.
Material:
Biological origin and processing history determine regulatory pathway, sterilization requirements, and shelf-life constraints across material categories.
- Bovine Grafts:Decellularized bovine pericardium and mesenteric vein scaffolds offer off-the-shelf availability without patient harvest morbidity. Edwards Lifesciences and Medtronic have secured FDA PMA approvals for specific bovine-derived configurations. Zoonotic disease screening requirements under USDA regulations add 6-8 weeks to production cycles.
- Allografts:Cadaveric human saphenous vein segments preserved through cryopreservation or lyophilization serve patients with inadequate autologous conduit. LifeNet Health and CryoLife dominate tissue bank supply chains. FDA 21 CFR Part 1271 human cell and tissue regulations mandate donor eligibility documentation extending procurement timelines.
- Synthetic Grafts:Expanded polytetrafluoroethylene and polyurethane alternatives compete on price and supply predictability.
- Others:Autologous harvested vein and emerging bioengineered constructs occupy niche positions.
Synthetic grafts maintain the volume foundation while bovine grafts expand at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where bundled reimbursement models reward graft patency outcomes, while procurement in India and Brazil operates on compressed margins driven by public hospital tender systems.
United States
Medicare Advantage penetration and CMS bundled payment models for coronary revascularization episodes concentrate purchasing authority within integrated delivery networks. FDA quality system regulations under 21 CFR Part 820 enforce biocompatibility and sterility benchmarks that filter supplier qualification. The Cleveland Clinic and Mayo Clinic Rochester anchor demand for premium modifier and composite graft configurations through high-complexity cardiac surgery volumes.
Germany
EMA Medical Device Regulation implementation accelerates hospital qualification of certified conduit suppliers while filtering non-compliant manufacturers from procurement rosters. The country's statutory health insurance system maintains stringent cost-effectiveness thresholds for biological graft reimbursement. German Heart Center Berlin and Charité Universitätsmedizin drive adoption of computational fluid dynamics-guided graft selection through dedicated hybrid procedure suites.
Japan
METI healthcare infrastructure investments expand tertiary cardiac capacity to address coronary artery disease prevalence among the elderly population. PMDA regulatory pathways for processed biological products require extended stability validation that extends market entry timelines for novel formats. Tokyo University Hospital and Osaka University Hospital maintain direct supplier relationships that bypass distributor markups through concentrated purchasing authority.
India
CDSCO streamlined medical device registration pathways enable first-mover positioning in cardiac centers emerging in Mumbai, Delhi, and Bangalore. Public hospital procurement through centralized medical equipment tenders compresses margins on standard conduit configurations. Fortis Escorts Heart Institute and Apollo Hospitals in Chennai anchor private-sector demand for premium graft categories through medical tourism and cash-pay cardiac surgery volumes.
Saphenous Vein Grafts Market Competitive Landscape
Diversified cardiovascular conglomerates and specialized biological tissue processors split the market into distinct capability tiers. Consolidation pressure intensifies as hospital value analysis committees reduce approved vendor lists to three or fewer suppliers per graft category. Integrated device manufacturers leverage catheter-lab relationships to capture hybrid procedure workflow integration, while tissue banks compete on cryopreservation quality and donor traceability documentation. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers seek backward integration into biological scaffold supply.
Within the diversified cardiovascular tier, Medtronic and Abbott exemplify integrated portfolio strategies that span graft supply through endovascular delivery systems. Terumo Corporation anchors the Asia-Pacific position through direct hospital partnerships and localized manufacturing. CryoLife and LifeNet Health occupy the biological tissue processing segment where cryopreservation expertise and donor network scale determine competitive position. Hancock Jaffe Laboratories and LeMaitre Vascular represent mid-scale specialists focused on vascular conduit innovation.
| Leading Market Players |
|---|
| LeMaitre Vascular |
| Abbott |
| Boston Scientific Corporation |
| Terumo Corporation |
| Getinge AB |
| Medtronic |
| CryoLife |
| LifeNet Health |
| Hancock Jaffe Laboratories |
| Others |
Value Network & Pricing Analysis
Air freight corridors connecting Frankfurt and Chicago transmit cost volatility from biological scaffold harvest sites to hospital procurement committees, amplifying price spreads between standardized conduits and patient-matched configurations while concentrating supplier qualification around EMA and FDA certified manufacturers.
Pricing Analysis
The customization-premium spread separates modifier grafts commanding 40% price premiums from commodity conduit configurations, with three-tier pricing structure across premium, standard, and economy levels anchored by ISO 13485 certification grade and operative preparation time. Price differentiation hinges on endothelial preservation quality and surgeon training requirements, while cost compression in standard conduit tiers intensifies due to synthetic polymer substitution in peripheral indications. Academic medical centers exhibit lowest price sensitivity, whereas public hospital tender systems in emerging markets drive aggressive unit-cost negotiations.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates supply chain risk calculus for processed allograft materials, with biological scaffold production concentrating in the United States, Germany, and Switzerland. Raw material dependencies encompass bovine pericardium from USDA-inspected herds, cadaveric tissue from accredited donor networks, and cryopreservation media from specialized chemical suppliers. Single-source vulnerability pervades composite graft manufacturing where three FDA-cleared vendors control proprietary hybrid-construct technologies. Distribution runs through integrated delivery network value analysis committees rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as hybrid procedure adoption creates demand niches for grafts compatible with both open surgical and endovascular workflows, splintering procurement authority between cardiac surgery divisions and catheterization laboratory directors.
For Market Incumbents: Build outcome-data moats through active implant registries tracking 12-month patency rates across Medicare Advantage networks. Defensive consolidation moves center on backward integration into bovine scaffold supply chains and captive cryopreservation facility construction. Synthetic polymer substitution in peripheral bypass segments threatens margin pools, requiring capacity addition in endothelial seeding bioreactor systems to maintain premium positioning.
For New Entrants and Emerging Players: India's tertiary cardiac expansion offers the most penetrable geographic entry point, with CDSCO streamlined registration pathways enabling first-mover positioning in Mumbai and Delhi private hospital networks. White-space targets include composite graft manufacturing where FDA-cleared vendor concentration creates supply vulnerability, and endothelial seeding convergence technologies for off-the-shelf living grafts. Go-to-market execution should anchor on direct hospital partnerships bypassing distributor markups through concentrated purchasing authority at Fortis Escorts Heart Institute and Apollo Hospitals.
For Investors and Strategic Acquirers: Biological tissue processors with cryopreservation expertise and donor network scale represent the priority acquisition archetype, with LifeNet Health and CryoLife exemplifying target profiles with established FDA 21 CFR Part 1271 compliance infrastructure. Long-term viability frames around 90-day episode-based reimbursement maturation and hybrid suite penetration trajectories. The signal to watch is CMS bundled payment model expansion into coronary revascularization categories, which would accelerate outcome-guarantee contract adoption and filter supplier pools toward patency-data-rich incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | EMA Article 10 clinical evidence requirements filter non-compliant manufacturers from European procurement rosters. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic direct relationships bypass distributor markups through concentrated purchasing authority. |
| Reimbursement Strategy | CMS bundled payment models reward suppliers demonstrating graft patency outcomes across 90-day postoperative windows. |
| Software Companion Development | Computational fluid dynamics platforms virtualize graft selection decisions at German Heart Center Berlin. |
| CE Marking Pathway | Retrospective clinical studies satisfy notified body expectations for processed allograft renewed CE marking. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA filings, EMA MDR submission databases, hospital procurement contract registries, and CMS Medicare cost report data. Cardiac surgeons, hospital value analysis committee directors, biomedical engineers, and GPO contracts managers contributed qualitative input through structured interviews. SEC 10-K disclosures from diversified cardiovascular manufacturers and tissue bank accreditation records provided financial and operational validation. Bottom-up demand modeling across product configurations triangulates against top-down expenditure analysis from national health accounts.
Forecast inputs encompass procedural volume trajectories, reimbursement policy shifts, and regulatory compliance timelines across the projection horizon. Segmentation dimensions modeled include product type, application setting, end-user facility tier, and material origin. CAGRs derive from logarithmic trend fitting across historical expenditure patterns and elasticity-adjusted demand projections. Industry-specific inputs incorporate MDR implementation pace and hybrid suite deployment rates at Johns Hopkins Hospital and Charité Berlin.
The forecast holds incumbent behavior within observed patterns; aggressive moves by synthetic polymer manufacturers or endothelial seeding technology developers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Aortic Stents Grafts Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Global Embolotherapy Market