
 Cardiac Biomarkers Market | 2026-2036
Cardiac Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Biomarkers Market Intelligence
The bundling of multiple cardiac biomarkers into single diagnostic panels is consolidating testing workflows in clinical settings. Roche Diagnostics Corporation leverages its extensive immunoassay portfolio to offer comprehensive panels for broad cardiovascular risk assessment. Abbott Laboratories differentiates through its leadership in high-sensitivity troponin assays for point-of-care applications. Siemens Healthineers competes by integrating biomarker testing into its wider laboratory automation and digital health platforms.
Cardiac biomarkers are proteins, enzymes, or hormones released into the bloodstream in response to cardiac stress or injury. These analytes, such as Troponin I, are measured using immunoassays with high analytical sensitivity. Their primary function is to aid in the rapid diagnosis of acute myocardial infarction and to assess the severity of heart failure. While Troponin I assays dominate for Myocardial Infarction Diagnosis, B-type Natriuretic Peptide tests are expanding rapidly for Heart Failure Detection.
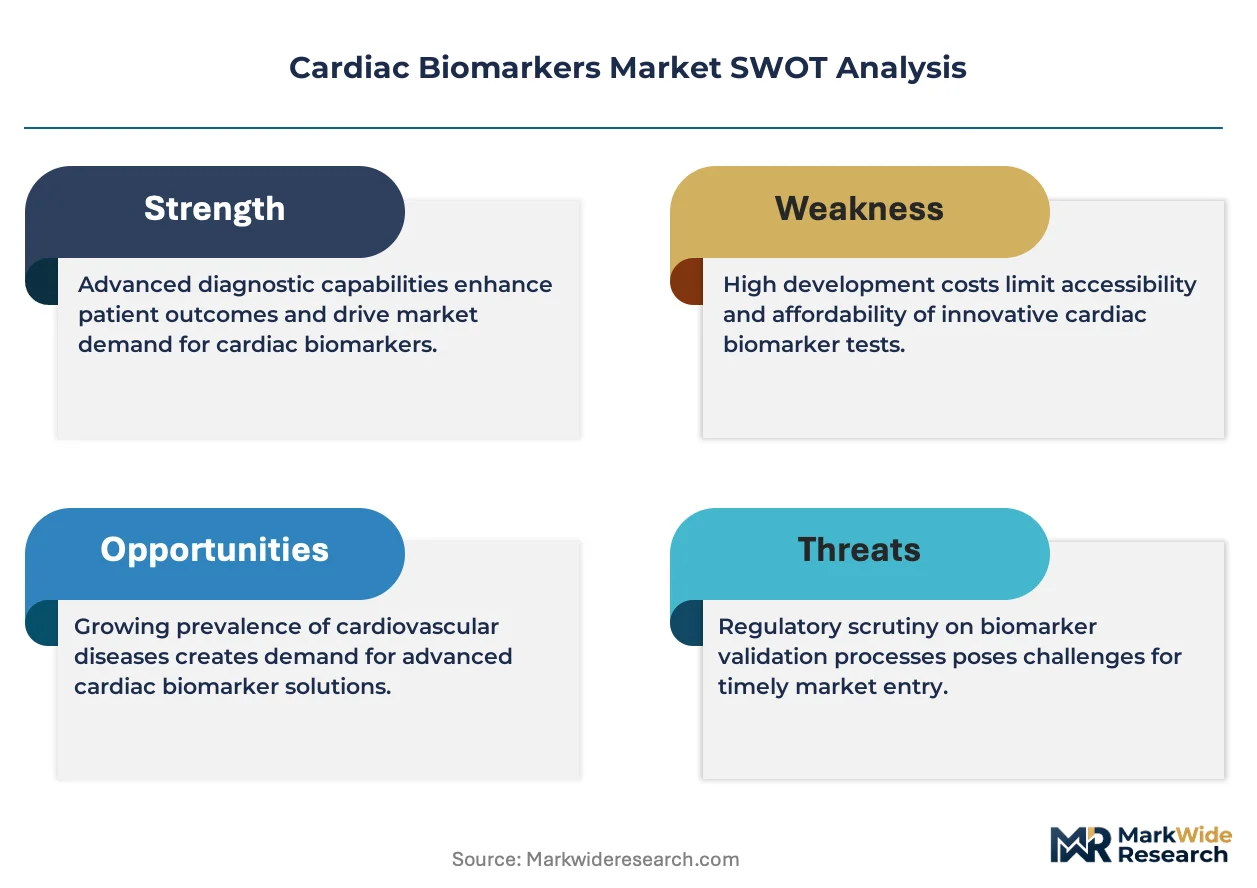
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA mandates stringent clinical validation for new biomarker assays. These frameworks establish performance requirements for sensitivity and specificity, directly influencing market access and product development timelines. Stakeholder success will depend on navigating the complex approval pathways for high-sensitivity assays and integrating them into decentralized, point-of-care diagnostic platforms.
Market Dynamics
The expansion of high-sensitivity assays into point-of-care testing formats is the primary force reshaping the market. This decentralization moves critical cardiac assessments from central laboratories directly to emergency departments and outpatient clinics, altering diagnostic workflows and timelines.
Growth Catalysts
- High-Sensitivity Assays:The development of high-sensitivity troponin assays improves diagnostic accuracy for acute myocardial infarction, enabling earlier clinical intervention.
- Infrastructure Expansion in China:The country's investment in emergency medical services and new hospitals creates significant demand for rapid cardiac testing capabilities.
- Point-of-Care Adoption:Integrating biomarker tests into point-of-care platforms allows for faster diagnostics in emergency rooms, shortening critical decision-making times.
Market Restraints
- Reimbursement Hurdles:Inconsistent reimbursement for novel, high-sensitivity biomarker panels limits widespread clinical adoption and return on investment in certain healthcare systems.
- Regulatory Scrutiny:Stringent validation demands from the US FDA and Europe's EMA for new assays extend development timelines and increase R&D costs.
- Assay Interference:Biotin interference in certain immunoassays presents a technical restraint, requiring specific protocols to ensure diagnostic accuracy.
Strategic Opportunities
- Predictive Analytics:Integrating artificial intelligence with multi-biomarker data offers an opportunity to develop algorithms for predictive cardiovascular risk stratification.
- Primary Care Integration:Expanding B-type Natriuretic Peptide (BNP) tests into primary care settings creates a new channel for early heart failure screening.
- Latin American Expansion:Modernizing hospitals in Brazil and Mexico present an underpenetrated market for point-of-care cardiac diagnostic solutions.
Industry Challenges
- Data System Integration:A key operational challenge is integrating data from diverse point-of-care testing devices into legacy hospital Electronic Health Record (EHR) systems.
- Assay Harmonization:The lack of standardization for assay calibration across manufacturers complicates result interpretation and hinders the establishment of universal clinical decision thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Biomarkers Market |
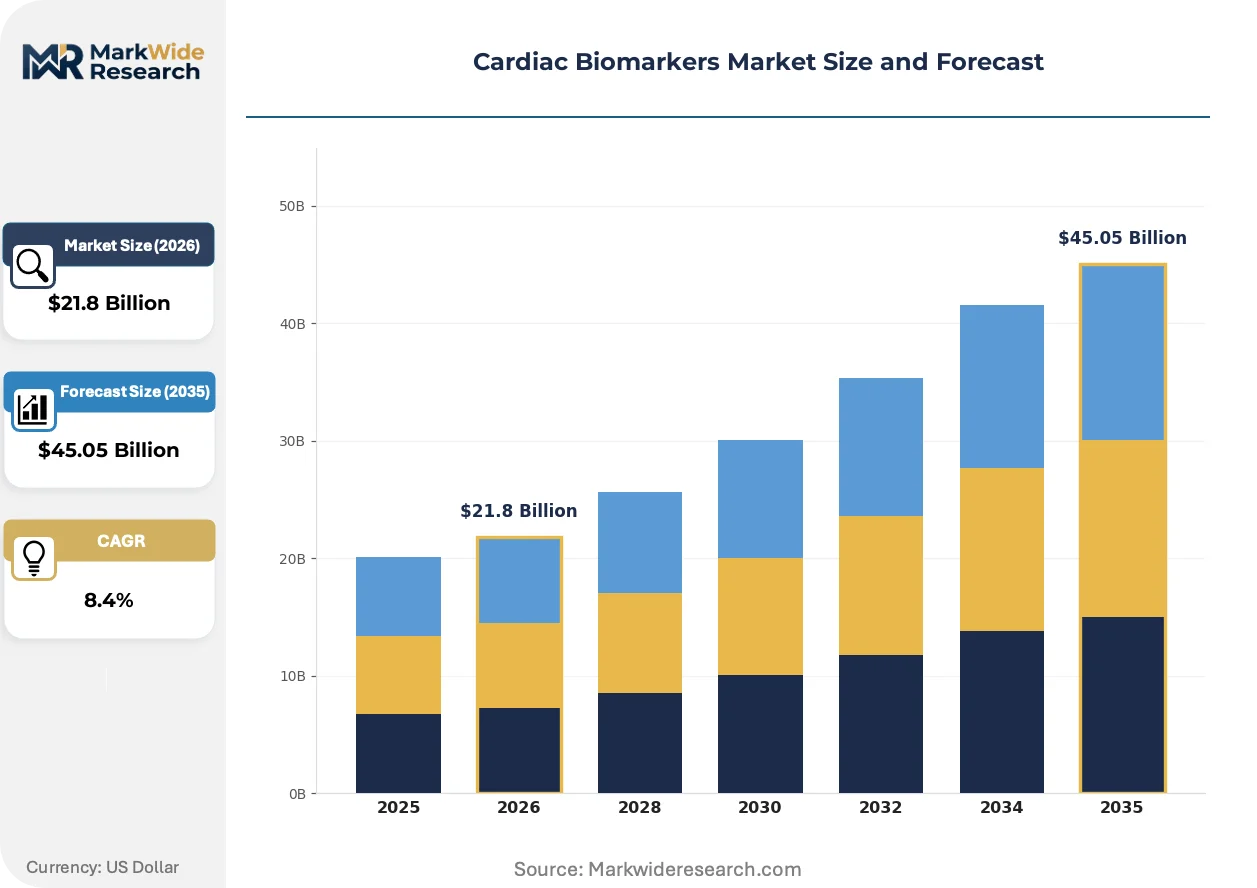
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $45.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Troponin I, Creatine Kinase-MB, Myoglobin, B-type Natriuretic Peptide, C-reactive Protein Application: Myocardial Infarction Diagnosis, Heart Failure Detection, Risk Stratification, Acute Coronary Syndrome Assessment End User: Diagnostic Laboratories, Cardiology Clinics, Research Institutes, Emergency Care Units Deployment: Point-of-Care Testing, Centralized Laboratory Testing, Home Monitoring Devices, Mobile Diagnostics |
| Companies Covered | Thermo Fisher Scientific, Randox Laboratories, Roche Diagnostics Corporation, Bio-Rad Laboratories, bioMérieux, Abbott Laboratories, Beckman Coulter, Becton Dickinson and Company, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Biomarkers Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of more sensitive analytical technologies with digital health platforms. This shift is enabling faster, more data-rich diagnostics outside of traditional laboratory environments.
Multiplex panels combine several cardiac biomarkers, such as troponins and natriuretic peptides, into a single test. Clinical laboratories and emergency departments are adopting these panels to gain a more holistic view of a patient's cardiovascular status from one sample. This technological evolution is consolidating diagnostic workflows, reducing the need for sequential, single-analyte testing and accelerating clinical decision-making.
Europe's In Vitro Diagnostic Regulation (IVDR) imposes stricter requirements for clinical evidence and post-market surveillance on all diagnostic tests. This forces manufacturers to generate more performance data, particularly for high-risk assays used in acute cardiac care. The cardiovascular diagnostics segment is consequently investing more in clinical trials to meet these European compliance standards.
A shift is occurring from simple reagent procurement to managed service contracts bundling instrumentation, consumables, and data management. Large hospital networks drive this change, seeking single-vendor solutions to standardize testing and streamline logistics across multiple sites. This trend is most visible in the US and Western Europe where integrated delivery networks are prevalent.
Cardiac Biomarkers Market Segmentation
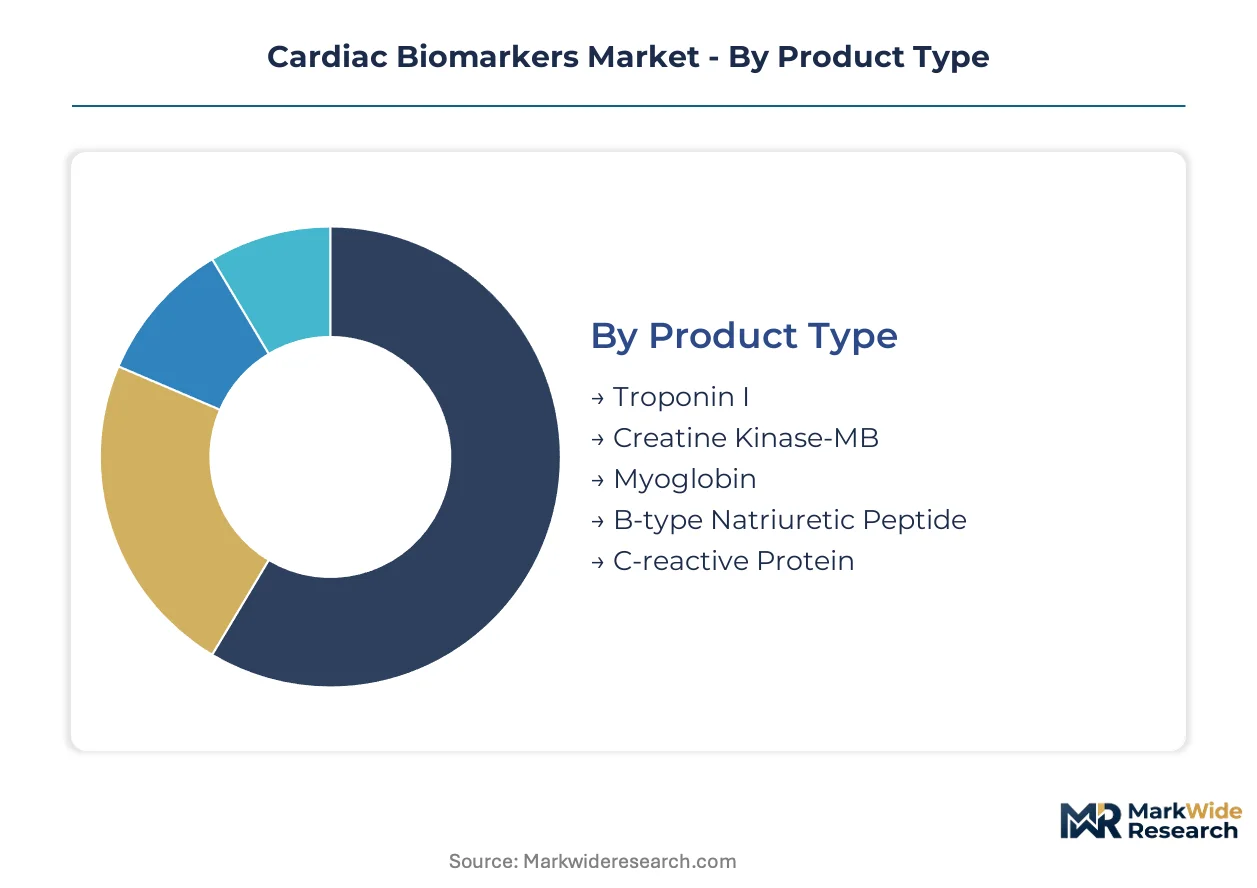
The cardiac biomarkers market is segmented to reflect the diverse diagnostic needs, technological advancements, and varied clinical settings where these critical tests are deployed. Understanding these segments is crucial for stakeholders to identify areas of high growth, targeted innovation, and evolving patient care pathways.
Product Type:
The cardiac biomarkers market segments by product type, reflecting a split between high-volume, established assays and more specialized, premium offerings.
- Troponin I:This protein is released from damaged heart muscle and serves as a highly specific indicator of cardiac injury. Demand for Troponin I assays is concentrating in emergency departments for rapid and accurate diagnosis of acute myocardial infarction.
- B-type Natriuretic Peptide:A hormone released by the heart in response to stress, indicating heart failure severity. Demand for BNP tests is expanding into primary care settings for early heart failure screening and management due to its prognostic value.
- Creatine Kinase-MB:An enzyme found predominantly in heart muscle, used as a secondary marker for myocardial damage.
- Myoglobin:An early but non-specific indicator of muscle damage, including cardiac muscle, often used in conjunction with other markers.
- C-reactive Protein:An inflammatory marker associated with systemic inflammation and increased cardiovascular disease risk.
Mature deployment sits with Troponin I. Newer deployment is concentrated in B-type Natriuretic Peptide.
Application:
Clinical utility drives the segmentation of cardiac biomarkers by application, reflecting diverse diagnostic and prognostic needs across patient populations.
- Myocardial Infarction Diagnosis:This application identifies cardiac muscle damage using specific biomarkers to confirm or rule out a heart attack. Demand for rapid MI diagnosis is concentrating in emergency medical services for immediate patient triage and intervention.
- Heart Failure Detection:This application assesses the severity and progression of heart failure using specific biomarkers. Demand for heart failure detection is expanding in cardiology clinics for chronic disease management and treatment optimization.
- Risk Stratification:Evaluates the future probability of cardiovascular events by combining biomarker data with patient clinical information.
- Acute Coronary Syndrome Assessment:Guides immediate management decisions for patients presenting with symptoms suggestive of acute coronary syndrome.
Market expansion is primarily driven by Heart Failure Detection, while Risk Stratification represents an area of significant clinical innovation.
End User:
Operational scale and patient flow patterns define the segmentation of cardiac biomarker end users, from centralized processing to immediate care environments.
- Diagnostic Laboratories:These are centralized facilities processing high volumes of patient samples using automated immunoassay platforms. Demand in diagnostic laboratories is concentrating in large hospital systems for comprehensive testing and cost-efficient operations.
- Emergency Care Units:These units provide rapid, point-of-care testing for critically ill patients presenting with acute cardiac symptoms. Demand in emergency care units is concentrating in urban hospitals for immediate diagnosis and accelerated treatment pathways.
- Cardiology Clinics:Outpatient settings using cardiac biomarkers for chronic disease management, follow-up, and risk assessment of their patient population.
- Research Institutes:Academic and industry entities exploring novel biomarkers, diagnostic methodologies, and disease mechanisms in cardiovascular health.
The largest volume of tests flows through Diagnostic Laboratories, with Emergency Care Units showing the most dynamic growth in decentralized testing.
Deployment:
Accessibility and speed of results are the primary differentiators in the deployment segmentation, ranging from immediate bedside analysis to remote patient management solutions.
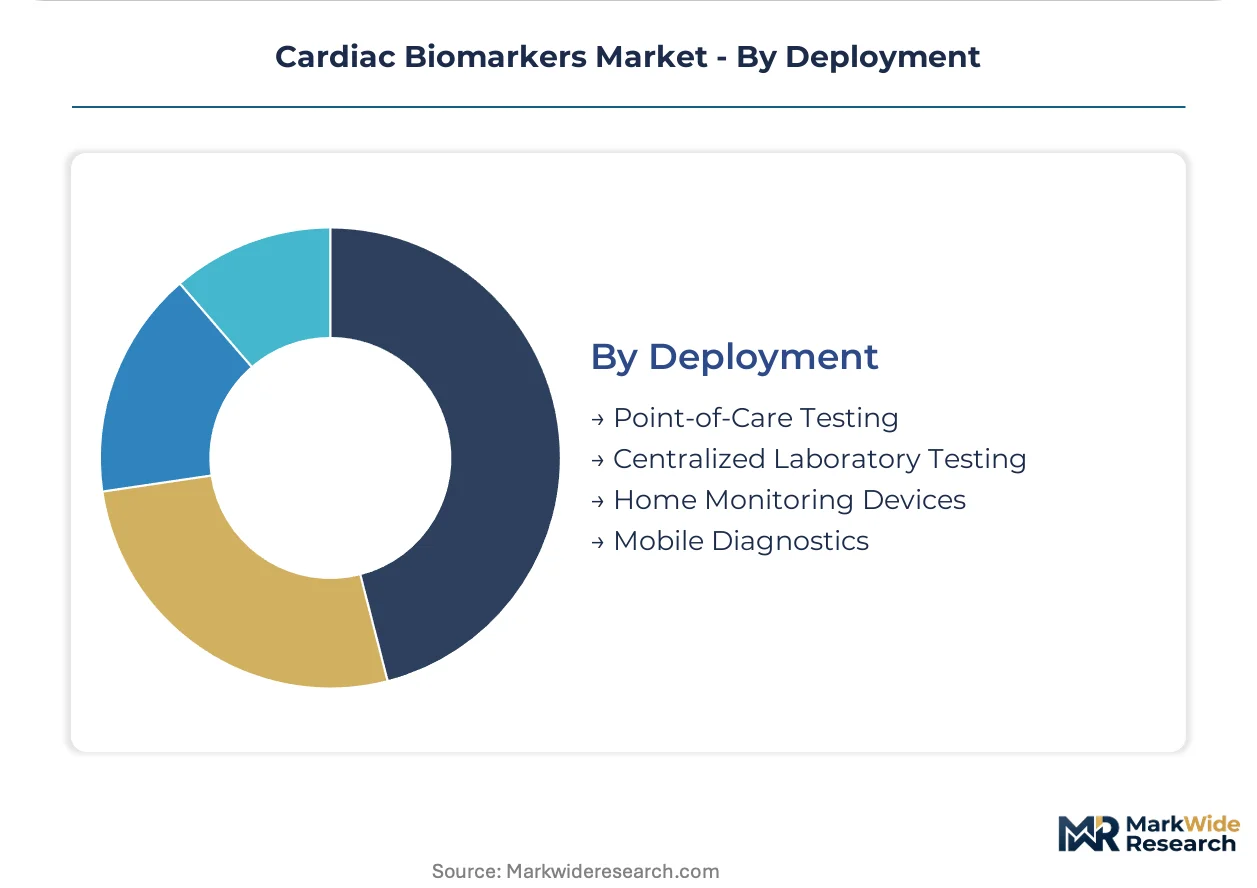
- Point-of-Care Testing:Diagnostic tests performed near the patient, often at the bedside or in an outpatient clinic, providing rapid results. Demand for point-of-care testing is concentrating in emergency departments and primary care settings for faster clinical decision-making.
- Centralized Laboratory Testing:The traditional method involving sample collection and transport to a central laboratory for analysis. Demand for centralized laboratory testing is concentrating in large hospital networks for high-throughput processing and specialized, high-sensitivity assays.
- Home Monitoring Devices:Emerging solutions enabling continuous or intermittent biomarker measurement by patients outside of traditional clinical settings.
- Mobile Diagnostics:Portable systems designed for field use or remote healthcare delivery, particularly in underserved geographical areas.
While Centralized Laboratory Testing remains the foundation, Point-of-Care Testing is experiencing the steepest expansion trajectory driven by technological advancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cardiac biomarkers market exhibits a clear divide between established innovation hubs and burgeoning consumption centers. Demand for cardiac biomarkers is global, but manufacturing and advanced assay development often concentrate in specific regions. Consumption patterns are shifting, with rapid expansion in emerging economies for diagnostic services, creating a dichotomy between established innovation hubs and burgeoning end-user markets.
United States
Demand for high-sensitivity troponin assays drives market expansion in the United States. The US FDA mandates rigorous clinical validation for new diagnostic tests, influencing product development timelines. Major academic medical centers and diagnostic laboratories in Boston and California lead innovation in biomarker research and adoption.
China
China's substantial investment in emergency medical services and new hospitals creates significant demand for rapid cardiac testing capabilities. The NMPA's regulatory approvals are crucial for market access and product distribution across the country. Urban centers like Beijing and Shanghai are rapidly integrating advanced diagnostic platforms into their healthcare systems.
Germany
German healthcare systems prioritize early and accurate cardiac diagnostics, boosting demand for advanced biomarker panels. European Medicines Agency (EMA) guidelines ensure high performance standards for in vitro diagnostics within the European Union. Research institutions and medical technology firms in Munich and Berlin contribute significantly to assay development.
India
India experiences growing demand for cardiac biomarkers due to expanding urban healthcare infrastructure and rising cardiovascular disease prevalence. The CDSCO regulates diagnostic kits, ensuring quality and safety standards for the Indian market. Large metropolitan areas like Mumbai and Delhi are integrating advanced cardiac testing into hospital networks.
Brazil
Brazilian hospitals are modernizing, leading to increased demand for point-of-care cardiac diagnostic solutions. ANVISA, Brazil's health surveillance agency, oversees the approval process for medical devices and diagnostic assays. Major cities such as São Paulo and Rio de Janeiro are key centers for adopting new diagnostic technologies.
Cardiac Biomarkers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the cardiac biomarkers market. The market exhibits a tiered structure, with large multinational corporations dominating centralized laboratory testing platforms and smaller innovators focusing on niche applications. Strategic archetypes include integrated diagnostic solution providers offering broad portfolios and specialized high-sensitivity assay developers. Companies pursue portfolio diversification to offer comprehensive panels and form strategic partnerships for point-of-care technology integration, aiming to capture new market segments.
Roche Diagnostics Corporation, a Swiss-based entity, exemplifies a diversified conglomerate leveraging an extensive immunoassay portfolio for comprehensive cardiac risk assessment. Abbott Laboratories, a US-headquartered firm, occupies a position as a leader in high-sensitivity troponin assays, particularly for point-of-care applications. Siemens Healthineers, a German-based medical technology company, represents an integrated diagnostic provider, combining biomarker testing with broader laboratory automation and digital health platforms. These companies anchor the market through their broad offerings and technological advancements, influencing diagnostic workflows across various clinical settings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Randox Laboratories |
| Roche Diagnostics Corporation |
| Bio-Rad Laboratories |
| bioMérieux |
| Abbott Laboratories |
| Beckman Coulter |
| Becton Dickinson and Company |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
European In Vitro Diagnostic Regulation (IVDR) compliance gates qualified supply, impacting both market access and premium-tier pricing for advanced cardiac biomarker assays. This stringent regulatory framework necessitates significant investment in clinical validation, directly influencing the cost structure of diagnostic products.
Pricing Analysis
Cost-down pressure on routine single-analyte tests accelerates because of increasing competition and volume-based procurement by large hospital systems. Pricing stratifies across premium multiplex panels from standard single-analyte tests, reflecting differentiation in diagnostic breadth and technological sophistication. Certification levels, such as US FDA approval and EMA compliance, drive significant price differentiation for high-sensitivity assays. Diagnostic laboratories, operating on high volumes, exhibit greater price sensitivity compared to emergency care units prioritizing rapid diagnostic turnaround.
Supply Chain Analysis
Skilled workforce availability in key manufacturing hubs like Germany and the United States underpins the production of complex immunoassay platforms and reagents. The supply chain draws from specialized raw materials, including high-purity antibodies and specific enzymes, primarily sourced from a concentrated global network. Regulatory restrictions, particularly those from China's NMPA, present a structural risk for market access and product distribution. Distribution runs through direct sales channels to large hospital networks and specialized medical device distributors for smaller clinics and outpatient settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiac biomarkers market operates under supply constraints, primarily due to the stringent regulatory validation required for novel, high-sensitivity assays, which props up premium pricing for approved solutions.
For Market Incumbents: Acquire specialized point-of-care technology developers to integrate rapid diagnostic capabilities directly into emergency workflows. This move mitigates the threat from agile, focused innovators and secures future channel control. Invest in advanced data integration platforms to connect diverse point-of-care devices with existing Electronic Health Record systems, enhancing operational efficiency and clinical utility.
For New Entrants and Emerging Players: Specialized diagnostic distributors represent a critical channel for penetrating underserved markets. Target primary care settings in regions like Latin America, where hospital modernization creates demand for early heart failure screening solutions. Focus product development on user-friendly, cost-effective B-type Natriuretic Peptide (BNP) tests designed for decentralized deployment, offering a clear value proposition for early disease management.
For Investors and Strategic Acquirers: Widespread adoption of AI-driven predictive analytics for cardiovascular risk stratification is the leading indicator that the market is ready for a new phase of value creation. Long-term viability remains strong for companies developing integrated diagnostic platforms that combine advanced biomarkers with digital health solutions. Target data analytics firms with proven expertise in multi-biomarker algorithms or specialized point-of-care device manufacturers with strong regulatory compliance records.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel high-sensitivity assays, securing market access in Europe and the US. |
| Platform Integration | Seamlessly connects point-of-care devices with Electronic Health Record systems, improving data flow for clinicians. |
| Strategic Partnership | Leverages AI expertise from external firms to develop predictive algorithms for cardiovascular risk assessment. |
| Geographic Expansion | Establishes a stronger presence in high-growth markets like China and Brazil, capitalizing on infrastructure development. |
| Product Launch | Introduces new multiplex panels combining several cardiac biomarkers, offering a holistic view of patient cardiovascular status. |
Research Approach
Multi-period observation of biomarker adoption rates, regulatory approval trends, and point-of-care deployment anchored the trend analysis, supplemented by interviews with clinical pathologists, emergency physicians, cardiology specialists, and IVD manufacturers. Secondary data validation drew from FDA filings, EMA guidelines, NMPA announcements, and hospital procurement reports. This approach facilitated bottom-up and top-down triangulation for robust market sizing.
An input-output matrix framework modeled market dynamics across the analysis window, integrating segmentation dimensions such as product type, application, end-user, deployment, and regional healthcare expenditure. Compound annual growth rates were derived from historical data and projected adoption curves. Key industry-specific forecast inputs included the prevalence of cardiovascular diseases and healthcare infrastructure investment in emerging markets.
Several conditions sit outside the modeled scope, including specific pricing strategies of individual manufacturers and the impact of unforeseen global health crises. Forecasts reflect assumptions regarding regulatory stability and technological progression in the absence of disruptive innovations. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
High-Sensitivity Cardiac Biomarker Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Ischemia Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Stable Angina Management Market