
 Cardiac Troponin Market | 2026-2036
Cardiac Troponin Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Troponin Market Analysis
High-sensitivity troponin I is hardening its position as the preferred biomarker over conventional troponin T in emergency cardiac diagnostics, reducing false-negative rates and shortening rule-out protocols. Abbott Laboratories leverages its Alinity platform to dominate high-throughput hospital laboratory installations across North America. Roche Diagnostics sustains competitive pressure through its Elecsys portfolio and deep integration with European hospital networks. Siemens Healthineers anchors its position with decentralized point-of-care instruments that extend testing into ambulance and urgent-care settings.
Cardiac troponin comprises regulatory proteins (troponin I, troponin T, and troponin C) integral to skeletal and cardiac muscle contraction, with cardiac-specific isoforms released into circulation following myocyte necrosis; high-sensitivity assays detect concentrations below 0.005 ng/mL, enabling detection of minor myocardial injury within one to three hours of symptom onset. Point-of-care testing segments are capturing disproportionate growth as health systems prioritize door-to-diagnosis time under sixty minutes, while immunoassay platforms still occupy the deepest margin pools due to reagent annuity streams and regulatory switching costs. ELISA-based workflows retain entrenched positions in research institutes and smaller diagnostic laboratories where capital replacement cycles lag.
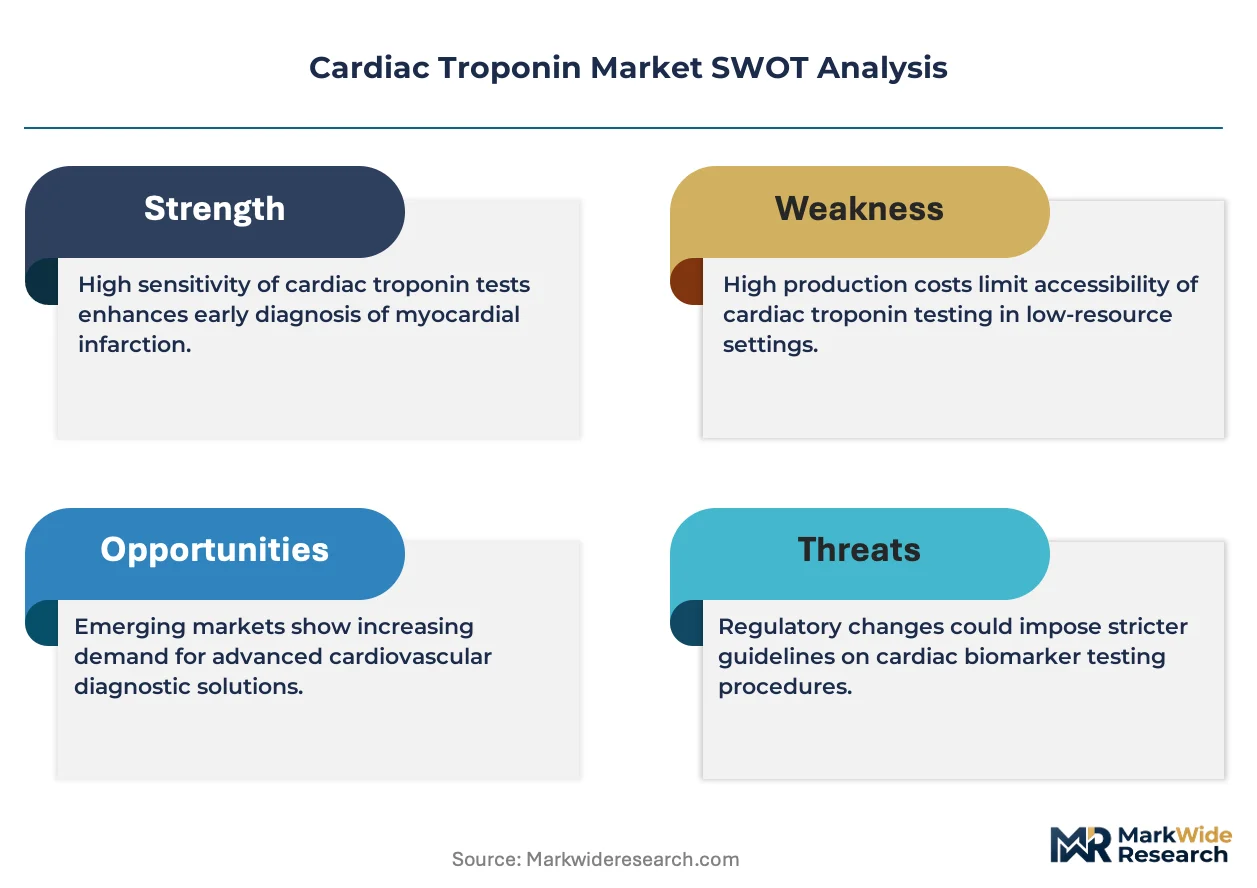
The FDA governs troponin assay approval through 510(k) and de novo pathways, with recent scrutiny on harmonization between high-sensitivity platforms creating compliance differentiation among manufacturers. The EU In Vitro Diagnostic Regulation (IVDR) is forcing recertification timelines that favor established players with dedicated regulatory affairs infrastructure. Clinical Laboratory Improvement Amendments (CLIA) complexity requirements shape where point-of-care versus central laboratory testing proliferates. Stakeholders must monitor evolving payer coverage decisions for serial troponin testing protocols, as reimbursement thresholds will determine whether high-sensitivity platforms achieve expected penetration in community hospital settings.
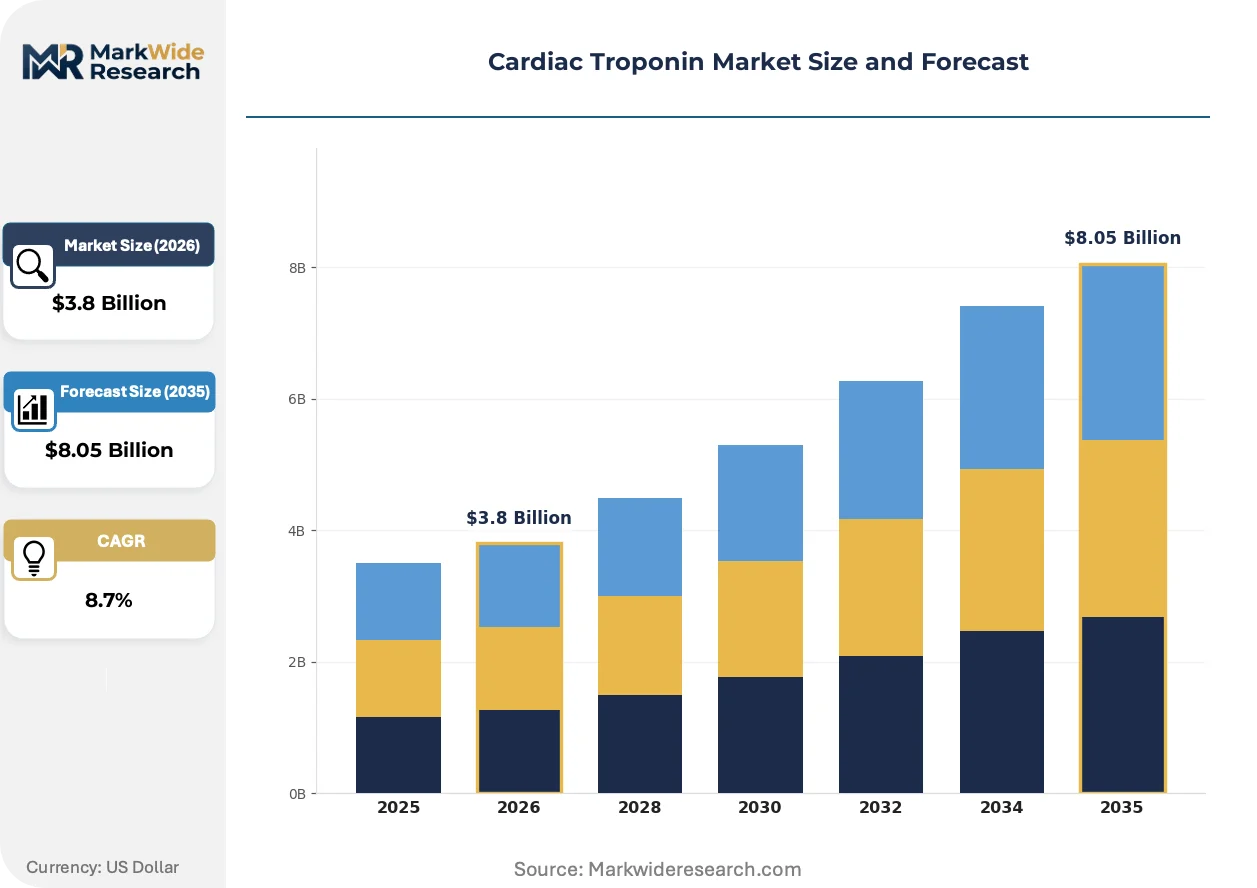
Market Dynamics
High-sensitivity troponin assay standardization is compressing competitive differentiation as FDA harmonization mandates force platform convergence among manufacturers. Laboratory consolidation within integrated health networks concentrates purchasing power and accelerates vendor lock-in effects.
Growth Catalysts
- Emergency department throughput mandates:Hospital administrators prioritize door-to-diagnosis protocols under sixty minutes, expanding point-of-care instrument installations in triage bays and ambulance services.
- CLIA complexity waivers:Moderate-complexity certifications for waived testing sites extend troponin diagnostics into urgent care clinics and rural health centers previously dependent on central laboratory send-outs.
- Myocardial injury detection thresholds:High-sensitivity assays detecting sub-0.005 ng/mL concentrations capture minor cardiac events previously invisible to conventional platforms, expanding the addressable patient population.
Market Restraints
- Reagent annuity lock-in:Proprietary consumable dependencies on closed immunoassay platforms create switching costs that suppress price competition and entrench incumbent positions.
- IVDR recertification timelines:European Union In Vitro Diagnostic Regulation compliance requirements favor established manufacturers with dedicated regulatory infrastructure, raising barriers for emerging entrants.
- Antibody specificity limitations:Cross-reactivity between skeletal and cardiac troponin isoforms in certain assay formulations generates false-positive signals that undermine clinical confidence in newer platforms.
Strategic Opportunities
- Ambulance-based prehospital testing:Emergency medical services in Germany and Japan deploy portable troponin analyzers to accelerate catheterization lab activation before hospital arrival.
- Artificial intelligence-enabled interpretation:Machine learning algorithms integrating serial troponin trajectories with electrocardiographic data reduce diagnostic uncertainty in intermediate-risk chest pain presentations.
- Serial testing reimbursement expansion:Payer coverage decisions for high-sensitivity protocols in community hospital settings unlock penetration into facilities currently constrained by limited capital budgets.
Industry Challenges
- Assay harmonization complexity:Discordance between high-sensitivity troponin I and troponin T platforms complicates multi-site clinical trials and retrospective biomarker research.
- Interoperability with legacy LIS infrastructure:Point-of-care instruments require middleware upgrades to integrate with existing laboratory information systems, extending implementation timelines and IT resource demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Troponin Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Troponin I, Troponin T, Combination Assays, Others Technology: ELISA, Point-of-Care Testing, Immunoassays, Mass Spectrometry End User: Hospitals, Diagnostic Laboratories, Home Care Settings, Research Institutes Application: Myocardial Infarction, Heart Failure, Cardiovascular Risk Assessment, Other Conditions |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Beckman Coulter, bioMérieux SA, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Bio-Rad Laboratories, Randox Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Troponin Market Emerging Trajectories
Diagnostic platforms are converging toward single-patient serial monitoring capabilities that compress rule-out protocols from six hours to under one hour. This shift demands simultaneous advances in assay sensitivity, instrument miniaturization, and clinical workflow redesign.
Magnetic bead-based chemiluminescence detection is absorbing market preference from traditional enzyme-linked immunosorbent assay workflows in high-throughput hospital laboratories. Academic medical centers in the United States and Switzerland have completed platform transitions over eighteen-month replacement cycles. The technology is absorbing reagent volume efficiencies and wash-step automation that reduce per-test labor costs while improving coefficient of variation consistency.
The EU In Vitro Diagnostic Regulation's 2022 implementation deadline forced manufacturers to resubmit technical documentation under expanded clinical evidence requirements. Mid-sized diagnostic firms without pre-existing notified body relationships faced eighteen-month certification delays that ceded shelf space to larger competitors. European hospital procurement committees now require IVDR conformity certificates as mandatory bid qualifications, filtering the vendor pool before technical evaluation begins.
Integrated health networks are consolidating laboratory purchasing decisions under centralized supply chain governance rather than allowing individual hospital laboratory directors independent vendor selection. This concentration shifts negotiation leverage toward multi-year enterprise agreements with exclusive reagent commitments. The phenomenon is most visible in United States metropolitan markets where three-hospital systems negotiate sole-source contracts covering chemistry, immunoassay, and hematology platforms simultaneously.
Cardiac Troponin Market Segmentation
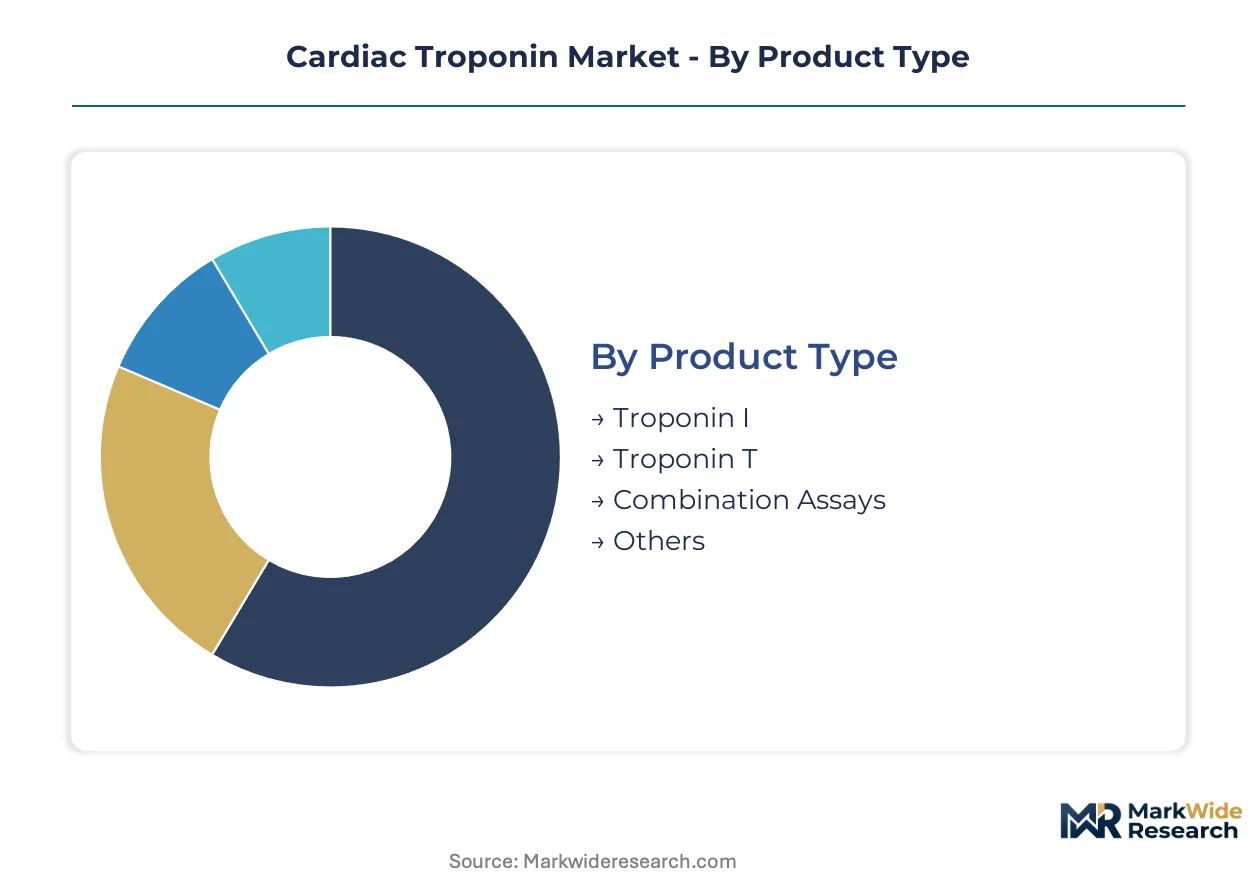
Cardiac troponin segmentation reflects divergent clinical workflows: centralized laboratories demand high-throughput precision while emergency departments prioritize speed over sensitivity. Manufacturers configure platform architectures around these opposing requirements, creating distinct margin profiles and switching cost barriers across each category.
Product Type:
Customization intensity spans from single-analyte specificity to multiplexed detection panels, with regulatory clearance pathways varying sharply by biomarker complexity.
- Troponin I:Cardiac-specific isoform with minimal skeletal muscle cross-reactivity dominates high-sensitivity assay development. United States emergency departments are consolidating purchasing around this biomarker for zero-hour rule-out protocols.
- Troponin T:Structural protein released during myocyte necrosis with slightly faster kinetics but greater interference risk from skeletal muscle expression. Retains entrenched positions in European hospital networks with legacy analyzer installations.
- Combination Assays:Simultaneous detection of troponin I and T variants in single-reaction formats.
- Others:Emerging biomarker panels incorporating troponin C or novel cardiac injury markers.
Most installed capacity flows through Troponin I. Expansion is steepest in Combination Assays.
Technology:
Capital intensity separates categories: benchtop analyzers demand million-dollar infrastructure while handheld units operate on disposable economics.
- Point-of-Care Testing:Portable analyzers delivering results within fifteen minutes from whole blood samples. Ambulance services in Germany and Japan are deploying prehospital units to activate catheterization labs before hospital arrival.
- Immunoassays:Automated chemiluminescence platforms processing hundreds of samples hourly with coefficients of variation below five percent. Integrated health networks in the United States negotiate sole-source contracts locking in reagent annuity streams.
- ELISA:Manual microplate workflows with lower capital barriers.
- Mass Spectrometry:Research-grade reference methods for assay harmonization studies.
Revenue concentrates in Immunoassays. Point-of-Care Testing is gaining share fastest.
End User:
Testing volume scales inversely with decision speed requirements across the care continuum.
- Hospitals:Emergency departments and cardiac catheterization laboratories conducting serial testing protocols. Door-to-diagnosis mandates under sixty minutes are accelerating point-of-care installations in triage bays.
- Diagnostic Laboratories:Centralized reference facilities processing outpatient and transferred specimens. CLIA complexity requirements shape whether high-sensitivity platforms achieve penetration in community hospital settings.
- Home Care Settings:Remote monitoring applications for post-discharge surveillance.
- Research Institutes:Academic medical centers validating novel assay formats.
Specimen throughput peaks in Diagnostic Laboratories. Home Care Settings show the steepest expansion trajectory.
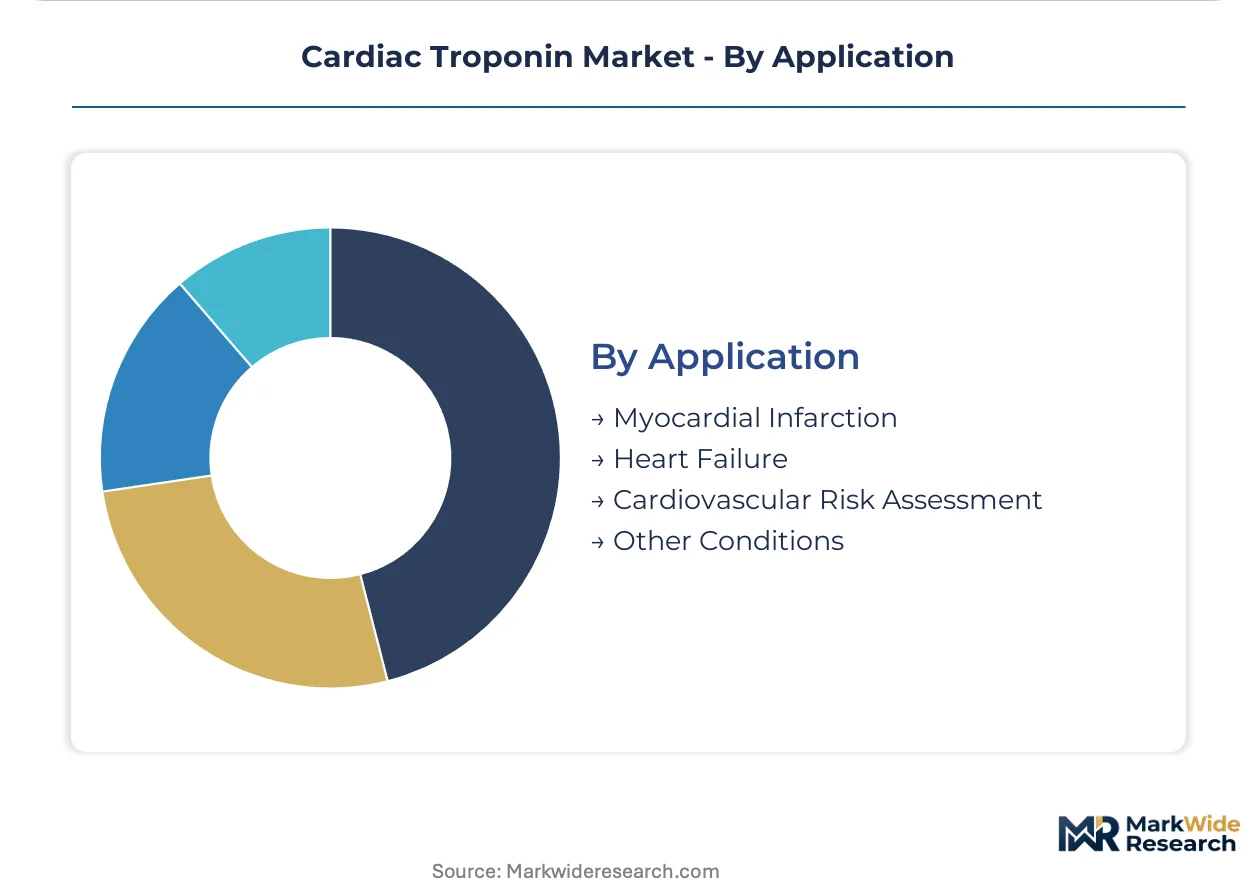
Application:
Clinical utility extends from acute event confirmation to longitudinal risk stratification, with reimbursement thresholds determining addressable population size.
- Myocardial Infarction:Acute coronary syndrome diagnosis with serial testing at zero, three, and six hours. FDA harmonization mandates on high-sensitivity platforms are compressing rule-out windows to under one hour.
- Cardiovascular Risk Assessment:Detection of subclinical myocardial injury in asymptomatic populations. High-sensitivity assays capturing concentrations below 0.005 ng/mL are expanding the addressable patient population.
- Heart Failure:Chronic monitoring of myocardial strain biomarkers.
- Other Conditions:Chemotherapy cardiotoxicity surveillance and sepsis-related myocardial dysfunction.
Protocol standardization centers on Myocardial Infarction. Cardiovascular Risk Assessment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors diagnostic demand through integrated health networks consolidating laboratory purchasing decisions under centralized supply chain governance.
United States
Emergency departments in Texas and Florida are expanding point-of-care troponin installations to meet door-to-diagnosis mandates under sixty minutes. FDA harmonization guidance on high-sensitivity assays is accelerating platform standardization across hospital systems. The Greater Boston cluster concentrates academic medical centers validating novel assay formats for multi-site clinical trials.
Germany
Ambulance services in Bavaria and North Rhine-Westphalia deploy portable analyzers to activate catheterization labs before hospital arrival. The national pharmaceutical regulator enforces IVDR recertification timelines that favor established manufacturers with dedicated regulatory infrastructure. The Munich-Stuttgart corridor hosts precision diagnostics firms advancing magnetic bead-based chemiluminescence detection platforms.
Japan
Prehospital emergency medical services in Tokyo and Osaka integrate troponin testing into mobile cardiac care units. METI funding programs support domestic development of miniaturized diagnostic instruments for aging rural populations. The Kansai region concentrates research institutes validating mass spectrometry reference methods for assay harmonization studies.
Switzerland
Academic medical centers in Zurich and Geneva completed eighteen-month platform transitions to high-sensitivity immunoassay architectures. Swissmedic maintains stringent clinical evidence requirements for novel biomarker panels entering the diagnostic market. The Basel cluster anchors pharmaceutical-diagnostic convergence projects targeting chemotherapy cardiotoxicity surveillance applications.
China
Tier-one hospitals in Shanghai and Beijing are adopting high-sensitivity platforms to reduce false-negative rates in acute coronary syndrome presentations. NMPA approval pathways for innovative diagnostic devices are compressing timelines for domestic manufacturers with established quality management systems. The Yangtze River Delta concentrates point-of-care instrument production facilities serving domestic and export markets.
Cardiac Troponin Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance infrastructure and health network integration depth. The vendor base concentrates around three strategic tiers: diversified conglomerates with full diagnostic portfolios, specialized immunoassay platform developers, and point-of-care instrument innovators. Consolidation pressures intensify as integrated health networks negotiate multi-year enterprise agreements with exclusive reagent commitments. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and geographic expansion through distributor networks in underserved markets.
Within the diversified conglomerate tier, Abbott Laboratories, Roche Diagnostics, and Siemens Healthineers exemplify platform breadth spanning chemistry, immunoassay, and hematology segments. Abbott occupies a position anchored in North American hospital laboratory installations through its Alinity platform architecture. Roche exemplifies European network integration depth with established notified body relationships navigating IVDR recertification requirements. Siemens represents point-of-care decentralization strategy extending testing into ambulance and urgent-care settings through instrument miniaturization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Beckman Coulter |
| bioMérieux SA |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Randox Laboratories |
| Others |
Supply Flow & Price Mechanics
Biomedical engineer concentrations in Massachusetts and Bavaria anchor reagent manufacturing labor pools, with wage differentials between these clusters and emerging production sites in Shanghai driving tiered pricing spreads across high-sensitivity assay platforms.
Pricing Analysis
Input-cost pass-through from monoclonal antibody production and magnetic bead substrates shapes contract structures. Pricing stratifies across FDA-cleared high-sensitivity tiers, CLIA-waived point-of-care instruments, and research-grade ELISA formats. Cost compression in standard immunoassay tiers is intensifying because integrated health networks negotiate multi-year enterprise agreements with exclusive reagent commitments. Community hospital laboratories exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize sensitivity specifications over per-test economics.
Supply Chain Analysis
Workforce availability in precision diagnostics manufacturing concentrates in the United States, Germany, and Switzerland, with these clusters anchoring high-sensitivity platform assembly. Supply chains draw from Chinese substrate suppliers for magnetic bead chemiluminescence components, German optical sensor manufacturers, and Japanese precision electronics fabricators. Single-source vulnerability in monoclonal antibody production creates concentration risk for assay specificity. Distribution runs through integrated health network procurement committees and GPO contracts rather than direct hospital laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cardiac troponin diagnostics rests on assay miniaturization cost curves and premium-tier shift toward high-sensitivity platforms with reagent annuity lock-in.
For Market Incumbents: Hedge against platform commoditization by deepening regulatory affairs infrastructure for IVDR recertification timelines and securing exclusive reagent contracts with consolidating integrated health networks. Threat from emerging point-of-care innovators with CLIA-waived instruments demands accelerated instrument miniaturization R&D. Vertical integration into monoclonal antibody production reduces input-cost volatility. For New Entrants and Emerging Players: Begin with ambulance-based prehospital testing in Germany and Japan, where emergency medical services procurement operates outside entrenched hospital laboratory vendor relationships. White space exists in AI-enabled serial troponin interpretation software integrating with existing analyzer platforms. Go-to-market through academic medical center validation partnerships builds clinical evidence for regulatory submissions. For Investors and Strategic Acquirers: Diversified diagnostic conglomerates with full chemistry-immunoassay-hematology portfolios are the most active acquirers in this space, seeking point-of-care capabilities to complement centralized laboratory platforms. Long-term viability favors targets with established notified body relationships and exclusive health network contracts. Watch FDA harmonization guidance on high-sensitivity troponin I versus T standardization as inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Recertification Investment | European hospital procurement committees now mandate conformity certificates as mandatory bid qualifications. |
| Point-of-Care Miniaturization | Ambulance services in Germany deploy portable analyzers to activate catheterization labs before hospital arrival. |
| AI-Enabled Interpretation Development | Machine learning algorithms integrating serial troponin trajectories with ECG data reduce diagnostic uncertainty. |
| Integrated Health Network Partnership | Multi-year enterprise agreements with exclusive reagent commitments concentrate purchasing power and accelerate vendor lock-in. |
| High-Sensitivity Platform Standardization | FDA harmonization mandates on troponin I versus T assays compress competitive differentiation and force platform convergence. |
Methodological Framework
Bottom-up hospital laboratory and emergency department demand modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, clinical laboratory directors, emergency medicine physicians, biomedical engineers, and regulatory affairs specialists at diagnostic manufacturers combined with secondary validation from FDA 510(k) filings, IVDR technical documentation databases, hospital GPO contract repositories, and CMS reimbursement coding updates. Triangulation between demand-side testing volume assumptions and supply-side instrument placement data ensures cross-verified market sizing.
Historical trendline analysis of installed base growth, replacement cycle timing, and assay menu expansion informs projection mechanics across the analysis window. Segmentation dimensions modeled include product type (troponin I, troponin T, combination assays), technology platform (point-of-care, immunoassay, ELISA), end-user setting (hospitals, diagnostic laboratories, home care), and application (myocardial infarction diagnosis, cardiovascular risk assessment). CAGRs derive from curve-fitting observed growth patterns against regulatory approval timelines and health network consolidation trajectories. Forecast inputs incorporate CLIA complexity waiver expansion rates and payer coverage decisions for serial testing protocols.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on high-sensitivity assay harmonization, disruptive biomarker substitution events, and macroeconomic shocks to hospital capital expenditure budgets. Forecasts reflect assumptions regarding continued integrated health network consolidation and stable antibody supply chains. Material deviation in FDA guidance timelines, IVDR enforcement intensity, or Medicare reimbursement thresholds for serial troponin testing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Ischemia Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Atherosclerosis Therapeutics Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market