
 Middle East and Africa Colorectal Cancer Diagnostics Market | 2026-2036
Middle East and Africa Colorectal Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Colorectal Cancer Diagnostics Market Foresight
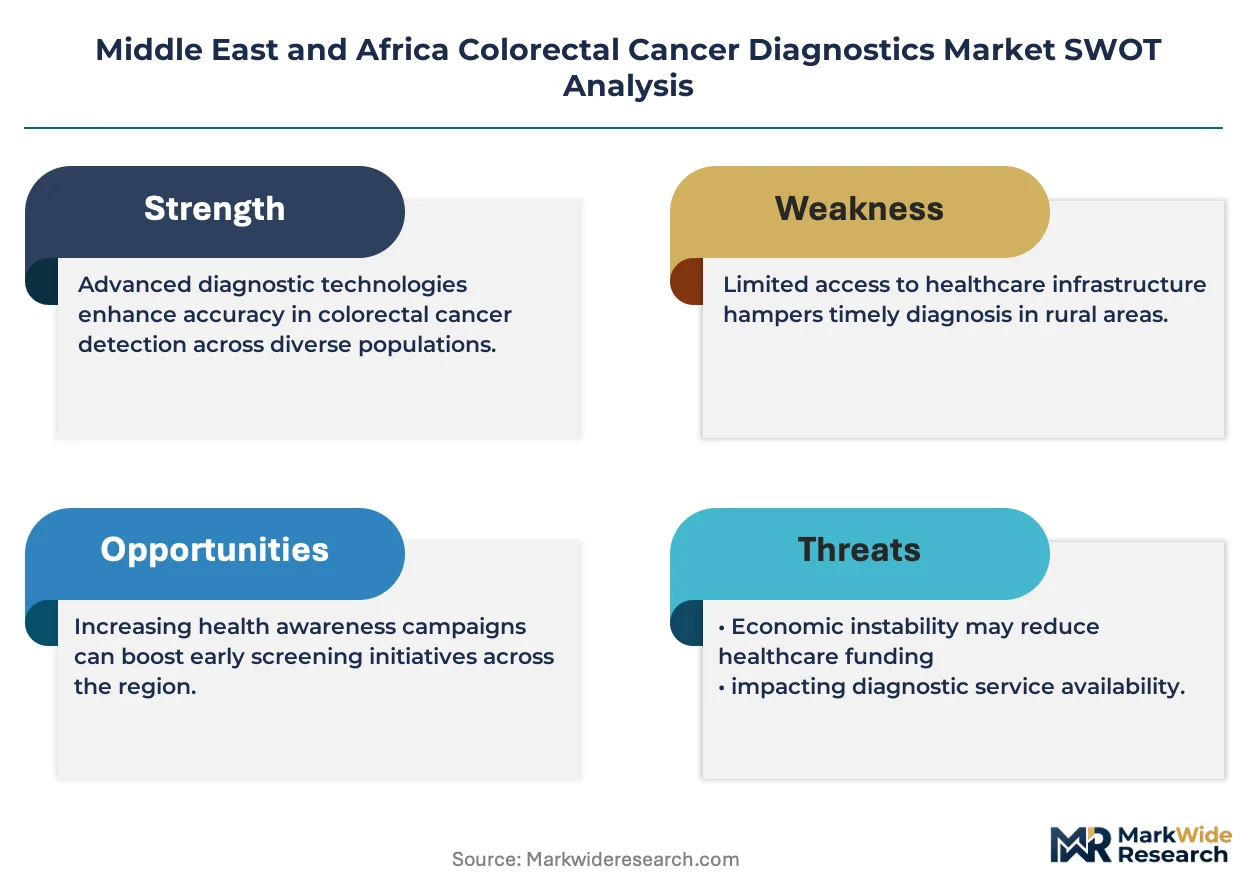
Aftermarket service revenue for installed imaging and sequencing platforms is tilting toward liquid biopsy-compatible system upgrades. Roche Holding AG leverages its centralized diagnostics infrastructure across Gulf state hospital networks. Thermo Fisher Scientific Inc anchors its position through PCR-based oncology assay distribution partnerships in North Africa. QIAGEN N.V. specializes in sample-to-insight workflow automation that reduces technician training burdens in understaffed laboratories.
Colorectal cancer diagnostics encompasses the detection, staging, and molecular characterization of malignancies arising in the colon or rectum through histopathological examination, biomarker quantification, and genomic profiling with detection thresholds typically reaching circulating tumor DNA concentrations below 0.1%. These technologies enable clinicians to identify Lynch syndrome variants, guide anti-EGFR therapy selection, and monitor minimal residual disease post-resection. Imaging modalities including CT colonography and MRI pelvis protocols retain the largest installed base across tertiary hospitals, while NGS-based genetic testing captures the fastest expansion as payers gradually reimburse comprehensive genomic profiling panels. Liquid biopsy technology occupies an emerging margin pool where Guardant Health competes on cell-free DNA extraction sensitivity without invasive tissue acquisition.
South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA enforce divergent clinical evidence requirements for novel biomarker assays, creating fragmented registration timelines that delay product commercialization. The European Union's In Vitro Diagnostic Regulation, though externally binding on CE-marked imports entering Middle Eastern markets through European distribution channels, indirectly elevates quality documentation expectations among Gulf procurement authorities. Laboratories and device manufacturers must monitor how national health insurance schemes in Egypt and Morocco update reimbursement catalogs to include next-generation sequencing platforms.
Market Dynamics
Stool-based screening programs are expanding across Gulf Cooperation Council diagnostic laboratories, compressing time-to-diagnosis intervals while blood-based liquid biopsy platforms penetrate private hospital networks in South Africa and Nigeria.
Growth Catalysts
- Saudi Arabia's SFDA streamlined pathways:The regulator has accelerated in-vitro diagnostic registration for oncology biomarkers, reducing commercialization delays for multiplexed assay manufacturers targeting Gulf state hospital procurement.
- Reference laboratory consolidation:Nigeria's emerging laboratory chains are deploying automated sample-to-insight workflows that expand screening access beyond major urban centers into secondary cities.
- PCR-based assay distribution:North African diagnostic networks are adopting thermocycler-compatible oncology panels that enable localized molecular testing without sample referral to European laboratories.
Market Restraints
- Reagent import dependency:Gulf state laboratories rely on temperature-controlled supply chains from European manufacturing hubs, exposing operations to shipping disruptions and customs processing variability.
- Technician training deficits:Next-generation sequencing platforms require specialized bioinformatics competencies that remain scarce across understaffed tertiary hospital pathology departments.
- Divergent evidence requirements:South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA maintain non-harmonized clinical validation standards, fragmenting product registration timelines.
Strategic Opportunities
- Morocco's reimbursement catalog expansion:National health insurance schemes are evaluating comprehensive genomic profiling inclusion, creating first-mover positioning for platform vendors.
- CT colonography-MRI convergence:Tertiary hospitals are integrating cross-modal imaging protocols that combine anatomical staging with functional tumor characterization.
- Private hospital network procurement centralization:South Africa's hospital groups are consolidating vendor relationships through single-source imaging and sequencing platform contracts.
Industry Challenges
- Minimal residual disease assay validation:Laboratories face protracted analytical performance studies required to demonstrate circulating tumor DNA detection thresholds below 0.1%.
- Lynch syndrome screening integration:Pathology departments must reconfigure immunohistochemistry workflows to accommodate universal mismatch repair deficiency testing without extending turnaround times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Colorectal Cancer Diagnostics Market |
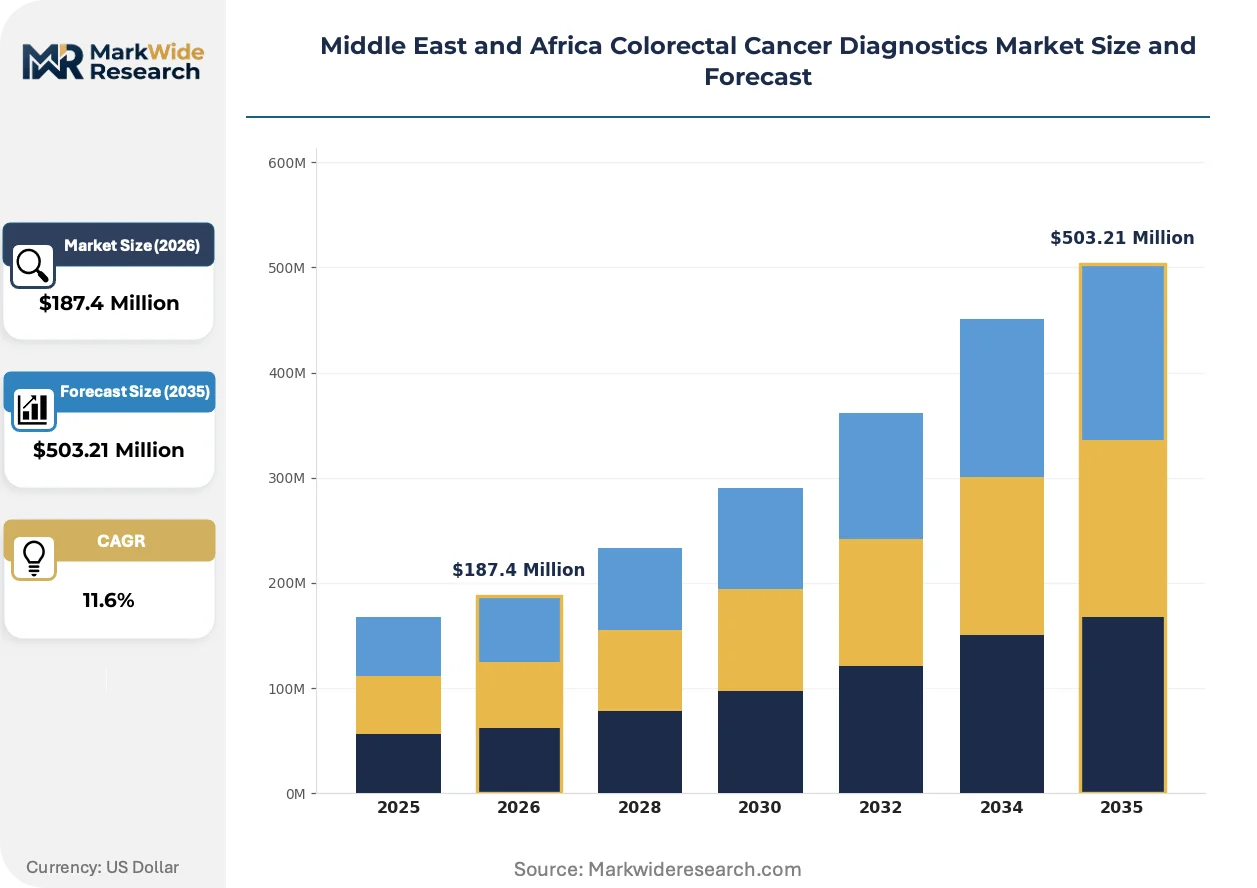
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Blood Tests, Biopsy, Genetic Tests End User: Hospitals, Diagnostic Laboratories, Outpatient Clinics, Research Institutes Technology: Immunohistochemistry, PCR, NGS, Liquid Biopsy Application: Screening, Risk Assessment, Monitoring, Treatment Decisions |
| Companies Covered | Roche Holding AG, Abbott Laboratories, GE HealthCare Technologies, Siemens Healthineers AG, Exact Sciences Corporation, Thermo Fisher Scientific Inc, Illumina Inc, QIAGEN N.V., Guardant Health, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Colorectal Cancer Diagnostics Market Shifts & Advancements
Liquid biopsy technology is compressing the diagnostic pathway by enabling serial monitoring without invasive tissue acquisition, while regulatory convergence pressures reshape quality documentation expectations across Middle Eastern procurement authorities.
Cell-free DNA extraction sensitivity is migrating from research-grade performance to clinical-grade reproducibility. Private oncology centers in Dubai and Riyadh are adopting automated plasma processing systems that standardize pre-analytical variables. This migration from manual protocols is enabling longitudinal treatment monitoring that was previously restricted to academic medical centers.
The European Union's In Vitro Diagnostic Regulation exerts extraterritorial influence through CE-marked import channels. Gulf procurement authorities now demand equivalent technical documentation from direct manufacturers. Egyptian reference laboratories are restructuring supplier qualification processes to preempt compliance gaps.
After-sales service unbundling is separating hardware maintenance from reagent supply commitments. South African hospital groups now negotiate standalone service contracts for installed sequencing platforms. This behavioral shift is most visible in Cape Town and Johannesburg, where procurement teams prioritize operational expenditure flexibility over bundled capital arrangements.
Middle East and Africa Colorectal Cancer Diagnostics Market Segmentation
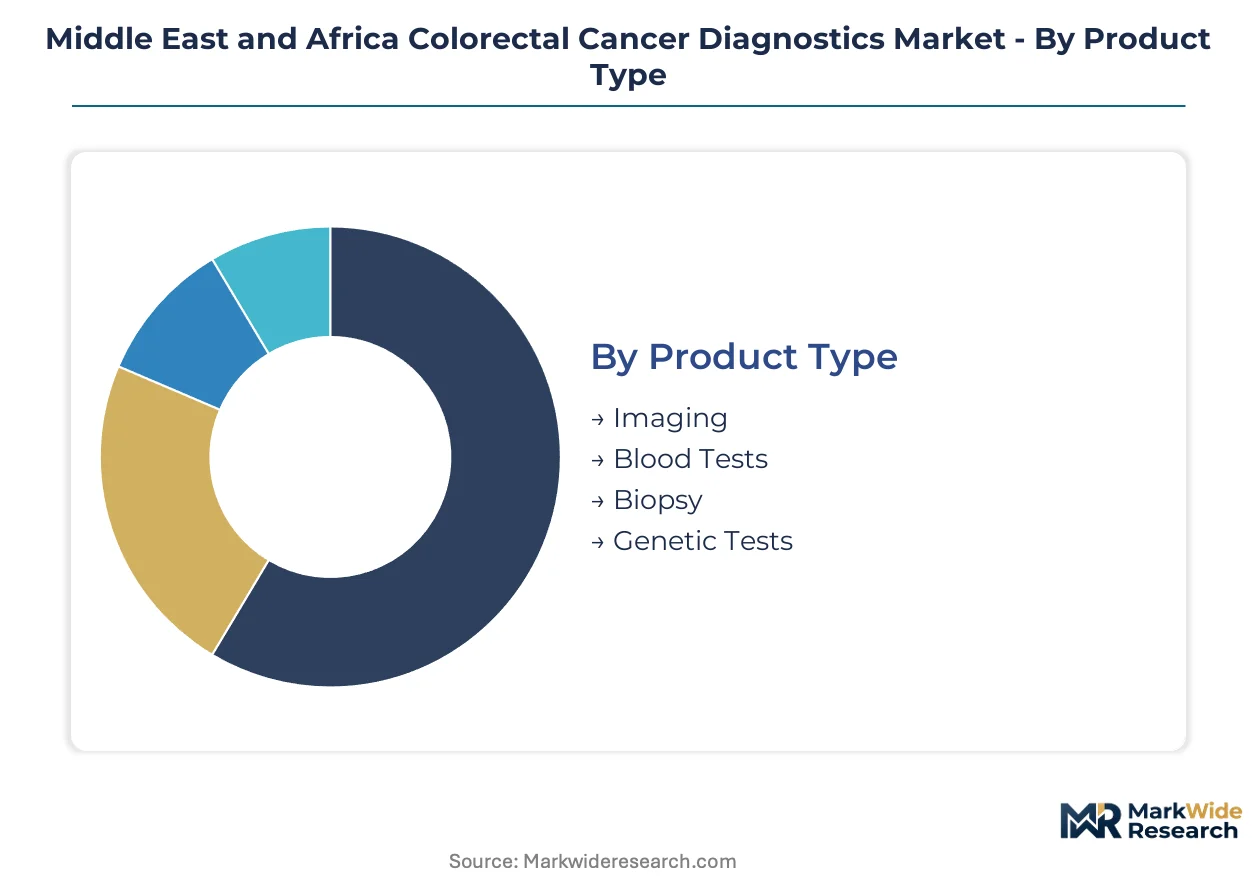
Colorectal cancer diagnostics in the Middle East and Africa fragment across four dimensions that determine service intensity, reimbursement pathways, and procurement centralization. Understanding these splits reveals where platform vendors must anchor field engineering resources versus where automated workflows suffice.
Product Type:
After-sales service intensity varies sharply across modalities, with imaging platforms demanding multi-year maintenance contracts while blood-based assays shift toward reagent rental models.
- Imaging:CT colonography and MRI pelvis protocols retain the largest installed base across tertiary hospitals in Saudi Arabia and South Africa. Service revenue concentrates in preventive maintenance contracts for Siemens and GE Healthcare systems deployed across Gulf state medical cities.
- Genetic Tests:NGS-based comprehensive genomic profiling panels capture the steepest expansion trajectory as Egyptian and Moroccan reimbursement authorities evaluate coverage inclusion. These platforms require specialized bioinformatics support that strains understaffed pathology departments.
- Blood Tests:Liquid biopsy cell-free DNA assays are penetrating private oncology centers in Dubai and Lagos through automated plasma processing systems.
- Biopsy:Histopathological examination remains volume-heavy across Nigeria's emerging reference laboratory chains.
By volume, Biopsy leads. By growth pace, Genetic Tests is ahead.
End User:
Procurement authority centralization distinguishes institutional buyers, with hospital groups negotiating enterprise contracts while independent laboratories prioritize instrument flexibility.
- Hospitals:South Africa's private hospital networks and Saudi Arabia's medical cities dominate capital equipment acquisition, consolidating imaging and sequencing platform procurement through single-source vendor relationships. These institutions absorb the highest service contract values per installed unit.
- Diagnostic Laboratories:Nigeria's emerging reference laboratory chains and Egypt's centralized testing facilities are deploying automated sample-to-insight workflows that expand screening access beyond major urban centers. Volume scale here supports reagent rental economics.
- Outpatient Clinics:Specialized oncology centers in Riyadh and Cape Town are adopting point-of-care blood-based screening to compress time-to-diagnosis intervals.
- Research Institutes:Academic medical centers in Johannesburg and Casablanca drive minimal residual disease assay validation studies requiring circulating tumor DNA detection below 0.1%.
Diagnostic Laboratories process the highest sample volumes. Hospitals command the largest per-transaction value.
Technology:
Margin structures diverge between mature immunohistochemistry workflows and emerging liquid biopsy platforms where consumable pull-through determines profitability.
- NGS:Next-generation sequencing platforms require specialized bioinformatics competencies that remain scarce across tertiary hospital pathology departments in the Gulf states. Thermo Fisher Scientific anchors market position through PCR-based oncology assay distribution partnerships that feed NGS confirmation workflows.
- Liquid Biopsy:Cell-free DNA extraction sensitivity is migrating from research-grade to clinical-grade reproducibility, with automated plasma processing systems standardizing pre-analytical variables in Dubai and Riyadh private oncology centers.
- PCR:Thermocycler-compatible oncology panels enable localized molecular testing across North African diagnostic networks without sample referral to European laboratories.
- Immunohistochemistry:Pathology departments must reconfigure workflows to accommodate universal mismatch repair deficiency testing for Lynch syndrome screening without extending turnaround times.
Immunohistochemistry maintains the broadest installed base. Liquid Biopsy is climbing the fastest.
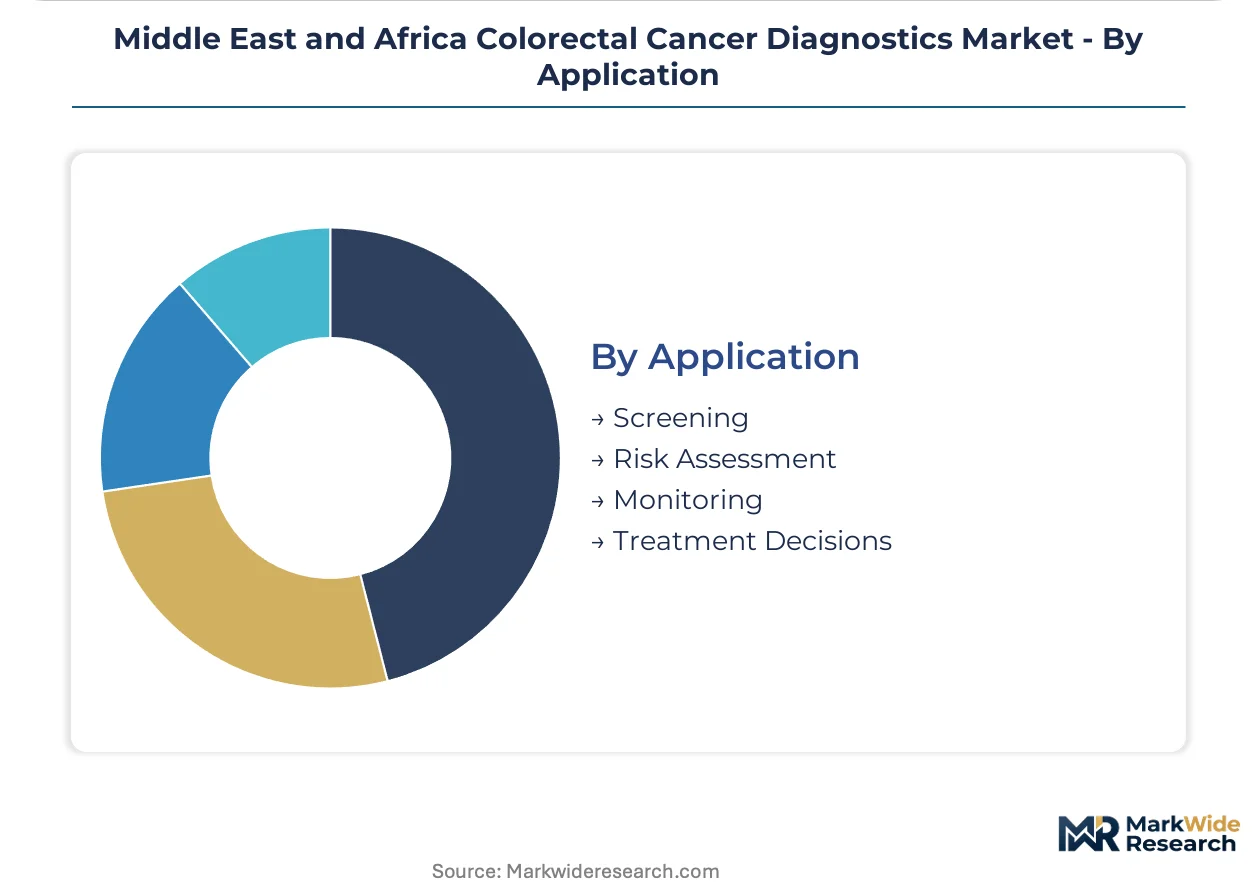
Application:
Reimbursement catalog coverage determines addressable market size, with screening programs enjoying public funding while treatment decision support faces prior authorization hurdles.
- Screening:Stool-based programs are expanding across Gulf Cooperation Council diagnostic laboratories, compressing time-to-diagnosis intervals while blood-based platforms penetrate private networks. Saudi Arabia's SFDA has streamlined in-vitro diagnostic registration pathways specifically for oncology biomarkers used in population screening.
- Treatment Decisions:Anti-EGFR therapy selection and comprehensive genomic profiling for targeted therapy matching concentrate in South Africa's private hospital networks where medical aid schemes reimburse molecular characterization.
- Monitoring:Serial liquid biopsy testing enables longitudinal treatment monitoring previously restricted to academic medical centers, now migrating to community oncology practices.
- Risk Assessment:Lynch syndrome variant identification and familial screening protocols are integrating into tertiary hospital genetic counseling services.
Screening commands the largest patient touchpoint volume. Treatment Decisions generates the highest revenue per test.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic buyers in Nigeria's emerging laboratory chains exhibit acute price sensitivity to reagent rental terms, while Saudi Arabia's medical cities absorb premium platform costs through centralized procurement budgets. This elasticity gap fragments vendor pricing power across the Middle East and Africa.
Saudi Arabia
Medical cities in Riyadh and Jeddah drive imaging platform installations through consolidated capital budgets. The SFDA has compressed oncology biomarker assay registration timelines, accelerating commercialization for multiplexed test manufacturers. Eastern Province tertiary hospitals are integrating CT colonography-MRI convergence protocols for anatomical-functional tumor characterization.
South Africa
Private hospital networks in Johannesburg and Cape Town anchor comprehensive genomic profiling adoption through medical aid scheme reimbursement. The Health Products Regulatory Authority enforces stringent clinical validation standards that delay novel assay introductions. Gauteng province laboratories are restructuring supplier qualification processes to align with evolving quality documentation expectations.
United Arab Emirates
Dubai's private oncology centers are deploying automated plasma processing systems for liquid biopsy standardization. MOHAP procurement frameworks emphasize operational expenditure flexibility over bundled capital arrangements. Abu Dhabi medical clusters are consolidating vendor relationships through single-source imaging platform contracts.
Egypt
Reference laboratories in Cairo and Alexandria are adopting PCR-based oncology panels to eliminate European sample referral dependencies. The national health insurance authority is evaluating comprehensive genomic profiling catalog inclusion. Nile Delta diagnostic networks are expanding automated sample-to-insight workflows into secondary cities.
Nigeria
Emerging laboratory chains in Lagos and Abuja prioritize thermocycler-compatible assays for localized molecular testing. The national pharmaceutical regulator maintains evolving documentation requirements for imported diagnostics. Southwest region facilities are deploying stool-based screening programs to compress rural time-to-diagnosis intervals.
Middle East and Africa Colorectal Cancer Diagnostics Market Competitive Landscape
Integrated diagnostics conglomerates and specialized molecular testing firms split the Middle East and Africa colorectal cancer diagnostics market along capital intensity lines. Imaging platform vendors command multi-year maintenance contracts across Gulf state medical cities, while assay manufacturers capture recurring revenue through rental economics in price-sensitive North African markets. Three archetypes dominate: full-stack diagnostics conglomerates with centralized infrastructure, sample-to-insight automation specialists, and liquid biopsy platform innovators. Competitive positioning hinges on strategic partnerships with reference laboratory chains and geographic expansion through localized distribution agreements.
Within the full-stack tier, Roche Holding AG and GE HealthCare Technologies exemplify infrastructure-heavy positioning. Among specialized molecular testing firms, QIAGEN N.V. and Thermo Fisher Scientific Inc occupy positions emphasizing workflow automation and PCR-based assay distribution respectively. Guardant Health represents the liquid biopsy innovation archetype focused on cell-free DNA extraction sensitivity.
| Leading Market Players |
|---|
| Roche Holding AG |
| Abbott Laboratories |
| GE HealthCare Technologies |
| Siemens Healthineers AG |
| Exact Sciences Corporation |
| Thermo Fisher Scientific Inc |
| Illumina Inc |
| QIAGEN N.V. |
| Guardant Health |
| Others |
Supply & Pricing Matrix
Temperature-controlled reagent import dependencies from European manufacturing hubs expose Gulf state laboratories to shipping disruption risks that widen pricing spreads between premium service-bundled platforms and bare-metal instrument procurement. This single-source vulnerability forces price differentiation across three tiers: medical cities in Riyadh and Jeddah absorb bundled capital arrangements with multi-year maintenance commitments, while Nigeria's emerging reference laboratory chains negotiate reagent rental models that shift cost to operational expenditure.
Pricing Analysis
After-sales service revenue from preventive maintenance contracts and extended warranty tiers now drives lifetime value more than initial hardware placement. Three-tier pricing structure across premium, standard, and economy levels separates Saudi medical cities with centralized procurement budgets from South African hospital groups prioritizing operational expenditure flexibility and Nigerian laboratories exhibiting acute reagent rental price sensitivity. Cost compression in economy-tier PCR panels is intensifying because local distributors compete on per-test consumable pricing. Diagnostic laboratories in North Africa represent the most price-sensitive segment, while Gulf state medical cities show least sensitivity due to consolidated capital budgets.
Supply Chain Analysis
Export-control restrictions on next-generation sequencing platform components limit flows from the United States, Germany, and Singapore into Middle Eastern and African markets. Supply chains for thermocycler-compatible oncology panels and automated plasma processing systems draw from manufacturing hubs in Germany, the United States, and China. Single-source vulnerability concentrates in temperature-controlled reagent logistics from European hubs. Distribution runs through authorized distributor networks with local service engineering capabilities rather than direct manufacturer presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue from installed imaging and sequencing platforms is expanding faster than new hardware placements, making service-attach rates the critical profitability lever across the Middle East and Africa colorectal cancer diagnostics market.
For Market Incumbents: Entrench position by deepening backward integration into reagent manufacturing to reduce import dependency exposure and by securing exclusive service contracts with South African hospital groups consolidating vendor relationships. Liquid biopsy platform innovators and automated workflow specialists represent emerging substitution threats that demand preemptive channel control investments in Nigeria's expanding reference laboratory chains. For New Entrants and Emerging Players: Mid-market diagnostic laboratories in Egypt's Nile Delta and secondary cities across Morocco's regional health networks represent the most penetrable entry point for automated sample-to-insight workflow providers. Point-of-care blood-based screening adoption in outpatient oncology clinics across Dubai and Cape Town offers a second white-space target with compressed sales cycles. A reagent rental go-to-market model with embedded field engineering support overcomes capital budget constraints among price-sensitive buyers. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors sample-to-insight automation specialists with proven Gulf state regulatory navigation capabilities. Long-term viability over a five-to-ten year window hinges on reimbursement catalog inclusion trajectories in Egypt and Morocco. The signal to watch as inflection indicator is SFDA registration timeline compression for multiplexed oncology biomarker assays, which would validate premium pricing power for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Egyptian national health insurance authority evaluation of comprehensive genomic profiling catalog inclusion creates first-mover positioning for platform vendors. |
| Hospital System Partnership | Single-source imaging and sequencing platform contracts with South African private hospital networks consolidate procurement authority and lock in multi-year service revenue. |
| CE Marking Pathway | European Union In Vitro Diagnostic Regulation compliance documentation elevates quality expectations among Gulf procurement authorities importing through European distribution channels. |
| Software Companion Development | Automated bioinformatics pipelines reduce technician training burdens in understaffed tertiary hospital pathology departments across Gulf states. |
| Geographic Expansion | Localized PCR-based oncology assay distribution partnerships in North Africa eliminate sample referral dependencies on European laboratories. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, reference laboratory operations directors, and regulatory affairs specialists across Saudi Arabia, South Africa, Egypt, and Nigeria and refined through secondary validation against SFDA registration databases, hospital procurement records, GPO contracts, and trade import statistics. Bottom-up and top-down triangulation cross-checked instrument installation counts with reagent consumption patterns and service contract values.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value outputs through segmentation across product type, end user, technology, application, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to installed base expansion and consumable pull-through rates, with specific inputs including SFDA registration timeline trends and Egyptian reimbursement catalog evaluation schedules.
Practitioners should monitor regulatory convergence pressures from European Union In Vitro Diagnostic Regulation extraterritorial effects and national health insurance scheme reimbursement updates for early signals of pricing power shifts. Forecasts reflect assumptions about technician training capacity expansion and temperature-controlled logistics reliability. Material shifts in Gulf state reagent import tariff structures or Egyptian comprehensive genomic profiling coverage decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market