
 Pericarditis Treatment Market | 2026-2036
Pericarditis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pericarditis Treatment Market Outlook
China is rewriting competitive dynamics in pericarditis therapeutics through expanded biopharma manufacturing zones and government-backed precision medicine initiatives. Kiniksa Pharmaceuticals leverages its interleukin-1 pathway expertise to sustain differentiation in recurrent pericarditis protocols. Pfizer Inc. anchors hospital formulary presence through established anti-inflammatory portfolios and cardiology sales infrastructure.
Pericarditis treatment encompasses pharmacological and procedural interventions targeting inflammation of the fibrous pericardial sac surrounding the heart, typically involving NSAIDs, colchicine, or corticosteroids administered via oral or intravenous routes to reduce effusion and prevent constrictive complications. The primary purpose is to terminate acute inflammatory episodes, prevent recurrence, and avert progression to cardiac tamponade or constrictive physiology. Non-Steroidal Anti-Inflammatory Drugs occupy the largest revenue share due to first-line guideline positioning and generic cost accessibility. Colchicine represents the fastest-expanding segment following label expansions for recurrent pericarditis prevention, while Immunosuppressive Agents command premium pricing in refractory cases despite narrower eligibility.
FDA cardiovascular and renal drug advisory frameworks, EMA orphan medicine designations, and NMPA priority review channels for rare disease therapeutics collectively shape trial endpoints, labeling requirements, and reimbursement negotiations across major markets. The FDA's Breakthrough Therapy pathway specifically compresses development timelines for novel biologics targeting cytokine-mediated pericardial inflammation. Stakeholders must monitor evolving payer evidence requirements for colchicine combination protocols versus standalone biologic regimens.
Market Dynamics
Hospital formulary consolidation and FDA Breakthrough Therapy pathway acceleration are compressing commercialization timelines for novel pericarditis biologics while concentrating prescribing authority within integrated cardiology networks.
Growth Catalysts
- EMA Orphan Medicine Designations:European incentives for rare cardiovascular indications reduce regulatory burden for developers targeting refractory pericarditis populations.
- Cardiac Inflammation Unit Expansion:Hospital systems in the United States are establishing dedicated centers that standardize biologic-first protocols for recurrent cases.
- Interleukin-1 Pathway Inhibition:Cytokine-targeted mechanisms demonstrate superior recurrence prevention compared to conventional NSAID-colchicine combinations in pivotal trials.
Market Restraints
- Biologic Manufacturing Concentration:Monoclonal antibody production for anti-inflammatory therapies clusters among contract manufacturers in Switzerland and Ireland, creating single-source vulnerability.
- Colchicine Supply Volatility:Active pharmaceutical ingredient sourcing for this first-line agent depends on limited Balkan and Portuguese agricultural processing capacity.
- Reimbursement Evidence Thresholds:CMS and commercial payers demand head-to-head cardiovascular outcome data that extends trial duration beyond patent exclusivity windows.
Strategic Opportunities
- Sub-Saharan Africa Penetration:Rheumatic heart disease burden creates addressable pericarditis incidence that remains untreated due to diagnostic infrastructure gaps.
- Telecardiology Integration:Remote monitoring platforms enable community hospital access to academic center treatment algorithms without capital-intensive unit construction.
- IRA Price Negotiation Exclusions:Orphan-designated cardiovascular therapies fall outside Medicare price-setting provisions, preserving pricing autonomy for qualifying indications.
Industry Challenges
- Cardio-Immunology Specialist Scarcity:Fellowship programs produce insufficient clinicians trained at the intersection of rheumatology and advanced heart failure management.
- Companion Diagnostic Development:Biomarker validation for IL-1 responder identification requires parallel regulatory submissions that synchronize poorly with therapeutic approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pericarditis Treatment Market |
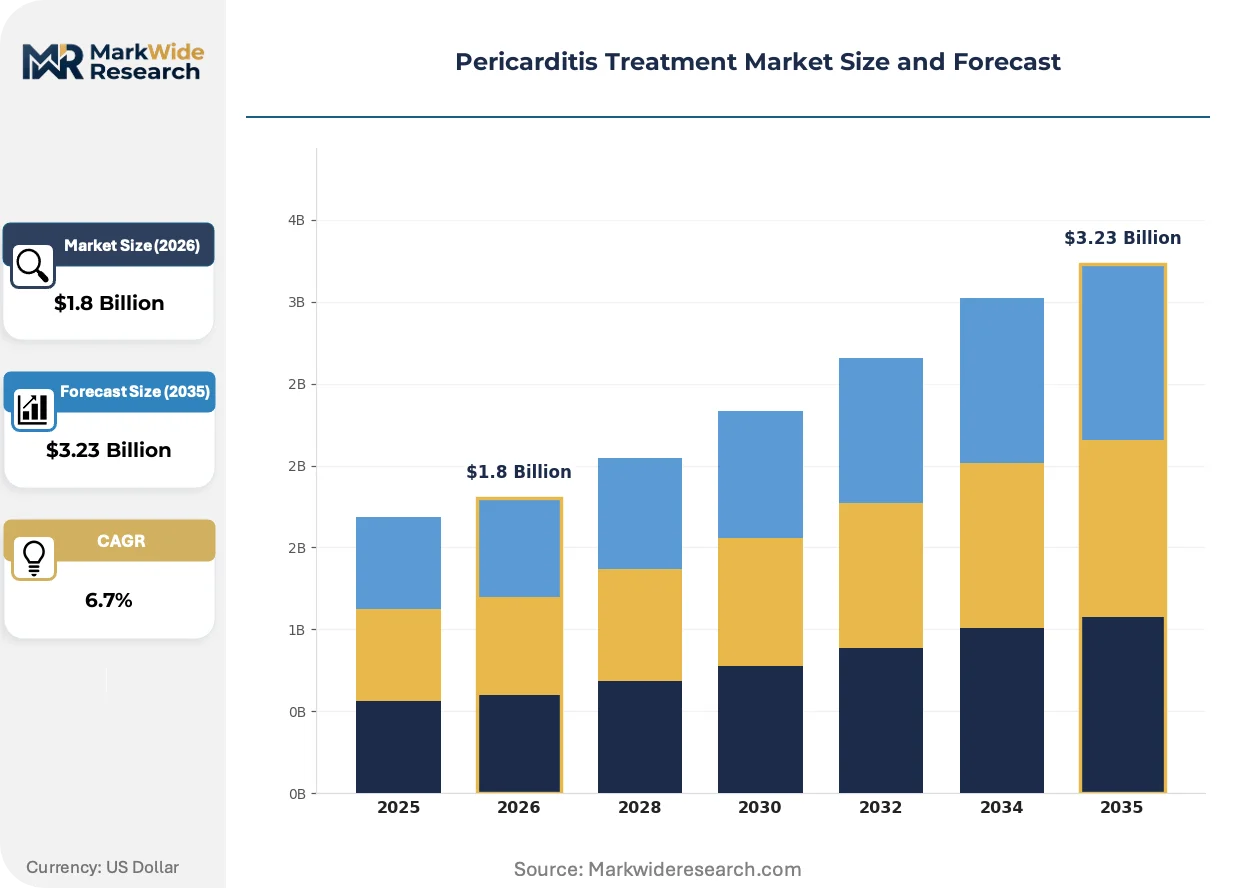
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Steroidal Anti-Inflammatory Drugs, Corticosteroids, Colchicine, Immunosuppressive Agents Delivery Mode: Oral, Intravenous, Topical, Intra-arterial End User: Hospitals, Outpatient Clinics, Homecare Settings, Specialty Clinics Treatment Approach: Medication Management, Surgical Intervention, Lifestyle Modifications, Therapeutic Monitoring |
| Companies Covered | Novartis AG, Kiniksa Pharmaceuticals, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Zydus Lifesciences Limited, Bayer AG, Sun Pharmaceutical Industries Ltd., Cardiol Therapeutics Inc., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pericarditis Treatment Market Strategic Shifts
Digital biomarker integration and decentralized trial infrastructure are rewriting how pericarditis recurrence gets detected and how regulatory evidence gets generated outside traditional hospital settings.
Artificial intelligence-enabled echocardiography analysis is digitizing pericardial effusion quantification and constriction pattern recognition. Community cardiology practices in Germany and Japan deploy these tools to reduce specialist referral dependency. The technology compresses diagnostic delay from symptom onset to treatment initiation by enabling point-of-care decision-making.
REACH regulatory requirements for pharmaceutical environmental risk assessments now extend to biologic manufacturing effluent management. European contract development organizations invest in closed-loop purification systems to satisfy ECHA discharge thresholds. This policy shift elevates manufacturing costs for inflammation-targeted biologics while advantaging facilities with pre-existing green chemistry infrastructure.
Hospital procurement committees now unbundle acute pericarditis episode management from chronic recurrence prevention contracts. Integrated delivery networks in Texas and California negotiate separate pricing for colchicine prophylaxis versus biologic rescue therapy. This purchasing pattern shift forces manufacturers to maintain dual commercial infrastructures for the same clinical indication.
Pericarditis Treatment Market Segmentation
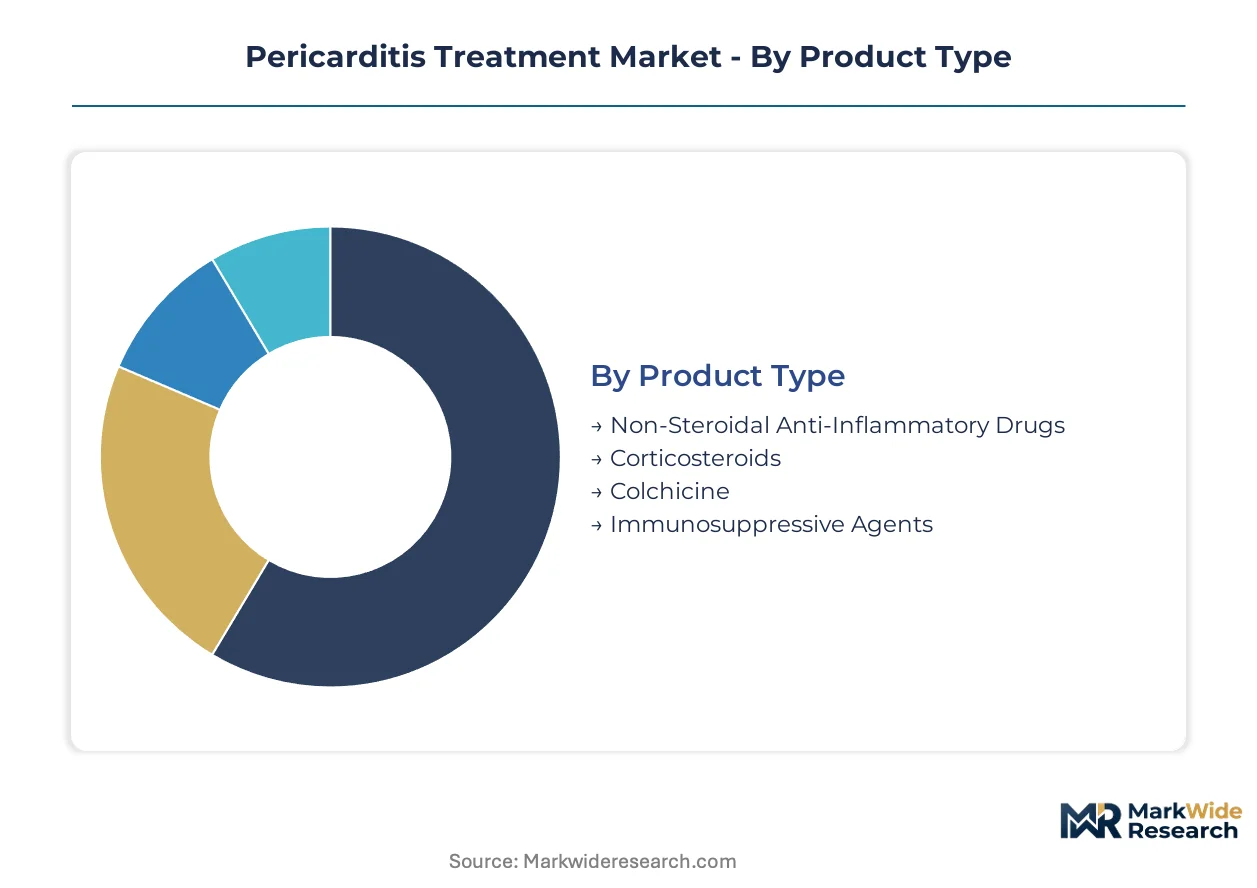
Pericarditis treatment protocols fragment across pharmacological classes, administration routes, and care settings that each demand distinct commercial infrastructure. Manufacturers must align formulation development with specific reimbursement codes and formulary placement requirements that vary by segment.
Product Type:
After-sales service intensity concentrates in biologics requiring cold-chain logistics, patient support programs, and infusion site coordination that generic manufacturers rarely provide.
- Non-Steroidal Anti-Inflammatory Drugs:First-line agents including ibuprofen and aspirin formulations dominate acute episode management through oral administration. Hospital systems in the United States negotiate these on annual generic tenders that compress margin but secure volume commitments through GPO consolidation.
- Colchicine:Microtubule inhibitor with established efficacy in recurrent pericarditis prophylaxis following label expansions. Demand clusters in specialty cardiology networks where protocol adherence drives repeat prescribing; supply volatility from limited agricultural API sourcing creates intermittent shortage risk.
- Corticosteroids:Prednisone and methylprednisolone reserved for NSAID-contraindicated patients or refractory cases.
- Immunosuppressive Agents:IL-1 pathway inhibitors and other biologics targeting cytokine-mediated inflammation in recurrent populations.
NSAIDs hold the largest share; momentum sits with Colchicine as guideline positioning expands.
Delivery Mode:
Cost tier differentiation separates hospital-administered infusion therapies from self-administered oral regimens that shift economic burden to outpatient pharmacy benefit managers.
- Oral:Tablets and capsules enabling outpatient management of uncomplicated acute episodes and maintenance prophylaxis. Community pharmacies in Germany and Japan dispense these through chronic disease management programs that bundle adherence monitoring.
- Intravenous:Hospital-based administration for severe presentations requiring rapid anti-inflammatory effect or when oral intake is compromised. Academic medical centers in the United States capture these episodes through dedicated cardiac inflammation unit protocols.
- Topical:Limited application for localized symptom management in specific pericarditis subtypes.
- Intra-arterial:Specialized interventional delivery for complex cases requiring targeted drug distribution.
Oral formulations dominate prescription volume; IV administration commands premium reimbursement in acute settings.
End User:
Customer type stratification reflects divergent purchasing authority between integrated delivery networks and independent specialty practices.
- Hospitals:Inpatient admission sites managing acute pericarditis with tamponade risk or hemodynamic compromise. Texas and California IDNs unbundle episode management from chronic prevention in separate procurement negotiations.
- Outpatient Clinics:Community cardiology practices in Germany deploy AI-enabled echocardiography to reduce specialist referral dependency for diagnosis.
- Homecare Settings:Self-administered oral regimens with remote monitoring support.
- Specialty Clinics:Academic center-affiliated inflammation units standardizing biologic-first protocols.
Hospitals anchor acute episode value; Specialty Clinics are expanding most quickly as dedicated cardiac inflammation units proliferate.
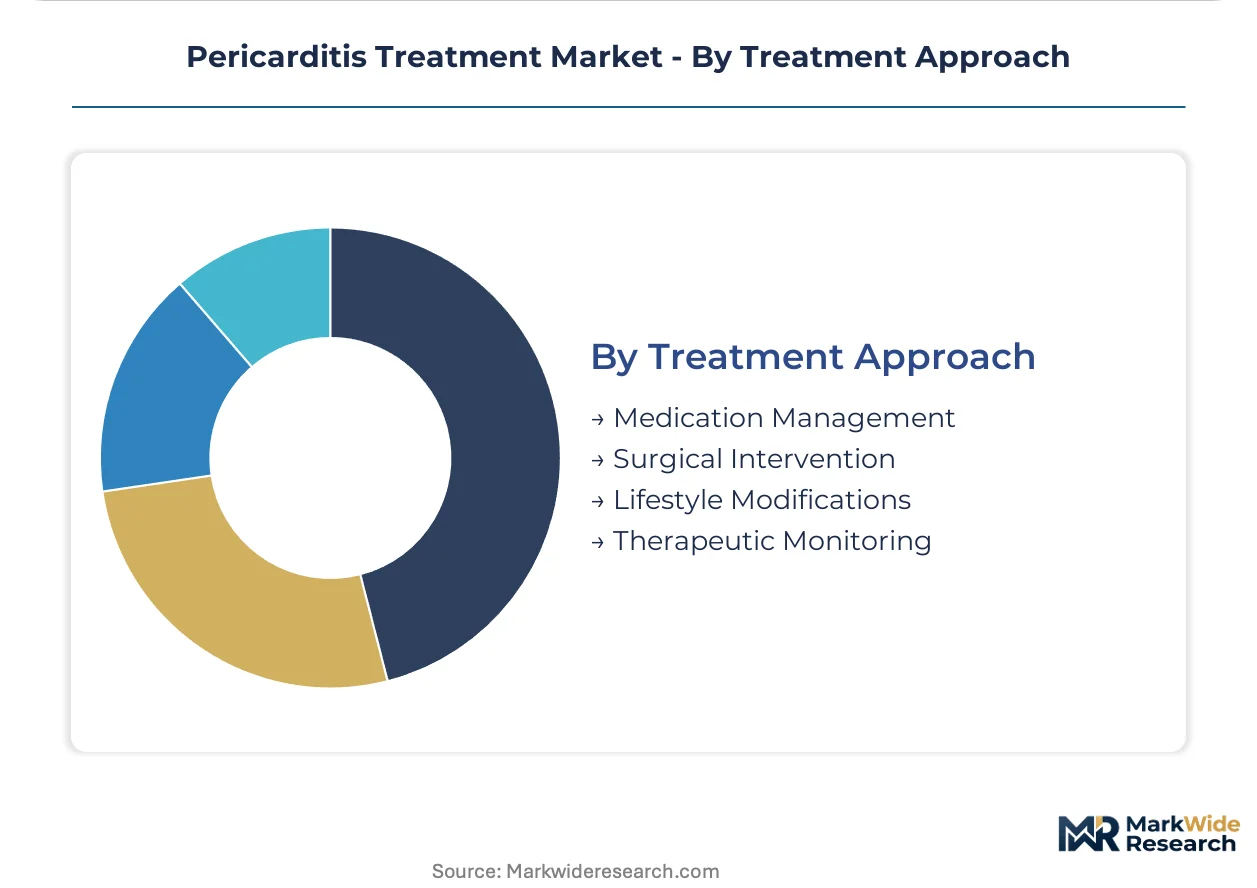
Treatment Approach:
Maturity variation separates established pharmaceutical protocols from emerging digital therapeutic monitoring platforms still seeking reimbursement codes.
- Medication Management:Pharmacological cornerstone encompassing NSAID, colchicine, and biologic sequencing per guideline algorithms. EMA orphan designations reduce regulatory burden for developers targeting refractory populations.
- Surgical Intervention:Pericardiocentesis and pericardiectomy for constrictive physiology or recurrent effusion.
- Lifestyle Modifications:Activity restriction and dietary protocols as adjunctive measures.
- Therapeutic Monitoring:Digital biomarker integration and decentralized trial infrastructure enabling recurrence detection outside traditional settings.
Medication Management retains dominant share; Therapeutic Monitoring climbs the fastest as telecardiology platforms enable remote algorithm access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing clusters in Switzerland and Ireland concentrate supply for anti-inflammatory monoclonal antibodies, while FDA Breakthrough Therapy approvals in the United States accelerate commercialization timelines for novel pericarditis therapeutics.
United States
Specialty cardiology networks in Texas and California drive protocol adoption for biologic-first recurrent pericarditis management. The IRA excludes orphan-designated cardiovascular therapies from Medicare price negotiation, preserving pricing autonomy. Boston and New York academic medical centers anchor cardiac inflammation unit expansion with standardized IL-1 pathway inhibitor protocols.
Germany
Community cardiology practices deploy AI-enabled echocardiography to reduce specialist referral dependency for pericardial effusion diagnosis. EMA orphan medicine designations reduce regulatory burden for developers targeting refractory pericarditis populations. The Munich and Heidelberg clusters concentrate precision medicine infrastructure supporting biomarker-guided therapy selection.
Switzerland
Contract manufacturing organizations in Basel and Zurich dominate monoclonal antibody production for inflammation-targeted biologics. Swissmedic coordinates with EMA on accelerated access pathways for rare cardiovascular indications. The country's pharmaceutical manufacturing base supplies critical capacity for IL-1 pathway inhibitors facing global demand pressure.
China
Government-backed precision medicine initiatives in Shanghai and Beijing expand biopharma manufacturing zones for cardiovascular therapeutics. NMPA priority review channels compress timelines for rare disease therapeutics including pericarditis indications. The Yangtze River Delta cluster attracts multinational joint ventures seeking localized production of anti-inflammatory biologics.
Japan
PMDA's Sakigake designation system accelerates approval for innovative pericarditis therapies addressing unmet medical need. METI funding supports digital biomarker integration in decentralized trial infrastructure. The Tokyo-Osaka corridor concentrates cardiology research hospitals adopting telecardiology platforms for remote recurrence monitoring.
Pericarditis Treatment Market Competitive Environment
Interleukin-1 pathway specialists and established anti-inflammatory portfolio holders split the market between novel biologic differentiation and formulary anchoring. The competitive structure concentrates around three strategic archetypes: cytokine-targeting biotechs with precision mechanisms, diversified pharmaceutical incumbents leveraging cardiology sales infrastructure, and generic manufacturers competing on colchicine and NSAID cost accessibility. Dominant competitive moves include hospital formulary consolidation through integrated delivery network contracting and accelerated regulatory pathway navigation for orphan cardiovascular indications.
Among the cytokine-targeting specialists, Kiniksa Pharmaceuticals occupies a position exemplifying interleukin-1 pathway expertise applied to recurrent pericarditis protocols. Pfizer Inc. anchors the diversified pharmaceutical tier through established hospital formulary relationships and cardiology sales infrastructure. Novartis AG sits within the inflammation-focused biologics segment with capabilities spanning autoimmune and cardiovascular therapeutic areas.
| Leading Market Players |
|---|
| Novartis AG |
| Kiniksa Pharmaceuticals |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Zydus Lifesciences Limited |
| Bayer AG |
| Sun Pharmaceutical Industries Ltd. |
| Cardiol Therapeutics Inc. |
| Merck & Co. Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Balkan and Portuguese colchicine API processing drives dual sourcing mandates among generic manufacturers while compressing margin structures across oral anti-inflammatory tiers. Hospital procurement committees exploit this fragility through unbundled episode-prevention contracting that separates acute NSAID tenders from chronic biologic protocols.
Pricing Analysis
The IRA's orphan drug exclusion from Medicare price negotiation dictates the pricing tier structure for cardiovascular biologics, preserving premium positioning for IL-1 pathway inhibitors while exposing generic NSAIDs to GPO-driven cost compression. Pricing stratifies across premium biologic, standard colchicine, and economy NSAID tiers based on formulation complexity and infusion site requirements. Cost compression in oral generics intensifies as annual hospital tenders consolidate volume commitments. Community pharmacy benefit managers exhibit highest price sensitivity; academic medical centers with dedicated cardiac inflammation units demonstrate lowest sensitivity due to protocol adherence mandates.
Supply Chain Analysis
Single-source vulnerability in Swiss and Irish monoclonal antibody contract manufacturing dominates supply chain risk assessment for inflammation-targeted biologics. Active pharmaceutical ingredient production draws from Balkan agricultural zones for colchicine, Portuguese processing facilities for purification, and Swiss fermentation capacity for biologic cell lines. Tariff exposure between European manufacturing hubs and United States distribution centers elevates landed costs for cold-chain-dependent therapies. Distribution runs through integrated delivery network central pharmacies for hospital-administered products, with specialty distributors handling outpatient biologic fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardio-immunology fellowship programs produce insufficient specialists trained at the intersection of rheumatology and advanced heart failure management, creating persistent capability gaps that constrain protocol expansion and biologic adoption velocity.
For Market Incumbents: Entrench formulary position through dedicated cardiac inflammation unit partnerships that standardize IL-1 pathway inhibitor protocols before biosimilar entry. Backward integration into Balkan colchicine API sourcing defends against supply volatility threatening generic margin structures. Lock in multi-year IDN contracts that unbundle acute episode management from chronic recurrence prevention to preserve pricing autonomy across both segments. For New Entrants and Emerging Players: Sub-Saharan Africa's untreated rheumatic heart disease burden represents the most penetrable entry point for diagnostic-therapeutic bundled offerings addressing infrastructure gaps. Telecardiology-enabled community hospital access to academic center algorithms bypasses capital-intensive unit construction requirements. Partner with established Swiss CMOs for monoclonal antibody production rather than building captive biologic manufacturing capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biologic developers with patient support programs and infusion site networks that generate chronic administration visibility. Long-term viability hinges on companion diagnostic co-development capabilities that synchronize biomarker validation with therapeutic approval timelines. Watch FDA Breakthrough Therapy designation velocity as the signal indicating which cytokine-targeting platforms will compress commercialization timelines sufficiently to outrun patent cliffs.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Designation Pathway Navigation | EMA and FDA accelerated channels compress development timelines for refractory pericarditis indications. |
| Biologic Manufacturing Scale-Up | Swiss and Irish CMO capacity expansion addresses single-source vulnerability in monoclonal antibody supply. |
| Telecardiology Platform Integration | Remote monitoring enables community hospital access to academic treatment algorithms without capital investment. |
| Companion Diagnostic Co-Development | Biomarker validation for IL-1 responder identification requires parallel regulatory submissions with therapeutic candidates. |
| IDN Contract Unbundling | Separate pricing for acute episode management and chronic prevention preserves margin across both care settings. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA cardiovascular and renal drug advisory filings, EMA orphan medicine designation databases, ClinicalTrials.gov protocols, and hospital formulary placement records. Drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and payer access specialists provided qualitative input through structured interviews. Bottom-up prescription volume modeling triangulates against top-down therapeutic class expenditure estimates from CMS and commercial claims data.
Forecast inputs span pharmacological class segmentation, administration route differentiation, and care setting stratification across the projection horizon. Modeled dimensions include treatment line positioning, dosage form, patient population severity, and regional regulatory cluster alignment. CAGRs derive from patient incidence projections, protocol adoption curves for biologic-first sequencing, and reimbursement code expansion timelines. Orphan designation velocity and Breakthrough Therapy approval rates inform biologic penetration assumptions.
Practitioners should monitor colchicine API supply disruptions, IRA implementation scope creep, and cardio-immunology fellowship graduation rates for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Vasculitis Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Ticagrelor Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Angina Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market