
 Pulmonary Valve Replacement Market | 2026-2036
Pulmonary Valve Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Valve Replacement Market Analytics
Transcatheter delivery is fragmenting the traditional surgical implantation pathway for pulmonary valve replacement. Edwards Lifesciences anchors its position through deep specialization in tissue valve platforms. Medtronic competes by extending its structural heart portfolio into robotic-compatible delivery systems. JenaValve Technology differentiates through dedicated transcatheter pulmonary valve designs that address complex right ventricular outflow tract anatomies.
Pulmonary valve replacement encompasses the surgical or percutaneous substitution of a diseased native or prosthetic pulmonary valve with a functional substitute, typically constructed from bovine or porcine pericardium, mechanical alloys, or polymer-supported tissue matrices engineered to withstand right-sided cardiac pressures of 15-30 mmHg systolic. The procedure restores hemodynamic efficiency in patients with congenital heart defects, valvular degeneration, or prior repair failures. Transcatheter valves capture the fastest expansion as minimally invasive alternatives displace open-heart redo surgeries in high-risk populations. Surgical implantation of tissue valves retains the largest installed base but faces margin compression from extended hospital stays. Percutaneous implantation concentrates in specialized congenital heart centers where procedure volume justifies dedicated hybrid operating suites.
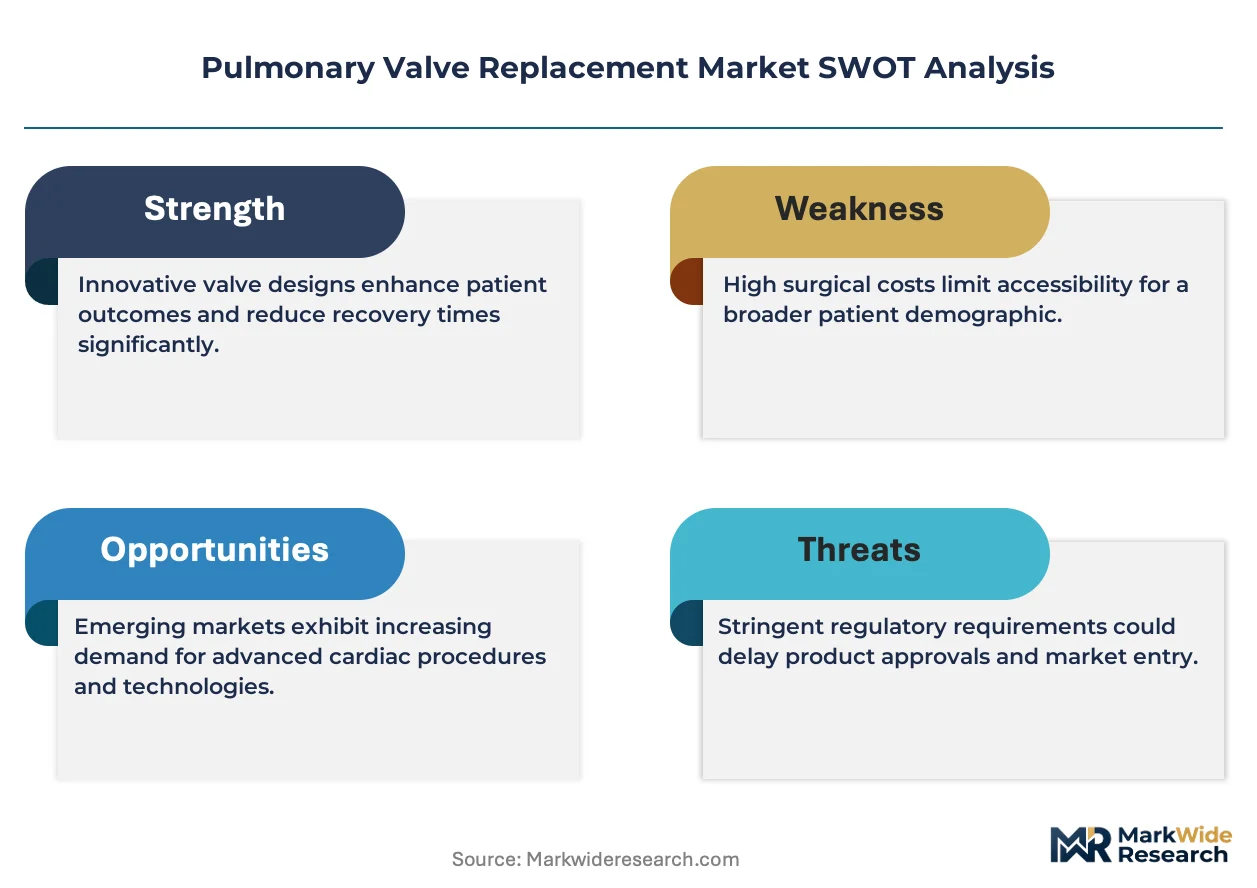
FDA premarket approval requirements and the EU Medical Device Regulation shape product development timelines, testing protocols, and market access conditions for valve manufacturers seeking multi-territory commercialization. The MDR's heightened clinical evidence standards for Class III implantable devices are forcing restructuring of post-market surveillance obligations. Stakeholders must monitor evolving reimbursement decisions for transcatheter pulmonary valve replacement across public and private payers, as coverage determinations will dictate which delivery modes achieve scalable adoption.
Market Dynamics
Transcatheter delivery systems are fragmenting the established surgical pathway for pulmonary valve replacement, compressing hospital stays and shifting procedure volume toward specialized congenital heart centers equipped with hybrid operating suites.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's accelerated review pathway for transcatheter pulmonary valves shortens clinical trial timelines and compresses time-to-market for novel delivery platforms.
- Pediatric Cardiology Expansion:Tertiary hospitals in the United States, Germany, and Japan are building dedicated transcatheter programs to capture complex congenital heart defect referrals.
- Biological Tissue Engineering:Advances in bovine and porcine pericardium processing improve valve durability under right-sided cardiac pressures of 15-30 mmHg systolic.
Market Restraints
- EU MDR Clinical Evidence Burden:The EU Medical Device Regulation's heightened standards for Class III implantable devices force restructuring of post-market surveillance obligations and extend certification timelines.
- Specialized Center Concentration:Transcatheter procedures concentrate in high-volume congenital heart centers, limiting addressable patient populations outside major metropolitan referral networks.
- Mechanical Valve Substitution:Long-life mechanical valves retain preference in specific pediatric populations where repeat intervention avoidance outweighs anticoagulation burden.
Strategic Opportunities
- Japan's Aging Congenital Population:Adult congenital heart disease centers in Tokyo and Osaka are expanding capacity to serve growing volumes of patients with prior repair failures.
- Robotic-Compatible Delivery Convergence:Integration of transcatheter platforms with surgical robotic systems enables precision deployment in complex right ventricular outflow tract anatomies.
- Hybrid Operating Suite Infrastructure:Hospital capital investment in combined catheterization laboratory and surgical theater environments creates captive demand for compatible valve systems.
Industry Challenges
- Pediatric Interventional Cardiology Talent Pipeline:The subspecialty requires dual training in congenital heart disease and catheter-based techniques, creating acute workforce scarcity.
- Reimbursement Determination Uncertainty:Public and private payer coverage decisions for transcatheter pulmonary valve replacement remain unsettled across multiple territories, constraining scalable adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Valve Replacement Market |
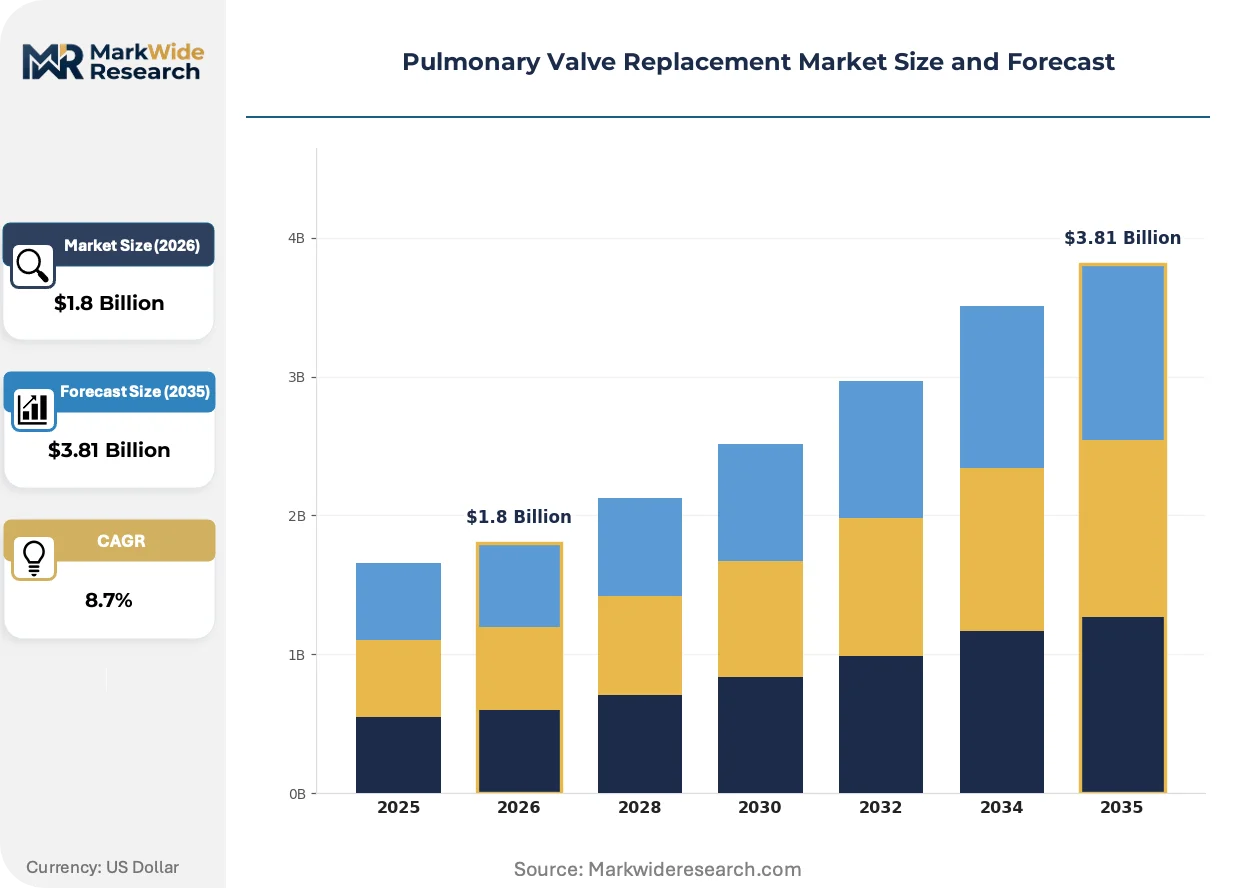
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tissue Valves, Mechanical Valves, Transcatheter Valves, Bioprosthetic Valves End User: Cardiology Clinics, Research Institutions, Hospitals, Outpatient Centers Delivery Mode: Surgical Implantation, Percutaneous Implantation, Minimally Invasive Surgery, Robotic-Assisted Surgery Application: Congenital Heart Defects, Valvular Heart Disease, Heart Failure, Pulmonary Hypertension |
| Companies Covered | Medtronic, Edwards Lifesciences, Abbott Laboratories, Boston Scientific, JenaValve Technology, LivaNova, Terumo Corporation, CryoLife, Artivion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Valve Replacement Market Evolving Landscape
Three distinct vectors are reshaping pulmonary valve replacement: biological-material innovation, regulatory pathway compression, and site-of-care migration toward integrated delivery environments.
Polymer-supported tissue matrices are hybridizing with traditional biological scaffolds to enhance structural integrity under cyclic right-ventricular loading. Pediatric cardiac surgeons at high-volume congenital centers are piloting these composite constructs in redo operations where native tissue availability is limited. The technology is hybridizing procurement patterns, as hospitals negotiate dual-source contracts covering both conventional tissue valves and next-generation matrix platforms.
The EU Medical Device Regulation's Class III implantable device requirements are forcing manufacturers to restructure clinical evidence packages and post-market surveillance systems. This regulatory compression disproportionately affects mid-tier valve producers lacking established European notified body relationships. German and French regulators are applying heightened scrutiny to biological valve durability claims, pushing developers toward extended follow-up protocols.
Service-line unbundling is separating transcatheter valve procurement from bundled cardiac surgery contracts. Independent purchasing committees at United States academic medical centers are negotiating direct manufacturer agreements, bypassing traditional group purchasing organizations. This shift concentrates price leverage with high-volume congenital heart programs in Boston, Philadelphia, and Houston while marginalizing lower-volume community hospitals.
Pulmonary Valve Replacement Market Segmentation
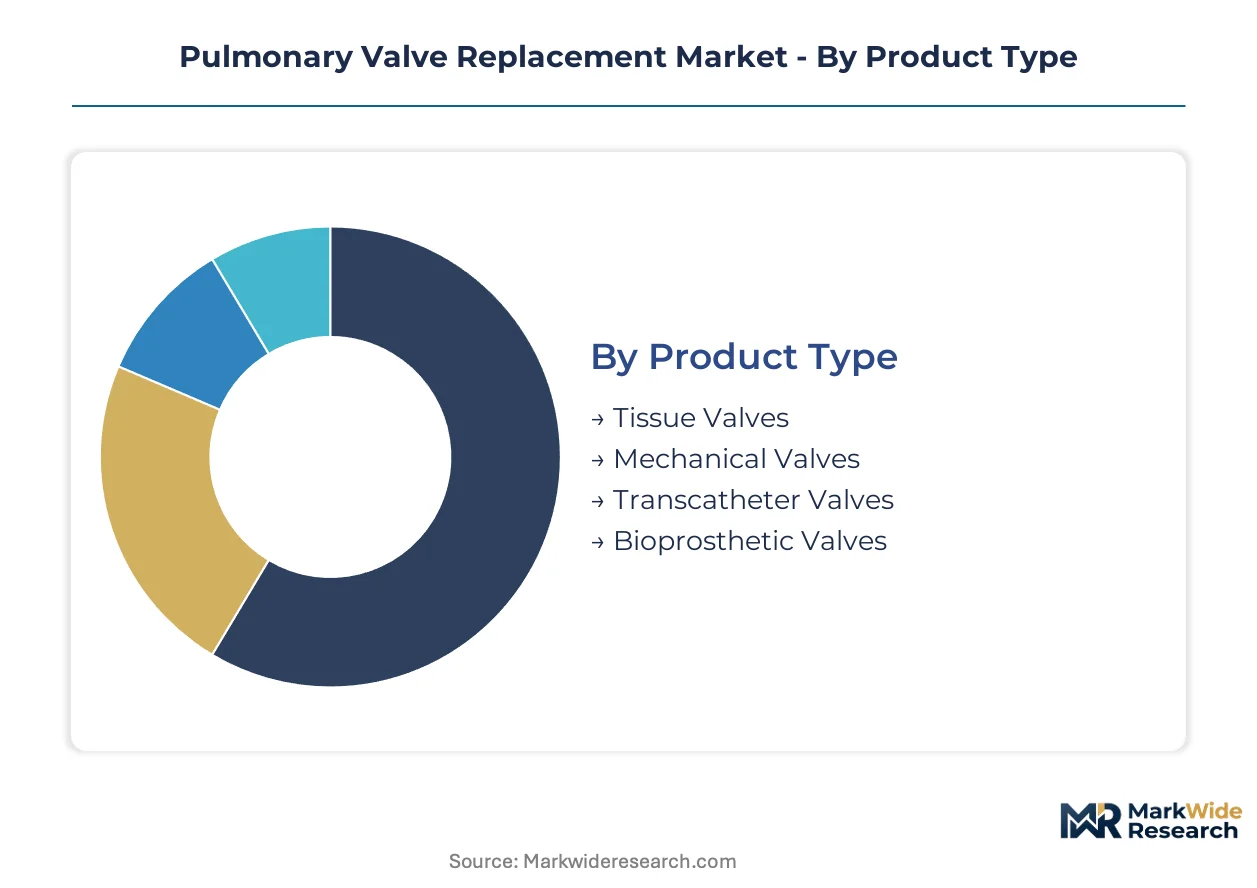
Segmentation in pulmonary valve replacement reveals distinct procurement patterns across product technologies, clinical settings, and patient populations. Each dimension carries specific reimbursement implications and site-of-care requirements that shape manufacturer go-to-market strategies.
Product Type:
Use cases span from lifelong mechanical durability in young patients to transcatheter convenience for high-risk redo procedures.
- Tissue Valves:Bovine or porcine pericardium constructs dominate surgical replacement volumes. Demand concentrates at United States academic medical centers where extended durability data supports premium positioning against mechanical alternatives.
- Mechanical Valves:Pyrolytic carbon and metal alloy designs deliver multi-decade functional lifespan. Pediatric cardiology programs in Germany favor these for patients under 30 where repeat intervention avoidance outweighs anticoagulation management burden.
- Transcatheter Valves:Nitinol-framed biological valves deployed via femoral or jugular access. Japan's adult congenital heart disease centers are expanding catheterization laboratory capacity to capture this minimally invasive shift.
- Bioprosthetic Valves:Tissue-engineered scaffolds with polymer reinforcement layers. Emerging adoption in complex right ventricular outflow tract reconstructions where native tissue availability is compromised.
The dominant share belongs to tissue valves, while transcatheter valves are gaining share fastest.
End User:
Procurement authority fragments across facility types with divergent capital budgets and procedure complexity thresholds.
- Hospitals:Tertiary centers with congenital heart surgery programs anchor tissue and mechanical valve volumes. Hybrid operating suite investments at Boston Children's Hospital, Children's Hospital of Philadelphia, and Texas Children's Hospital concentrate high-acuity demand.
- Cardiology Clinics:Specialized congenital heart disease practices manage pre-operative assessment and post-implant surveillance. German outpatient cardiology networks in Munich and Heidelberg coordinate referral pathways to surgical centers.
- Outpatient Centers:Ambulatory surgical facilities with catheterization capabilities capture select transcatheter cases. Tokyo and Osaka centers are piloting same-day discharge protocols for hemodynamically stable patients.
- Research Institutions:Academic medical centers with NIH or MHLW funding drive clinical trial enrollment for novel valve platforms. Preclinical testing partnerships with manufacturers accelerate regulatory submission timelines.
Hospital systems command procurement volume leadership, though outpatient centers are climbing the fastest as transcatheter eligibility expands.
Delivery Mode:
Technical complexity and capital intensity stratify competitive positioning across implantation approaches.
- Surgical Implantation:Median sternotomy with cardiopulmonary bypass remains the reference standard for complex anatomies. Retains largest installed base but faces margin pressure from extended intensive care unit stays.
- Percutaneous Implantation:Transcatheter deployment via vascular access eliminates sternotomy. Specialized congenital heart centers in the United States, Germany, and Japan justify dedicated hybrid suite investments based on procedure volume thresholds.
- Minimally Invasive Surgery:Right thoracotomy or mini-sternotomy approaches reduce surgical trauma. Select adoption for patients with favorable anatomy who are ineligible for transcatheter routes.
- Robotic-Assisted Surgery:Da Vinci or proprietary systems enable precision suturing in confined right ventricular spaces. Emerging integration with transcatheter platforms for complex outflow tract reconstructions.
Surgical implantation maintains volume dominance, while percutaneous approaches show steepest expansion trajectory.
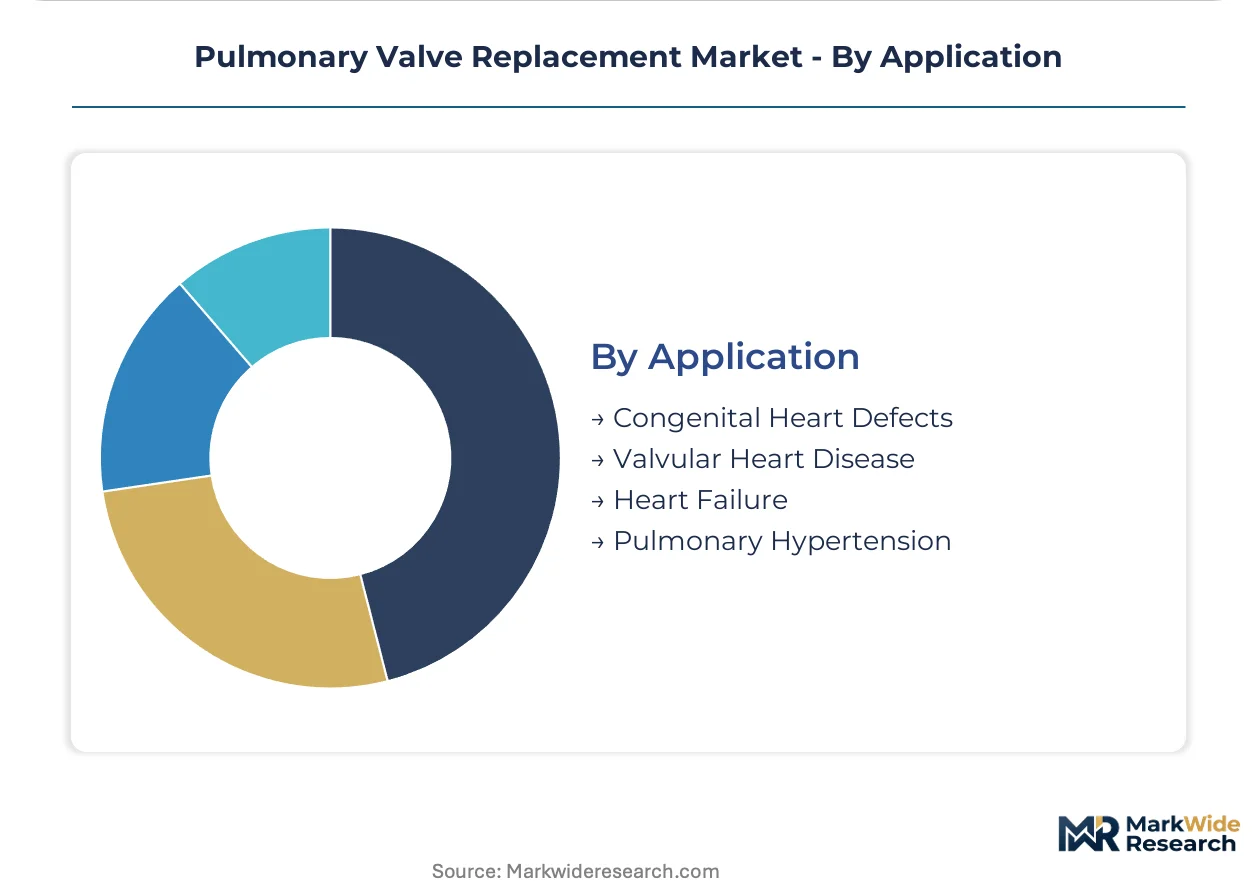
Application:
Patient etiology determines valve durability requirements and redo surgery probability.
- Congenital Heart Defects:Tetralogy of Fallot and other cyanotic lesions generate recurring replacement need as prior repairs degenerate. Adult congenital heart disease programs in the United States and Japan are expanding capacity for this aging population.
- Valvular Heart Disease:Native pulmonary valve degeneration or prior bioprosthetic failure drives replacement demand. Mechanical valve preference in younger patients where tissue valve calcification risk is elevated.
- Pulmonary Hypertension:Secondary valve dysfunction from pressure overload requires durable solutions. Transcatheter options are expanding for patients with prohibitive surgical risk profiles.
- Heart Failure:Right ventricular remodeling with functional pulmonary regurgitation. Emerging indication where valve replacement may modify disease progression.
Congenital heart defects capture the dominant procedure volume, though valvular heart disease applications are expanding most quickly as transcatheter platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports specialized transcatheter delivery systems while exporting tissue valve processing technologies to European and Asian markets. Germany and Japan maintain trade surpluses in precision-manufactured valve components. Emerging production capacity in India and China is gradually reducing import dependency for standard surgical implants.
United States
FDA breakthrough device designations for transcatheter pulmonary valves accelerate regulatory timelines for manufacturers seeking market entry. The Centers for Medicare & Medicaid Services is evaluating expanded coverage determinations for percutaneous procedures in congenital heart disease populations. Boston Children's Hospital, Children's Hospital of Philadelphia, and Texas Children's Hospital anchor demand through dedicated hybrid operating suite investments.
Germany
EU MDR compliance requirements for Class III implantable devices extend certification timelines for valve manufacturers seeking CE marking. The Federal Institute for Drugs and Medical Devices applies heightened scrutiny to biological valve durability claims. Munich and Heidelberg outpatient cardiology networks coordinate referral pathways to surgical centers, concentrating procedure volume in Bavaria and Baden-Württemberg.
Japan
METI funding for adult congenital heart disease infrastructure expands catheterization laboratory capacity in Tokyo and Osaka. PMDA accelerated approval pathways compress review timelines for novel transcatheter platforms. Same-day discharge protocols for hemodynamically stable patients are piloting at ambulatory surgical facilities in the Kanto region.
United Kingdom
NICE technology appraisals for transcatheter pulmonary valve replacement influence NHS commissioning decisions across integrated care systems. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR standards. London and Birmingham congenital heart centers concentrate specialist workforce and procedure volume.
India
CDSCO medical device rules for Class D implantables establish registration requirements for imported valve systems. Government medical colleges in Delhi, Mumbai, and Chennai are expanding pediatric cardiac surgery programs. Private hospital chains in Gurugram and Hyderabad are investing in hybrid catheterization laboratories to capture medical tourism flows.
Pulmonary Valve Replacement Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated cardiovascular conglomerates with structural heart portfolios, dedicated transcatheter specialists with regulatory expertise, and biological tissue processors with manufacturing scale. Strategic archetypes include full-platform developers competing across surgical and percutaneous modalities, focused innovators addressing complex right ventricular outflow tract anatomies, and contract manufacturers supplying pericardium-derived scaffolds. Dominant competitive moves encompass technology licensing agreements to access novel delivery systems and backward integration into biological tissue processing to secure raw material supply.
Within the integrated cardiovascular tier, Medtronic and Edwards Lifesciences occupy positions spanning surgical tissue valves and transcatheter platforms. JenaValve Technology exemplifies the focused innovator archetype through dedicated pulmonary valve designs. These three entities represent distinct strategic postures: scale-driven platform breadth, deep specialization in tissue engineering, and anatomical complexity targeting.
| Leading Market Players |
|---|
| Medtronic |
| Edwards Lifesciences |
| Abbott Laboratories |
| Boston Scientific |
| JenaValve Technology |
| LivaNova |
| Terumo Corporation |
| CryoLife |
| Artivion |
| Others |
Value Network & Pricing Analysis
Single-source dependency on bovine pericardium processors in the United States and Ireland determines both the premium-to-economy valve pricing spread and the elongated supply chain shape that favors vertically integrated manufacturers with captive tissue processing capabilities.
Pricing Analysis
Hospital purchasing committees anchor valve procurement through three-tier pricing structure across premium, standard, and economy levels differentiated by FDA breakthrough designation status and biological durability certification. Price differentiation stems from anticoagulation management bundling and hybrid suite compatibility guarantees. Cost compression in standard-tier surgical valves is intensifying because extended EU MDR certification timelines favor incumbents with established notified body relationships. Pediatric cardiology programs exhibit highest price sensitivity due to constrained reimbursement codes, while adult congenital centers demonstrate lowest sensitivity where transcatheter convenience commands premium positioning.
Supply Chain Analysis
Extended payment terms from tier-one congenital heart centers in the United States, Germany, and Japan are restructuring working capital requirements for biological tissue processors. Manufacturing concentrates in Costa Rica, Ireland, and Singapore where FDA-registered facilities cluster near major export hubs. Raw material flows draw from Australian bovine herds, New Zealand porcine sources, and German nitinol wire suppliers. Single-source vulnerability in pericardium tanning chemistry exposes processors to regulatory restriction risk from ECHA substance evaluations. Distribution runs through specialized cardiovascular device distributors with cold-chain capabilities for biological scaffolds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcatheter pulmonary valve replacement sits at an FDA breakthrough acceleration phase that favors manufacturers with pre-established congenital heart center relationships and hybrid suite compatibility portfolios.
For Market Incumbents: Insulate market position by securing backward integration into bovine pericardium processing to neutralize raw material cost volatility from Australian herd supply fluctuations. Expand dedicated pediatric interventional cardiology training partnerships at Tokyo and Osaka adult congenital centers to preempt emerging entrant access. Priority defensive investment targets robotic-compatible delivery system certification to maintain pricing power against minimally invasive surgery substitution. For New Entrants and Emerging Players: India's underpenetrated pediatric cardiac surgery programs at government medical colleges in Delhi, Mumbai, and Chennai offer white-space access where hybrid laboratory infrastructure is scaling rapidly. Target medical tourism flows through Gurugram and Hyderabad private hospital chains seeking transcatheter capability differentiation. Go-to-market leverage centers on CDSCO Class D registration pathway expertise that incumbent multinational submissions have delayed. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors acquisition targets with EU MDR technical documentation completeness and Japanese PMDA pre-submission engagement history. Long-term viability over the extended analysis window hinges on reimbursement strategy execution across CMS and German G-BA parallel review processes. Signal to monitor: NICE technology appraisal timelines for transcatheter pulmonary valve replacement as NHS commissioning precedent.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses time-to-market for nitinol-framed biological valve platforms. |
| EU MDR Technical Documentation | Class III implantable evidence packages determine CE marking access for pericardium-derived scaffolds. |
| Hybrid Operating Suite Partnership | Boston Children's and Texas Children's capital investments create captive demand for compatible systems. |
| Reimbursement Strategy Development | CMS coverage determinations dictate scalable adoption across United States congenital heart networks. |
| Pediatric Interventional Training Program | Dual-trained catheter specialists at German outpatient cardiology networks concentrate referral control. |
Research Methodology
A standing panel of pediatric interventional cardiologists, congenital heart surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) and PMA filings, EUDAMED device registrations, CMS Medicare claims data, and hospital procurement database extracts. Bottom-up valve shipment estimates triangulated against top-down congenital heart surgery volume projections across the analysis window.
Scenario-bracketing around regulatory approval velocity and reimbursement expansion pace structured the projection framework across product type, delivery mode, end-user facility tier, and patient etiology segments. CAGRs derived from fitted growth curves applied to historical procedure volumes adjusted for FDA breakthrough designation timing and hybrid suite installation rates at high-volume congenital centers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by contract tissue processors or sudden CMS coverage reversals would shift outcomes. Macroeconomic pressure on hospital capital budgets, EU MDR notified body capacity constraints, or biological valve durability failures prompting regulatory safety actions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Fractional Flow Reserve Market
Cardiovascular
Vasculitis Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Pulmonary Embolism Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Myocardial Infarction Market