
 Chronic Myeloid Leukemia Treatment Market | 2026-2036
Chronic Myeloid Leukemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Myeloid Leukemia Treatment Market Intelligence
Buyer concentration among oncology centers is pivoting toward integrated health systems that consolidate formulary decisions across multiple sites. Novartis AG leverages its established manufacturing scale in tyrosine kinase inhibitor production to sustain supply commitments across these networks. Pfizer Inc. competes through geographic dominance in European specialty clinic channels. Bristol-Myers Squibb Company differentiates via R&D intensity in next-generation targeted compounds.
Chronic myeloid leukemia treatment encompasses pharmaceutical and cellular interventions designed to suppress BCR-ABL fusion protein activity, restore normal hematopoiesis, and achieve molecular remission through sustained tyrosine kinase inhibition. The therapeutic objective centers on preventing blast crisis progression while maintaining quality-adjusted survival. Tyrosine kinase inhibitors occupy the dominant margin pool due to chronic oral administration and patent-protected pricing power. Immunotherapy segments are expanding fastest as combination protocols gain traction in relapse management settings. Stem cell transplant remains concentrated in research hospitals with specialized graft-versus-leukemia expertise.
The FDA's accelerated approval framework and the EMA's conditional marketing authorization pathway shape product entry timelines and post-market evidence requirements for novel CML agents. REACH and MDR compliance in Europe adds manufacturing and traceability costs that filter into procurement negotiations. Stakeholders must monitor how payer consolidation in the United States and reference pricing expansion in Germany reshape net pricing for chronic oral therapies.
Market Dynamics
The FDA's accelerated approval pathway is compressing development timelines for tyrosine kinase inhibitors while simultaneously intensifying post-market evidence requirements. This regulatory velocity is forcing manufacturers to build real-world evidence infrastructure before launch rather than after.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review framework reduces time-to-market for novel BCR-ABL inhibitors. Manufacturers file rolling submissions that compress traditional approval windows by twelve to eighteen months.
- Integrated Cancer Networks:Consolidated oncology centers in the United States standardize formulary decisions across multiple sites. This concentration amplifies procurement volumes for single-source contracts.
- Next-Generation Sequencing:Molecular diagnostic platforms enable earlier detection of kinase domain mutations. Community oncology practices adopt these tools to guide treatment selection at initial diagnosis.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Tyrosine kinase inhibitor synthesis depends on specialized intermediate suppliers concentrated in India and China. Geopolitical friction or export restrictions threaten supply continuity.
- EMA MDR Compliance Burden:Europe's Medical Device Regulation imposes enhanced traceability and post-market surveillance obligations on companion diagnostics. Compliance costs filter into pricing negotiations.
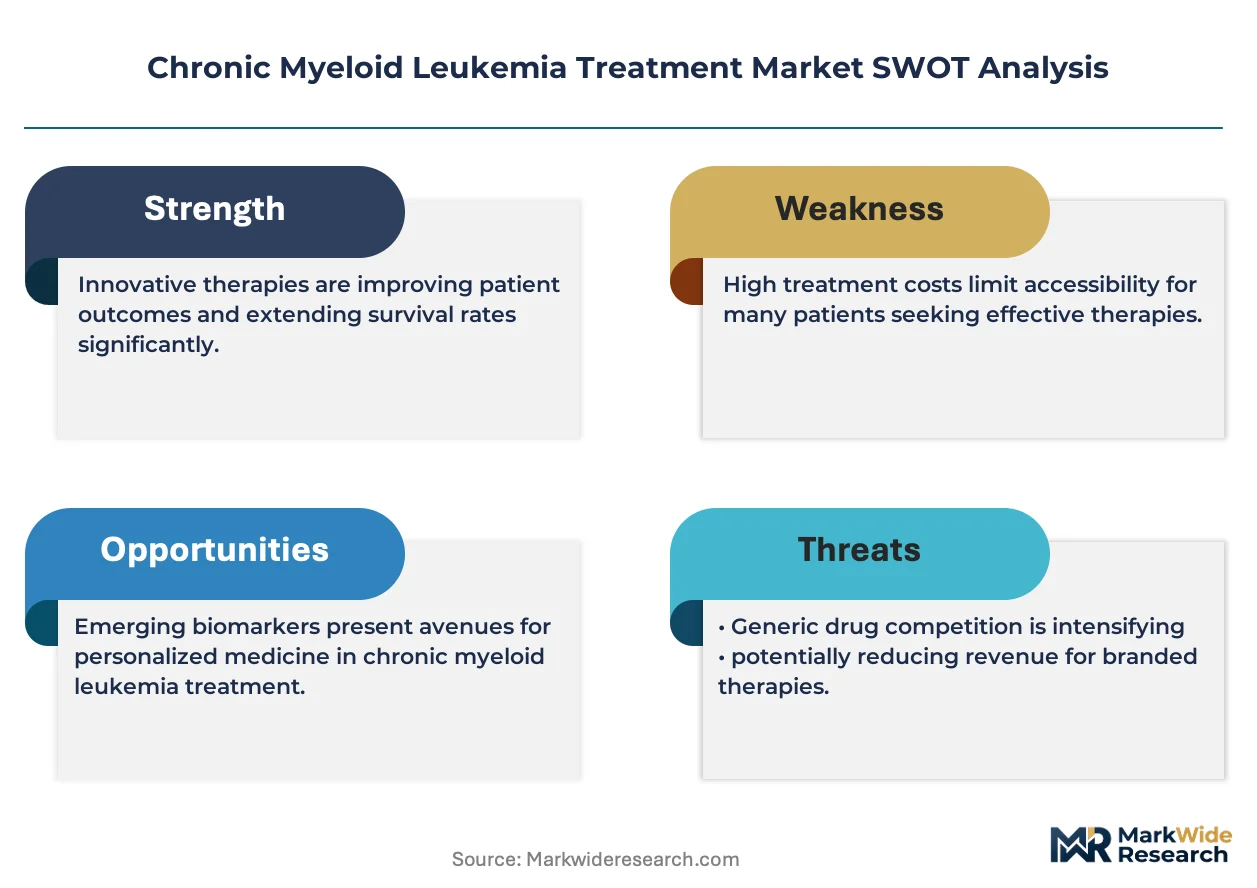
- Generic Erosion Timeline:Patent cliffs for first-generation imatinib formulations expose originator portfolios to price compression. Payers in Germany leverage reference pricing to amplify substitution incentives.
Strategic Opportunities
- Combination Protocol Development:Immunotherapy segments expand fastest as checkpoint inhibitors pair with tyrosine kinase inhibitors in relapse settings. Research hospitals with graft-versus-leukemia expertise pioneer these regimens.
- Real-World Evidence Infrastructure:The FDA's requirement for confirmatory trials creates demand for patient registry platforms. Data analytics vendors capture value by structuring longitudinal outcomes databases.
- Specialty Pharmacy Channels:Oral chronic therapies shift fulfillment from hospital infusion centers to home-delivery networks. PBM-owned specialty pharmacies consolidate patient access and adherence monitoring.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Post-market surveillance requirements outpace the supply of qualified drug safety professionals. Manufacturers compete for epidemiologists capable of designing registry studies.
- Legacy Manufacturing Retrofit:Continuous processing technologies require capital redeployment from batch facilities. Site validation timelines extend eighteen to twenty-four months for quality system harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Myeloid Leukemia Treatment Market |
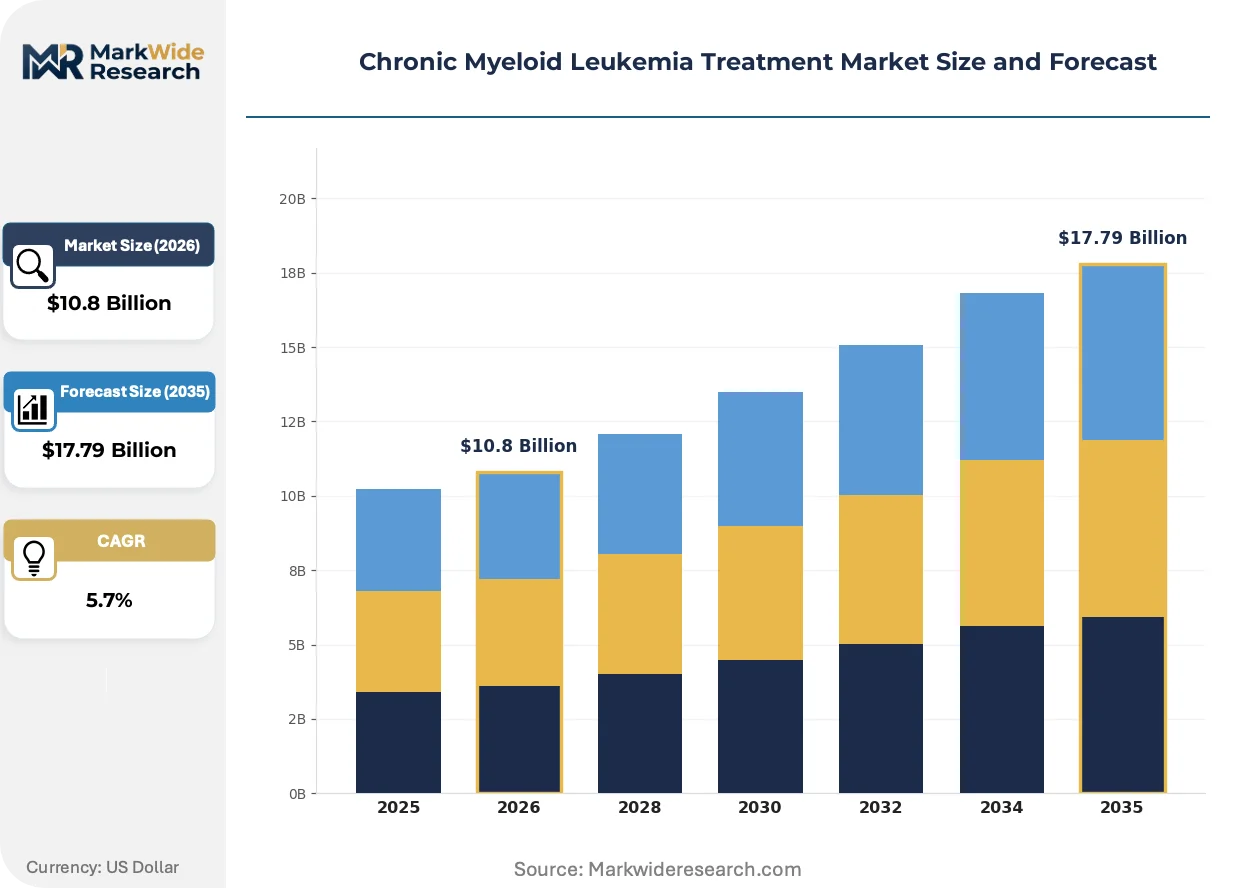
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.79 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tyrosine Kinase Inhibitors, Chemotherapy, Immunotherapy, Stem Cell Transplant, Targeted Therapy Therapy Area: First-Line Treatment, Second-Line Treatment, Maintenance Therapy, Relapse Management End User: Specialty Clinics, Research Hospitals, Oncology Centers, Hematology Labs Delivery Mode: Oral, Intravenous, Subcutaneous, Transplantation |
| Companies Covered | Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, Teva Pharmaceutical Industries Ltd., Takeda Pharmaceutical Company Limited, Incyte Corporation, F. Hoffmann-La Roche Ltd., Otsuka Pharmaceutical Co. Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Myeloid Leukemia Treatment Market Strategic Shifts & Innovations
Digital biomarker integration is restructuring how molecular response gets measured outside clinical trial settings. Remote patient monitoring platforms compress the interval between treatment adjustment and clinical assessment.
Third-generation tyrosine kinase inhibitors with activity against the T315I mutation are decentralizing treatment decisions from academic medical centers to community oncology practices. These compounds eliminate the need for mutation-specific referral protocols. Smaller practices in the United States adopt them to retain patients who would otherwise transfer to specialized centers. This geographic redistribution is compressing the concentration of CML expertise.
The EMA's conditional marketing authorization pathway is reshaping evidence generation obligations for novel agents. Manufacturers must commit to post-authorization efficacy studies as a condition of initial approval. This framework accelerates patient access while transferring clinical trial risk to the commercial phase. European reference pricing systems amplify the pressure to demonstrate superior outcomes against established comparators.
Integrated health systems are consolidating formulary authority across previously independent oncology centers. Centralized pharmacy and therapeutics committees now govern drug selection for networks spanning multiple states. This buyer concentration shifts negotiation leverage toward volume-based contracting with single-source commitments. The United States exhibits this pattern most acutely as hospital systems acquire community practices.
Chronic Myeloid Leukemia Treatment Market Segmentation
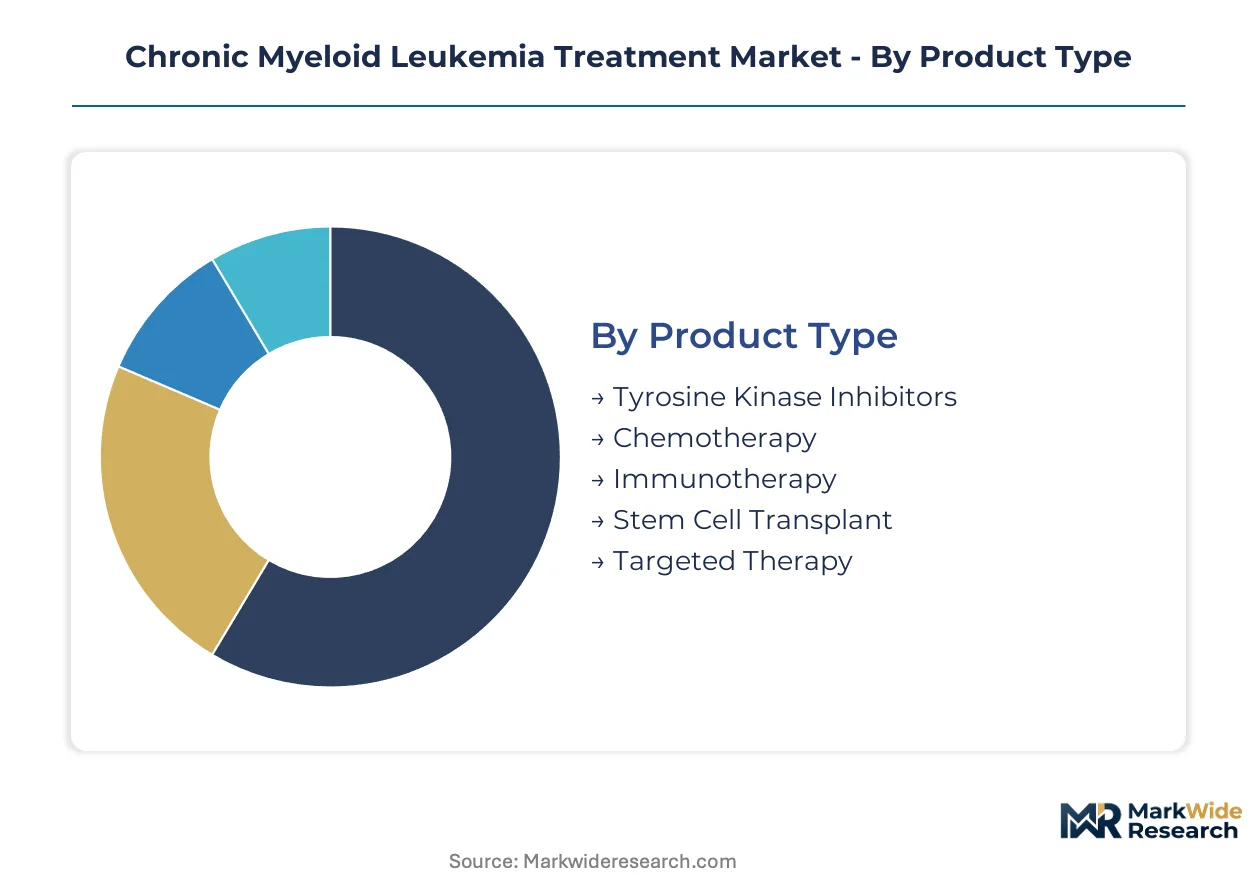
Segmentation in the chronic myeloid leukemia treatment market reveals how regulatory pathways, reimbursement structures, and clinical settings fragment procurement decisions across distinct therapeutic modalities and care delivery environments.
Product Type:
FDA breakthrough therapy designation and EMA conditional marketing authorization requirements vary sharply across these segments, with small-molecule inhibitors facing distinct pharmacovigilance obligations versus cellular therapies.
- Tyrosine Kinase Inhibitors:Oral small-molecule compounds that competitively inhibit BCR-ABL kinase activity. Demand concentrates in United States integrated cancer networks where chronic administration protocols generate recurring prescription volume. FDA accelerated approval pathways compress development timelines for next-generation compounds.
- Immunotherapy:Checkpoint inhibitors and engineered cellular products targeting residual disease populations. Research hospitals with graft-versus-leukemia expertise in Germany and the United Kingdom drive adoption for combination protocols in relapse settings. EMA post-authorization study requirements shape commercialization risk profiles.
- Chemotherapy:Cytotoxic agents reserved for blast crisis progression or TKI resistance.
- Stem Cell Transplant:Allogeneic procedures requiring specialized conditioning regimens and HLA matching infrastructure.
- Targeted Therapy:Non-kinase mechanisms including protein degradation and epigenetic modulation.
Leading the category by volume: Tyrosine Kinase Inhibitors. Expanding most quickly: Immunotherapy.
Therapy Area:
Cost tier differentiation separates chronic oral management from high-acuity intervention episodes, with reimbursement intensity scaling to treatment failure events.
- First-Line Treatment:Initial TKI selection upon chronic phase diagnosis. Community oncology practices in the United States concentrate volume for imatinib and nilotinib prescriptions. PBM formulary placement determines patient access before resistance testing.
- Second-Line Treatment:Switch protocols following primary resistance or intolerance. Academic medical centers in France and Italy manage mutation-directed sequencing to guide dasatinib or bosutinib selection. EMA reference pricing amplifies substitution pressure.
- Maintenance Therapy:Long-term molecular remission surveillance with treatment-free interval protocols.
- Relapse Management:Salvage regimens incorporating third-generation TKIs or transplant evaluation.
Dominating expenditure: First-Line Treatment. Gaining share fastest: Second-Line Treatment.
End User:
Customer type fragmentation reflects credentialing requirements and infrastructure investment thresholds that concentrate advanced modalities in designated centers.
- Oncology Centers:Integrated health system networks standardizing formulary decisions across multi-state footprints. United States hospital systems consolidate procurement through centralized pharmacy and therapeutics committees.
- Research Hospitals:Academic medical centers with specialized graft-versus-leukemia programs and transplant accreditation. Germany's university hospitals and the United Kingdom's NHS tertiary centers concentrate stem cell procedure volume.
- Specialty Clinics:Community-based hematology practices managing stable chronic phase patients.
- Hematology Labs:Diagnostic facilities processing molecular monitoring and mutation profiling.
Highest procedure complexity: Research Hospitals. Fastest consolidation: Oncology Centers.
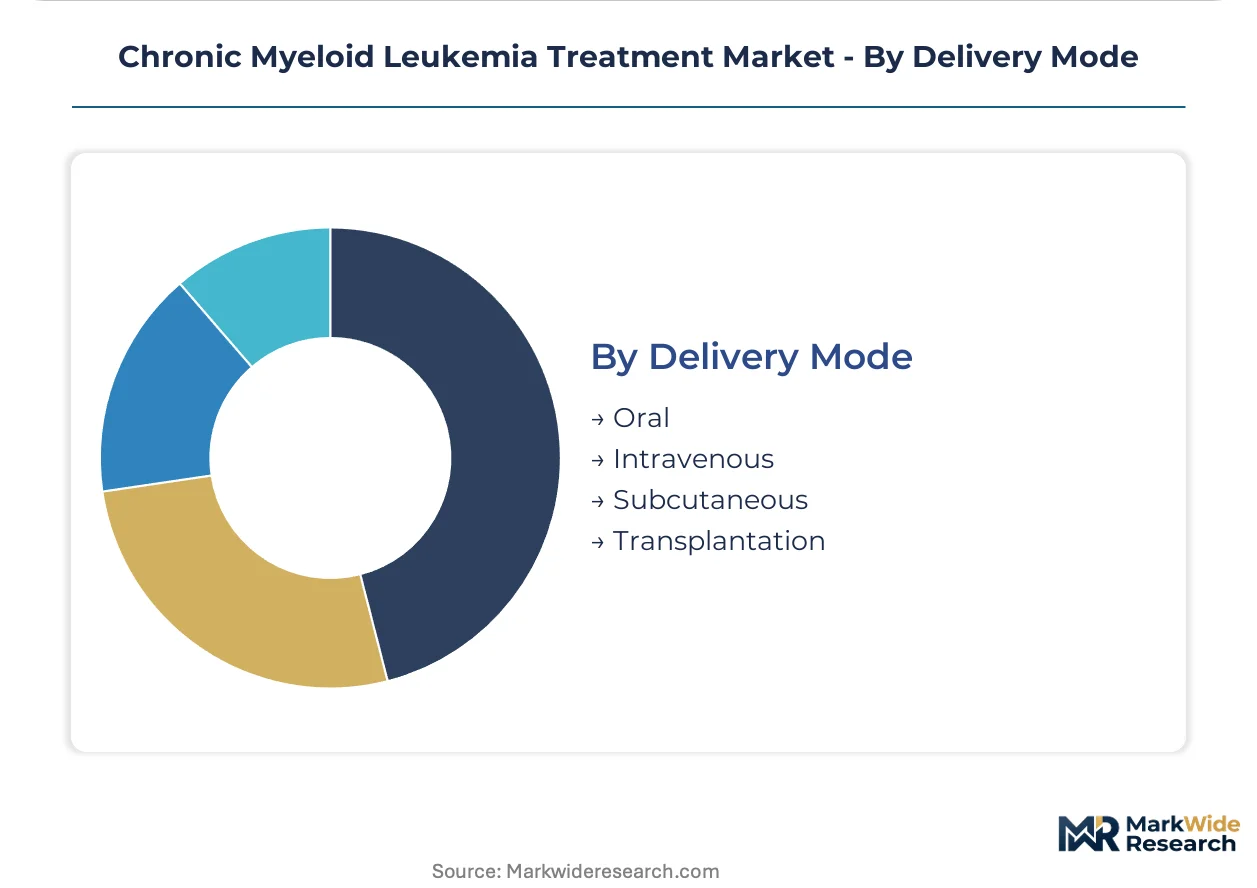
Delivery Mode:
Supply concentration for active pharmaceutical ingredients and cold-chain logistics shapes geographic availability and pricing negotiation leverage.
- Oral:Chronic daily administration enabling home-based compliance monitoring. Specialty pharmacy channels in the United States consolidate fulfillment and adherence tracking through PBM-owned networks.
- Intravenous:Infusion-dependent agents requiring hospital-based administration. European day-clinic infrastructure in Spain and the Netherlands manages intermittent dosing schedules.
- Subcutaneous:Self-administered biologics with reduced healthcare utilization.
- Transplantation:Cellular therapy procedures restricted to accredited centers with apheresis and cryopreservation capabilities.
Widest patient reach: Oral. Most infrastructure-constrained: Transplantation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where integrated cancer networks and specialty pharmacy channels dominate procurement volume for chronic oral therapies. Germany and Japan anchor European and Asian demand respectively through reference pricing systems and universal reimbursement frameworks. Emerging markets in India and Brazil are expanding access programs for tyrosine kinase inhibitors.
United States
Oncology center consolidation across hospital systems drives volume-based contracting for tyrosine kinase inhibitors. The FDA's accelerated approval pathway compresses development timelines while intensifying post-market evidence requirements. The MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor graft-versus-leukemia expertise and transplant referral networks.
Germany
Reference pricing systems amplify substitution pressure for generic imatinib formulations. The EMA's conditional marketing authorization pathway shapes post-authorization study commitments for novel BCR-ABL inhibitors. University hospitals in Heidelberg and Berlin concentrate stem cell procedure volume and molecular diagnostic capabilities.
Japan
PMDA review frameworks prioritize domestic clinical trial data for tyrosine kinase inhibitor approvals. The Ministry of Health, Labour and Welfare maintains universal reimbursement for chronic phase CML management. Tokyo's National Cancer Center and Osaka University Hospital anchor molecular monitoring and treatment-free interval protocols.
India
CDSCO accelerated approval pathways expand patient access to imatinib generics and second-generation TKIs. The country's national pharmaceutical regulator enforces bioequivalence standards for domestic manufacturers. Mumbai and Hyderabad host active pharmaceutical ingredient synthesis clusters supplying specialized kinase inhibitor intermediates.
Brazil
ANVISA's priority review designation compresses registration timelines for oncology therapies. The Ministry of Health's high-cost medication program subsidizes tyrosine kinase inhibitor access through public oncology networks. São Paulo's Hospital das Clínicas and Rio de Janeiro's National Cancer Institute concentrate molecular diagnostic and transplant infrastructure.
Chronic Myeloid Leukemia Treatment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue combination immunotherapy protocols and real-world evidence platforms. The market structure concentrates around large-cap pharmaceutical developers with manufacturing scale in small-molecule synthesis. Three archetypes dominate: vertically integrated originators with patent-protected portfolios, generic manufacturers exploiting formulation cliffs, and biotech specialists in mutation-resistant compounds. Competitive moves center on single-source contracting with integrated health systems and strategic partnerships with molecular diagnostic vendors.
Among Swiss-based originators, Novartis AG anchors the tyrosine kinase inhibitor segment through established manufacturing scale and supply commitments across United States oncology networks. Pfizer Inc. represents geographic diversification strength in European specialty clinic channels. Bristol-Myers Squibb Company exemplifies R&D intensity in next-generation targeted compounds and combination protocol development.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Teva Pharmaceutical Industries Ltd. |
| Takeda Pharmaceutical Company Limited |
| Incyte Corporation |
| F. Hoffmann-La Roche Ltd. |
| Otsuka Pharmaceutical Co. Ltd. |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Kinase inhibitor intermediate pricing indices in India and China cascade through three-tier cost structures that separate originator-grade from authorized-generic and commodity-compound supply tiers. FDA accelerated approval timelines compress procurement cycles for branded BCR-ABL inhibitors while EMA reference pricing in Germany amplifies substitution pressure on mature formulations.
Pricing Analysis
Volume concentrates in chronic oral tyrosine kinase inhibitors while margins pool in mutation-resistant third-generation compounds. Price differentiation rests on FDA breakthrough therapy designation status and companion diagnostic bundling. Cost compression in first-line imatinib generics intensifies because German reference pricing systems amplify substitution incentives. Community oncology practices in the United States exhibit highest price sensitivity; integrated cancer networks with single-source contracts demonstrate lowest.
Supply Chain Analysis
Specialized chemical synthesis workforce scarcity in Hyderabad and Shanghai constrains active pharmaceutical ingredient batch release timelines for BCR-ABL inhibitor intermediates. Manufacturing concentrates in India, China, and Switzerland. Raw material dependencies include piperazine derivatives, fluorinated aromatics, and chiral resolution agents. Single-source vulnerability threatens supply continuity for T315I-resistant compound precursors. Distribution runs through PBM-owned specialty pharmacy networks consolidating patient access and adherence monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active pharmaceutical ingredient synthesis capacity bottlenecks in South Asian manufacturing clusters prop pricing power for vertically integrated originators with captive intermediate supply.
For Market Incumbents: Anticipate generic erosion acceleration in first-generation imatinib formulations by securing single-source contracts with consolidating United States oncology networks. Prioritize backward integration into specialized intermediate synthesis to reduce exposure to Indian and Chinese export restriction risks. Real-world evidence infrastructure investment represents the critical lever for FDA confirmatory trial compliance. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for mutation-resistant compound developers to capture second-line treatment share from academic medical center referral networks. The most penetrable segment lies in community oncology practices adopting third-generation tyrosine kinase inhibitors to retain patients locally. A go-to-market angle pairing molecular diagnostic platforms with treatment protocols bypasses formulary committee resistance. For Investors and Strategic Acquirers: Distressed-cycle entries favor biotech specialists with T315I-resistant compound pipelines and existing EMA conditional marketing authorization commitments in Germany. Long-term viability centers on five-to-ten year windows for combination immunotherapy protocol development before checkpoint inhibitor commoditization. Watch FDA post-market surveillance requirement intensity as the inflection signal for real-world evidence platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Platform Development | FDA confirmatory trial requirements create demand for longitudinal patient registry databases. |
| Companion Diagnostic Partnership | Next-generation sequencing integration with treatment selection protocols secures formulary placement. |
| Specialty Pharmacy Channel Integration | PBM-owned networks consolidate oral chronic therapy fulfillment and adherence monitoring. |
| Regulatory Approval Pathway Optimization | Rolling submission strategies compress FDA review timelines for breakthrough-designated compounds. |
| Manufacturing Scale-Up in Controlled Geographies | Site validation in Switzerland reduces exposure to Indian and Chinese API supply disruptions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated demand assumptions. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases supplied quantitative benchmarks. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation reconciled volume estimates.
Granularity-level modeling treated treatment line, dosage form, administration route, and regional regulatory cluster as distinct forecast dimensions. CAGRs derived from patient incidence projections, therapy persistence rates, and pricing trajectory assumptions across the analysis window. Mutation prevalence data and resistance testing adoption curves informed second-line treatment share allocations. Reimbursement intensity scaling by treatment failure episode shaped value projections.
The model assumes a particular technology adoption path; alternative pathways for digital biomarker integration would alter the outlook. Forecasts reflect assumptions regarding FDA accelerated approval pathway stability and EMA conditional marketing authorization continuity. Material deviation in payer consolidation velocity or reference pricing expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Chronic Smell and Flavor Loss Treatment Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market