
 Dilated Cardiomyopathy Market | 2026-2036
Dilated Cardiomyopathy Market Size, Share, and Industry Trends Forecast 2026-2036
Dilated Cardiomyopathy Market Analysis
The EU Medical Device Regulation is expanding compliance requirements for implantable cardiac devices, forcing manufacturers to recertify legacy product lines under stricter clinical-evidence thresholds. Bristol-Myers Squibb leverages its cardiovascular R&D infrastructure to sustain a pipeline of heart failure therapeutics. Novartis anchors its position through entrenched relationships with European and North American hospital systems. Pfizer competes by extending manufacturing scale across multiple dosage formulations for oral heart failure medications.
Dilated cardiomyopathy denotes a myocardial disorder characterized by ventricular chamber enlargement and systolic dysfunction, typically presenting with ejection fractions below 40 percent, and serves clinically to precipitate progressive heart failure requiring pharmacological or device-based intervention. Implantable Cardioverter Defibrillators dominate the product type segment due to established mortality benefit in sudden cardiac death prevention, while Cardiac Resynchronization Therapy Devices represent the fastest-growing category as guidelines expand indications to milder heart failure classes. Hospitals command the end user landscape through concentration of electrophysiology labs and implanting physicians, whereas Homecare Settings are gaining share as remote monitoring technologies mature.
FDA premarket approval pathways and EMA centralized procedures govern device commercialization, with both agencies demanding randomized trial data for novel therapeutic indications. The EU AI Act introduces additional scrutiny for algorithm-enabled diagnostic tools used in cardiac imaging and risk stratification. Stakeholders must monitor evolving reimbursement thresholds for combination drug-device therapies across Medicare, national health services, and statutory insurance frameworks.
Market Dynamics
Hospital-based cardiac care units are scaling device therapy adoption as first-line intervention, compressing the traditional pharmacological treatment window and forcing manufacturers to recertify legacy implantable devices under stricter clinical-evidence thresholds imposed by the EU Medical Device Regulation.
Growth Catalysts
- FDA Breakthrough Device Designations:Accelerated premarket approval pathways compress time-to-market for novel therapeutics targeting systolic dysfunction below 40 percent ejection fraction.
- Cardiac Resynchronization Therapy Devices:Expanded guideline indications to milder heart failure classes drive implant volumes in electrophysiology labs across Germany, Japan, and the United States.
- Remote Monitoring Technologies:Maturation of algorithm-enabled diagnostic tools shifts care delivery toward Homecare Settings, extending patient surveillance beyond hospital walls.
Market Restraints
- EU MDR Recertification Burden:Legacy implantable cardiac device portfolios face extended compliance timelines and supplemental clinical trial requirements.
- Specialized Physician Concentration:Electrophysiology-trained implanting physicians cluster in tertiary heart failure centers, constraining procedure capacity outside metropolitan hospital systems.
- Algorithm-Enabled Diagnostic Scrutiny:The EU AI Act introduces additional validation requirements for cardiac imaging risk stratification tools, delaying commercial deployment.
Strategic Opportunities
- Combination Drug-Device Therapies:Reimbursement threshold evolution across Medicare and statutory insurance frameworks creates white space for integrated treatment protocols.
- Japan's Aging Demographics:Concentrated patient volumes in specialized heart failure centers support premium device penetration in the Asia-Pacific's most reimbursement-dense market.
- EMA Accelerated Assessment Pathways:Centralized procedures for novel therapeutic indications enable faster geographic expansion across European hospital networks.
Industry Challenges
- Electrophysiology Talent Pipeline:Extended fellowship training requirements and procedure volume thresholds limit the supply of qualified implanting physicians.
- CE Mark Transition Complexity:Manufacturers must maintain parallel regulatory dossiers during the MDR transition period, straining quality management system resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dilated Cardiomyopathy Market |
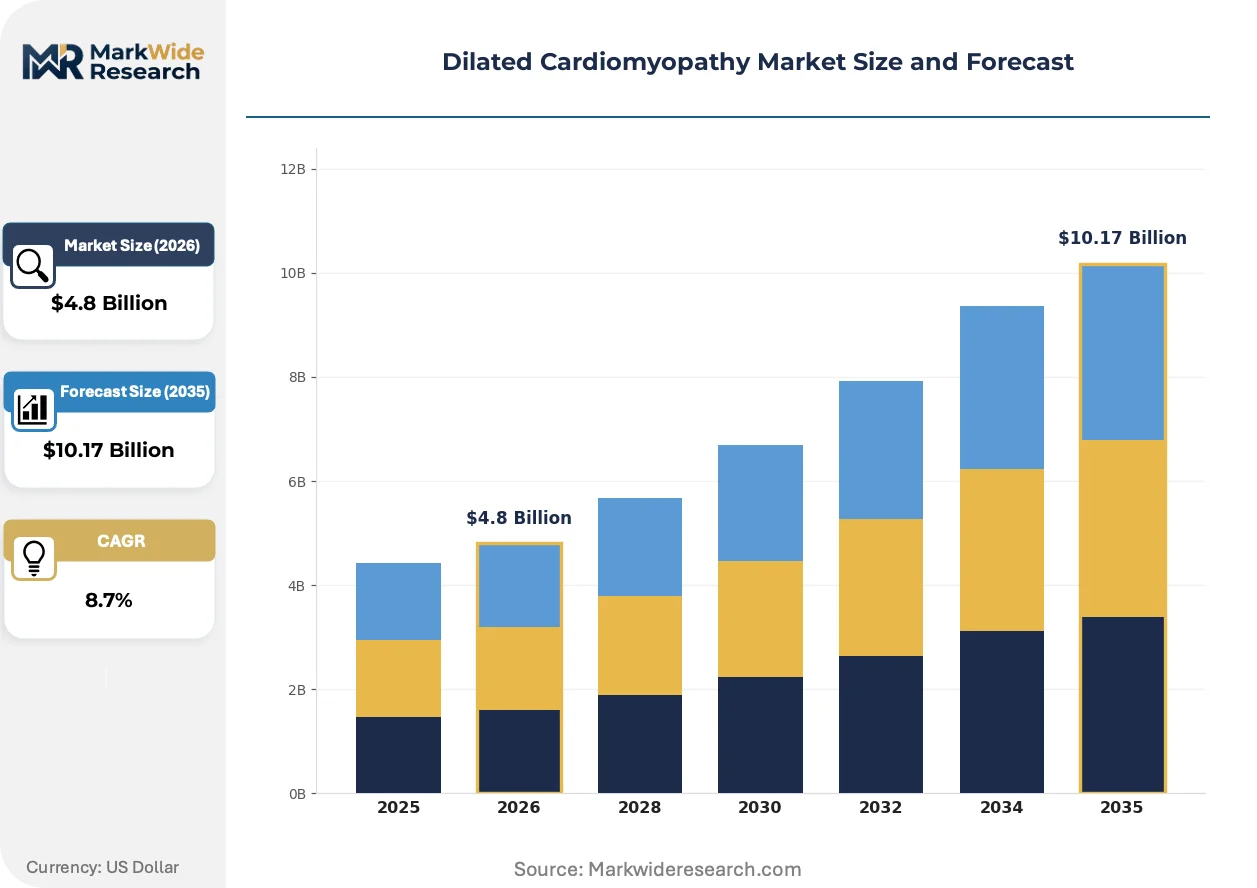
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Resynchronization Therapy Devices, Implantable Cardioverter Defibrillators, Medications, Electrical Stimulation Devices End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: Intravenous, Oral, Implantable, Transdermal Treatment Type: Pharmacological, Surgical, Lifestyle Modification, Device Therapy |
| Companies Covered | Bristol-Myers Squibb Company, Novartis AG, Pfizer Inc., AstraZeneca PLC, Cumberland Pharmaceuticals, Constant Therapeutics LLC, Berlin Cures, Capricor Therapeutics Inc., Rocket Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dilated Cardiomyopathy Market Emerging Trajectories
Device miniaturization and algorithmic risk stratification are converging to reshape how dilated cardiomyopathy patients transition from pharmacological management to invasive intervention.
Leadless pacemaker technology is expanding into the cardiac resynchronization therapy segment, enabling left ventricular pacing without transvenous leads. Heart failure centers in Germany and the United States are piloting these systems for patients with vascular access limitations. The technology is expanding into previously contraindicated anatomies, compressing the eligible population for traditional transvenous systems.
The EU AI Act imposes conformity assessment requirements on machine-learning diagnostic tools used in echocardiographic ejection fraction quantification. Device manufacturers must now submit algorithm performance data alongside hardware technical documentation. Cardiac imaging software vendors serving European hospital systems are restructuring quality management systems to accommodate this layered compliance framework.
After-sales service unbundling is fragmenting the traditional device procurement bundle in North American hospital systems. Purchasing departments now negotiate remote monitoring subscriptions, lead extraction coverage, and generator replacement warranties as separate line items. This disaggregation is most visible in United States academic medical centers with dedicated value analysis committees.
Dilated Cardiomyopathy Market Segmentation
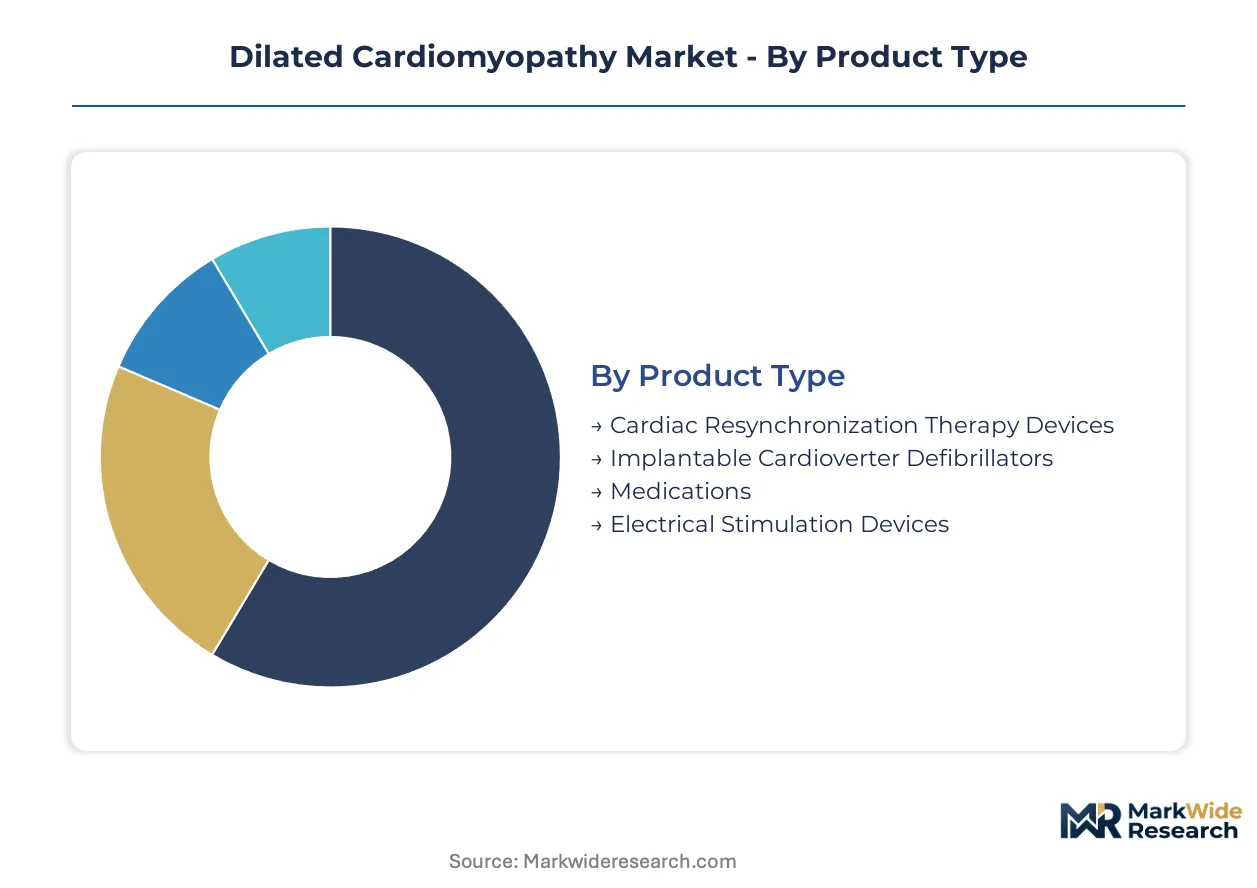
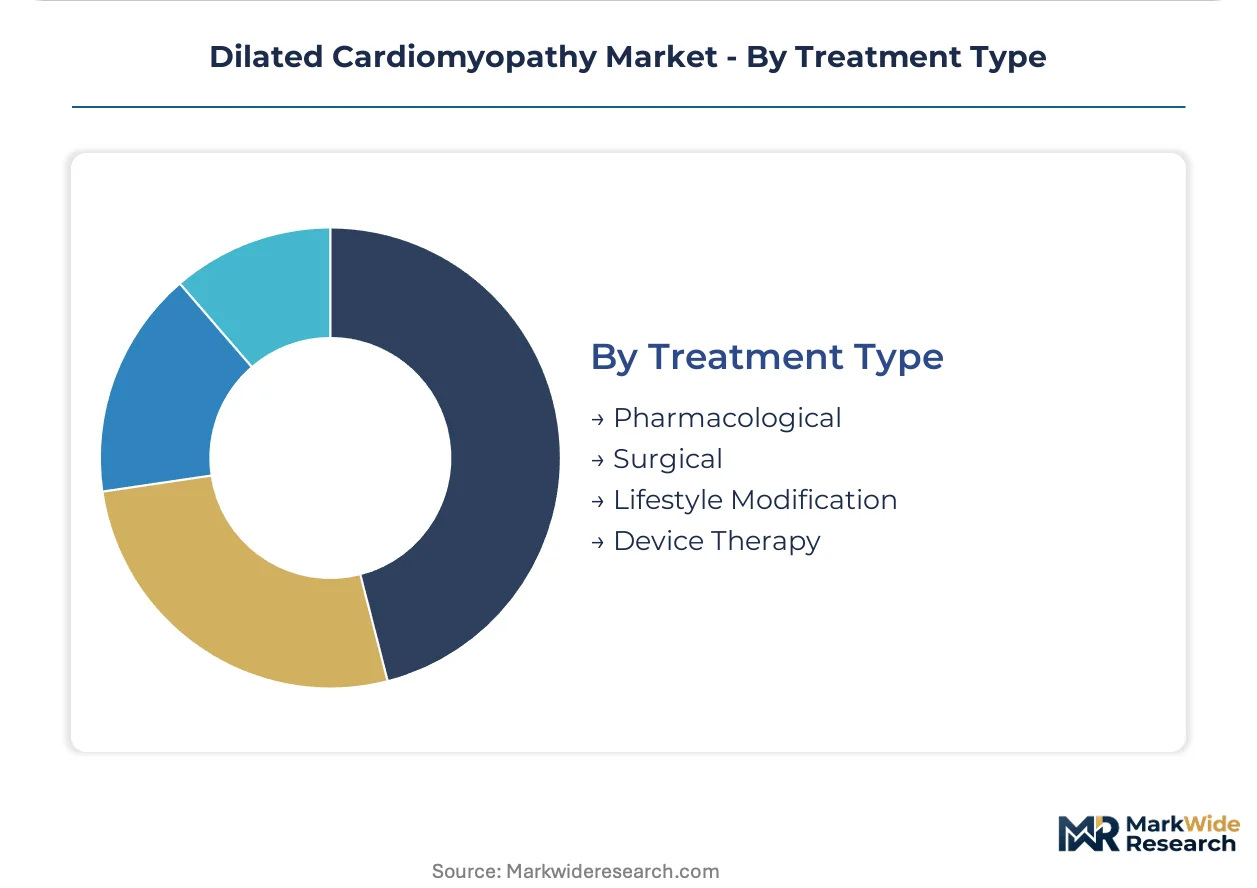
Device therapy and pharmacological intervention serve distinct patient risk strata in dilated cardiomyopathy, with reimbursement density and implanting physician availability determining where each modality dominates. Segmentation reveals how treatment pathways bifurcate between acute hospital-based intervention and longitudinal ambulatory management.
Product Type:
Customization intensity varies sharply across this category, from patient-programmable implantable devices to standardized oral formulations.
- Implantable Cardioverter Defibrillators:These battery-powered devices deliver tiered therapy for ventricular tachyarrhythmias through transvenous leads positioned in the right ventricle. Demand clusters in tertiary heart failure centers across the United States and Germany, where electrophysiology lab density supports high implant volumes and established mortality benefit drives first-line adoption.
- Cardiac Resynchronization Therapy Devices:Biventricular pacing systems resynchronize depolarization in dyssynchronous ventricles via left ventricular leads placed through the coronary sinus. Japanese and United States hospitals are expanding indications to NYHA Class II patients, accelerating implant growth as guidelines broaden eligibility criteria.
- Medications:Oral formulations including ACE inhibitors, beta-blockers, and SGLT2 inhibitors constitute the foundational pharmacological regimen prescribed across all care settings.
- Electrical Stimulation Devices:Emerging neuromodulation systems target autonomic imbalance through vagus nerve or spinal cord stimulation.
Leading the category by volume: Implantable Cardioverter Defibrillators. Growing fastest: Cardiac Resynchronization Therapy Devices.
End User:
Capital intensity and regulatory accreditation requirements create steep barriers between institutional settings.
- Hospitals:Academic medical centers and community hospitals with electrophysiology labs concentrate device implantation, generator replacements, and lead extraction procedures under cardiac surgery backup.
- Homecare Settings:Remote monitoring infrastructure enables post-implant surveillance and medication adherence tracking outside institutional walls, with United States and German reimbursement frameworks expanding coverage for telecardiology services.
- Clinics:Outpatient cardiology practices manage stable patients on optimized medical therapy and coordinate referral for device evaluation.
- Rehabilitation Centers:Structured exercise programs and patient education for heart failure self-management occur in post-acute settings.
Volume concentrates in hospitals. Homecare Settings are climbing the fastest as remote monitoring technologies mature.
Delivery Mode:
Invasiveness correlates directly with reimbursement complexity and regulatory scrutiny across this spectrum.
- Implantable:Subcutaneous or transvenous placement requires surgical suite resources and specialized implanting physicians, with EMA and FDA premarket approval pathways governing commercialization.
- Oral:Tablet and capsule formulations of guideline-directed medical therapy enable outpatient titration and long-term adherence monitoring.
- Intravenous:Inotropic support and acute decompensated heart failure management require infusion center or inpatient administration.
- Transdermal:Patch-based drug delivery and external wearable defibrillators occupy niche indications.
Oral delivery dominates prescription volume. Implantable systems command the steepest expansion trajectory as device indications broaden.
Treatment Type:
Intervention timing and reversibility distinguish acute rescue from chronic disease modification approaches.
- Device Therapy:Implantable defibrillators and resynchronization systems provide electrical intervention for arrhythmia prevention and hemodynamic optimization, with Japanese and German heart failure centers driving adoption through specialized referral networks.
- Pharmacological:Neurohormonal antagonists and SGLT2 inhibitors form the evidence-based foundation for systolic heart failure management across all geographies.
- Surgical:Ventricular assist device implantation and cardiac transplantation represent end-stage options concentrated in high-volume United States transplant centers.
- Lifestyle Modification:Sodium restriction, exercise training, and implantable device activity monitoring support self-management.
Pharmacological treatment anchors volume. Device Therapy is gaining share fastest as electrophysiology capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleveland Clinic anchors device implantation volume in North America, while specialized heart failure centers in Heidelberg and Tokyo concentrate electrophysiology capacity for advanced cardiac interventions.
United States
Academic medical centers in Boston and Houston drive CRT-D adoption through expanded NYHA Class II indications. FDA breakthrough device designations compress premarket timelines for novel defibrillator platforms. The Texas Medical Center cluster generates procedure volume through high-volume electrophysiology labs with cardiac surgery backup.
Germany
Heidelberg and Berlin heart failure centers scale leadless pacemaker trials for vascular access-limited patients. EU MDR recertification requirements force legacy device portfolio updates under stricter clinical-evidence thresholds. Baden-Württemberg manufacturers restructure quality management systems to accommodate algorithm-enabled diagnostic conformity assessments.
Japan
Aging demographics concentrate patient volumes in Tokyo and Osaka specialized heart failure centers with premium reimbursement density. PMDA accelerated approval pathways enable faster geographic expansion for novel therapeutic devices. The Kanto region leads Asia-Pacific implant volumes through entrenched hospital system relationships.
United Kingdom
London teaching hospitals pilot remote monitoring subscriptions unbundled from traditional device procurement bundles. NICE technology appraisals govern combination drug-device therapy reimbursement thresholds. The Southeast England cluster advances telecardiology coverage expansion for post-implant surveillance beyond hospital walls.
Switzerland
Zurich and Geneva cardiac centers attract cross-border patient flows from EU member states seeking specialized device therapy. Swissmedic maintains alignment with EMA centralized procedures while preserving national flexibility for novel indication assessments. The Basel pharmaceutical corridor supports integrated drug-device development pipelines.
Dilated Cardiomyopathy Market Vendor Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with cardiovascular R&D infrastructure. Tier-one players anchor market share through hospital system relationships and manufacturing scale across multiple dosage formulations. Three archetypes dominate: Big Pharma with heart failure portfolios, emerging gene therapy specialists, and device manufacturers with algorithm-enabled diagnostic platforms. M&A activity targets electrophysiology talent and remote monitoring capabilities; portfolio diversification extends into combination drug-device protocols.
Among US-based pharmaceutical conglomerates, Bristol-Myers Squibb Company and Pfizer Inc. exemplify the diversified archetype with entrenched cardiovascular development infrastructure. Novartis AG represents the European hospital-system-anchored position through specialized heart failure center relationships. AstraZeneca PLC occupies the SGLT2 inhibitor-led pharmacological tier alongside emerging device integration strategies.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Novartis AG |
| Pfizer Inc. |
| AstraZeneca PLC |
| Cumberland Pharmaceuticals |
| Constant Therapeutics LLC |
| Berlin Cures |
| Capricor Therapeutics Inc. |
| Rocket Pharmaceuticals Inc. |
| Others |
Supply Flow & Price Mechanics
United States academic medical centers with dedicated value analysis committees concentrate procurement power, compressing device margins through unbundled negotiations for remote monitoring subscriptions and lead extraction coverage.
Pricing Analysis
Outcome-based pricing anchors device reimbursement across Medicare and German statutory insurance frameworks, tying implantable system payments to mortality reduction and heart failure hospitalization avoidance. Three-tier pricing structure across premium, standard, and economy levels separates leadless pacemaker platforms from traditional transvenous systems and refurbished generator replacements. Pricing pressure stems from after-sales service unbundling in North American hospital systems. Community hospitals with limited electrophysiology capacity exhibit highest price sensitivity, while Japanese specialized heart failure centers with premium reimbursement density show lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates in the United States Inflation Reduction Act and Japan's METI procurement guidelines reshape sourcing for battery cells and semiconductor components in implantable devices. Manufacturing concentrates in Ireland, Switzerland, and Costa Rica for final device assembly, drawing from Malaysian and Mexican suppliers for lead conductors and titanium enclosures. Single-source vulnerability persists for specialized lithium-silver vanadium oxide battery chemistry. Distribution runs through hospital procurement consortia and group purchasing organizations in the United States, direct tender processes in Germany, and specialized cardiac device distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrophysiology-trained implanting physician scarcity props device pricing, constraining procedure capacity outside tertiary heart failure centers and preserving margin structures for qualified manufacturers.
For Market Incumbents: Acquire remote monitoring algorithm capabilities to defend against software-enabled diagnostic entrants. Backward integration into lead conductor manufacturing mitigates Malaysian supply concentration. Lock in long-term hospital system partnerships before EU MDR recertification timelines strain competitor portfolios. For New Entrants and Emerging Players: FDA Breakthrough Device Designation in the United States opens a window for leadless cardiac resynchronization therapy platforms in vascular access-limited populations. Target United States academic medical centers with unbundled procurement committees as the most penetrable customer segment. Lead with value-based contracting proposals tied to heart failure hospitalization reduction metrics. For Investors and Strategic Acquirers: The window for entry favors gene therapy specialists with cardiovascular pipelines ahead of device-device convergence. Long-term viability hinges on combination drug-device protocol ownership. Watch PMDA accelerated approval pathway utilization rates as the inflection signal for Asia-Pacific premium market access.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification compresses timelines for legacy device portfolio updates under stricter clinical-evidence thresholds. |
| Hospital System Partnership | Cleveland Clinic and Texas Medical Center clusters concentrate implant volumes and lock in preferred vendor status. |
| Software Companion Development | Algorithm-enabled diagnostic tools face EU AI Act conformity assessments requiring quality management system restructuring. |
| Reimbursement Strategy | Medicare and NICE technology appraisals govern combination drug-device therapy coverage thresholds. |
| Regulatory Approval Pathway | PMDA accelerated pathways enable faster geographic expansion across Japanese specialized heart failure centers. |
Methodological Framework
Independent corroboration across electrophysiology lab directors, hospital procurement managers, and regulatory affairs leads at device manufacturers underwrites the qualitative findings. Primary interviews with biomedical engineers and GPO contracts managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases anchor the assessment. Bottom-up implant volume modeling and top-down market sizing triangulate across the analysis window.
Comparable historical periods spanning device approval waves and guideline revision cycles anchor the projection framework. Segmentation dimensions include product type, end user setting, delivery mode, and treatment type across the modeling period. CAGRs derive from procedure volume trajectories, pricing evolution patterns, and reimbursement density differentials by geography. Forecast inputs incorporate electrophysiology fellowship graduation rates and EU MDR transition timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for leadless cardiac resynchronization therapy would alter the outlook. Forecasts reflect assumptions regarding guideline expansion timing and reimbursement threshold evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Cardiac Valvulotome Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Vasculitis Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Global Statin Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Venous Thromboembolism Treatment Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Coronary Artery Disease Therapeutics Market