
 Chronic Pulmonary Hypertension Treatment Market | 2026-2036
Chronic Pulmonary Hypertension Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Pulmonary Hypertension Treatment Market Outlook
Aftermarket patient support program revenue is narrowing as manufacturers consolidate access services in-house. United Therapeutics anchors its position through vertical integration into specialty pharmacy distribution. Bayer leverages its cardiovascular portfolio to sustain presence across European reimbursement markets. Johnson & Johnson competes through hospital system partnerships that streamline prostacyclin infusion logistics.
Chronic pulmonary hypertension treatment encompasses pharmacological interventions targeting elevated pulmonary arterial pressure exceeding 25 mmHg at rest, including endothelin receptor antagonists that block vasoconstrictive signaling and prostacyclin analogs that promote vascular dilation through cAMP pathway activation. These therapies serve to delay disease progression, improve exercise capacity, and reduce right heart failure mortality in patient populations with World Health Organization Group 1 classifications. Oral administration routes dominate prescription volumes due to patient preference for home-based management, while intravenous and subcutaneous delivery segments retain premium positioning for functional class IV cases requiring continuous hemodynamic support. Prostacyclin analogs represent the fastest-growing product category as clinicians shift toward upfront combination regimens rather than sequential monotherapy escalation.
FDA orphan drug designations and EMA priority medicines eligibility accelerate development timelines for novel vasodilator classes, while WHO pulmonary hypertension diagnostic guidelines standardize treatment initiation criteria across national health systems. Reimbursement authorities in Germany, France, and Japan apply distinct cost-effectiveness thresholds that fragment pricing power for single-source therapies. Stakeholders must monitor evolving biosimilar entry timelines for expired prostacyclin patents and corresponding shifts in payer contracting leverage.
Market Dynamics
Specialty clinics are consolidating prostacyclin infusion services in-house, compressing margins for third-party home infusion providers and reshaping how manufacturers contract for patient support programs.
Growth Catalysts
- FDA orphan drug incentives:Tax credits and extended exclusivity accelerate investment in novel vasodilator classes, shortening development timelines for therapies targeting small patient populations.
- Combination therapy protocols:Clinicians increasingly initiate dual endothelin receptor antagonist and prostacyclin analog regimens upfront, expanding addressable prescription volumes per patient.
- Japan's rare disease framework:Sakigake designation and priority review vouchers incentivize sponsors to launch pulmonary hypertension therapies in the Japanese market earlier than historical patterns.
Market Restraints
- Prostacyclin API concentration:Active pharmaceutical ingredient synthesis for epoprostenol and treprostinil concentrates among a limited supplier base in India and China, exposing manufacturers to supply disruption risk.
- Reimbursement heterogeneity:Germany's IQWiG benefit assessment applies distinct cost-effectiveness thresholds versus France's HAS evaluation, fragmenting pricing power across European markets.
- Biologic complexity barriers:Inhaled prostacyclin formulations require specialized nebulizer device compatibility, limiting generic substitution and maintaining high production qualification costs.
Strategic Opportunities
- Biosimilar entry timelines:Expired prostacyclin patents in the United States create openings for follow-on biologics to capture share through payer contracting leverage.
- Pediatric investigation plans:EMA requirements for pediatric study commitments generate regulatory exclusivity extensions and first-mover positioning in underdeveloped age-segment indications.
- Telemedicine-enabled monitoring:Remote hemodynamic assessment platforms allow specialty clinics to manage functional class III patients outside traditional infusion center footprints.
Industry Challenges
- Right heart catheterization training gaps:Confirmatory diagnosis requires invasive hemodynamic measurement, and interventional cardiology fellowship programs produce insufficient specialists relative to suspected case volume.
- Cold chain integrity for biologics:Prostacyclin analog stability requirements demand continuous temperature-controlled distribution, complicating last-mile delivery to rural patient populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Pulmonary Hypertension Treatment Market |
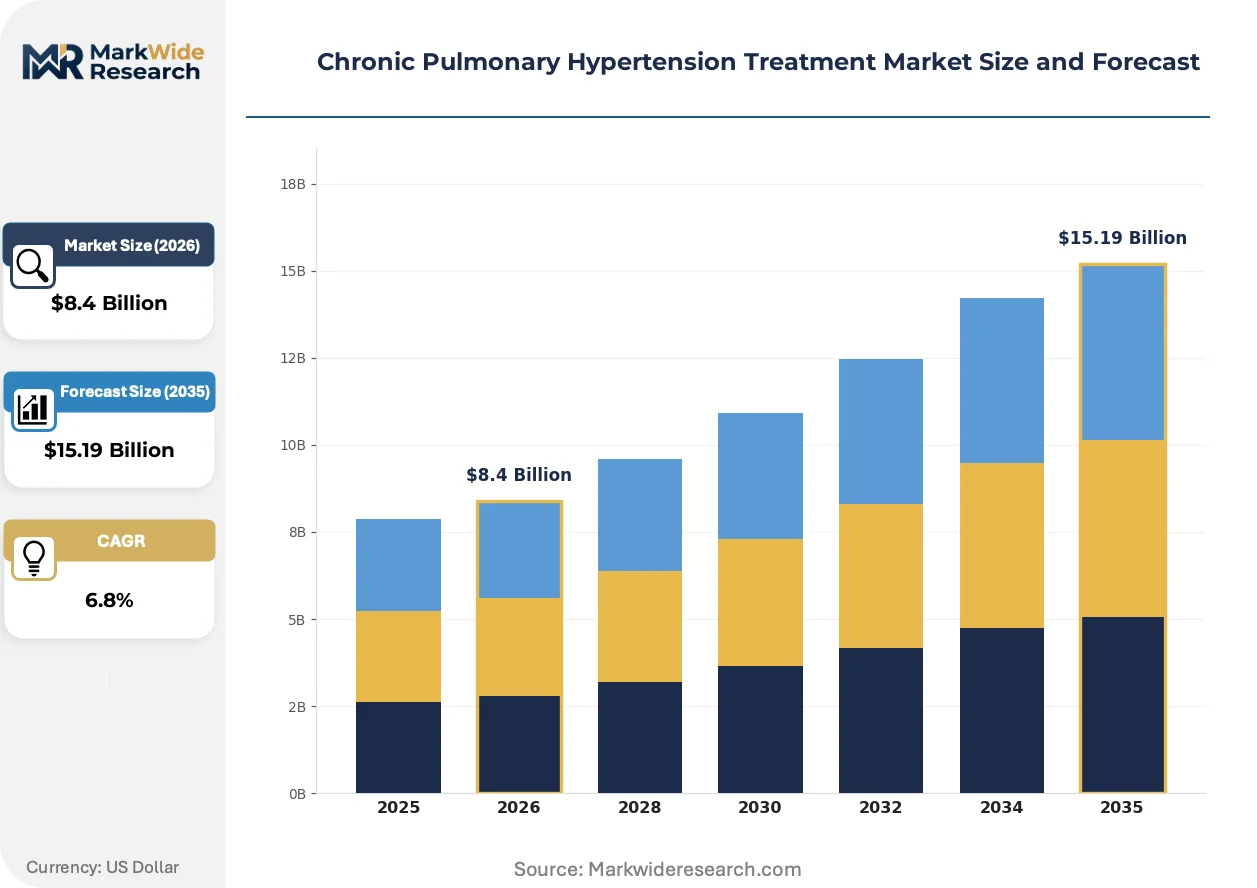
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endothelin Receptor Antagonists, Phosphodiesterase-5 Inhibitors, Prostacyclin Analogs, Soluble Guanylate Cyclase Stimulators Administration Route: Oral, Intravenous, Inhalation, Subcutaneous End User: Hospitals, Specialty Clinics, Homecare Settings, Ambulatory Surgical Centers Therapy Area: Heart Failure, Respiratory Disorders, Rare Diseases, Vascular Conditions |
| Companies Covered | GlaxoSmithKline plc, United Therapeutics, Bayer, Johnson & Johnson, Gilead Sciences, AstraZeneca plc, Boehringer Ingelheim International GmbH, Novartis International AG, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Pulmonary Hypertension Treatment Market Strategic Shifts
Oral prostacyclin receptor agonists are compressing the functional class threshold for hospital-based infusion therapy, while regulatory frameworks accelerate novel mechanism approvals.
Selexipag and other oral IP receptor agonists are hybridizing treatment pathways previously dominated by parenteral prostacyclin analogs. Functional class III patients who would have escalated to subcutaneous treprostinil now maintain stability on oral monotherapy. This shift is compressing the addressable market for infusion pump manufacturers and specialty pharmacy services.
EMA's priority medicines scheme and FDA's breakthrough therapy designation are compressing review timelines for novel soluble guanylate cyclase stimulators. Sponsors receive rolling review protocols that parallelize clinical and manufacturing module submissions. European reference pricing systems are responding with earlier health technology assessment engagements to preempt launch delays.
Patient advocacy organizations are consolidating purchasing influence through dedicated pharmacy benefit carve-outs for rare cardiopulmonary conditions. United States specialty pharmacies now compete on adherence program quality rather than distribution margin alone. This behavioral shift is most visible in Pennsylvania and California where pulmonary hypertension foundation chapters maintain direct relationships with regional payers.
Chronic Pulmonary Hypertension Treatment Market Segmentation
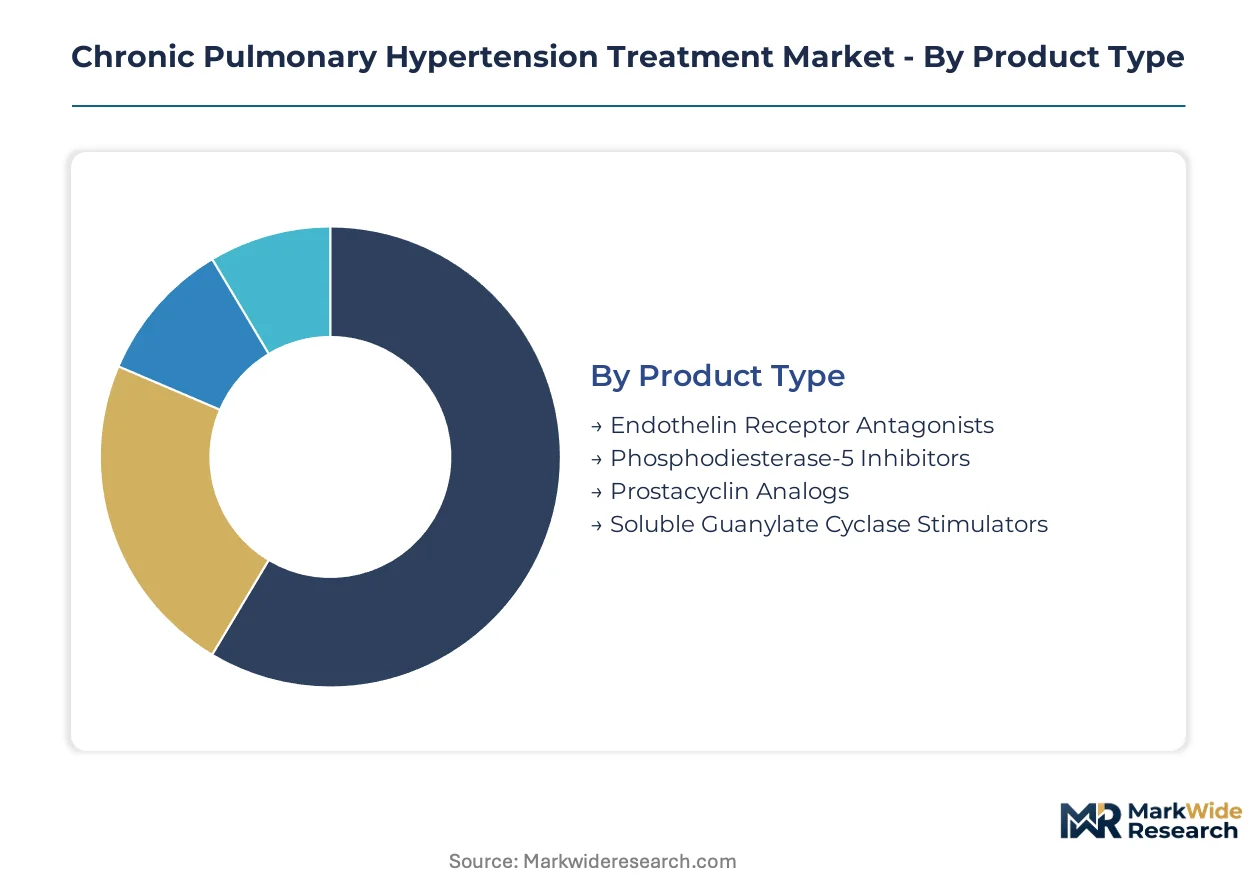
Segmentation in chronic pulmonary hypertension treatment reveals distinct service intensity profiles across delivery modes. Patient support requirements vary dramatically between infusion-dependent therapies and oral regimens, reshaping manufacturer investment in adherence infrastructure.
Product Type:
After-sales service intensity peaks with prostacyclin analogs requiring pump maintenance, cold chain logistics, and 24-hour nursing hotlines.
- Prostacyclin Analogs:Continuous infusion therapies demand specialized pump programming, cartridge replacement training, and emergency backup systems. Demand concentrates in United States specialty clinics where United Therapeutics and Johnson & Johnson maintain captive pharmacy networks for treprostinil and epoprostenol delivery. Cold chain integrity requirements and infusion site infection management drive highest per-patient service costs.
- Endothelin Receptor Antagonists:Oral bosentan and ambrisentan block ETA/ETB receptors to reverse pulmonary vascular remodeling. German and Japanese prescribing patterns favor these as first-line combination anchors due to favorable liver monitoring protocols and established reimbursement. Monthly pharmacy fulfillment and hepatotoxicity surveillance create moderate service intensity.
- Phosphodiesterase-5 Inhibitors:Sildenafil and tadalafil enhance nitric oxide signaling through cGMP preservation.
- Soluble Guanylate Cyclase Stimulators:Riociguat directly stimulates sGC independent of nitric oxide availability.
Endothelin receptor antagonists hold the largest share; momentum sits with prostacyclin analogs.
Administration Route:
Route selection dictates supply chain complexity and margin structure through distribution qualification requirements.
- Oral:Tablet and capsule formulations dominate prescription volumes through patient preference for home autonomy. United States and Japanese formularies prioritize oral selexipag and tadalafil for functional class II-III patients, minimizing hospital dependency. Standard pharmacy distribution with standard cold chain requirements supports lowest per-dose logistics cost.
- Intravenous:Epoprostenol sodium requires continuous central venous catheter infusion with programmable pump systems. German hospital pharmacies and United States home infusion providers maintain specialized compounding facilities for daily bag preparation. Sterile manufacturing qualification and catheter-related sepsis protocols generate highest regulatory burden.
- Subcutaneous:Treprostinil infusion through portable micro-pumps enables outpatient functional class III management.
- Inhalation:Iloprost nebulization demands device compatibility verification and proper breathing technique training.
Oral administration commands volume leadership; intravenous delivery claims premium positioning.
End User:
Site-of-care economics drive divergent contracting strategies between institutional purchasers and dispersed home settings.
- Specialty Clinics:Dedicated pulmonary hypertension centers concentrate diagnostic catheterization, combination therapy initiation, and clinical trial enrollment. Pennsylvania and California foundation-affiliated clinics in the United States negotiate direct manufacturer contracts for patient assistance programs. Vertical integration of infusion services is compressing third-party pharmacy margins.
- Homecare Settings:Subcutaneous and oral therapy administration outside institutional walls requires nursing coordination, pump training, and remote monitoring infrastructure. Japanese home healthcare agencies and United States Medicare-certified home health providers compete on nurse specialization in prostacyclin management. Telemedicine platforms are expanding rural reach.
- Hospitals:Acute decompensation and diagnostic right heart catheterization anchor institutional revenue.
- Ambulatory Surgical Centers:Limited role for diagnostic procedures and port placement.
Specialty clinics capture the highest therapy complexity; homecare settings are expanding fastest.
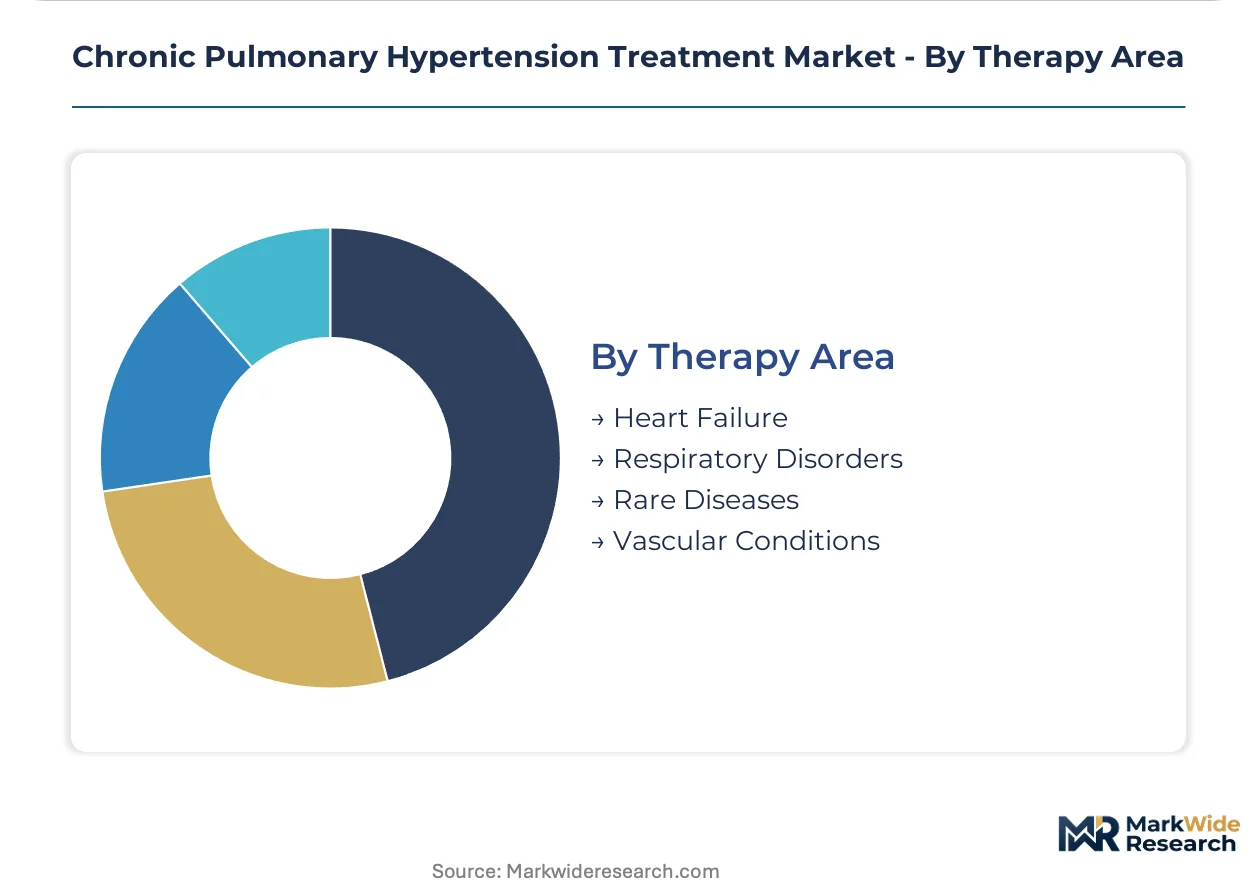
Therapy Area:
Indication scope determines regulatory pathway, trial design, and payer evidence requirements across cardiopulmonary domains.
- Rare Diseases:WHO Group 1 pulmonary arterial hypertension qualifies for FDA orphan drug incentives and EMA priority medicines designation. United States, Germany, and Japan maintain distinct rare disease frameworks that accelerate approval timelines and extend exclusivity. Pediatric investigation plans generate additional regulatory exclusivity through EMA requirements.
- Heart Failure:Right ventricular failure complicating pulmonary hypertension drives hospitalization burden and mortality endpoints in clinical trials. German IQWiG and French HAS apply distinct cost-effectiveness thresholds for cardiovascular mortality claims, fragmenting European pricing. Combination therapy protocols increasingly target right heart preservation.
- Respiratory Disorders:Interstitial lung disease-associated pulmonary hypertension expands addressable population.
- Vascular Conditions:Chronic thromboembolic disease and connective tissue-related vasculopathy represent mechanistically distinct subgroups.
Rare diseases anchor regulatory strategy; heart failure applications are broadening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit lower price elasticity due to established rare disease reimbursement frameworks, while United States purchasers face higher cost-sharing exposure that intensifies contracting pressure on manufacturers.
United States
Specialty clinic consolidation in Pennsylvania and California concentrates prostacyclin infusion demand within vertically integrated health systems. FDA orphan drug tax credits accelerate novel vasodilator development timelines for sponsors targeting small patient populations. Philadelphia-based United Therapeutics maintains captive pharmacy networks that compress third-party home infusion margins.
Germany
IQWiG benefit assessments apply stringent cost-effectiveness thresholds that fragment pricing power for single-source therapies across European markets. EMA priority medicines eligibility accelerates rolling review protocols for novel soluble guanylate cyclase stimulators. Bavarian pulmonary hypertension centers anchor diagnostic catheterization volumes and clinical trial enrollment across the DACH region.
Japan
Sakigake designation and priority review vouchers incentivize earlier launch timelines for pulmonary hypertension therapies than historical patterns. PMDA consultations align pediatric investigation plans with EMA requirements to streamline multinational regulatory submissions. Tokyo and Osaka foundation-affiliated clinics negotiate direct manufacturer contracts for patient assistance programs.
United Kingdom
NICE technology appraisals apply distinct evidence thresholds for cardiovascular mortality claims versus German or French counterparts. NHS England specialized commissioning concentrates prostacyclin initiation within designated pulmonary hypertension centers in London and Manchester. Brexit-related regulatory divergence complicates parallel EMA-FDA submission strategies for UK-based sponsors.
India
CDSCO accelerated approval pathways for rare diseases remain underdeveloped relative to FDA or EMA frameworks, delaying novel therapy access. Domestic active pharmaceutical ingredient synthesis for epoprostenol concentrates in Hyderabad and Ahmedabad, exposing manufacturers to supply disruption risk. Maharashtra specialty hospitals import reference-priced therapies through named patient programs.
Chronic Pulmonary Hypertension Treatment Market Competitive Environment
Capability concentration sits with integrated biopharmaceutical firms controlling prostacyclin synthesis and infusion logistics; scale advantage sits with diversified cardiovascular portfolios spanning multiple reimbursement markets. The market structure reflects a tiered competitive field where orphan drug exclusivity periods create temporary monopolies in specific vasodilator classes. Three archetypes dominate: vertically integrated specialty pharmacy operators, diversified cardiovascular portfolio holders, and rare disease-focused biotechnology firms. Competitive moves center on backward integration into API manufacturing and hospital system partnerships that streamline infusion center placement.
Among vertically integrated operators, United Therapeutics exemplifies the captive distribution model through in-house production of treprostinil and controlled specialty pharmacy networks. Bayer occupies a position representing diversified cardiovascular portfolio leverage across European reimbursement markets. Johnson & Johnson sits within the hospital partnership archetype, anchoring prostacyclin infusion logistics through institutional contracting relationships. These three firms represent distinct strategic postures without implying specific market share positions or operational details beyond their visible industry positioning.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| United Therapeutics |
| Bayer |
| Johnson & Johnson |
| Gilead Sciences |
| AstraZeneca plc |
| Boehringer Ingelheim International GmbH |
| Novartis International AG |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Single-source API dependency for epoprostenol and treprostinil concentrates manufacturing exposure in Indian and Chinese chemical parks, compressing margin buffers across both premium infusion therapies and oral formulations while forcing manufacturers to absorb logistics qualification costs or pass them through tiered service contracts.
Pricing Analysis
After-sales service intensity for prostacyclin infusion therapies drives lifetime value capture through pump maintenance contracts and 24-hour nursing hotlines. Three-tier pricing structure across premium parenteral analogs, standard oral receptor agonists, and economy-tier PDE-5 inhibitors reflects delivery complexity and cold chain requirements. Cost compression in home infusion services is intensifying because specialty clinics are consolidating patient support programs in-house. Hospital purchasing committees exhibit highest price sensitivity due to formulary budget constraints, while rare disease foundations in Pennsylvania and California demonstrate lowest elasticity through dedicated pharmacy benefit carve-outs.
Supply Chain Analysis
Upstream feedstock synthesis for prostacyclin analogs draws from specialized chemical intermediates produced in Hyderabad, Ahmedabad, and select coastal Chinese manufacturing zones. Active pharmaceutical ingredient production rests on epoprostenol sodium, treprostinil diolamine, and iloprost formulations as critical inputs. Single-source vulnerability concentrates in sterile manufacturing qualification for intravenous bag compounding. Distribution runs through United States specialty pharmacy networks, German hospital pharmacy compounding facilities, and Japanese home healthcare agencies with cold chain certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized synthesis capabilities for prostacyclin analogs and infusion pump logistics expertise represent scarce assets that constrain competitive entry, with only a handful of manufacturers possessing both API production and patient support infrastructure.
For Market Incumbents: Harden supply chain resilience through backward integration into API manufacturing or captive supplier agreements with Indian chemical parks, while consolidating patient support services to offset compression in third-party home infusion margins. Orphan drug exclusivity windows require defensive patent strategy investments as biosimilar entry timelines approach for expired prostacyclin patents. For New Entrants and Emerging Players: Pediatric investigation plans for pulmonary arterial hypertension represent the most penetrable entry point, generating EMA regulatory exclusivity extensions and first-mover positioning in underdeveloped age-segment indications. Telemedicine-enabled remote hemodynamic monitoring platforms offer a go-to-market angle for functional class III patients outside traditional infusion center footprints, bypassing incumbent captive pharmacy networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated operators with captive distribution and API synthesis capabilities. Long-term viability over the next decade hinges on rare disease portfolio depth and reimbursement contracting leverage across German, Japanese, and United States frameworks. Biosimilar entry timelines for prostacyclin analogs serve as the critical signal to watch for inflection in payer contracting power.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Submission | EMA requirements generate regulatory exclusivity extensions in underdeveloped age-segment indications. |
| Specialty Clinic Partnership | Vertical integration of infusion services compresses third-party pharmacy margins and secures patient access. |
| API Manufacturing Scale-Up | Backward integration into epoprostenol synthesis mitigates single-source dependency on Indian suppliers. |
| Telemedicine Platform Development | Remote hemodynamic monitoring expands rural reach for functional class III oral therapy management. |
| Orphan Drug Designation Pursuit | FDA tax credits and extended exclusivity accelerate novel vasodilator development timelines. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA orphan drug filings, EMA priority medicines submissions, ClinicalTrials.gov enrollment data, and German IQWiG benefit assessment records. Bottom-up prescription volume modeling and top-down market sizing triangulated across patient registry data and reimbursement claims databases.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions covering administration route, product class, end-user site-of-care, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, treatment escalation patterns, and pricing trajectory assumptions. Forecast inputs incorporated WHO diagnostic guideline adoption curves and biosimilar entry probability assessments.
Practitioners should monitor EMA pediatric investigation plan commitments, FDA orphan drug exclusivity expirations, and German IQWiG benefit assessment outcomes for early signals of competitive inflection. Forecasts reflect documented assumptions regarding referral network expansion and combination therapy protocol adoption. Cross-checking against national pulmonary hypertension registry enrollment trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Endothelial Dysfunction Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
Angina Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Cardiometabolic Disease Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Heart Health Products Market