
 Middle East and Africa Rett Syndrome Market | 2026-2036
Middle East and Africa Rett Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Rett Syndrome Market Foresight
South Africa's emerging gene therapy manufacturing infrastructure is reconfiguring regional supply dynamics for rare disease therapeutics. Novartis AG leverages its established oncology and neurology networks to sustain distribution reach across sub-Saharan markets. Hikma Pharmaceuticals PLC anchors its competitive position through localized production of supportive care medications tailored to Middle Eastern formularies. Sun Pharmaceutical Industries Ltd. competes on cost-optimized symptomatic treatment portfolios accessible to public hospital procurement systems.
Rett Syndrome constitutes a rare X-linked dominant neurodevelopmental disorder caused by MECP2 gene mutations, characterized by arrested neurological development after six to eighteen months of apparently normal early growth, with diagnostic confirmation requiring genetic testing for pathogenic variants. The condition demands lifelong multidisciplinary management spanning seizure control, respiratory support, orthopedic intervention, and communication therapy. Gene therapy segments attract concentrated R&D investment due to curative potential, while symptomatic treatment categories currently dominate revenue flows through established hospital pharmacy channels. Next-generation sequencing technologies are displacing older cytogenetic methods in diagnostic testing applications, shortening time-to-diagnosis and expanding identifiable patient pools across Saudi Arabia and the UAE.
South Africa's Health Products Regulatory Authority and Saudi Arabia's SFDA govern orphan drug approvals and clinical trial frameworks across the region's two largest addressable markets, with both agencies accelerating review timelines for rare neurological indications. The UAE's MOHAP implements genetic screening mandates that directly expand diagnostic tool demand through newborn and prenatal testing protocols. Stakeholders must monitor how harmonization efforts between national regulators affect cross-border trial participation and centralized manufacturing qualification requirements.
Market Dynamics
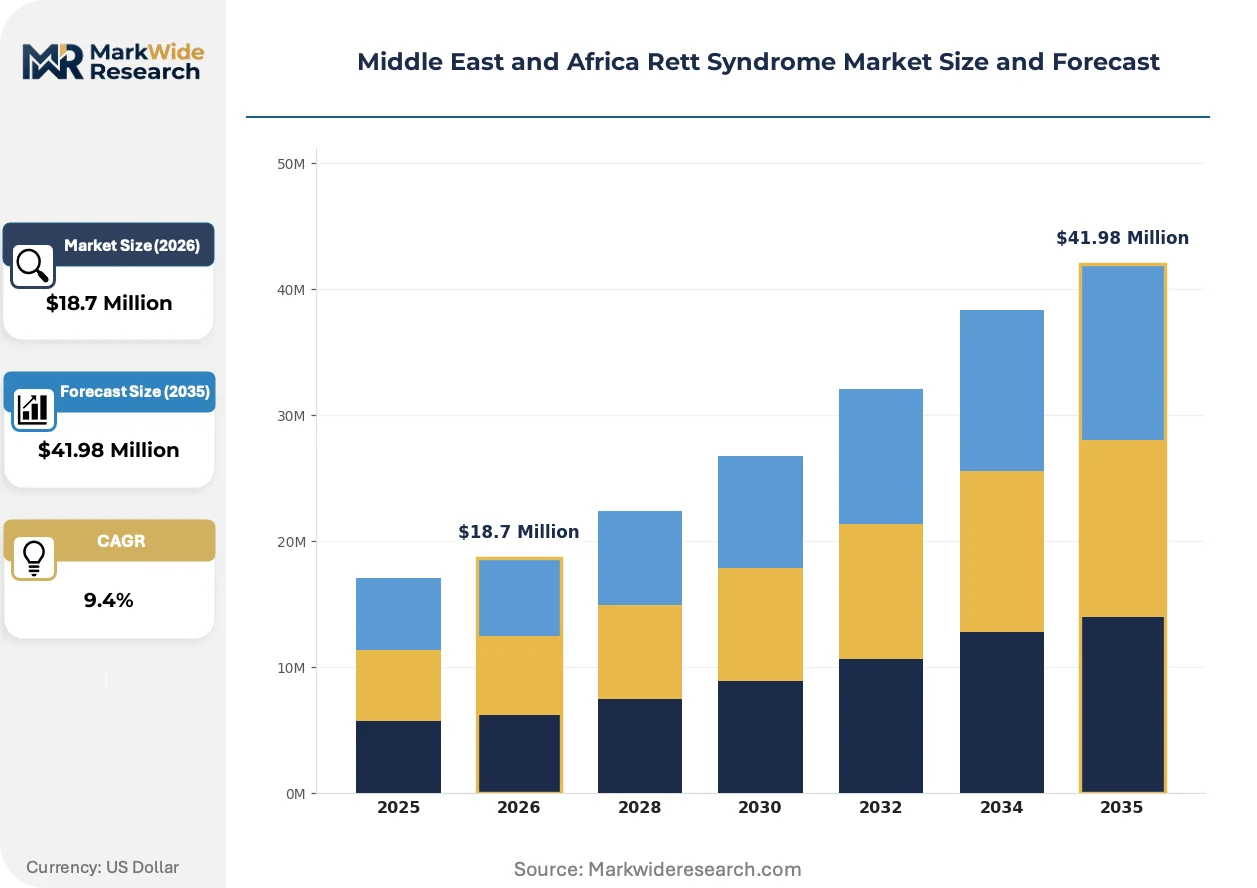
Gene therapy manufacturing infrastructure in South Africa is concentrating regional supply capabilities for rare disease therapeutics, while Gulf Cooperation Council genetic screening mandates are systematically expanding addressable patient pools through newborn and prenatal testing protocols.
Growth Catalysts
- SFDA Accelerated Review Pathways:Saudi Arabia's streamlined orphan drug approval timelines compress time-to-market for neurological therapeutics. Pediatric neurology departments across Riyadh and Jeddah are expanding specialized Rett Syndrome care capacity.
- Next-Generation Sequencing Displacement:Diagnostic laboratories in Dubai and Abu Dhabi are replacing cytogenetic methods with NGS platforms, shortening diagnostic timelines and expanding identifiable MECP2 mutation cases.
- MOHAP Genetic Screening Mandates:The UAE's Ministry of Health and Prevention mandates newborn screening protocols that directly expand demand for diagnostic testing infrastructure across Emirates.
Market Restraints
- Refrigerated Cold Chain Gaps:Last-mile distribution infrastructure across sub-Saharan Africa outside South Africa limits temperature-sensitive biologic access to tertiary hospitals.
- Specialized Neurology Workforce Scarcity:South Africa trains fewer than fifteen pediatric neurologists annually, constraining diagnosis and management capacity expansion.
- High-Cost Gene Therapy Reimbursement Friction:Gulf state insurance frameworks lack established pathways for single-administration curative therapies priced above traditional chronic management models.
Strategic Opportunities
- Kenya and Nigeria Diagnostic Penetration:East and West African markets currently register sub-five percent diagnostic capture rates for rare neurodevelopmental disorders, representing substantial white space for NGS laboratory partnerships.
- Telemedicine-Enabled Multidisciplinary Care:Remote consultation platforms connect Gulf-based specialists with North African patient populations, extending reach without physical infrastructure deployment.
- South African Manufacturing Qualification:Localized gene therapy production under SAHPRA oversight could serve as a regional supply hub for sub-Saharan markets, reducing import dependency.
Industry Challenges
- Cross-Border Regulatory Harmonization Gaps:Divergent clinical trial approval timelines between SAHPRA and Gulf regulators complicate multi-site study design and patient recruitment coordination.
- Genetic Counseling Workforce Shortfalls:Fewer than two hundred certified genetic counselors serve the entire Middle East and Africa region, creating bottlenecks in family communication and informed consent processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Rett Syndrome Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Symptomatic Treatment, Diagnostic Tools, Supportive Care Technology: Next-Generation Sequencing, CRISPR, Pharmacogenomics, Biomarkers End User: Hospitals, Homecare, Rehabilitation Centers, Research Institutions Application: Clinical Trials, Diagnostic Testing, Patient Management, Drug Development |
| Companies Covered | Teva Pharmaceutical USA, Cipla Inc., Zydus Cadila, UCB SA, Novartis AG, Hikma Pharmaceuticals PLC, Dr. Reddy’s Laboratories Ltd., Sun Pharmaceutical Industries Ltd., LUPIN, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Rett Syndrome Market Shifts & Advancements
Artificial intelligence applications are compressing diagnostic timelines for rare neurological conditions, while regulatory agencies across the Gulf and South Africa are constructing specialized frameworks for gene therapy evaluation and reimbursement.
Next-generation sequencing platforms are digitizing the diagnostic pathway for MECP2 mutation detection. Tertiary hospitals in Saudi Arabia and the UAE are adopting these systems at accelerated procurement cycles. This technology is digitizing patient identification workflows, enabling earlier intervention windows and expanding treatable cohorts beyond historical cytogenetic capture rates.
SFDA and SAHPRA are implementing parallel track review mechanisms for rare neurological indications. These frameworks compress approval timelines while maintaining safety surveillance standards. Gene therapy sponsors targeting the region are responding by prioritizing Saudi and South African sites for pivotal trials, leveraging regulatory familiarity to accelerate market entry.
Hospital procurement departments across Gulf Cooperation Council states are consolidating vendor relationships for rare disease therapeutics. Single-source agreements with specialized distributors are displacing fragmented pharmacy purchasing. This concentration is most visible in Dubai and Abu Dhabi, where health system consolidation is driving preferred provider arrangements for orphan drug supply.
Middle East and Africa Rett Syndrome Market Segmentation
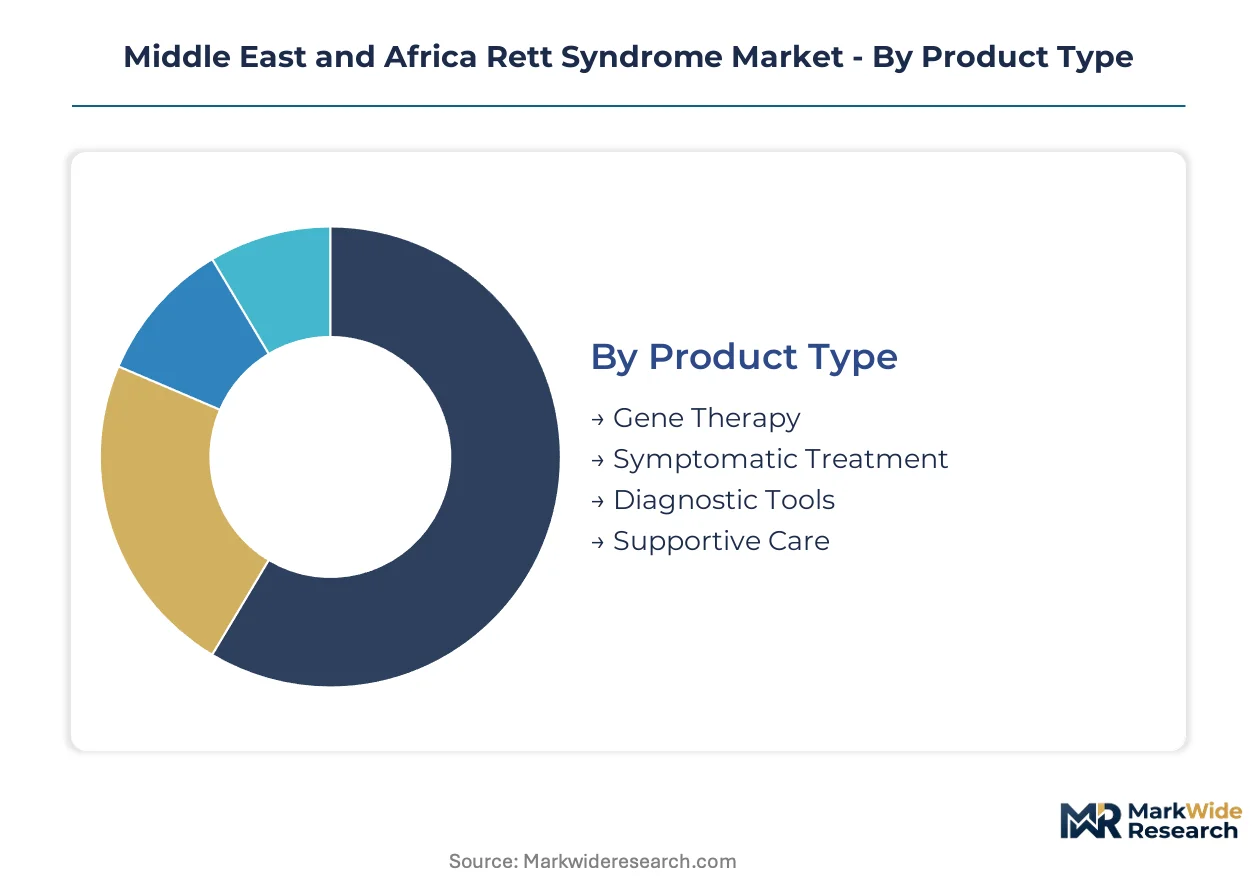
Segmentation of the Middle East and Africa Rett Syndrome market reveals distinct service intensity profiles across therapeutic modalities. Each category demands specialized supply chain configurations and stakeholder engagement models tailored to rare disease management requirements.
Product Type:
After-sales service intensity varies sharply across product categories, with gene therapy requiring specialized administration support and long-term monitoring infrastructure.
- Gene Therapy:Single-administration curative interventions targeting MECP2 mutations demand cryogenic cold chain logistics and specialized clinical administration protocols. Saudi Arabia's SFDA accelerated review pathways are concentrating initial commercial deployments in Riyadh and Jeddah tertiary centers.
- Symptomatic Treatment:Chronic pharmacological management spanning seizure control, respiratory support, and motor function modulation generates recurring revenue through established hospital pharmacy procurement channels. South Africa's public hospital systems anchor volume demand through centralized tender processes.
- Diagnostic Tools:Genetic testing platforms and MECP2 mutation screening assays.
- Supportive Care:Orthopedic devices, feeding support systems, and communication aids for lifelong disease management.
By volume, Symptomatic Treatment leads. By growth pace, Gene Therapy is ahead.
Technology:
Cost tier stratification separates capital-intensive sequencing infrastructure from accessible biomarker applications.
- Next-Generation Sequencing:High-throughput genetic analysis platforms are displacing cytogenetic methods in Dubai and Abu Dhabi diagnostic laboratories. UAE MOHAP newborn screening mandates are accelerating platform procurement cycles and shortening MECP2 detection timelines.
- CRISPR:Gene editing technologies for preclinical therapeutic development and research applications.
- Pharmacogenomics:Patient-specific drug response profiling to optimize symptomatic treatment selection.
- Biomarkers:Accessible diagnostic indicators supporting disease monitoring and treatment response assessment.
By installed base, Next-Generation Sequencing leads. By expansion trajectory, CRISPR applications are climbing the fastest.
End User:
Customer type segmentation maps to reimbursement complexity and care delivery infrastructure maturity.
- Hospitals:Tertiary pediatric neurology departments across South Africa and Gulf Cooperation Council states concentrate specialized Rett Syndrome diagnosis and acute intervention capacity.
- Homecare:Family-based management protocols for chronic respiratory support and daily living assistance.
- Rehabilitation Centers:Dedicated facilities for motor function therapy and communication skills development.
- Research Institutions:Academic medical centers conducting clinical trials and natural history studies.
By patient volume concentration, Hospitals lead. By service expansion, Homecare is gaining share fastest.
Application:
Volume and margin profiles diverge across the clinical-to-commercial spectrum.
- Clinical Trials:Pivotal and early-phase studies for gene therapy candidates are prioritizing Saudi and South African sites to leverage regulatory familiarity. Cross-border harmonization gaps between SAHPRA and Gulf agencies complicate multi-site coordination.
- Diagnostic Testing:MECP2 mutation confirmation and carrier screening services.
- Patient Management:Coordinated multidisciplinary care spanning neurology, orthopedics, and respiratory medicine.
- Drug Development:Preclinical and translational research for novel therapeutic mechanisms.
By revenue contribution, Patient Management leads. By investment intensity, Clinical Trials show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA's accelerated orphan drug pathways anchor Saudi Arabia's emergence as the dominant regulatory hub for rare neurological therapeutics across the Middle East and Africa. Pediatric neurology capacity expansion in Riyadh and Jeddah concentrates specialized Rett Syndrome diagnosis and intervention infrastructure. Cross-border harmonization gaps between Gulf and sub-Saharan regulators complicate multi-site clinical trial coordination.
Saudi Arabia
Pediatric neurology departments in Riyadh and Jeddah are expanding dedicated Rett Syndrome care protocols to address rising MECP2 mutation identification. SFDA's streamlined review timelines for rare neurological indications compress commercialization pathways for gene therapy sponsors. King Faisal Specialist Hospital anchors the kingdom's diagnostic and therapeutic infrastructure.
United Arab Emirates
MOHAP-mandated newborn genetic screening programs systematically expand addressable patient pools through prenatal and neonatal testing protocols. Dubai and Abu Dhabi diagnostic laboratories are accelerating next-generation sequencing platform procurement to displace older cytogenetic methods. Tertiary hospital consolidation across Emirates is driving preferred provider arrangements for orphan drug supply.
South Africa
SAHPRA's orphan drug registration streamlining is reconfiguring regional supply dynamics for rare disease therapeutics. The country's emerging gene therapy manufacturing infrastructure positions it as a potential sub-Saharan supply hub. Pediatric neurology workforce scarcity—fewer than fifteen specialists trained annually—constrains diagnosis capacity expansion in Johannesburg and Cape Town academic centers.
Nigeria
Diagnostic capture rates for rare neurodevelopmental disorders remain below five percent, representing substantial white space for next-generation sequencing laboratory partnerships. The country's national pharmaceutical regulator lacks established orphan drug frameworks, creating reimbursement friction for imported therapeutics. Lagos and Abuja tertiary hospitals concentrate limited pediatric neurology expertise.
Israel
Advanced genetic research infrastructure supports preclinical gene therapy development and natural history studies for MECP2 mutations. Sheba Medical Center and Hadassah Medical Center anchor clinical trial participation for multinational sponsors targeting the region. Regulatory alignment with European Medicines Agency standards facilitates technology transfer partnerships.
Middle East and Africa Rett Syndrome Market Competitive Landscape
Multinational pharmaceutical conglomerates and regional generic manufacturers split the market across curative and symptomatic treatment vectors. The competitive structure tiers into gene therapy developers targeting accelerated regulatory pathways and established players monetizing chronic management portfolios. Three archetypes dominate: R&D-intensive innovators pursuing single-administration curatives, cost-optimized generic houses serving public procurement systems, and specialized rare disease distributors managing cold chain logistics. Capacity expansion in South African manufacturing and strategic partnerships with Gulf health system consolidators represent the dominant competitive moves.
Within the multinational innovator tier, Novartis AG and UCB SA exemplify archetypes leveraging established neurology networks to sustain distribution reach across sub-Saharan and Gulf markets. Hikma Pharmaceuticals PLC occupies a position among Middle East-headquartered manufacturers anchoring competitive standing through localized production aligned to regional formularies. Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. represent Indian-origin cost-optimized houses competing on accessible symptomatic treatment portfolios for public hospital procurement systems.
| Leading Market Players |
|---|
| Teva Pharmaceutical USA |
| Cipla Inc. |
| Zydus Cadila |
| UCB SA |
| Novartis AG |
| Hikma Pharmaceuticals PLC |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| LUPIN |
| Others |
Supply & Pricing Matrix
Jebel Ali Port cold chain logistics corridors connect Gulf manufacturing hubs to sub-Saharan distribution nodes, with freight cost differentials between temperature-controlled and ambient lanes compressing margin structures for gene therapy sponsors while amplifying price spreads between tertiary hospital and peripheral clinic access tiers.
Pricing Analysis
Gulf-to-sub-Saharan price spreads exceed threefold for equivalent symptomatic treatment portfolios, with SAHPRA-registered generics in South Africa anchoring economy-tier procurement and SFDA-accelerated orphan biologics commanding premium positioning in Riyadh and Dubai. Price differentiation rests on regulatory certification tier and cold chain service bundling rather than molecule differentiation alone. Cost compression in public hospital tenders is intensifying as centralized procurement authorities consolidate vendor panels. Pediatric neurology departments exhibit lowest price sensitivity due to restricted therapeutic alternatives, while primary care distributors face acute margin pressure from formulary exclusion risks.
Supply Chain Analysis
Extended payment terms from Gulf health system consolidators are restructuring supplier financing requirements, with 90-120 day receivables cycles now standard for orphan drug distributors serving Dubai and Abu Dhabi hospital networks. Manufacturing concentration centers on Switzerland, Singapore, and emerging South African gene therapy facilities. Cryogenic logistics equipment, MECP2 vector production substrates, and specialized clinical administration kits constitute critical input dependencies. Single-source vulnerability in vector manufacturing creates systemic exposure for curative therapy launches. Distribution runs through specialized rare disease distributors with validated cold chain credentials rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection is materializing through diagnostic-to-therapeutic interoperability standards, with next-generation sequencing data formats enabling seamless patient identification-to-treatment enrollment workflows that reshape competitive moats around integrated care ecosystems.
For Market Incumbents: Pre-empt emerging gene therapy entrants by securing exclusive distribution agreements with King Faisal Specialist Hospital and Sheba Medical Center anchor sites. Accelerate backward integration into South African vector manufacturing under SAHPRA oversight to neutralize supply security threats from single-source biologics dependencies. Lock in preferred provider status with Gulf health system consolidators before tender consolidation completes.
For New Entrants and Emerging Players: Nigeria's sub-five percent diagnostic capture rate for MECP2 mutations represents the most penetrable white space for NGS laboratory partnerships targeting Lagos and Abuja tertiary hospitals. Telemedicine-enabled multidisciplinary care platforms offer lowest-friction go-to-market positioning for North African patient populations underserved by physical pediatric neurology infrastructure. Prioritize diagnostic tool commercialization ahead of therapeutic development to secure patient identification channel control.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors gene therapy platform companies with validated MECP2 delivery mechanisms and established regulatory relationships with SFDA or SAHPRA. Long-term viability hinges on manufacturing asset control rather than licensing-dependent revenue models. Watch for reimbursement pathway establishment in Gulf state insurance frameworks as the critical inflection signal for curative therapy commercialization feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Accelerated Approval Pathway | Compresses commercialization timelines for gene therapy sponsors targeting Saudi pediatric neurology centers. |
| South African Manufacturing Qualification | Positions regional supply hub status for sub-Saharan markets under SAHPRA gene therapy oversight. |
| NGS Laboratory Partnership Network | Expands MECP2 mutation identification capacity across underpenetrated East and West African markets. |
| Gulf Health System Consolidator Agreements | Secures preferred provider status through single-source orphan drug procurement arrangements in Dubai and Abu Dhabi. |
| Telemedicine Multidisciplinary Platform | Connects Gulf-based specialists to North African patients without physical infrastructure deployment costs. |
Research Methodology
Cross-validation between regulatory filing analysis and clinical trial database monitoring anchors the qualitative findings in this study. Primary interviews with pediatric neurologists, SAHPRA regulatory affairs leads, Gulf hospital procurement managers, and genetic counseling program directors combined with secondary validation against SFDA submission records, ClinicalTrials.gov entries, and MOHAP newborn screening protocol documents. Bottom-up patient identification modeling and top-down health system expenditure analysis provide triangulation across estimation approaches.
Calibration against historical gene therapy launch trajectories in adjacent rare neurological indications informs the analytical framework across the projection horizon. Segmentation dimensions include therapeutic modality, technology platform, end-user facility type, and regional regulatory cluster. CAGRs derive from patient pool expansion rates, diagnostic penetration curves, and reimbursement pathway establishment timelines. Forecast inputs incorporate MECP2 mutation incidence assumptions and next-generation sequencing platform procurement cycles in Gulf diagnostic laboratories.
Practitioners should monitor regulatory harmonization progress between SAHPRA and Gulf agencies, gene therapy reimbursement decisions in Saudi and Emirati insurance frameworks, and South African manufacturing qualification milestones for early signals of trajectory deviation. Forecasts reflect assumptions regarding diagnostic technology adoption curves and orphan drug approval pathway efficiency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market