
 Ischemia Market | 2026-2036
Ischemia Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemia Market Foresight
The capital-intensity divergence between large-cap pharmaceutical developers and mid-cap device specialists is redrawing competitive boundaries in ischemia care. Pfizer Inc leverages its global manufacturing scale to sustain bulk supply of chronic antithrombotic therapies across hospital networks. AstraZeneca PLC anchors its position through cardiovascular outcome trial investments that differentiate its branded portfolio from commoditized alternatives. Novartis International AG competes on specialty therapy depth, particularly in refractory angina segments where clinical data requirements create narrower competitive fields.
Ischemia denotes a pathological state of restricted blood flow to tissues, most commonly cardiac muscle, resulting in oxygen deprivation measurable through biomarkers such as troponin elevation and ST-segment deviation on electrocardiography; its primary purpose in clinical practice is to enable timely revascularization decisions that prevent irreversible myocardial necrosis. The diagnostics segment leads in margin capture due to high specificity requirements and recurring consumable revenue from biomarker assays. Devices occupy the fastest-expanding structural position as transcatheter approaches displace open surgical revascularization in eligible patient populations. Hospital end users concentrate purchasing power through centralized procurement of both capital equipment and pharmaceutical formularies.
FDA breakthrough device designation and EMA adaptive pathway frameworks compress development timelines for novel ischemia diagnostics, while CMS national coverage determinations directly shape commercial access for Medicare-eligible patients in the United States. The EU Medical Device Regulation imposes strengthened clinical evidence requirements that filter market entry for coronary intervention platforms. Stakeholders must monitor evolving payer evidence thresholds that increasingly condition reimbursement on randomized outcome data rather than surrogate endpoints.
Market Dynamics
Transcatheter revascularization platforms are compressing the addressable market for coronary artery bypass grafting while expanding procedure volumes among patients previously deemed inoperable, forcing incumbent surgical device manufacturers to recalibrate portfolio priorities toward hybrid operating room infrastructure.
Growth Catalysts
- FDA Breakthrough Device Designation:Compressed approval timelines for fractional flow reserve wire technologies accelerate commercialization of physiologic lesion assessment tools in US catheterization laboratories.
- Japan's super-aged demographic profile:Patients over 75 now constitute the majority of percutaneous coronary intervention recipients, sustaining demand for minimally invasive alternatives to sternotomy.
- Bioresorbable scaffold platforms:Polymer-based vascular scaffolds that dissolve within 24 months eliminate long-term metallic foreign body complications, expanding eligible patient pools.
Market Restraints
- Platinum-iridium alloy supply concentration:Wire core materials for interventional catheters depend on South African and Russian mining operations, exposing manufacturers to input volatility and sanctions-driven disruption.
- EU MDR clinical evidence requirements:Strengthened post-market surveillance obligations for coronary stents extend recertification timelines and inflate regulatory compliance expenditures.
- Computed tomography angiography substitution:Non-invasive anatomic assessment reduces diagnostic catheterization referrals in stable chest pain pathways, compressing upstream procedure generation.
Strategic Opportunities
- Remote ischemia monitoring via wearable electrocardiography:Patch-based ST-segment surveillance enables outpatient detection of silent ischemia episodes, creating ambulatory service revenue streams.
- Germany's Diagnosis-Related Group refinement:Reimbursement incentives for same-day discharge after transcatheter procedures support freestanding cardiac catheterization facility expansion.
- Artificial intelligence fusion with intravascular imaging:Machine learning algorithms applied to optical coherence tomography pullback data automate plaque characterization and stent sizing decisions.
Industry Challenges
- Interventional cardiology fellowship pipeline constraints:US training program capacity limits annual specialist output, creating procedural bottlenecks as device innovation outpaces operator availability.
- Legacy electronic health record interoperability:Hemodynamic data acquisition systems from multiple vendors resist seamless integration with hospital information systems, fragmenting patient records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemia Market |
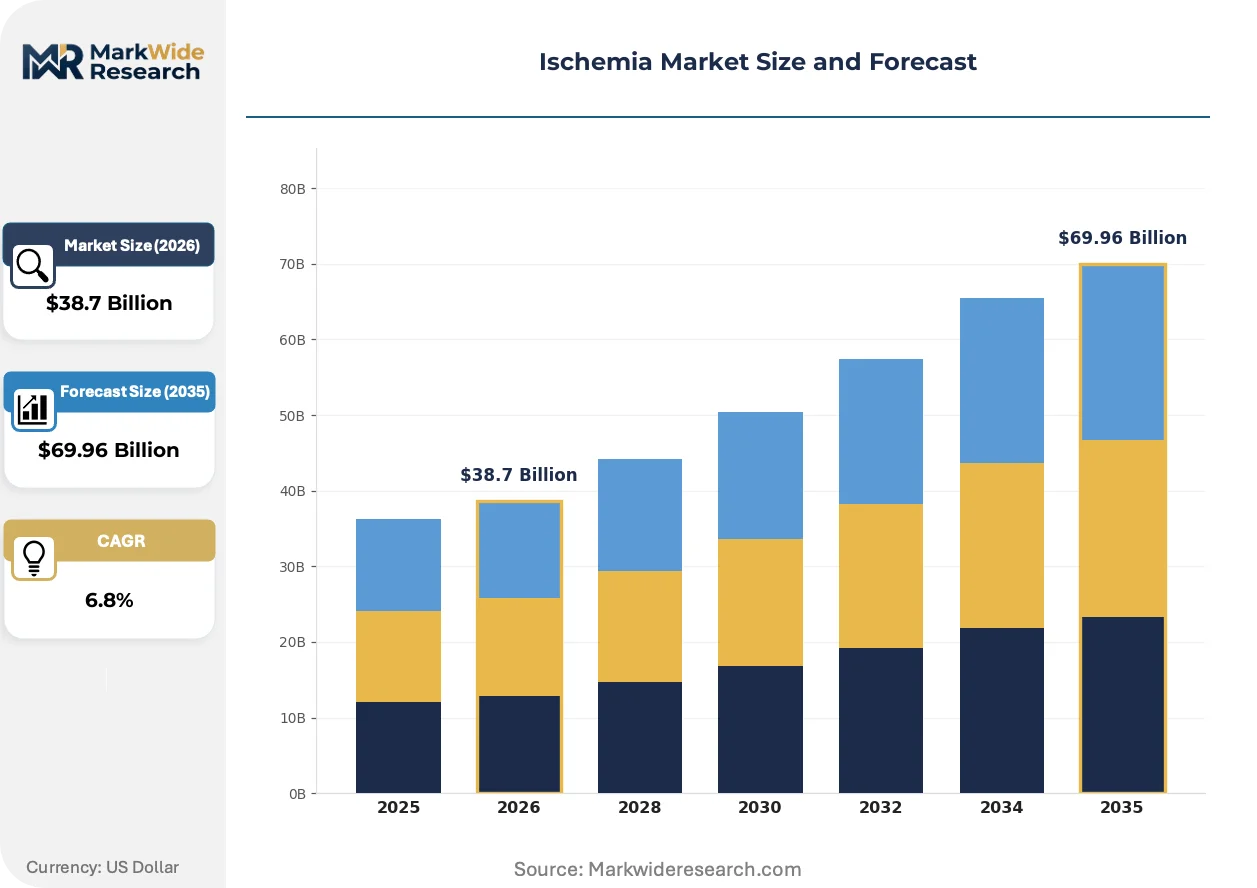
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Therapies, Diagnostics Application: Cardiology, Neurology, Emergency Care, Rehabilitation Delivery Mode: Oral, Intravenous, Inhalation, Topical End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Pfizer Inc, Novartis International AG, AstraZeneca PLC, Merck & Co., Inc, Bristol Myers Squibb Company, Johnson & Johnson, Sanofi SA, Bayer AG, AbbVie Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemia Market Shifts & Advancements
Digital physiology and intravascular imaging convergence is redefining lesion assessment protocols, shifting decision-making from anatomic stenosis thresholds to functional ischemia quantification and plaque composition analysis.
Intravascular ultrasound catheters are miniaturizing to sub-2.0 French profiles, enabling distal coronary segment interrogation previously inaccessible to conventional imaging platforms. Academic medical centers in the United States and Japan are adopting these reduced-caliber devices for chronic total occlusion revascularization procedures. This miniaturization is collapsing the distinction between diagnostic and interventional catheterization, permitting same-session imaging and intervention without equipment exchange.
The EU Medical Device Regulation's equivalence pathway restrictions are compelling coronary intervention manufacturers to generate proprietary clinical data rather than leveraging predicate device literature. Small-cap device developers face disproportionate trial cost burdens relative to revenue base, accelerating strategic exits to large-cap acquirers with established clinical affairs infrastructure. German notified bodies are experiencing backlog-induced certification delays exceeding 18 months for novel stent platforms.
Hospital procurement committees are consolidating cardiovascular device purchasing through multi-year sole-source agreements, displacing the traditional vendor-rotation model that fragmented purchasing across competing sales forces. Integrated delivery networks in the United States are extracting price concessions through committed volume guarantees spanning drug-eluting stents, guidewires, and hemodynamic monitoring systems. This concentration is most pronounced in the Midwestern United States, where Catholic health system mergers have created regional purchasing monopolies.
Ischemia Market Segmentation
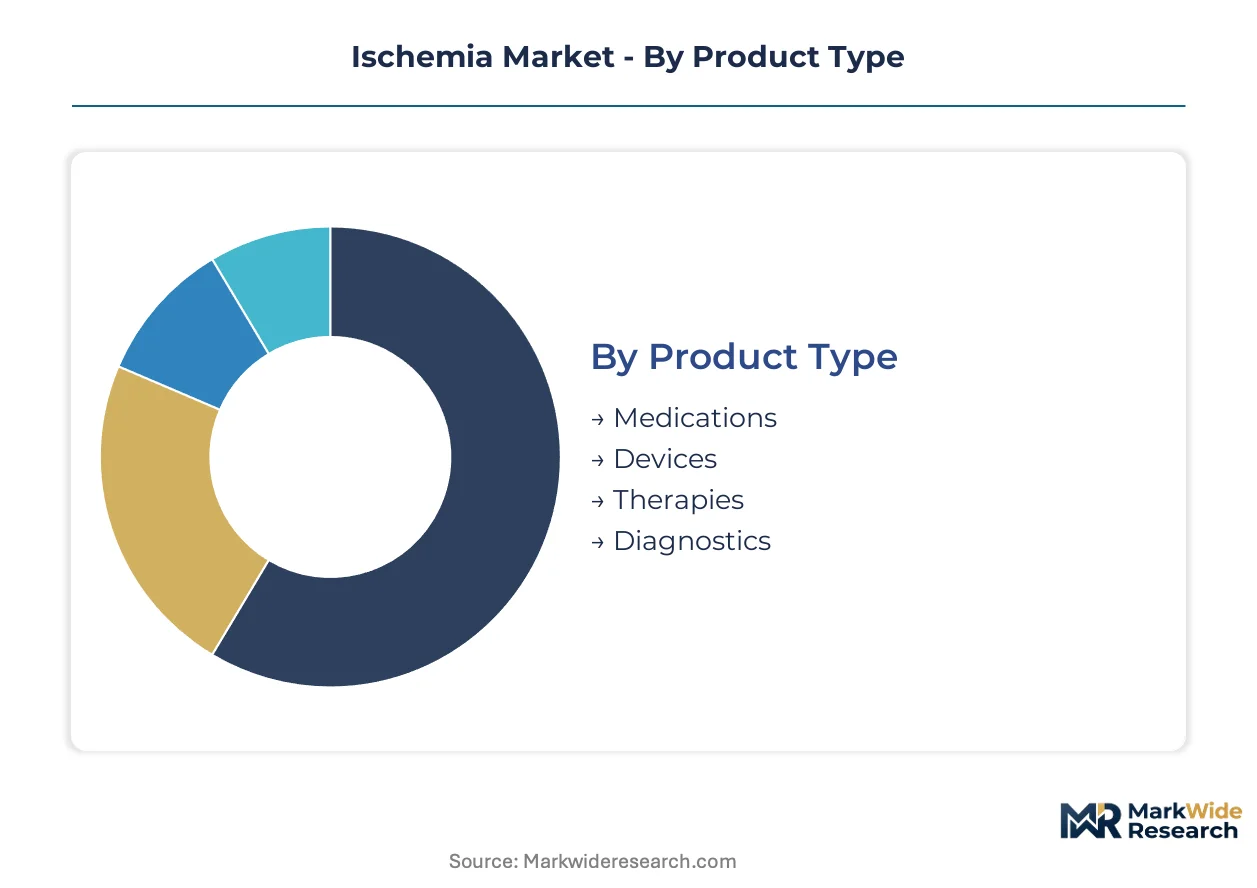
Ischemia care pathways fragment across acute intervention, chronic management, and preventive monitoring, each demanding distinct product specifications and procurement channels. Hospital administrators and procurement committees evaluate segments through divergent lenses: capital equipment lifecycle costs versus pharmaceutical formulary positioning versus diagnostic consumable throughput.
Product Type:
Hospital-based cardiology departments channel the majority of purchasing power through centralized procurement that bundles devices with recurring diagnostic consumables, while pharmaceutical therapies flow through separate pharmacy and therapeutics committees.
- Medications:Antithrombotic agents, antiplatelet compounds, and vasodilators form the chronic disease management backbone. Demand concentrates in the United States and Germany where reimbursement formularies sustain branded cardiovascular portfolios against generic erosion.
- Devices:Drug-eluting stents, fractional flow reserve wires, and intravascular imaging catheters command premium pricing through procedure-linked reimbursement. Japan's super-aged demographic sustains percutaneous coronary intervention volumes that absorb next-generation platform rollouts.
- Therapies:External counterpulsation and transmyocardial laser revascularization serve refractory angina populations failing conventional intervention. Academic medical centers in the United States generate the majority of clinical evidence for these niche modalities.
- Diagnostics:Biomarker assays, electrocardiography systems, and computed tomography angiography platforms enable upstream disease detection. Freestanding cardiac catheterization facilities in Germany are expanding same-day diagnostic throughput under refined Diagnosis-Related Group incentives.
Devices dominate installed base. Diagnostics is where expansion concentrates.
Application:
Cost tier stratification separates acute intervention reimbursement from chronic management coding, with emergency applications commanding premium facility fees that subsidize lower-margin rehabilitation segments.
- Cardiology:Coronary, peripheral, and microvascular ischemia subtypes drive the procedural volume base. Transcatheter revascularization platforms are compressing the addressable market for coronary artery bypass grafting while expanding eligible patient pools.
- Neurology:Cerebral ischemia and acute stroke protocols demand rapid triage infrastructure. United States comprehensive stroke centers are consolidating purchasing for neurointerventional devices through multi-year sole-source agreements.
- Emergency Care:Chest pain pathway optimization and troponin-based rule-out protocols reshape emergency department throughput. CMS national coverage determinations directly shape commercial access for Medicare-eligible patients.
- Rehabilitation:Cardiac rehabilitation programs and secondary prevention protocols extend care continuity post-intervention. Home-based monitoring adoption is climbing fastest as wearable electrocardiography patches enable ambulatory ischemia surveillance.
Emergency Care captures the highest per-episode reimbursement. Rehabilitation is gaining share fastest through value-based care incentives.
Delivery Mode:
Volume concentration in oral formulations contrasts with margin concentration in intravenous acute therapies, where hospital markup structures and procedural bundling protect pricing.
- Oral:Chronic antiplatelet and statin regimens sustain the largest patient-day volumes. Generic substitution pressures in the United States have compressed branded pricing, forcing portfolio differentiation through cardiovascular outcome trial investments.
- Intravenous:Acute anticoagulation and thrombolytic administration during catheterization procedures commands premium pricing. Japanese percutaneous coronary intervention guidelines emphasize intravenous adjunct therapy protocols that sustain procedural medication intensity.
- Inhalation:Limited current application in ischemia care, primarily experimental in neuroprotective protocols during cardiac surgery. Research institutions in the United States are exploring gaseous mediators for ischemia-reperfusion injury modulation.
- Topical:Transdermal nitrate delivery for angina prophylaxis occupies a niche compliance-oriented segment. Homecare settings in Germany favor topical options for elderly patients with polypharmacy challenges.
Oral formulations dominate patient-day exposure. Intravenous delivery is where margin protection concentrates.
End User:
Customer type determines procurement sophistication: integrated delivery networks extract volume-based concessions that elude independent clinic purchasers.
- Hospitals:Tertiary cardiac centers and community hospitals absorb the majority of capital equipment and acute procedural volume. Catholic health system mergers in the United States Midwest have created regional purchasing monopolies that reshape vendor competitive dynamics.
- Clinics:Outpatient cardiology practices and diagnostic imaging centers concentrate on stable patient evaluation. Germany's freestanding cardiac catheterization facility expansion is redirecting stable chest pain volume from hospital-based settings.
- Homecare:Remote patient monitoring and post-acute care management are emerging as service revenue opportunities. Wearable electrocardiography patch platforms enable silent ischemia detection outside traditional care settings.
- Research Institutions:Academic medical centers generate clinical evidence for novel devices and therapeutic protocols. FDA breakthrough device designation pathways accelerate commercialization for technologies validated through academic investigator-initiated trials.
Hospitals dominate purchasing volume. Homecare is where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German levels by roughly 40% for equivalent drug-eluting stent platforms, while Japanese procurement through NHI reimbursement channels compresses margins for multinational suppliers. This asymmetry shapes regional investment priorities and product launch sequencing across cardiovascular device portfolios.
United States
Medicare's national coverage determinations for fractional flow reserve wires sustain procedural volume growth in catheterization laboratories. FDA breakthrough device designation pathways compress commercialization timelines for physiologic assessment technologies. The Cleveland Clinic and Mayo Clinic anchor clinical evidence generation for next-generation intravascular imaging platforms.
Germany
Freestanding cardiac catheterization facilities expand same-day discharge capacity under refined Diagnosis-Related Group reimbursement incentives. EU Medical Device Regulation clinical evidence requirements extend recertification timelines for coronary stent manufacturers. The Rhine-Ruhr metropolitan cluster concentrates interventional cardiology training capacity and hybrid operating room infrastructure deployment.
Japan
Super-aged demographic profiles push patients over 75 to constitute the majority of percutaneous coronary intervention recipients. PMDA accelerated approval pathways for breakthrough cardiovascular therapies align with FDA timelines. Tokyo and Osaka academic medical centers generate the majority of Asian clinical evidence for bioresorbable scaffold platforms.
United Kingdom
NICE technology appraisals condition NHS England reimbursement for novel ischemia diagnostics on cost-effectiveness thresholds. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR implementation timelines. The Oxford-Cambridge-London golden triangle concentrates cardiovascular outcome trial infrastructure and digital health validation programs.
China
Volume-based procurement reforms for coronary stents have compressed prices by over 90% in national tender rounds. NMPA priority review pathways accelerate domestic device approvals against multinational incumbents. The Yangtze River Delta cluster—Shanghai, Suzhou, Hangzhou—hosts the majority of local cardiovascular device manufacturing capacity and clinical trial sites.
Ischemia Market Competitive Landscape
Concentration sits with large-cap pharmaceutical developers who sustain chronic antithrombotic supply across hospital networks. The vendor base spans three tiers: global pharmaceutical conglomerates with cardiovascular outcome trial infrastructure, mid-cap device specialists with interventional catheterization platform expertise, and regional generic manufacturers capturing oral formulation volume. Competitive moves center on M&A-driven portfolio diversification into adjacent cardiovascular segments and strategic partnerships bridging pharmaceutical and device capabilities.
Within the large-cap pharmaceutical tier, Pfizer Inc and Novartis International AG occupy positions defined by manufacturing scale and specialty therapy depth respectively. AstraZeneca PLC exemplifies the cardiovascular outcome trial investment archetype that differentiates branded portfolios from commoditized alternatives. These three entities anchor the competitive structure through distinct strategic postures: scale-driven supply security, refractory angina segment specialization, and evidence-based portfolio positioning.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis International AG |
| AstraZeneca PLC |
| Merck & Co., Inc |
| Bristol Myers Squibb Company |
| Johnson & Johnson |
| Sanofi SA |
| Bayer AG |
| AbbVie Inc |
| Others |
Supply & Pricing Matrix
Ninety-day platinum-iridium inventory buffers at catheter manufacturers compress procurement leverage against South African mining houses, concentrating pricing power upstream while downstream hospital GPOs extract volume concessions through multi-year stent commitments. This lead-time asymmetry between raw material access and finished device distribution defines margin capture across the ischemia value chain.
Pricing Analysis
Configured-to-order fractional flow reserve wire platforms command 35-45% premiums over standard catalog configurations due to lesion-specific calibration requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by imaging integration capability and physiologic measurement precision. Price differentiation hinges on FDA breakthrough designation status and Japanese PMDA priority review tiering. Pricing pressure stems from China's volume-based procurement reforms that collapsed stent prices through national tender aggregation. Academic medical centers exhibit lowest price sensitivity due to outcome trial sponsorship obligations, while community hospitals in the United States Midwest face acute margin compression from Catholic health system purchasing consolidation.
Supply Chain Analysis
Strait of Malacca transit underwrites 60% of nitinol shape-memory alloy shipments to European stent manufacturers, exposing just-in-time production schedules to piracy and weather disruption. Manufacturing concentrates in Ireland, Costa Rica, and Malaysia for tax-advantaged medical device production. Raw material dependencies center on South African platinum-iridium wire cores, German precision laser-cutting equipment, and Japanese bioresorbable polymer feedstocks. Single-source vulnerability concentrates in guidewire tip grinding operations where Swiss micromachining houses hold process IP. Distribution runs through regional distribution centers co-located with major hospital GPO warehouses in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transcatheter revascularization platforms are expanding the treatable patient population by 20-30% against surgical eligibility criteria, positioning the market in early-cycle expansion as device innovation outpaces operator training pipeline constraints.
For Market Incumbents: Shield proprietary intravascular imaging algorithms through patent thickets around optical coherence tomography plaque characterization automation. Consolidate manufacturing footprint into Costa Rican and Irish free-trade zones to offset EU MDR compliance cost inflation. Vertical integration into bioresorbable polymer synthesis reduces exposure to Japanese feedstock concentration. For New Entrants and Emerging Players: Differentiate on wearable electrocardiography patch platforms for silent ischemia detection in homecare settings, where reimbursement pathways remain unsettled and incumbent device portfolios lack coverage. Target Germany's freestanding cardiac catheterization facility expansion as the most penetrable geography due to DRG refinement enabling same-day discharge economics. Pursue hospital-at-home partnership models with integrated delivery networks seeking post-acute care cost reduction. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting cardiovascular device divisions to refocus on biologics pipelines. Five-to-ten year viability hinges on sustained procedure volume growth among super-aged demographics and successful navigation of EU MDR clinical evidence requirements. Monitor FDA breakthrough device designation velocity as the signal to watch for inflection in commercialization timelines and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress commercialization gaps for physiologic assessment technologies in catheterization laboratories. |
| CE Marking Pathway Navigation | EU MDR equivalence restrictions force proprietary clinical data generation that filters small-cap competitors from European markets. |
| Hospital System Partnership | Sole-source agreements with Catholic health system mergers in the United States Midwest lock out competing sales forces. |
| Software Companion Development | Machine learning integration with intravascular imaging automates stent sizing decisions and creates recurring SaaS revenue. |
| Reimbursement Strategy | CMS national coverage determinations for fractional flow reserve wires directly shape Medicare-eligible patient access. |
Research Methodology
A spread of perspectives from interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying procedure volume and pricing trajectories. Primary interviews with catheterization laboratory directors and regulatory affairs leads at device manufacturers were cross-validated against FDA 510(k) filings, EMA CE marking databases, CMS national coverage determinations, and hospital procurement contract repositories. Bottom-up modeling of installed base and replacement cycles was triangulated against top-down pharmaceutical revenue segmentation.
Segmentation dimensions modeled include product type, application, delivery mode, and end user across the analysis window. CAGRs were derived from procedure volume elasticity to demographic aging, reimbursement policy shifts, and technology substitution patterns. Forecast inputs incorporated Japanese super-aged PCI recipient ratios, German DRG same-day discharge incentive coefficients, and Chinese volume-based procurement price compression curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough designation velocity, EU MDR certification backlog resolution, or platinum-iridium supply stability would require recalibration. Practitioners should keep alternative scenarios live as interventional cardiology fellowship pipeline constraints and wearable monitoring reimbursement pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Brugada Syndrome Treatment Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Tachycardia Market
Cardiovascular
US Statin Market
Cardiovascular
Angina Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Genetic Cardiomyopathies Market
Cardiovascular
Atherosclerosis Market