
 Hypercholesterolemia Drugs Market | 2026-2036
Hypercholesterolemia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Hypercholesterolemia Drugs Market Analysis
The United States is reshaping production dynamics for advanced biologic therapies targeting lipid disorders. Amgen leverages its manufacturing scale in monoclonal antibody production to maintain supply continuity for injectable cholesterol-lowering therapies. Pfizer anchors its position through extensive R&D investment across oral and parenteral formulation platforms. Sanofi competes through differentiated positioning in the PCSK9 inhibitor segment with sustained clinical trial infrastructure.
Hypercholesterolemia drugs comprise pharmaceutical agents designed to reduce elevated serum cholesterol levels, primarily targeting LDL-C reduction through hepatic enzyme inhibition, intestinal bile acid binding, or monoclonal antibody-mediated PCSK9 pathway blockade. These therapies serve the primary commercial purpose of preventing atherosclerotic cardiovascular disease progression in patients with familial or acquired lipid disorders. The statin drug class occupies the largest volume share due to decades of generic availability and established clinical guidelines, while PCSK9 inhibitors represent the fastest-expanding margin pool driven by biologic pricing and specialty pharmacy distribution. Injectable formulations command premium positioning compared to oral tablets, reflecting manufacturing complexity and cold-chain logistics requirements.
The FDA, EMA, and WHO collectively govern market access through cardiovascular outcomes trial mandates, good manufacturing practice standards, and prequalification pathways for essential medicines. These frameworks elevate clinical evidence requirements for novel mechanisms while streamlining biosimilar entry for mature statin compounds. Stakeholders must monitor evolving pharmacoeconomic assessments from national reimbursement bodies as they determine formulary placement for next-generation lipid-lowering therapies.
Market Dynamics
The Hypercholesterolemia Drugs Market is experiencing structural compression as injectable biologics displace oral statins in high-risk patient populations, driven by Medicare reimbursement pathways that favor PCSK9 inhibitor adoption in the United States.
Growth Catalysts
- Accelerated FDA Approval Pathways:The FDA's cardiovascular therapy fast-track mechanisms compress development timelines for novel lipid-lowering mechanisms. Specialty clinics expand biologic procurement under these streamlined frameworks.
- Medicare Reimbursement Realignment:United States federal policies now cover PCSK9 inhibitors for broader patient risk categories. Hospital pharmacies respond with expanded cold-chain infrastructure.
- Injectable Formulation Demand:Specialty pharmacy networks are consolidating distribution for monoclonal antibody therapies. This channel concentration reduces patient access friction for parenteral cholesterol management.
Market Restraints
- Biologic Manufacturing Complexity:Monoclonal antibody production requires single-use bioreactor systems and extensive viral clearance validation. Capacity constraints limit supply elasticity for PCSK9 inhibitors.
- Reimbursement Fragmentation:European national health technology assessment bodies apply divergent cost-effectiveness thresholds. EMA-approved therapies face delayed market access in key member states.
- Generic Statin Saturation:Decades of atorvastatin and rosuvastatin generic availability compress pricing power. Primary care prescribing inertia preserves volume but erodes margin expansion.
Strategic Opportunities
- Underpenetrated Familial Hypercholesterolemia Screening:India's diagnostic infrastructure gaps leave inherited lipid disorders undetected. CDSCO-aligned clinical pathways could unlock patient identification at scale.
- Oral PCSK9 Small Molecule Development:Convergence of peptide chemistry and hepatocyte-targeting delivery systems promises tablet alternatives to injectable biologics. Formulation innovators capture compliance advantages.
- Specialty Pharmacy Direct Distribution:United States hub-and-spoke models bypass wholesale intermediaries for temperature-sensitive biologics. Manufacturers gain patient-level data and adherence monitoring capabilities.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Cell culture optimization and continuous manufacturing expertise concentrates among limited specialist cohorts. Workforce gaps delay facility commissioning.
- Cardiovascular Outcomes Trial Burden:FDA and EMA mandate extensive hard endpoint studies for novel mechanisms. Trial duration and cost intensity deter mechanistic diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypercholesterolemia Drugs Market |
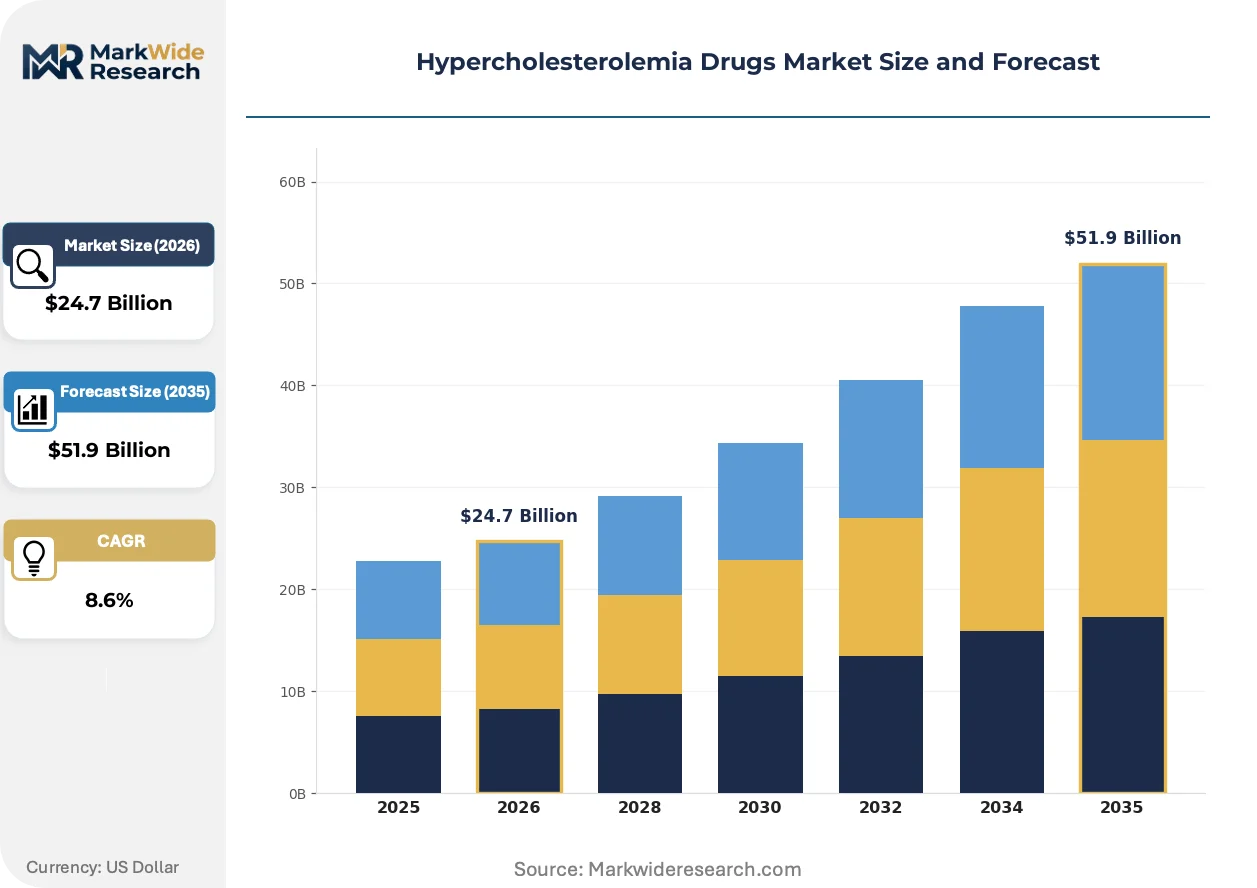
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Statins, PCSK9 Inhibitors, Bile Acid Sequestrants, Fibrates Formulation: Tablets, Injectable, Capsules, Oral Solutions Administration Route: Oral, Subcutaneous, Intravenous, Transdermal Prescription Type: Generic, Brand, Over-the-Counter, Specialty |
| Companies Covered | AstraZeneca, Amgen, Pfizer, Regeneron Pharmaceuticals, AbbVie, Novartis, Sanofi, Viatris, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypercholesterolemia Drugs Market Emerging Trajectories
Active transformation across the Hypercholesterolemia Drugs Market centers on formulation technology migration, regulatory evidence requirements, and distribution channel restructuring that collectively redefine competitive positioning.
Gene silencing technologies are migrating from research-stage RNA interference toward clinical antisense oligonucleotide applications for lipid metabolism modulation. Academic medical centers in the United States and Germany are establishing dedicated nucleic acid therapeutic infusion units. Hepatocyte-targeted delivery mechanisms compress the dosing frequency gap between small molecules and biologics.
The EMA's evolving guidance on cardiovascular outcomes trial design is mandating longer follow-up periods and composite endpoint specifications. European manufacturers must now integrate health technology assessment input earlier in Phase III planning. PCSK9 inhibitor sponsors face particular scrutiny on cost-effectiveness modeling for familial hypercholesterolemia subpopulations.
Hospital systems are consolidating cholesterol management into integrated specialty pharmacy carve-outs. United States academic medical centers now require manufacturer direct contracting for injectable biologics, displacing traditional wholesale relationships. This channel compression concentrates purchasing leverage among fewer institutional buyers.
Hypercholesterolemia Drugs Market Segmentation
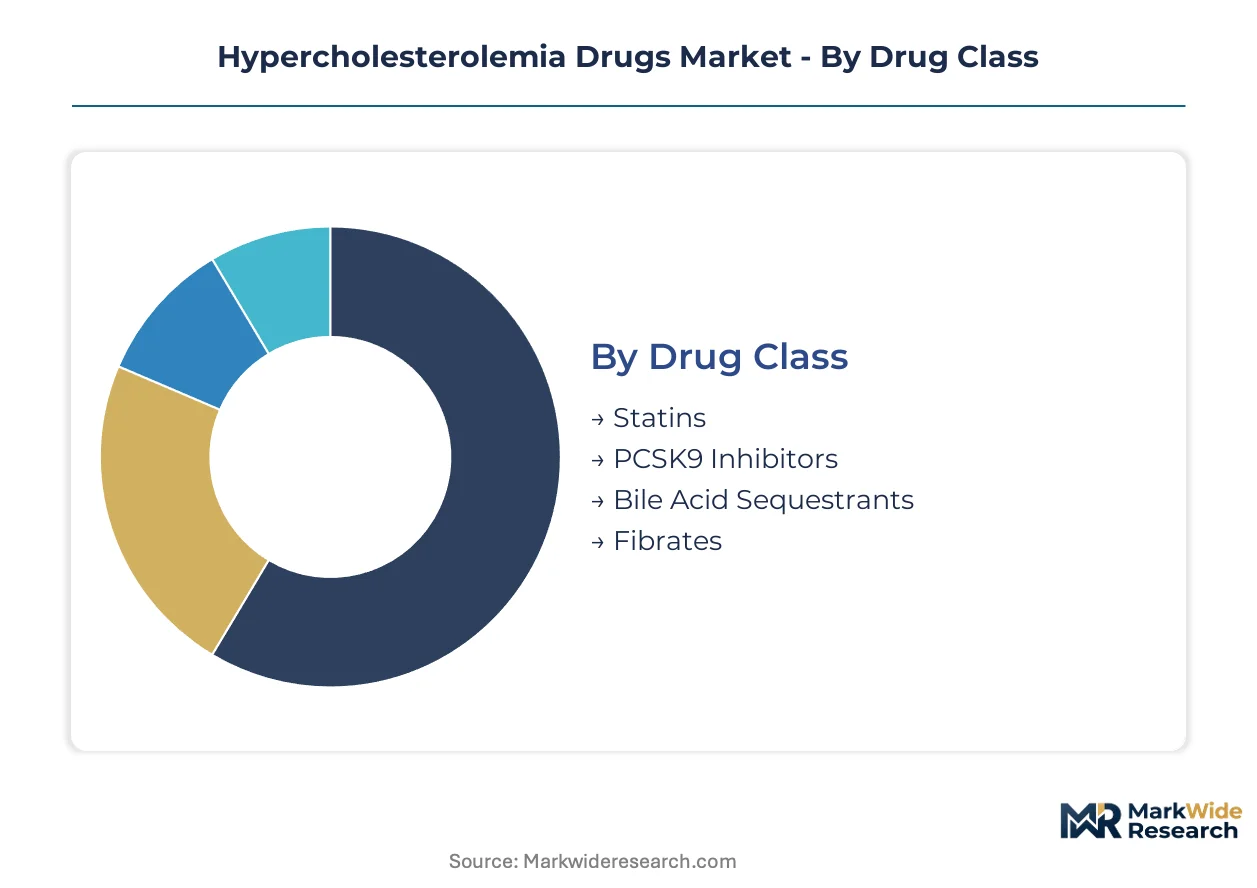
Segmentation in the Hypercholesterolemia Drugs Market reveals divergent margin profiles across molecular mechanisms and delivery formats. Drug class stratification separates commoditized oral therapies from premium biologics, while formulation and route of administration determine cold-chain infrastructure requirements and reimbursement complexity.
Drug Class:
Cycle times vary dramatically across therapeutic categories, with small-molecule generics turning inventory weekly while monoclonal antibodies require months-long production campaigns.
- Statins:HMG-CoA reductase inhibitors including atorvastatin and rosuvastatin dominate prescription volume through decades of generic availability. United States Medicare formularies prioritize these agents for primary prevention, though pricing compression limits manufacturer investment in next-generation formulations.
- PCSK9 Inhibitors:Monoclonal antibodies targeting proprotein convertase subtilisin/kexin type 9 deliver LDL-C reductions exceeding 50% in familial hypercholesterolemia patients. Specialty pharmacy networks in the United States consolidate procurement for these injectable biologics under revised federal reimbursement pathways.
- Bile Acid Sequestrants:Resin-based intestinal binding agents serve as adjunct therapy or statin-intolerant populations.
- Fibrates:Peroxisome proliferator-activated receptor agonists target triglyceride elevation with limited LDL-C impact.
Statins anchor the volume base while PCSK9 Inhibitors gain share at the steepest rate.
Formulation:
Cost tier stratification separates commodity oral solids from precision-manufactured parenteral biologics requiring specialized handling infrastructure.
- Tablets:Compressed oral solids represent the dominant dispense format for statin therapy, with immediate-release and extended-release variants accommodating compliance preferences. United States retail pharmacies process millions of monthly prescriptions for atorvastatin tablets under standardized insurance formularies.
- Injectable:Prefilled syringes and autoinjector devices for monoclonal antibody delivery command premium positioning through manufacturing complexity and cold-chain requirements. Hospital pharmacies invest in validated refrigeration infrastructure to support PCSK9 inhibitor storage at 2-8°C.
- Capsules:Gelatin or HPMC shells enclose powder or granule formulations for bile acid sequestrants requiring large active loads.
- Oral Solutions:Liquid formulations address pediatric dosing and dysphagia populations with concentration-calibrated delivery.
Tablets generate the highest absolute prescription counts while Injectable formulations capture the most favorable gross margins.
Administration Route:
Patient compliance patterns diverge sharply between self-administered oral regimens and clinic-dependent parenteral delivery.
- Oral:Gastrointestinal absorption routes dominate daily therapy for statins, fibrates, and bile acid sequestrants. Primary care physicians in the United States default to oral prescribing for uncomplicated hyperlipidemia management.
- Subcutaneous:Abdominal or thigh injection sites enable patient self-administration of PCSK9 inhibitors on biweekly or monthly schedules. Specialty pharmacies provide injection training and adherence monitoring for home administration.
- Intravenous:Infusion delivery applies to investigational RNA interference therapies and acute lipid apheresis adjuncts.
- Transdermal:Skin patch delivery remains experimental for lipid-lowering applications with limited commercial penetration.
Oral administration retains the broadest patient reach while Subcutaneous delivery achieves the highest persistence rates in high-risk cohorts.
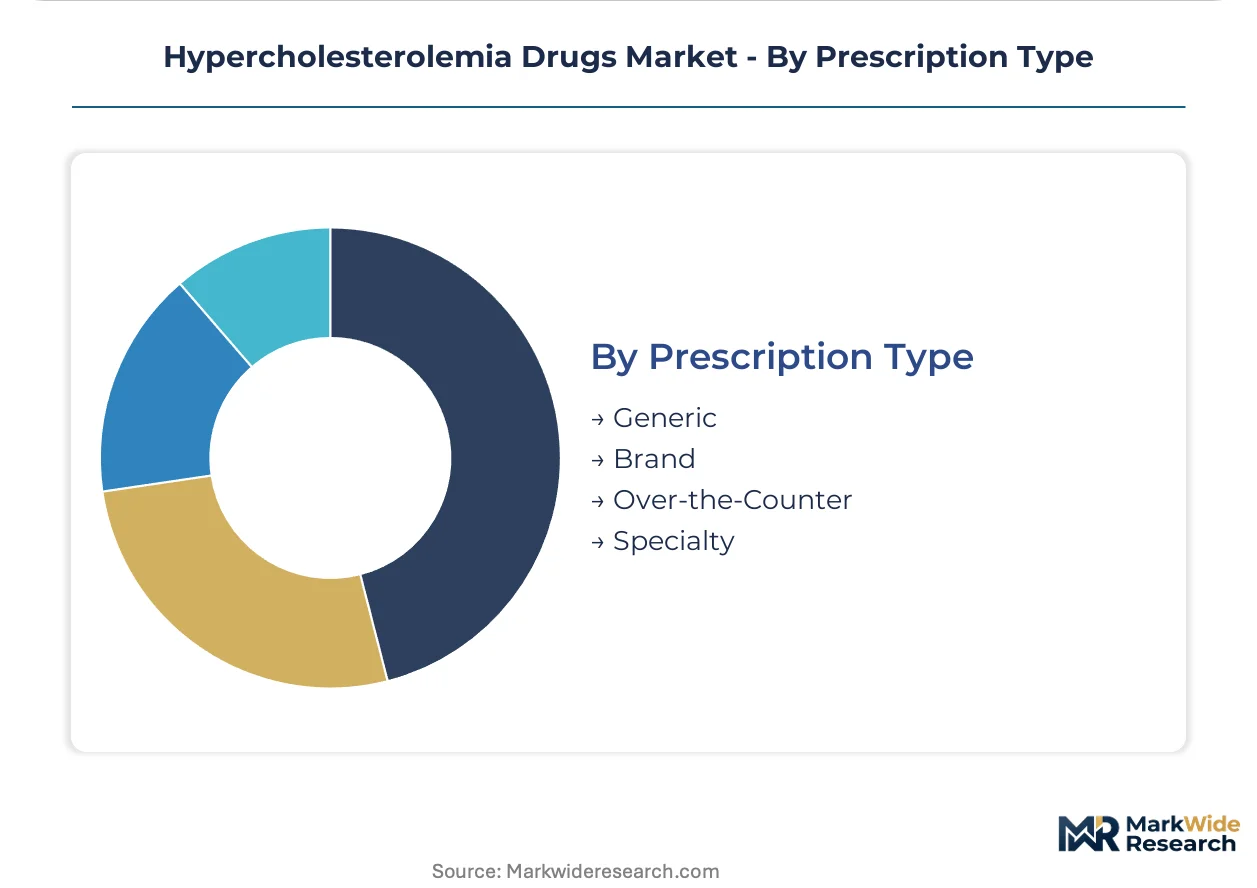
Prescription Type:
Regulatory exclusivity status determines pricing power and channel access across the commercial landscape.
- Generic:Bioequivalent statin copies from multiple manufacturers compete on pharmacy reimbursement rates. United States 180-day exclusivity periods for first filers create temporary margin windows before price collapse.
- Brand:Patent-protected novel mechanisms including PCSK9 inhibitors maintain list pricing through specialty pharmacy distribution. Prior authorization requirements from United States payers filter patient access to branded biologics.
- Over-the-Counter:Low-dose statin availability without prescription applies in limited jurisdictions with pharmacist oversight requirements.
- Specialty:Restricted distribution through accredited pharmacies manages REMS programs and patient monitoring for high-cost biologics.
Generic prescriptions fill the most units daily while Specialty classification delivers the highest revenue per dispense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic manufacturing capacity clusters in the United States, Germany, and Switzerland, with regulatory approval velocity determining competitive entry sequencing across major pharmaceutical markets.
United States
Medicare reimbursement expansion for PCSK9 inhibitors drives hospital pharmacy procurement of injectable biologics. The FDA's accelerated approval pathways compress development timelines for novel lipid-lowering mechanisms. Boston and San Francisco biotech corridors host concentrated clinical trial infrastructure for cardiovascular outcomes studies.
Germany
EMA-aligned health technology assessment bodies apply stringent cost-effectiveness thresholds for PCSK9 inhibitor formulary placement. The country's national pharmaceutical regulator mandates extended cardiovascular outcomes data for novel mechanisms. The Rhine-Main cluster anchors monoclonal antibody production scale for European distribution.
Switzerland
Specialty pharmaceutical manufacturing concentrates in Basel and Zurich for biologic export to EU markets. Swissmedic maintains alignment with EMA standards while offering streamlined review for innovative cardiovascular therapies. The Lake Geneva region hosts contract manufacturing organizations supporting PCSK9 inhibitor fill-finish operations.
India
Underpenetrated familial hypercholesterolemia screening leaves inherited lipid disorders undetected at scale. CDSCO-aligned clinical pathways could unlock patient identification through diagnostic infrastructure expansion. Hyderabad and Mumbai pharmaceutical clusters specialize in generic statin active pharmaceutical ingredient production for export markets.
Japan
PMDA review timelines for cardiovascular biologics shape regional launch sequencing for Asia-Pacific markets. The country's national pharmaceutical regulator emphasizes long-term safety surveillance for novel mechanisms. The Kanto region maintains specialized cold-chain distribution infrastructure for temperature-sensitive injectable therapies.
Hypercholesterolemia Drugs Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and delivery technology. The market structure consolidates around large-cap biopharmaceutical entities with monoclonal antibody manufacturing scale, while mid-tier specialists occupy niche segments in oral small-molecule development. Three archetypes dominate: integrated biologic manufacturers with single-use bioreactor networks, multi-platform pharmaceutical conglomerates spanning oral and parenteral portfolios, and focused cardiovascular specialists with concentrated R&D pipelines. Competitive moves center on specialty pharmacy direct contracting arrangements and hepatocyte-targeting delivery technology licensing.
Within the integrated biologic tier, Amgen and Sanofi occupy positions anchored in PCSK9 inhibitor commercial infrastructure. Pfizer exemplifies the multi-platform archetype with spanning investments across statin generics and novel biologic formulations. Regeneron Pharmaceuticals sits within the cardiovascular specialist category, representing concentrated clinical development capabilities in lipid-lowering mechanisms.
| Leading Market Players |
|---|
| AstraZeneca |
| Amgen |
| Pfizer |
| Regeneron Pharmaceuticals |
| AbbVie |
| Novartis |
| Sanofi |
| Viatris |
| Merck |
| Others |
Supply Flow & Price Mechanics
Monoclonal antibody manufacturing capacity in the United States and Switzerland anchors margin capture downstream, where specialty pharmacy networks extract premium positioning for temperature-sensitive biologics. Cold-chain infrastructure investments by hospital systems concentrate purchasing leverage among fewer institutional buyers, compressing wholesale intermediaries and reshaping where value accrues across the value chain.
Pricing Analysis
Medicare reimbursement policy dictates the pricing tier structure for hypercholesterolemia therapies, separating patent-protected PCSK9 inhibitors from commoditized generic statins. Three-tier pricing structure across premium biologics, standard branded small molecules, and economy generics reflects FDA exclusivity status and formulary placement. Pricing pressure stems from generic statin saturation in primary care channels, where pharmacy benefit managers prioritize lowest-net-cost alternatives. Price-sensitive patient populations in Medicare Part D drive volume toward generic atorvastatin, while least-sensitive cohorts in specialty clinics absorb biologic premiums.
Supply Chain Analysis
Export controls on single-use bioreactor technology and viral filtration systems limit capacity expansion for monoclonal antibody producers in emerging markets. Active pharmaceutical ingredient production draws from India and China for statin intermediates, while fill-finish operations concentrate in Switzerland and the United States for PCSK9 inhibitors. Single-source vulnerability in Chinese heparin-derived raw materials creates supply continuity exposure for anticoagulant adjunct therapies. Distribution runs through specialty pharmacy hub-and-spoke models that bypass traditional wholesale channels for temperature-controlled biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hypercholesterolemia drugs market is recovering from generic statin saturation through biologic substitution cycles, as Medicare reimbursement realignment accelerates PCSK9 inhibitor adoption in high-risk cardiovascular populations.
For Market Incumbents: Build manufacturing scale moats through single-use bioreactor network expansion in the United States and Switzerland. Secure cold-chain distribution partnerships with specialty pharmacy networks to lock out wholesale competitors. Invest in hepatocyte-targeting delivery technology to preempt oral small-molecule PCSK9 threats. Regulatory exclusivity extensions through pediatric indication studies defend against biosimilar erosion. For New Entrants and Emerging Players: Pursue underpenetrated familial hypercholesterolemia screening infrastructure in India, where diagnostic gaps leave inherited lipid disorders undetected at scale. Target oral formulation development for PCSK9 pathway inhibition, capturing compliance advantages over injectable biologics. Leverage direct-to-specialist education campaigns to bypass entrenched primary care prescribing inertia for statin therapy. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier cardiovascular specialists with concentrated RNA interference pipelines and hepatocyte-targeting delivery platforms. Long-term viability hinges on regulatory approval velocity for novel mechanisms beyond PCSK9 inhibition. Watch FDA accelerated approval pathway utilization rates as the inflection indicator for competitive entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Pharmacy Direct Contracting | Bypasses wholesale intermediaries and captures patient-level adherence data for biologics. |
| Oral PCSK9 Small Molecule Development | Peptide chemistry convergence promises tablet alternatives to injectable monoclonal antibodies. |
| Familial Hypercholesterolemia Screening Expansion | CDSCO-aligned pathways in India unlock patient identification for inherited lipid disorders. |
| Cold-Chain Infrastructure Investment | Hospital pharmacy refrigeration validation supports 2-8°C storage requirements for biologics. |
| Hepatocyte-Targeted Delivery Licensing | Nucleic acid therapeutic infusion units enable gene silencing technology migration. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare formulary databases. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation anchored the market sizing framework.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeling across drug class, formulation type, administration route, and patient risk category. CAGRs derived from historical generic erosion patterns and biologic adoption curves in cardiovascular populations. Forecast inputs incorporated Medicare reimbursement policy trajectories and specialty pharmacy network expansion rates.
Sensitivities concentrate around FDA approval pathway timing, Medicare coverage determination reversals, and biosimilar entry sequencing for monoclonal antibodies. Forecasts reflect documented assumptions on patient risk stratification and prescriber behavior shifts. Material shifts in cardiovascular outcomes trial requirements or federal reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Antihypertensive Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Tachycardia Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Asia-Pacific Acute Coronary Syndrome Market
Cardiovascular
US Statin Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Vasculitis Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Global Hypotension Treatment Market