
 Aortic Coarctation Market | 2026-2036
Aortic Coarctation Market Size, Share, and Industry Trends Forecast 2026-2036
Aortic Coarctation Market Analysis
Aftermarket service revenue for implanted stent monitoring is rewriting profitability expectations across the value chain. Medtronic leverages its integrated cath lab ecosystem to capture recurring follow-up revenue. Boston Scientific Corporation anchors its position through specialized training programs for pediatric interventional cardiologists. W. L. Gore & Associates, Inc. differentiates via proprietary expanded polytetrafluoroethylene graft technology for complex arch reconstructions.
Aortic coarctation denotes a congenital narrowing of the descending aorta, typically occurring distal to the left subclavian artery, requiring intervention when the gradient exceeds 20 mmHg or when systemic hypertension develops. The condition demands precise anatomical assessment through computed tomography angiography or magnetic resonance imaging prior to procedural planning. Stent platforms command the dominant share of product revenue due to their durability in adult and adolescent populations, while balloon angioplasty retains relevance in neonatal cases where vessel growth must continue unimpeded. Minimally invasive catheter-based approaches are displacing open surgical repair across eligible patient cohorts, though hybrid procedures preserve margin pools in complex arch hypoplasia cases.
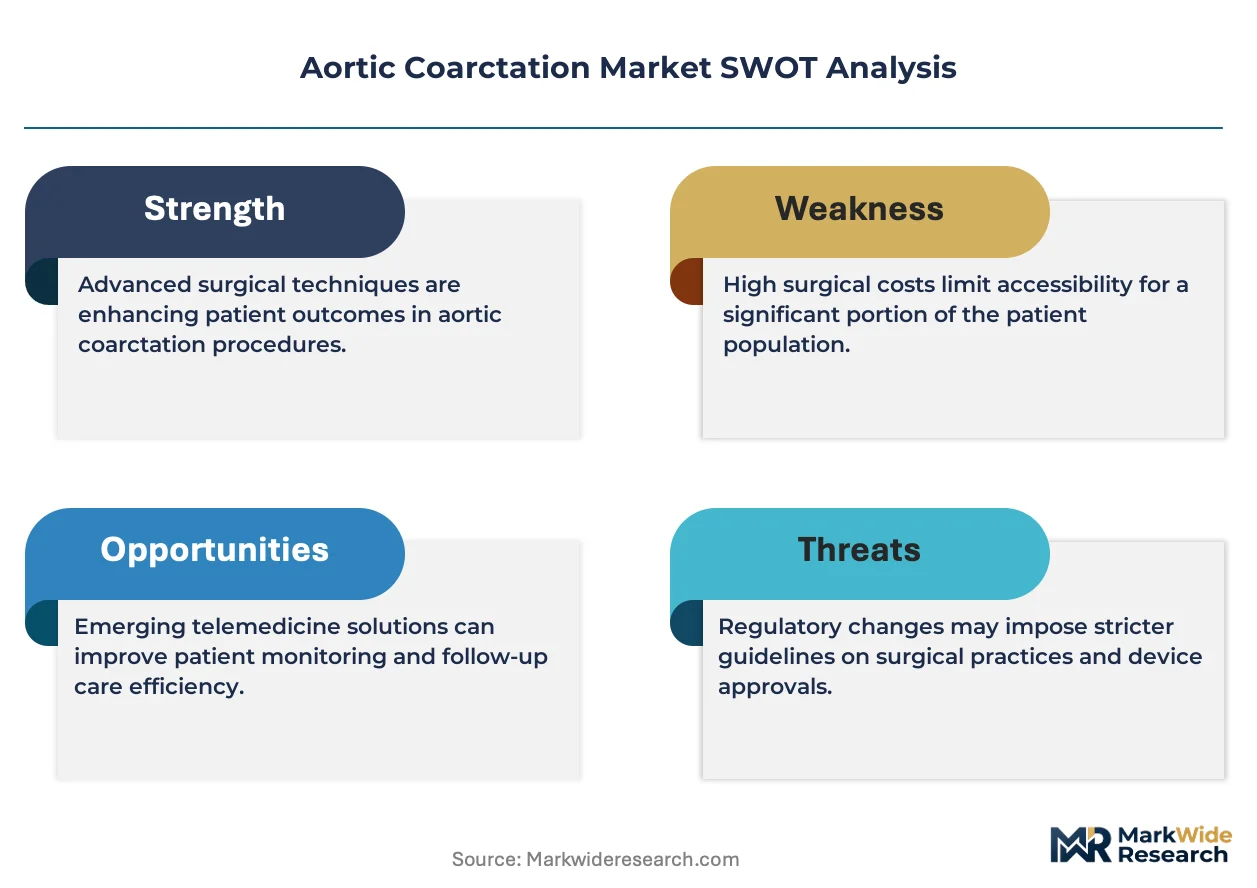
The FDA maintains stringent premarket approval standards for pediatric cardiovascular devices through its humanitarian device exemption and pediatric device consortia frameworks. The EU Medical Device Regulation requires enhanced clinical evidence and post-market surveillance for class III implantable devices, directly elevating R&D costs for manufacturers seeking CE marking. Japan's PMDA operates a priority review pathway for orphan pediatric indications that accelerates market access for innovative coarctation therapies. Stakeholders must monitor evolving reimbursement thresholds for same-day discharge procedures versus extended hospitalization protocols.
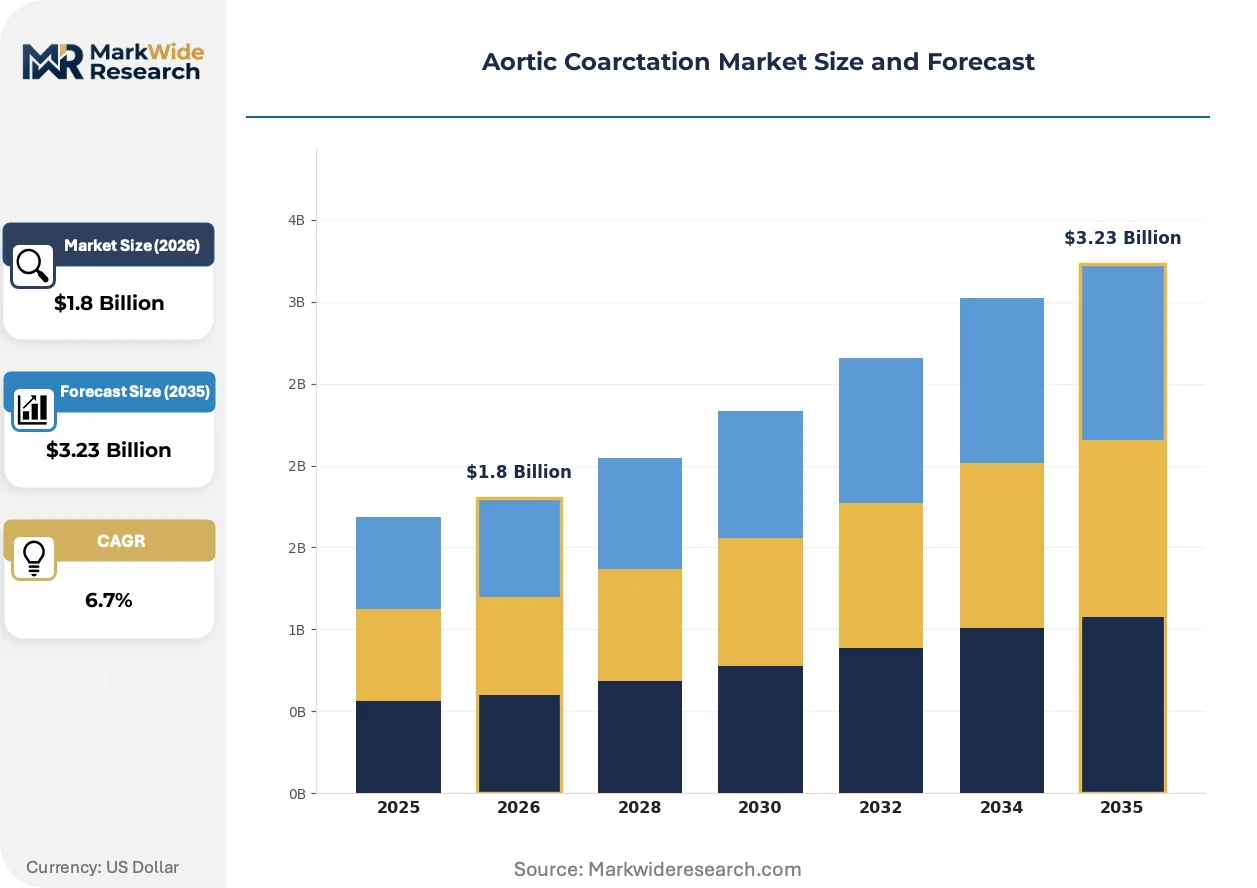
Market Dynamics
Catheter-based interventions are displacing open surgical repair as the dominant treatment modality for eligible aortic coarctation patients, compressing procedure times and reshaping hospital capacity planning across tertiary cardiac centers.
Growth Catalysts
- Japan's PMDA Priority Review:The orphan pediatric indication pathway accelerates market access for innovative coarctation therapies, reducing regulatory timelines for novel stent platforms.
- Same-Day Discharge Protocols:Tertiary cardiac centers in Germany and the United States are expanding minimally invasive programs to capture reimbursement advantages from shortened hospitalization.
- Computed Tomography Angiography:Pre-procedural anatomical assessment via advanced imaging is standardizing patient selection and improving stent sizing accuracy.
Market Restraints
- EU MDR Evidence Requirements:Enhanced clinical evidence and post-market surveillance mandates for class III implantable devices are elevating R&D costs for CE marking.
- Neonatal Balloon Angioplasty Limitations:Vessel growth requirements in infants prevent stent deployment, fragmenting product revenue across incompatible age cohorts.
- Specialized Cath Lab Infrastructure:Concentration of hybrid operating suites in pediatric hospitals in the United States and Germany limits procedural access in secondary markets.
Strategic Opportunities
- Implanted Stent Monitoring Services:Aftermarket revenue streams from follow-up surveillance are rewriting profitability expectations across the device value chain.
- Hybrid Arch Reconstruction Procedures:Complex arch hypoplasia cases preserve margin pools for surgical graft technologies alongside catheter platforms.
- Pediatric Device Consortia Frameworks:FDA humanitarian device exemption pathways offer streamlined approval routes for orphan cardiovascular indications.
Industry Challenges
- Pediatric Interventional Cardiologist Training:Specialized catheter skills for congenital heart procedures require extended fellowship pipelines that lag program expansion.
- Post-Market Surveillance Integration:Long-term stent durability tracking demands data infrastructure that conflicts with legacy hospital record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aortic Coarctation Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Catheters, Devices Application: Pediatric Care, Surgical Intervention, Diagnostic Imaging, Therapy End User: Hospitals, Clinics, Outpatient Centers, Emergency Care Technology: Minimally Invasive, Robotic Surgery, Imaging Techniques, Hybrid Procedures |
| Companies Covered | Cook, RENATA MEDICAL, Medtronic, Andramed GmbH, B. Braun Melsungen AG, Boston Scientific Corporation, W. L. Gore & Associates, Inc., Artivion, Inc, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aortic Coarctation Market Emerging Trajectories
Digital integration across the procedural workflow is compressing decision cycles and enabling real-time anatomical modeling that reshapes how interventions are planned and executed.
Computational fluid dynamics coupled with patient-specific modeling is digitizing pre-procedural planning for aortic coarctation interventions. Tertiary cardiac centers in Germany and Japan are adopting these platforms to simulate hemodynamic outcomes before catheter insertion. The technology is digitizing surgical consultation workflows and reducing revision rates in complex arch anatomies.
The EU Medical Device Regulation's enhanced clinical evidence requirements are restructuring how manufacturers design pivotal trials for class III cardiovascular implants. Companies must now generate prospective pediatric data rather than extrapolating from adult studies. Stent platforms targeting adolescent and adult populations face the steepest compliance cost increases under these frameworks.
After-sales service unbundling is separating device procurement from long-term monitoring contracts in tertiary cardiac centers. Pediatric hospitals in the United States are negotiating standalone follow-up service agreements that decouple implant purchase from surveillance revenue. This pattern is most visible in academic medical centers with established congenital heart surgery programs.
Aortic Coarctation Market Segmentation
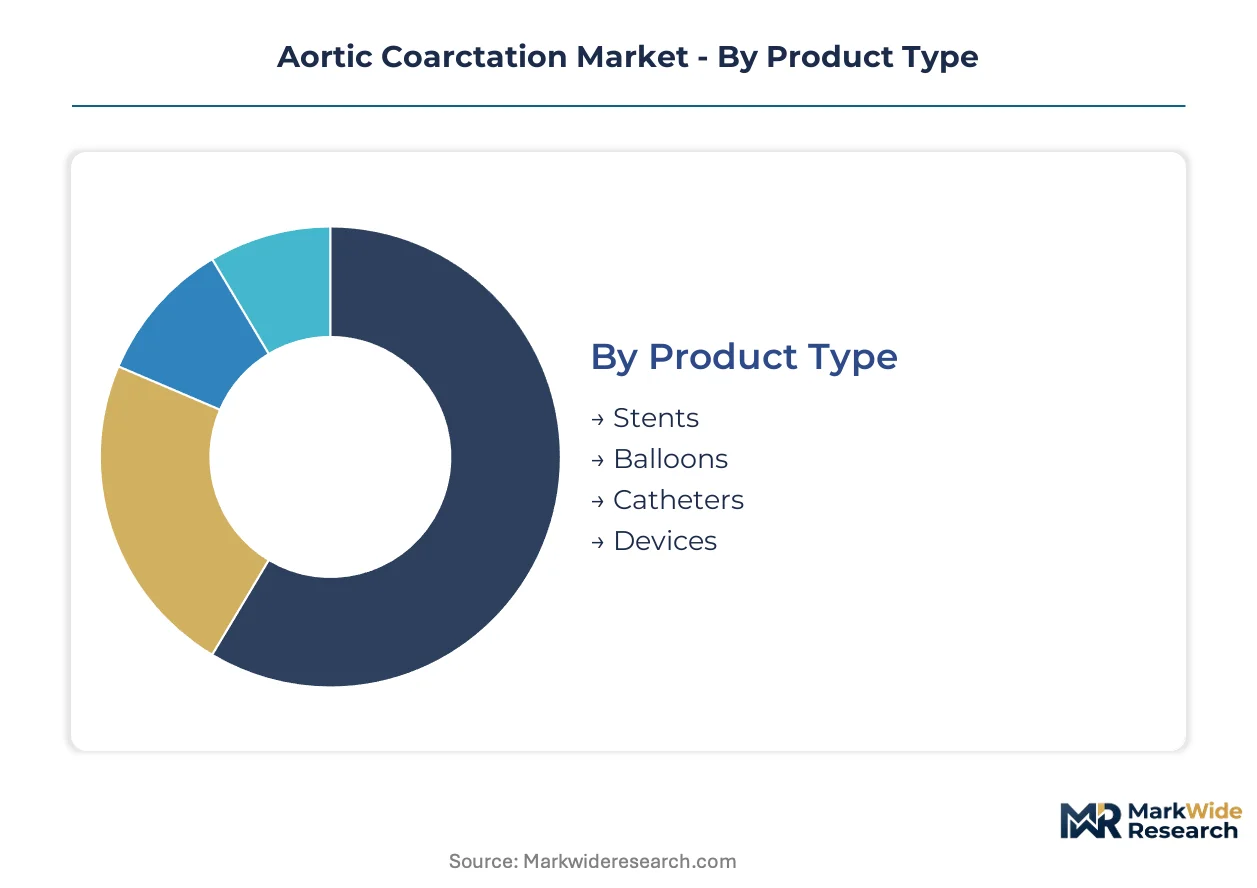
Aortic coarctation interventions fragment across incompatible age cohorts and procedural settings, forcing manufacturers to maintain parallel product portfolios. Segmentation discipline separates high-turnover consumables from durable implants with decade-long replacement cycles.
Product Type:
Balloons and catheters turn over fastest in neonatal cases requiring repeated dilations, while stent platforms anchor long-term installed base economics.
- Stents:Self-expanding nitinol or stainless steel platforms sized for aortic diameters from 12mm to 24mm. Demand concentrates in adolescent and adult populations at tertiary cardiac centers in Germany and the United States where stent durability justifies premium positioning.
- Balloons:High-pressure angioplasty balloons rated to 20 atmospheres for native coarctation dilation. Pediatric hospitals in Japan deploy these most intensively for infants below stent-eligible age thresholds, driving rapid inventory turnover.
- Catheters:Delivery sheaths and guidewires for transcatheter access.
- Devices:Covered stent-grafts and occlusion plugs for complex anatomies.
Stents dominate installed base. Balloons are where expansion concentrates.
Application:
Cost tier stratification separates high-acuity surgical intervention from recurring diagnostic surveillance.
- Pediatric Care:Longitudinal management from neonatal diagnosis through adolescent transition, requiring age-appropriate intervention sequencing. Tertiary cardiac centers in the United States structure dedicated transition clinics to retain patients across growth stages.
- Surgical Intervention:Open repair and hybrid arch reconstruction for complex hypoplasia. German pediatric hospitals preserve margin pools here through specialized extracorporeal perfusion capabilities that catheter labs cannot replicate.
- Diagnostic Imaging:CTA and MRI protocols for anatomical assessment.
- Therapy:Pharmacological hypertension management adjunctive to mechanical intervention.
Pediatric care captures lifetime value. Surgical intervention commands highest per-procedure revenue.
End User:
Volume concentrates in hospital-based congenital heart programs, though outpatient migration is accelerating for stable adult coarctation follow-up.
- Hospitals:Pediatric cardiac centers with hybrid operating suites and on-site surgical backup. Japan's university hospitals anchor procedural volume through PMDA priority review pathway access.
- Clinics:Adult congenital heart disease clinics managing long-term hypertension surveillance.
- Outpatient Centers:Same-day discharge protocols for stent surveillance angiography.
- Emergency Care:Acute presentation management for undiagnosed coarctation in hypertensive crisis.
Hospitals dominate installed base. Outpatient centers are where expansion concentrates.
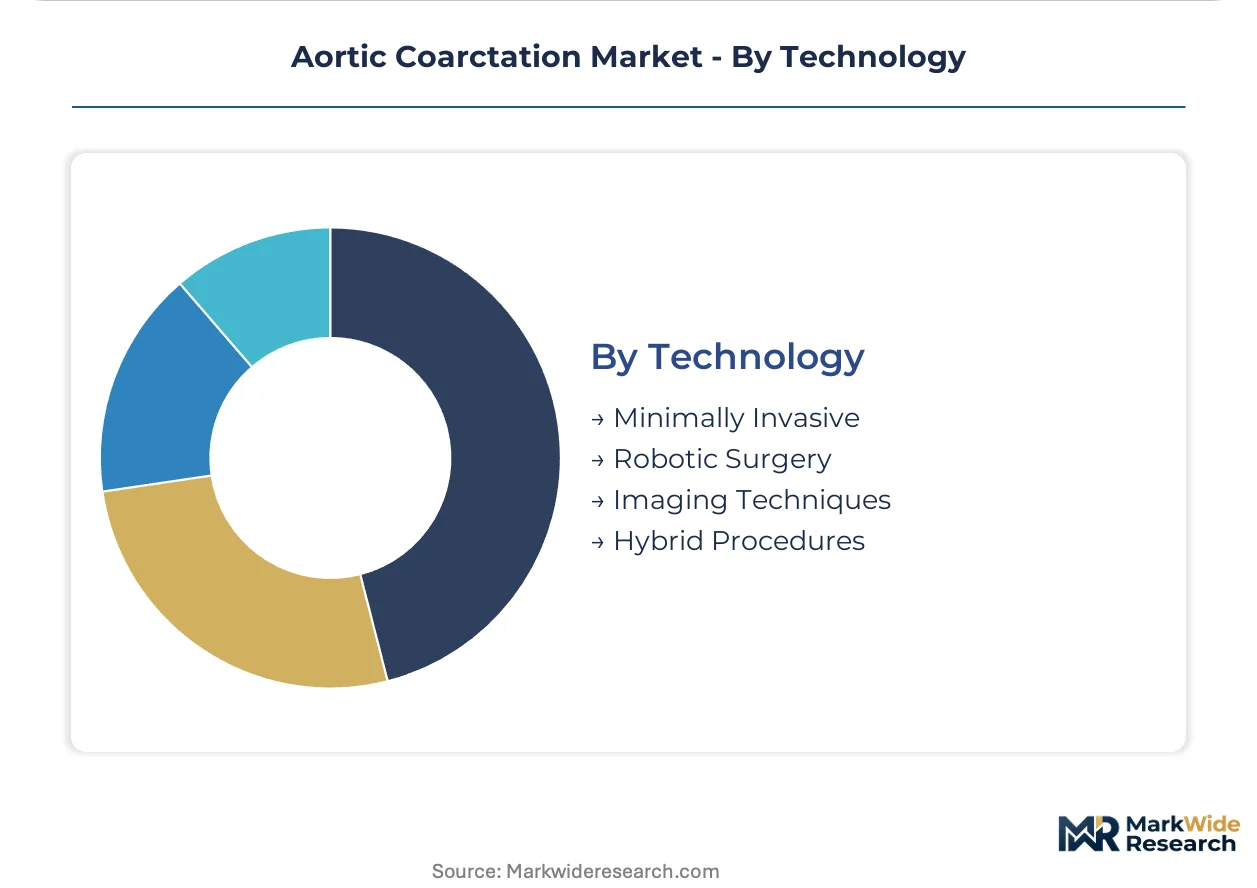
Technology:
Supply concentration in minimally invasive platforms is displacing open surgical market share fastest.
- Minimally Invasive:Transcatheter stent deployment via femoral or brachial access. Tertiary cardiac centers across Germany and the United States standardize these workflows to compress procedure times and capture same-day discharge reimbursement.
- Hybrid Procedures:Combined surgical and catheter-based arch reconstruction for complex anatomy. Japanese pediatric hospitals deploy these for arch hypoplasia cases exceeding standalone catheter capabilities.
- Robotic Surgery:Telemanipulation platforms for precision arch reconstruction.
- Imaging Techniques:Intravascular ultrasound and fusion imaging for stent positioning.
Minimally invasive dominates installed base. Hybrid procedures preserve margin pools in complex cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement elasticity varies sharply across markets. Japanese pediatric hospitals absorb premium stent pricing through PMDA priority pathways, while Indian tertiary centers face acute cost compression that favors balloon angioplasty over implantable platforms.
United States
Pediatric interventional cardiology fellowship pipelines at Boston Children's Hospital and Children's Hospital of Philadelphia sustain procedural volume growth. FDA humanitarian device exemption frameworks streamline orphan indication approvals for congenital heart devices. Tertiary cardiac centers across the Northeast Corridor capture same-day discharge reimbursement advantages that reshape capacity planning.
Germany
Hybrid operating suite investments at Deutsches Herzzentrum Berlin and Universitätsklinikum Heidelberg preserve surgical margin pools in complex arch hypoplasia cases. EU MDR post-market surveillance mandates for class III implantable devices elevate compliance costs for CE marking renewals. Bavarian pediatric hospitals anchor extracorporeal perfusion capabilities that catheter laboratories cannot replicate.
Japan
University hospital networks in Tokyo and Osaka leverage PMDA priority review pathways to accelerate novel stent platform access for orphan pediatric indications. METI funding programs support computational fluid dynamics adoption for pre-procedural hemodynamic simulation. Kanto region tertiary centers standardize minimally invasive workflows to compress intervention times.
United Kingdom
NHS England specialized commissioning frameworks concentrate aortic coarctation procedures at designated pediatric cardiac surgical centers in London and Birmingham. MHRA alignment with EU MDR clinical evidence requirements extends pediatric trial obligations for stent manufacturers. Great Ormond Street Hospital anchors transition clinic infrastructure for adolescent patient retention.
Canada
Provincial health authority reimbursement thresholds for congenital heart interventions vary across Ontario, Quebec, and British Columbia, creating patchwork access patterns. Health Canada premarket approval timelines for pediatric cardiovascular devices lag FDA pathways by 8-14 months. Toronto's Hospital for Sick Children anchors national referral volume for complex arch reconstructions.
Aortic Coarctation Market Vendor Landscape
Capability concentration sits with integrated cath lab ecosystem providers; scale advantage sits with diversified cardiovascular conglomerates. The vendor base separates into three functional tiers: stent platform specialists commanding premium positioning in adolescent populations, balloon catheter manufacturers serving high-turnover neonatal segments, and surgical graft technology holders preserving hybrid procedure margins. Dominant competitive moves include aftermarket service unbundling for long-term monitoring revenue and specialized training program deployment to lock in pediatric interventional cardiologist relationships.
Within the integrated ecosystem tier, Medtronic exemplifies cath lab infrastructure control that captures recurring follow-up revenue. Boston Scientific Corporation represents specialized training investment strategies that secure physician loyalty across academic medical centers. W. L. Gore & Associates, Inc. occupies the surgical graft technology position for complex arch reconstruction cases where catheter platforms face anatomical limitations.
| Leading Market Players |
|---|
| Cook |
| RENATA MEDICAL |
| Medtronic |
| Andramed GmbH |
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| W. L. Gore & Associates, Inc. |
| Artivion, Inc |
| Abbott |
| Others |
Supply Flow & Price Mechanics
Bavarian pediatric hospitals anchor extracorporeal perfusion capabilities that catheter laboratories cannot replicate, concentrating supply-side leverage for hybrid arch reconstruction procedures and enabling premium positioning for surgical graft technologies against commoditized stent platforms.
Pricing Analysis
After-sales service contracts for implanted stent monitoring drive lifetime value economics across the device value chain. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with bundled surveillance agreements from secondary hospitals purchasing devices alone. Cost compression in neonatal balloon segments intensifies because Japanese pediatric hospitals absorb premium stent pricing through PMDA priority pathways, forcing manufacturers to offset margin erosion in high-turnover consumable tiers. Tertiary cardiac centers in Germany exhibit lowest price sensitivity due to same-day discharge reimbursement advantages, while Indian tertiary centers face acute cost pressure favoring balloon angioplasty over implantable platforms.
Supply Chain Analysis
Export-control restrictions on nitinol shape-memory alloys and specialized catheter polymers limit technology flows between the United States, Germany, and Japan. Manufacturing concentration draws from Minnesota and Massachusetts clusters for delivery systems, Bavaria for hybrid surgical platforms, and Osaka for high-pressure balloon catheters. Raw material dependencies rest on nickel-titanium alloys, medical-grade polytetrafluoroethylene, and radiopaque marker bands. Single-source vulnerability runs through Japanese suppliers of superelastic nitinol wire. Distribution runs through GPO contracts at academic medical centers and direct procurement at specialized pediatric hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aortic coarctation interventions sit in early-cycle expansion as catheter-based approaches displace open surgical repair across eligible patient cohorts, with computational fluid dynamics adoption accelerating procedural standardization.
For Market Incumbents: Harden installed base economics by unbundling after-sales monitoring contracts from device procurement, capturing recurring surveillance revenue that competitors cannot replicate. Deepen backward integration into nitinol wire production to offset raw material cost volatility from Japanese suppliers. Lock in pediatric interventional cardiologist pipelines through specialized training programs at Boston Children's Hospital and Children's Hospital of Philadelphia, defending against emerging entrants lacking fellowship relationships. For New Entrants and Emerging Players: Mid-tier pediatric hospitals in the United Kingdom and Canada represent the most penetrable entry point, as NHS specialized commissioning frameworks and provincial reimbursement patchworks create access gaps that agile suppliers can exploit. Target neonatal balloon angioplasty segments where inventory turnover velocity compensates for lower per-unit margins, avoiding direct confrontation with entrenched stent platforms. Pursue FDA humanitarian device exemption pathways for orphan pediatric indications to compress regulatory timelines versus standard premarket approval routes. For Investors and Strategic Acquirers: Long-term, this sits as a installed-base annuity play because stent durability creates decade-long replacement cycles and aftermarket monitoring contracts generate recurring revenue streams insulated from acute pricing pressure. Acquisition targets should display hybrid procedure capabilities combining catheter platforms with surgical graft technologies for complex arch hypoplasia cases. Monitor PMDA priority review pathway utilization rates as the signal for Japanese market access velocity and premium pricing endurance.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance secures access to German hybrid operating suite investments. |
| Hospital System Partnership | Academic medical center alliances lock in pediatric interventional cardiologist training pipelines. |
| Software Companion Development | Computational fluid dynamics platforms compress decision cycles at Heidelberg and Berlin centers. |
| Reimbursement Strategy | Same-day discharge protocol alignment captures US tertiary cardiac center volume concentration. |
| Regulatory Approval Pathway | FDA humanitarian device exemption accelerates orphan pediatric indication market entry. |
Methodological Framework
The analysis maps stent platforms, balloon catheters, hybrid surgical grafts, and diagnostic imaging modalities, each validated through pediatric interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation from FDA premarket approval databases, EMA CE marking registries, PMDA priority review disclosures, and hospital procurement contract filings. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Forecasts hold fixed the regulatory frameworks of FDA humanitarian device exemption, EU MDR class III implantable requirements, and PMDA orphan pediatric pathways while varying adoption curves for computational fluid dynamics and same-day discharge protocols. Segmentation dimensions modeled include product type, age cohort eligibility, procedural setting, and geographic reimbursement cluster. CAGRs derive from installed base replacement cycles and aftermarket service penetration trajectories. Industry-specific inputs incorporate stent durability tracking data and hybrid operating suite capacity expansion plans.
Practitioners should monitor EU MDR post-market surveillance cost escalation and PMDA priority review pathway backlog accumulation for early signals of regulatory friction. Forecasts reflect assumptions of stable nickel-titanium alloy supply chains and continued tertiary cardiac center concentration in the United States, Germany, and Japan. Material shifts in export-control restrictions on medical-grade polymers or reimbursement collapses for catheter-based interventions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Statin Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
United States Cardiometabolic Fixed-Dose Combinations Market
Cardiovascular
Heart Transplant Market
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Restrictive Cardiomyopathy Treatment Market
Cardiovascular
Unstable Angina Therapeutics Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Tachycardia Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Middle East and Africa Acute Coronary Syndrome Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Chronic Heart Failure Market