
 Global Biomarkers Market | 2026-2036
Global Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomarkers Market Analysis
Multi-source procurement of assay reagents is consolidating as large diagnostic manufacturers absorb specialized suppliers into captive supply networks. F. Hoffmann-La Roche Ltd leverages its vertically integrated reagent-instrument platform to dominate high-throughput clinical workflows. Thermo Fisher Scientific Inc. sustains scale advantages through global distribution infrastructure for research-use biomarker kits. QIAGEN competes in sample preparation technologies that anchor downstream genomic analysis pipelines.
Biomarkers are measurable biological indicators—proteins, nucleic acids, metabolites, or imaging signatures—detected through immunoassay, mass spectrometry, or sequencing platforms to indicate normal or pathological processes, pharmacological responses, or disease susceptibility. Their primary commercial purpose is stratifying patient populations for targeted therapy selection and monitoring treatment efficacy in clinical and research settings. Oncology applications command the deepest margin pools as companion diagnostic requirements expand across solid tumor indications. Genomics technologies lead volume adoption while metabolomics represents the fastest-expanding frontier for discovering novel surrogate endpoints. Pharmaceutical companies constitute the most concentrated end-user segment, driving demand for biomarker-integrated drug development services.
FDA companion diagnostic guidance, EMA's evolving qualification pathway for novel methodologies, and Japan's PMDA biomarker qualification program collectively shape product development timelines and market access conditions across major jurisdictions. Regulatory stringency around analytical validation and clinical utility evidence directly determines which biomarker platforms achieve reimbursable status in national healthcare systems. Stakeholders must monitor divergence between FDA and EMA evidentiary standards when designing multi-regional trial strategies.
Market Dynamics
The convergence of FDA companion diagnostic mandates with pharmaceutical R&D restructuring is compressing biomarker assay development timelines while concentrating procurement power among vertically integrated diagnostic platforms.
Growth Catalysts
- Companion Diagnostic Mandates:FDA guidance requiring co-development of biomarker tests with targeted oncology therapies is institutionalizing biomarker-integrated trial designs across pharmaceutical pipelines.
- Pharmaceutical R&D Restructuring:Large drug developers are internalizing biomarker discovery capabilities to reduce dependency on external contract research organizations and accelerate patient stratification.
- China NMPA Acceleration:Streamlined review pathways for genomic-based assays are shortening time-to-market for molecular diagnostic platforms serving China's expanding hospital network.
Market Restraints
- Reagent Supply Concentration:Specialized assay chemistries depend on captive supply networks controlled by three dominant diagnostic manufacturers, creating single-source vulnerability for mid-scale laboratories.
- Analytical Validation Burden:EMA's evolving evidentiary standards for novel biomarker methodologies require extensive clinical utility documentation that extends development cycles by 18-24 months.
- Mass Spectrometry Cost Structure:High capital intensity of metabolomics infrastructure limits deployment to reference laboratories and academic medical centers, constraining point-of-care adoption.
Strategic Opportunities
- Metabolomics White Space:Surrogate endpoint discovery through metabolic profiling represents an underexploited frontier for cardiovascular and neurodegenerative indications where genomic biomarkers show limited predictive value.
- Japan PMDA Qualification:The biomarker qualification program creates accelerated pathways for novel assay formats seeking reimbursable status in the world's second-largest pharmaceutical market.
- Multi-Omics Convergence:Integration of proteomic, genomic, and metabolomic signatures into composite biomarker panels is enabling indication expansion beyond oncology into immunology and rare diseases.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists capable of integrating multi-omic data streams is bottlenecking assay development at mid-sized diagnostic firms.
- Cross-Jurisdictional Validation:Divergence between FDA and EMA evidentiary requirements forces redundant clinical studies, inflating regulatory costs for multi-regional product launches.
- Legacy LIMS Integration:Hospital laboratory information management systems require costly middleware development to accommodate next-generation sequencing data formats and reporting standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomarkers Market |
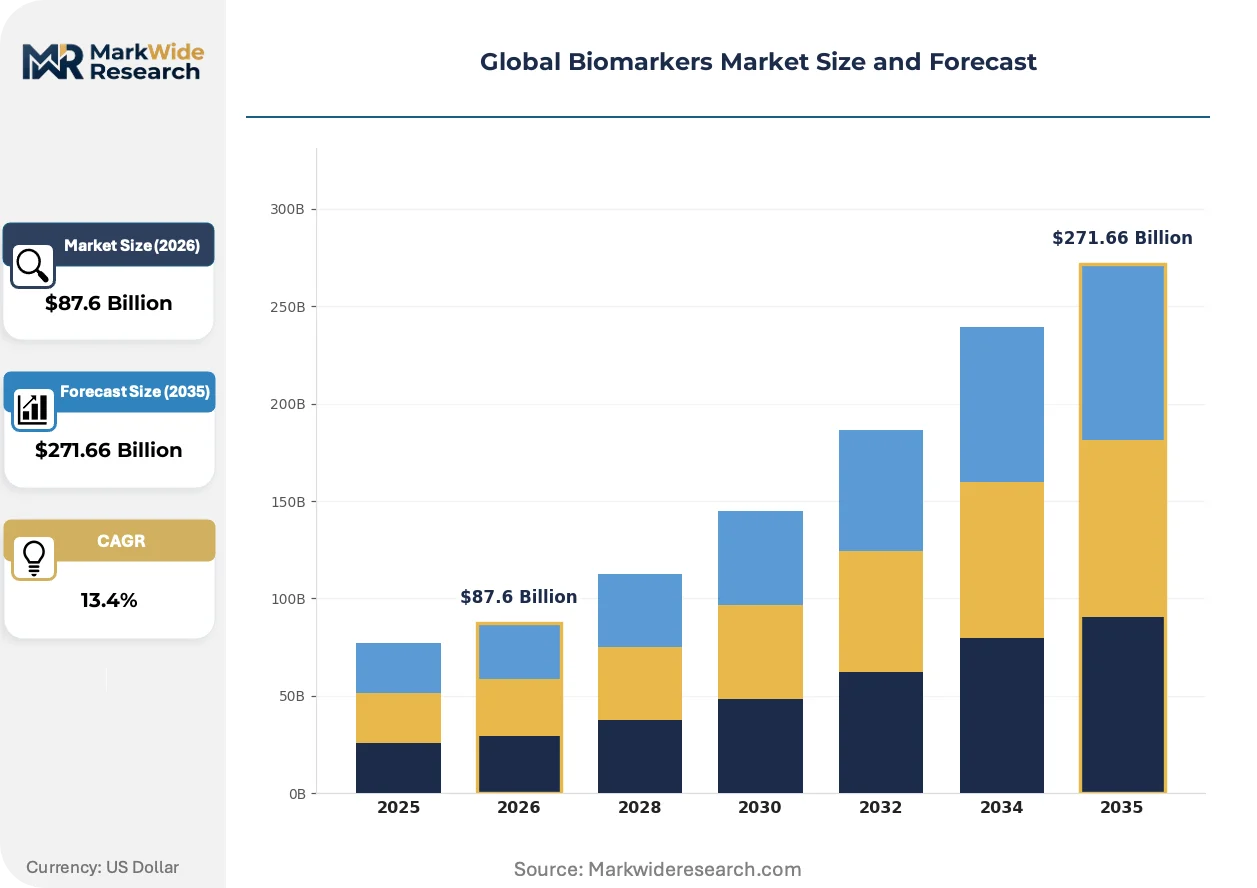
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $271.66 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services Application: Oncology, Neurology, Cardiovascular, Infectious Diseases Technology: Genomics, Proteomics, Metabolomics, Imaging End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Abbott, QIAGEN, Merck KGaA, Agilent Technologies, Bio-Rad Laboratories, Illumina Inc., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomarkers Market Emerging Trajectories
Digital pathology and artificial intelligence are restructuring how tissue-based biomarkers are quantified, while liquid biopsy platforms shift sample collection from invasive procedures to routine blood draws.
Liquid biopsy technologies using circulating tumor DNA are expanding into early-stage cancer screening and minimal residual disease monitoring. Pharmaceutical sponsors now specify ctDNA endpoints in 40% of new oncology trial protocols. This expansion is compressing the addressable market for tissue-based companion diagnostics while creating demand for ultra-sensitive detection platforms.
EMA's In Vitro Diagnostic Medical Devices Regulation is forcing analytical validation upgrades for existing biomarker assays seeking CE marking renewal. Manufacturers must resubmit clinical evidence packages under stricter performance criteria. High-complexity oncology tests face the steepest compliance burden, driving consolidation among smaller kit suppliers.
Pharmaceutical procurement departments now mandate biomarker-integrated protocol designs from phase one, displacing the traditional sequential approach where biomarker development followed drug candidate selection. Contract research organizations report that 70% of new oncology engagements require embedded diagnostic strategies. This behavioral shift is most pronounced in United States and Germany, where payer pressure for demonstrated clinical utility is strongest.
Global Biomarkers Market Segmentation
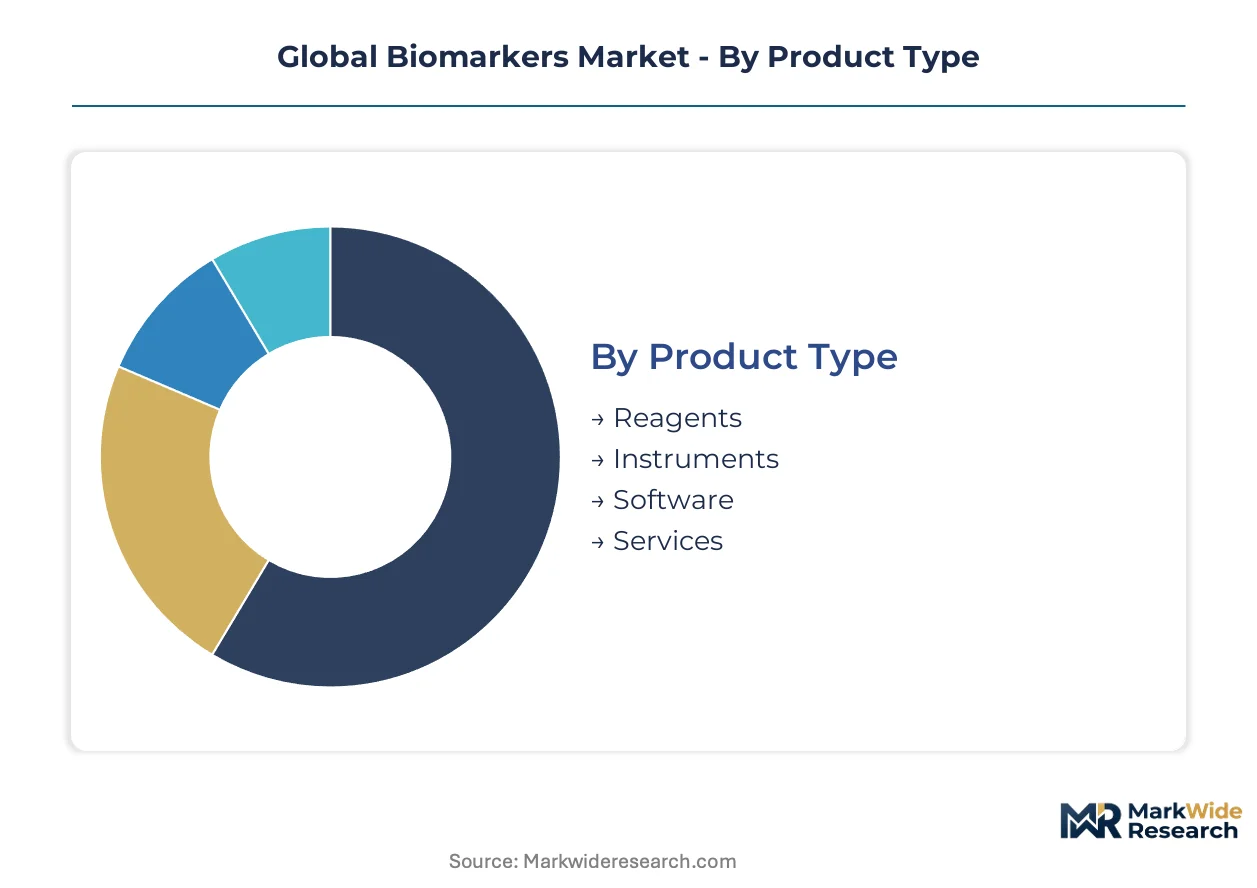
Biomarker market segmentation reveals how technology platforms, clinical applications, and procurement channels distribute value across the supply chain. Understanding these divides exposes where pricing power concentrates and where commoditization pressures emerge.
Product Type:
Technical specifications and workflow integration requirements determine how product categories capture margin across laboratory environments.
- Reagents:Specialized assay chemistries—antibodies, primers, enzymes, and detection substrates—constitute the highest recurring revenue stream in clinical workflows. Demand concentrates in oncology companion diagnostic applications across the United States and Germany, where FDA and EMA validation requirements lock laboratories into approved reagent formulations.
- Instruments:Automated platforms for immunoassay, mass spectrometry, and next-generation sequencing anchor laboratory infrastructure decisions. Procurement power has consolidated among three vertically integrated diagnostic manufacturers controlling both hardware and captive reagent supply.
- Software:Bioinformatics pipelines for multi-omic data integration and AI-assisted image analysis support interpretation workflows. Research institutes in Japan and the United States drive adoption of cloud-based analytical platforms.
- Services:Contract biomarker discovery, analytical validation, and regulatory submission support address capability gaps at mid-sized pharmaceutical developers. China's expanding CRO sector is absorbing regional demand for genomic assay development.
Mature deployment sits with Reagents. Newer deployment is concentrated in Software.
Application:
Clinical utility evidence and reimbursement status shape how therapeutic areas allocate biomarker investment.
- Oncology:Solid tumor companion diagnostics command the deepest margin pools as FDA mandates co-development of biomarker tests with targeted therapies. Patient stratification requirements in non-small cell lung cancer and colorectal indications sustain volume leadership.
- Neurology:Cerebrospinal fluid protein assays and neuroimaging biomarkers face reimbursement uncertainty despite amyloid and tau test approvals. Academic medical centers in Germany and Japan anchor current adoption while payer evidence requirements delay mainstream clinical integration.
- Cardiovascular:Metabolic profiling and protein biomarker panels for heart failure risk stratification represent an expanding frontier. The EMA's evolving qualification pathway for novel cardiovascular surrogate endpoints is accelerating pharmaceutical sponsor investment.
- Infectious Diseases:Host response biomarkers for sepsis severity and antibiotic resistance prediction address antimicrobial stewardship priorities. Hospital laboratory demand in the United States and China supports point-of-care platform development.
Commercial maturity clusters in Oncology. Steepest expansion trajectory is emerging in Cardiovascular metabolomics applications.
Technology:
Detection platform capabilities and sample throughput requirements segment technology adoption across laboratory tiers.
- Genomics:Next-generation sequencing and PCR-based assays dominate companion diagnostic volume, with circulating tumor DNA platforms displacing tissue-based testing in 40% of new oncology protocols. Regulatory clearances in the United States, Europe, and China sustain platform standardization.
- Proteomics:Mass spectrometry and immunoassay workflows support protein biomarker quantification in clinical reference laboratories. High capital intensity constrains deployment to academic medical centers and centralized diagnostics networks.
- Metabolomics:Small molecule profiling through LC-MS platforms enables surrogate endpoint discovery for cardiovascular and neurodegenerative indications where genomic markers show limited predictive value. Pharmaceutical R&D departments are internalizing these capabilities.
- Imaging:Digital pathology and radiomic signature extraction using AI-assisted quantification are restructuring tissue-based biomarker workflows. Japan's PMDA qualification program creates accelerated pathways for novel imaging assay formats.
Volume leadership belongs to Genomics. Technology investment is shifting fastest toward Metabolomics.
End User:
Procurement scale and regulatory sophistication determine how customer segments access biomarker platforms.
- Pharmaceutical Companies:Internalized biomarker discovery capabilities and mandated diagnostic-integrated trial designs from phase one concentrate the highest value demand. Sponsors in the United States and Germany specify embedded companion diagnostic strategies in 70% of new oncology engagements.
- Diagnostic Laboratories:High-throughput clinical reference labs depend on vertically integrated reagent-instrument platforms from dominant manufacturers. Reagent supply concentration creates single-source vulnerability for mid-scale operators.
- Hospitals:Point-of-care biomarker testing adoption remains limited by legacy LIMS integration costs and middleware development requirements for next-generation sequencing data formats.
- Research Institutes:Academic medical centers anchor metabolomics infrastructure deployment and multi-omics convergence research, with funding concentration in the United States, Germany, and Japan.
Revenue concentration rests with Pharmaceutical Companies. Procurement expansion is most pronounced in Diagnostic Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Genomic reagent manufacturing clusters in Basel, Massachusetts, and San Diego anchor the industry's geographic footprint. FDA companion diagnostic mandates and EMA's evolving qualification pathways concentrate high-value assay development in these regulatory-adjacent zones.
United States
Pharmaceutical sponsors now mandate biomarker-integrated trial designs from phase one, displacing sequential development approaches. FDA guidance on companion diagnostics institutionalizes co-development requirements across oncology pipelines. The Greater Boston and San Diego clusters concentrate liquid biopsy platform developers serving ctDNA endpoint specifications in 40% of new oncology protocols.
Germany
Academic medical centers in Heidelberg and Munich anchor metabolomics infrastructure for cardiovascular surrogate endpoint discovery. EMA's stricter analytical validation standards under the In Vitro Diagnostic Medical Devices Regulation force extensive clinical utility documentation. The Rhine-Main cluster concentrates high-throughput reference laboratories dependent on vertically integrated reagent-instrument platforms.
China
Hospital network expansion drives demand for molecular diagnostic platforms serving precision oncology programs. NMPA's accelerated review pathways for genomic-based assays compress time-to-market for domestic assay developers. The Yangtze River Delta cluster absorbs regional contract research demand for biomarker discovery services.
Japan
Payer pressure for demonstrated clinical utility concentrates biomarker adoption in academic medical centers and large hospital systems. PMDA's biomarker qualification program creates accelerated pathways for novel assay formats seeking reimbursable status. The Kanto region anchors multi-omics convergence research integrating proteomic, genomic, and metabolomic signatures.
Switzerland
Pharmaceutical R&D restructuring drives internalization of biomarker discovery capabilities to reduce contract research organization dependency. Swissmedic maintains alignment with EMA evidentiary standards while offering streamlined local qualification pathways. The Basel biotech corridor concentrates vertically integrated diagnostic manufacturers controlling captive reagent supply networks.
Global Biomarkers Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance capabilities and reagent supply security. Three diagnostic manufacturers dominate high-throughput clinical workflows through vertically integrated reagent-instrument platforms. Strategic archetypes include scale-driven platform consolidators, specialized sample preparation technology providers, and multi-omics convergence specialists. Competitive moves concentrate on backward integration into specialized assay chemistries and geographic expansion into China's expanding hospital network.
Among Swiss and German diagnostic conglomerates, F. Hoffmann-La Roche Ltd and Merck KGaA exemplify vertically integrated platform dominance. American life science conglomerates Thermo Fisher Scientific Inc. and Agilent Technologies occupy positions spanning research-use kits through clinical validation services. Dutch sample preparation specialist QIAGEN represents the technology-anchor archetype for downstream genomic analysis pipelines. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning across the reagent-to-software value chain.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Abbott |
| QIAGEN |
| Merck KGaA |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Illumina Inc. |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
Specialized assay reagent spot prices on the Shanghai Chemicals Index cascade through three-tier pricing structures separating FDA-validated premium formulations from research-grade standard tiers and unvalidated economy chemistries, with pharmaceutical procurement departments in the United States and Germany absorbing bundled service premiums while mid-scale laboratories face unbundled validation costs.
Pricing Analysis
Service bundling distinguishes premium tiers from stripped economy offerings. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic reagents with full analytical validation support from research-use kits with limited documentation and raw assay chemistries requiring in-house qualification. Certification level—FDA PMA versus CE-IVD versus RUO designation—drives price differentiation alongside volume scale commitments. Pricing pressure stems from pharmaceutical sponsors consolidating procurement through sole-source contracts with vertically integrated platform manufacturers. Mid-scale hospital laboratories exhibit highest price sensitivity due to unrecoverable middleware integration costs, while large reference labs leverage multi-year offtake agreements for least sensitivity.
Supply Chain Analysis
Biochemist and molecular biologist availability constraints in Basel, Massachusetts, and San Diego constrain specialized reagent manufacturing capacity expansion. Geographic supply concentration centers on Switzerland, the United States, and China for antibody production, oligonucleotide synthesis, and enzyme fermentation respectively. Raw material dependencies encompass fetal bovine serum, high-purity solvents, and rare-earth magnetic beads for nucleic acid extraction. Single-source vulnerability pervades polymerase and fluorescent dye supply chains controlled by dominant diagnostic manufacturers. Distribution runs through captive direct sales forces for high-throughput clinical customers and specialized distributors for research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's stricter In Vitro Diagnostic Medical Devices Regulation qualification requirements are forcing consolidation among smaller assay kit suppliers unable to fund 18-24 month clinical utility documentation cycles, eliminating sub-scale competitors and concentrating procurement power among vertically integrated platform holders.
For Market Incumbents: Anticipate liquid biopsy platform displacement of tissue-based companion diagnostics by securing ultra-sensitive detection technology through backward integration or exclusive licensing. Lock pharmaceutical sponsors into multi-omic data integration contracts before mid-sized competitors resolve bioinformatics talent scarcity. Prioritize reagent supply security investments in China's Yangtze River Delta to defend against NMPA-accelerated domestic competitors capturing hospital network procurement. For New Entrants and Emerging Players: The 40-60% price-point gap between FDA-cleared premium reagents and research-use economy chemistries creates entry space for mid-tier validation services targeting European mid-scale laboratories facing EMA analytical documentation burdens. Cardiovascular metabolomics applications offer lowest competitive density where genomic markers show limited predictive value. Pursue contract analytical validation partnerships with pharmaceutical R&D departments internalizing biomarker discovery capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor sample preparation technology specialists with automated nucleic acid extraction platforms in Germany and Japan where PMDA qualification programs create accelerated reimbursable pathways. Five-to-ten year viability hinges on multi-omics convergence capabilities integrating proteomic, genomic, and metabolomic signatures beyond oncology into immunology and rare diseases. Monitor ctDNA endpoint specification rates in new oncology trial protocols as the inflection signal—sustained expansion above current levels validates ultra-sensitive detection platform valuations, while plateau indicates commoditization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA guidance mandates institutionalize biomarker-integrated trial designs across pharmaceutical pipelines. |
| Metabolomics Infrastructure Acquisition | Cardiovascular surrogate endpoint discovery expands addressable market beyond oncology indications. |
| China NMPA Regulatory Submission Acceleration | Streamlined genomic assay review pathways capture hospital network expansion demand. |
| Multi-Omics Data Integration Platform Launch | AI-assisted bioinformatics pipelines resolve talent scarcity bottlenecks at mid-sized diagnostic firms. |
| Liquid Biopsy Ultra-Sensitivity Technology Investment | ctDNA endpoint specifications in oncology protocols compress tissue-based diagnostic markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with biomarker discovery executives, regulatory affairs leads at diagnostic manufacturers, hospital laboratory directors, and pharmaceutical procurement managers supplied qualitative validation. FDA 510(k) and PMA submission databases, EMA qualification pathway documentation, ClinicalTrials.gov protocol specifications, and NMPA approval registries constituted core secondary sources. Bottom-up reagent demand modeling by therapeutic area and top-down instrument installed base analysis were triangulated against pharmaceutical R&D expenditure patterns.
Data-stream reconciliation across genomic assay volume trends, mass spectrometry capital expenditure cycles, and metabolomics R&D internalization rates informed the analytical framework. Segmentation dimensions encompassed product type, application, technology platform, and end-user procurement sophistication across the analysis window. CAGRs were derived from instrument placement trajectories and reagent recurring revenue attach rates. Companion diagnostic co-development pipeline density and liquid biopsy platform technical performance specifications served as industry-specific forecast inputs.
Inputs from FDA, EMA, and NMPA regulatory databases were available through the study window; gaps in real-time pharmaceutical sponsor procurement intention data introduce uncertainty bands around contract research organization demand forecasts. Forecasts reflect assumptions regarding EMA evidentiary standard stability and China hospital network expansion continuity. Material deviation in companion diagnostic mandate enforcement intensity or NMPA review pathway duration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market