
 High-Sensitivity Cardiac Biomarker Market | 2026-2036
High-Sensitivity Cardiac Biomarker Market Size, Share, and Industry Trends Forecast 2026-2036
High-Sensitivity Cardiac Biomarker Market Analytics
Hospital procurement channels for cardiac biomarker assays is tilting toward integrated delivery networks that negotiate system-wide contracts. Roche Diagnostics leverages its installed base of cobas analyzers to sustain recurring revenue streams across major health systems. Abbott Laboratories anchors its position through vertical control over both instrument and test menu development. Siemens Healthineers competes on throughput capacity, targeting high-volume reference laboratories with automated immunoassay platforms.
High-sensitivity cardiac biomarkers are blood-based proteins—principally troponin I and T isoforms—detectable at nanogram-per-liter thresholds using chemiluminescent immunoassay methods, enabling identification of myocardial injury hours before conventional assays. Their primary purpose centers on rapid exclusion or confirmation of acute coronary events in emergency settings. Troponin testing dominates current volume due to its established clinical utility in acute coronary syndrome protocols, while point-of-care testing technology represents the fastest-expanding segment as health systems prioritize door-to-result time reduction. Microfluidics-based platforms are capturing margin pools through disposable cartridge economics and reduced sample-volume requirements.
FDA premarket review pathways for novel high-sensitivity troponin assays shape product development timelines and clinical validation requirements for US market entrants. The Clinical Laboratory Improvement Amendments, administered by CMS, govern analytical performance standards that laboratories must maintain for reimbursement eligibility. Stakeholders must monitor evolving payer coverage determinations for serial troponin testing protocols as value-based contracting models expand in cardiovascular care.
Market Dynamics
Emergency department protocols are compressing door-to-result timeframes for acute coronary syndrome diagnosis, forcing health systems to reconfigure laboratory workflows around rapid troponin testing platforms. This operational imperative is restructuring capital allocation decisions across integrated delivery networks.
Growth Catalysts
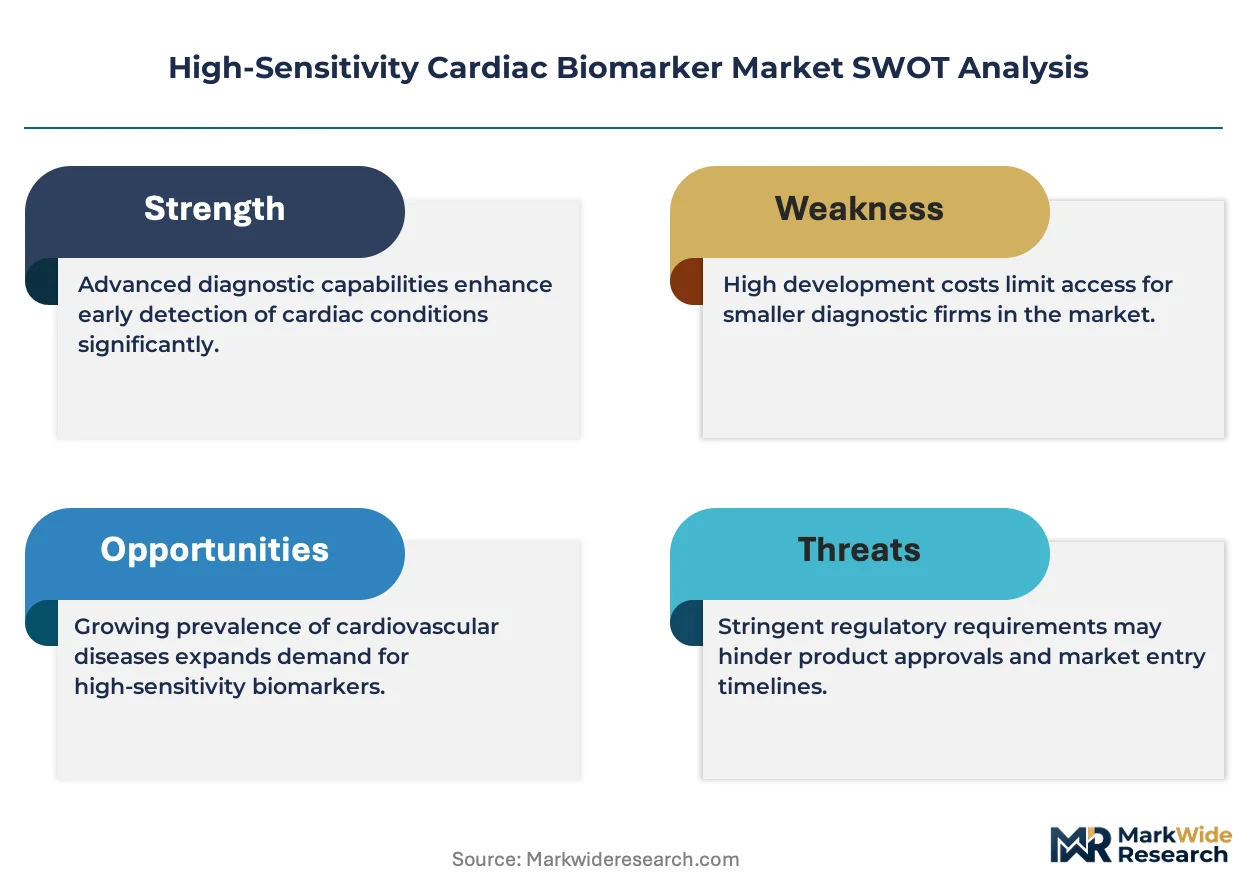
- FDA assay standardization:Evolving premarket review pathways for high-sensitivity troponin assays are accelerating clinical validation investments by diagnostic manufacturers seeking US market entry.
- Point-of-care microfluidics:Disposable cartridge platforms are capturing margin pools through reduced sample-volume requirements and decentralized testing deployment.
- Emergency medicine protocols:Hospital emergency departments are expanding adoption of rapid cardiac biomarker testing to meet door-to-result quality metrics.
Market Restraints
- Reimbursement uncertainty:CMS coverage determinations for serial troponin testing protocols remain unsettled under value-based cardiovascular care models.
- Analytical standardization gaps:Variability between troponin I and T assay platforms creates clinical interpretation friction across multi-site health systems.
- Capital intensity:Automated immunoassay platforms require substantial upfront investment, constraining adoption by independent reference laboratories.
Strategic Opportunities
- Integrated delivery networks:System-wide laboratory purchasing consolidation in the United States creates volume aggregation opportunities for platform vendors.
- AI-assisted interpretation:Machine learning algorithms converging with biomarker data streams are enabling predictive risk stratification for emergency department triage.
- CLIA-waived point-of-care expansion:Regulatory pathways for moderate-complexity testing are opening ambulatory and urgent care channels previously served by centralized labs.
Industry Challenges
- Interoperability fragmentation:Laboratory information systems require costly reconfiguration to integrate high-sensitivity assay data streams with electronic health records.
- Specialized workforce scarcity:Clinical laboratory scientists with immunoassay validation expertise command premium compensation in competitive metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Sensitivity Cardiac Biomarker Market |
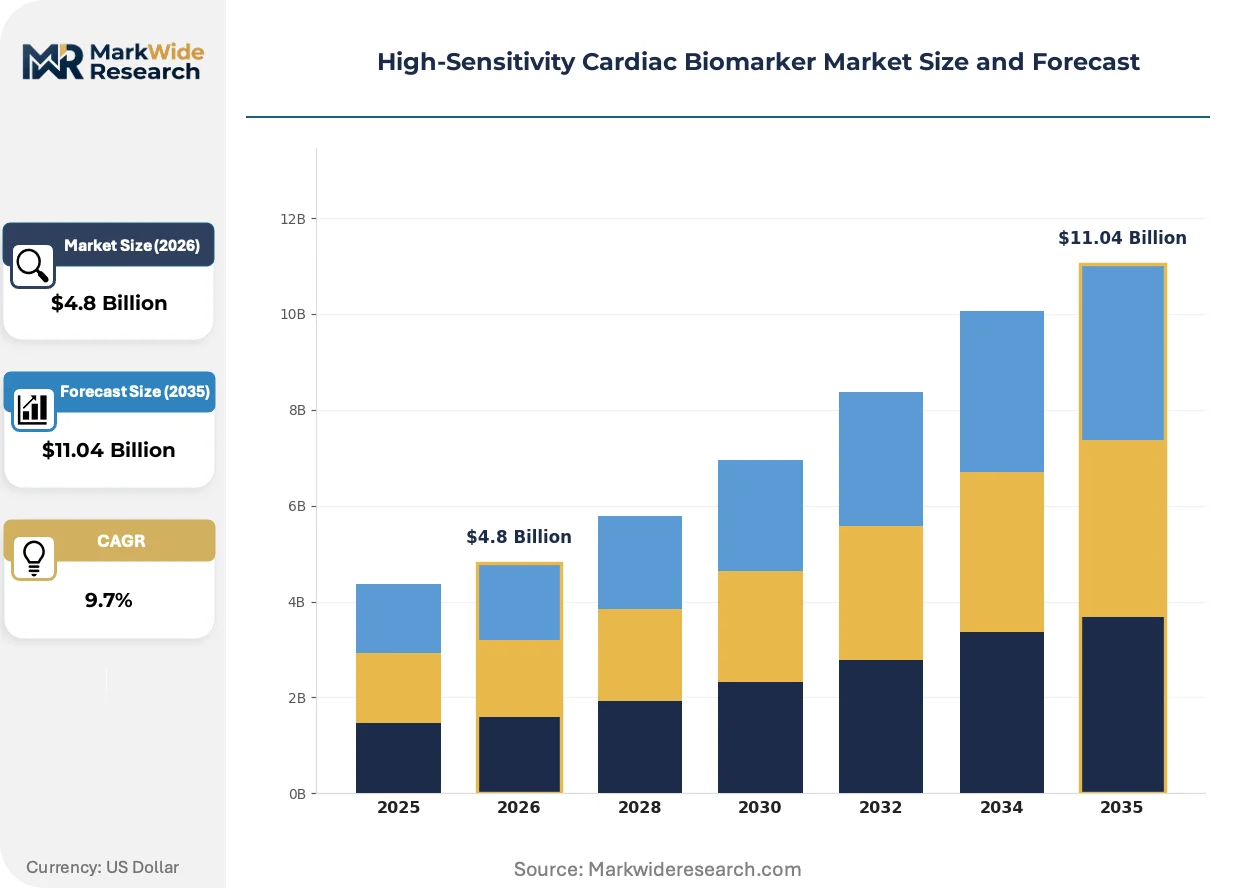
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Troponin, B-Type Natriuretic Peptide, Creatine Kinase, Myeloperoxidase Technology: ELISA, Immunoassay, Point-of-Care Testing, Microfluidics End User: Hospitals, Diagnostic Laboratories, Home Care, Research Institutions Application: Heart Failure, Acute Coronary Syndrome, Risk Stratification, Cardiovascular Rehabilitation |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Beckman Coulter, BioMérieux, Randox Laboratories, Bio-Rad Laboratories, Ortho Clinical Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Sensitivity Cardiac Biomarker Market Evolving Landscape
Diagnostic platforms are converging with digital infrastructure to compress diagnostic timelines and enable predictive cardiac risk modeling. Three developments are restructuring competitive positioning.
Microfluidic cartridge systems are miniaturizing chemiluminescent detection into handheld formats for bedside deployment. Community hospital emergency departments are adopting these platforms to bypass centralized laboratory bottlenecks during peak census periods. The technology is rendering obsolete the traditional send-out model for troponin testing in facilities under 200 beds.
FDA guidance on high-sensitivity troponin assay harmonization is mandating standardized calibrator traceability across manufacturers. This regulatory pressure is forcing revalidation investments by incumbent platform holders and erecting compliance barriers for new entrants. US-based reference laboratories are prioritizing assay menus that demonstrate metrological equivalence to predicate devices.
Health system procurement officers are consolidating vendor relationships through sole-source agreements covering instrumentation, consumables, and service contracts. Integrated delivery networks are displacing fragmented purchasing decisions previously made at individual hospital laboratories. This concentration is most visible in the southeastern United States, where multi-state systems are negotiating enterprise-wide cardiac biomarker testing contracts.
High-Sensitivity Cardiac Biomarker Market Segmentation
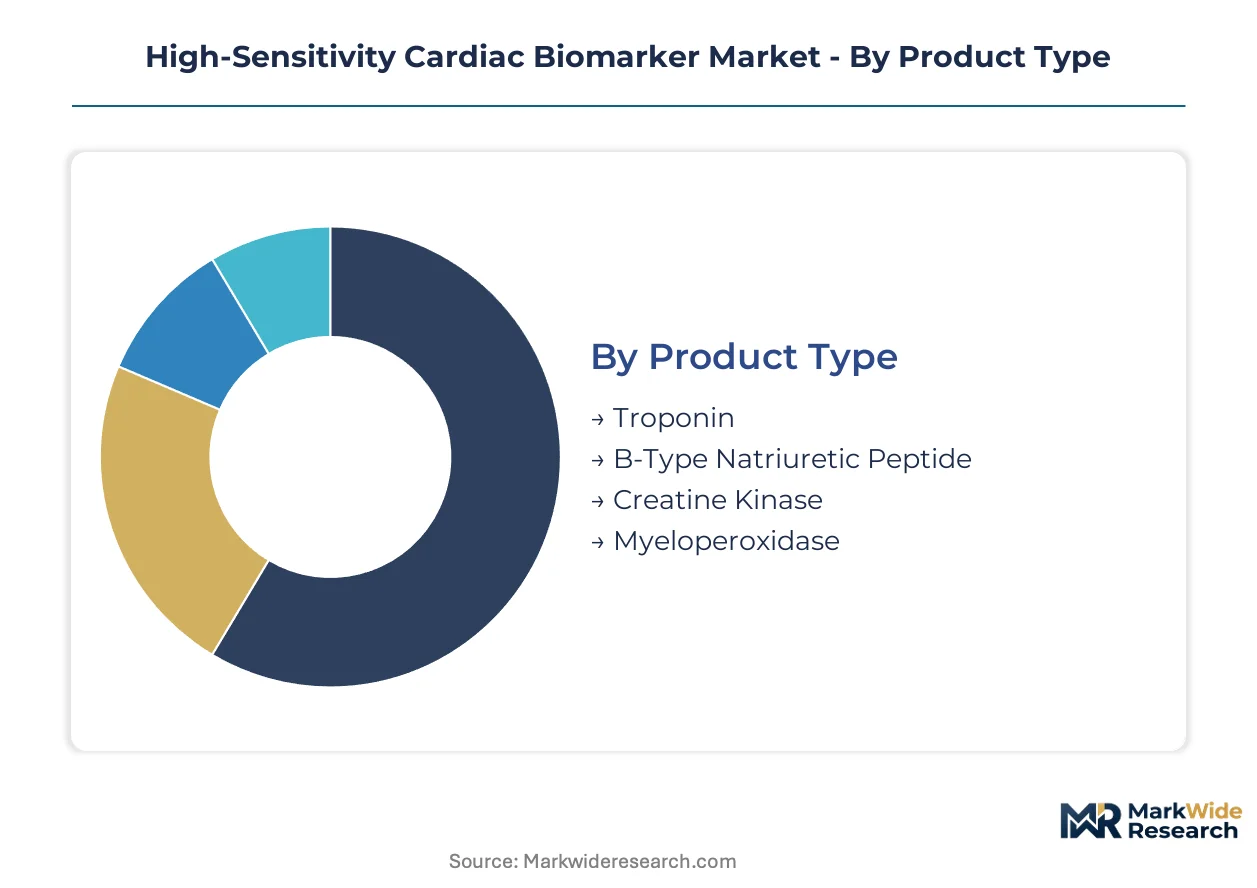
Segmentation reveals how cardiac biomarker demand fragments across testing modalities and care settings. Product chemistry, platform technology, and end-user workflow requirements create distinct competitive arenas with divergent margin structures and regulatory pathways.
Product Type:
Cost tier differentiation separates routine screening assays from specialized cardiac injury markers with premium pricing power.
- Troponin:Cardiac-specific regulatory proteins (I and T isoforms) detectable at sub-nanogram thresholds. Hospital emergency departments in the United States concentrate procurement of high-sensitivity troponin assays as door-to-result protocols compress diagnostic windows. Troponin holds installed capacity. B-Type Natriuretic Peptide is rotating up the share rankings.
- B-Type Natriuretic Peptide:Neurohormonal peptide secreted by ventricular myocardium under wall stress, quantified through competitive immunoassay formats. Integrated delivery networks are consolidating BNP testing contracts alongside troponin menus to capture heart failure diagnostic workflows. Demand concentrates in cardiology service lines managing chronic heart failure populations.
- Creatine Kinase:Cytosolic enzyme marker with established utility in myocardial infarction protocols, though displaced by troponin specificity in acute settings.
- Myeloperoxidase:Leukocyte-derived enzyme marker targeting inflammatory components of atherosclerotic plaque instability.
Troponin dominates procurement volumes. BNP is climbing the fastest as heart failure protocols expand.
Technology:
Platform maturity creates a spectrum from laboratory-validated methods to emerging point-of-care formats.
- ELISA:Enzyme-linked immunosorbent assay employing colorimetric detection with batch processing economics. Reference laboratories in Germany and Japan maintain ELISA capacity for research-grade cardiac biomarker quantification where throughput requirements justify manual workflow investment. Research institutions anchor residual demand as clinical laboratories migrate to automated alternatives.
- Immunoassay:Automated chemiluminescent platforms dominating clinical laboratory throughput with random-access processing. Siemens Healthineers and Roche Diagnostics compete on analyzer installed base across high-volume hospital laboratories seeking STAT processing capability. Immunoassay holds installed capacity. Point-of-Care Testing is rotating up the share rankings.
- Point-of-Care Testing:Bedside-deployable platforms eliminating preanalytical transport delays. Microfluidics-based cartridge systems are capturing emergency department adoption through CLIA-waived regulatory pathways.
- Microfluidics:Miniaturized fluid handling enabling sub-100 microliter sample volumes with integrated detection.
Immunoassay platforms retain laboratory dominance. Microfluidics is gaining share fastest through emergency medicine deployment.
End User:
Customer type determines purchasing authority structure and service contract complexity.
- Hospitals:Acute care facilities with emergency department and cardiology service lines driving STAT testing demand. United States integrated delivery networks are consolidating hospital laboratory purchasing through enterprise procurement offices, displacing individual facility decision-making. Hospitals hold installed capacity. Diagnostic Laboratories is rotating up the share rankings.
- Diagnostic Laboratories:Independent and health system-affiliated reference labs processing outpatient and send-out cardiac biomarker panels. Centralized laboratories in the United States are rationalizing assay menus around FDA-harmonized troponin platforms to ensure inter-site analytical equivalence.
- Home Care:Ambulatory and post-acute settings with emerging remote monitoring applications.
- Research Institutions:Academic medical centers and contract research organizations requiring specialized biomarker quantification for cardiovascular clinical trials.
Hospital systems command procurement volume. Diagnostic laboratories are expanding fastest through outpatient cardiac risk screening.
Application:
Clinical indication severity shapes testing frequency and reimbursement pathway stability.
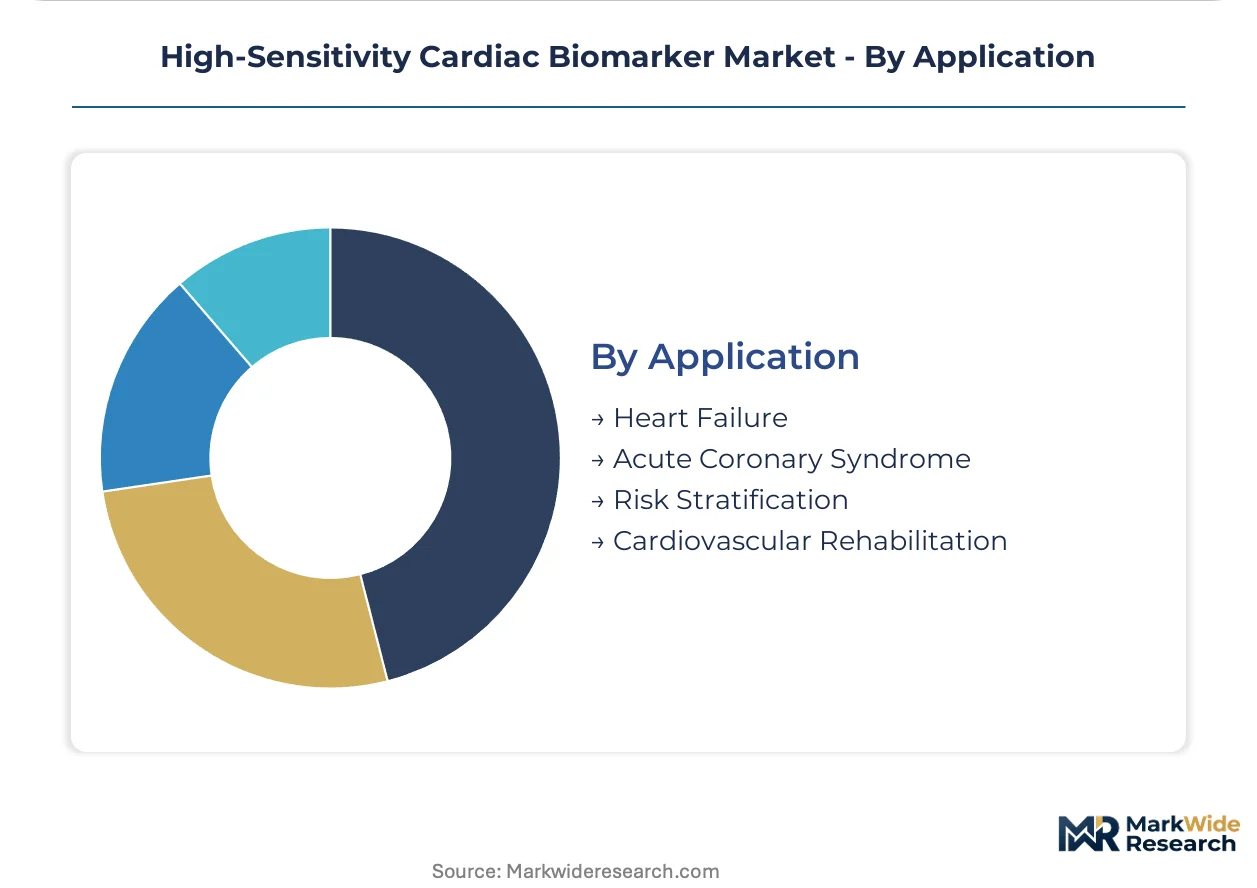
- Heart Failure:Chronic condition management requiring serial natriuretic peptide monitoring for therapeutic optimization. Cardiology clinics in the United States are embedding BNP testing into guideline-directed medical therapy protocols with quarterly surveillance intervals. Heart Failure holds installed capacity. Acute Coronary Syndrome is rotating up the share rankings.
- Acute Coronary Syndrome:Emergency presentation demanding rapid troponin serial testing for myocardial infarction rule-out. Emergency medicine protocols in the United States are compressing door-to-result timeframes below 60 minutes, restructuring laboratory capital allocation.
- Risk Stratification:Preoperative and primary prevention screening applications with emerging multi-marker algorithms.
- Cardiovascular Rehabilitation:Post-event monitoring during structured exercise and lifestyle intervention programs.
Heart failure surveillance generates recurring volume. Acute coronary syndrome protocols are expanding most quickly through emergency department quality mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review pathways for high-sensitivity troponin assays anchor strategic planning in the United States, while EMA harmonization efforts and Japan's PMDA guidelines shape validation requirements across other developed markets. Diagnostic manufacturers prioritize regulatory alignment across these three jurisdictions to secure market access.
United States
Hospital emergency departments in Texas and Florida are compressing door-to-result timeframes below 60 minutes for acute coronary syndrome protocols. CMS reimbursement determinations for serial troponin testing under value-based cardiovascular care models remain under active review. The Research Triangle Park cluster in North Carolina hosts multiple reference laboratories validating FDA-harmonized assay platforms for multi-site health system deployment.
Germany
Reference laboratories in Bavaria and Baden-Württemberg maintain high-throughput immunoassay capacity for cardiac biomarker panels serving Central European health networks. The country's national pharmaceutical regulator enforces analytical performance standards under the In-Vitro Diagnostic Medical Devices Regulation transition. Berlin-Brandenburg anchors clinical validation studies for EMA-aligned troponin assay harmonization initiatives.
Japan
Acute care hospitals in the Kanto region around Tokyo are adopting point-of-care cardiac testing to address emergency department census pressures. PMDA guidelines on high-sensitivity troponin assay approval pathways mandate local clinical trials for foreign manufacturers. The Osaka-Kobe industrial corridor concentrates diagnostic reagent production for Asia-Pacific distribution.
China
Tertiary hospitals in the Yangtze River Delta and Pearl River Delta are expanding cardiac biomarker testing menus for aging cardiovascular patient populations. NMPA regulatory pathways for imported high-sensitivity troponin assays require domestic clinical validation studies. Beijing-Tianjin-Hebei hosts national reference laboratories establishing analytical standardization for hospital network procurement.
United Kingdom
NHS England's emergency medicine quality standards are mandating troponin turnaround time metrics for acute coronary syndrome pathways. The national pharmaceutical regulator enforces post-market surveillance requirements for in-vitro diagnostic devices under retained EU law frameworks. The Oxford-Cambridge arc anchors academic medical centers developing multi-marker risk stratification algorithms for emergency department triage.
High-Sensitivity Cardiac Biomarker Market Competitive Landscape
Integrated diagnostics conglomerates and specialized immunoassay developers split the market through divergent scale and focus strategies. The vendor base concentrates around three tiers: global platform holders with installed analyzer bases, regional reagent specialists, and emerging point-of-care technology developers. Dominant competitive moves include sole-source procurement negotiations with integrated delivery networks and microfluidics platform development for decentralized testing deployment.
Among Swiss and German diagnostics conglomerates, Roche Diagnostics and Siemens Healthineers exemplify the integrated platform archetype through captive instrument and consumable ecosystems. Abbott Laboratories occupies a position representing the diversified health technology archetype with vertical control over assay development. Thermo Fisher Scientific anchors the life sciences conglomerate tier, leveraging research-grade reagent expertise toward clinical translation.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Beckman Coulter |
| BioMérieux |
| Randox Laboratories |
| Bio-Rad Laboratories |
| Ortho Clinical Diagnostics |
| Others |
Value Network & Pricing Analysis
The Research Triangle Park cluster in North Carolina anchors domestic reagent production capacity for high-sensitivity troponin assays, concentrating manufacturing scale that feeds downstream pricing power to integrated delivery networks negotiating enterprise-wide contracts. This geographic concentration of CLIA-validated production infrastructure allows platform holders to resist margin compression while independent laboratories face cartridge cost premiums.
Pricing Analysis
United States hospital systems pay 15-25% premiums over German reference laboratories for identical assay menus due to FDA harmonization compliance costs and service bundling. Three-tier pricing structure across premium, standard, and economy levels separates STAT-capable immunoassay platforms from microfluidic point-of-care cartridges and research-grade ELISA panels. Price differentiation hinges on CLIA certification tier and analyzer throughput capacity. Cost compression in the point-of-care tier is intensifying because disposable cartridge commoditization invites multi-source procurement. Independent reference laboratories exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over per-test pricing.
Supply Chain Analysis
Export control regimes restricting chemiluminescent detection component flows to Chinese diagnostic manufacturers have reshuffled supplier relationships across the Asia-Pacific region. Reagent production concentrates in the United States, Germany, and Japan, with monoclonal antibody supply anchored in Swiss and American biotechnology clusters. Manufacturing draws from specialized polymer substrates for microfluidic cartridges, rare-earth phosphors for signal detection, and recombinant protein calibrators. Single-source vulnerability in monoclonal antibody supply creates structural risk for assay standardization timelines. Distribution runs through health system GPO contracts and direct vendor agreements with reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-sensitivity cardiac biomarker market sits in early-cycle expansion as FDA harmonization mandates force platform upgrades across hospital emergency departments, creating replacement demand independent of patient volume growth.
For Market Incumbents: Pre-empt microfluidic point-of-care challengers by accelerating CLIA-waived cartridge development for ambulatory deployment before regulatory pathways mature. Lock in sole-source agreements with southeastern United States integrated delivery networks expanding through multi-state consolidation. Vertical integration into monoclonal antibody production reduces exposure to biotechnology supplier concentration. For New Entrants and Emerging Players: Establish a beachhead in community hospital emergency departments under 200 beds where centralized laboratory send-out models remain vulnerable to bedside microfluidic displacement. Target urgent care chains and freestanding emergency centers lacking in-house immunoassay capacity. Pursue white-label manufacturing partnerships with established platform holders seeking cartridge diversification without R&D investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors point-of-care microfluidics developers with FDA pre-submission pathways already initiated over mature immunoassay platform holders facing replacement revenue pressure. Long-term viability over the coming decade rests on regulatory approval velocity and health system procurement channel access. Watch CMS coverage determinations for serial troponin testing as the inflection signal for outpatient volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Harmonization Compliance | Accelerates revalidation investments by incumbent platform holders seeking predicate device equivalence. |
| Point-of-Care Microfluidics Development | Captures emergency department door-to-result mandates displacing centralized laboratory workflows. |
| Integrated Delivery Network Partnership | Consolidates fragmented hospital procurement into enterprise contracts with multi-year consumable commitments. |
| CLIA-Waived Regulatory Pathway | Opens ambulatory and urgent care channels previously served by reference laboratory send-outs. |
| AI-Assisted Interpretation Integration | Enables predictive risk stratification algorithms converging with biomarker data streams for triage optimization. |
Research Methodology
Operator-level perspectives from emergency department directors, clinical laboratory scientists, health system procurement officers, and diagnostic manufacturer product managers anchored the qualitative base for this analysis. Primary interviews with hospital purchasing committees and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS coverage determinations, hospital procurement databases, and CLIA laboratory registry data. Bottom-up assay volume estimates triangulated against top-down health system capital expenditure tracking.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning testing modality, platform technology, end-user facility type, and clinical application severity. CAGRs derived from instrument placement trajectories, consumable attach rates, and assay menu expansion patterns within integrated delivery networks. Forecast inputs incorporated emergency department quality metric adoption curves and point-of-care regulatory pathway maturation timelines.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, hospital capital expenditure cycles, or biotechnology input costs would shift the trajectory. Forecasts reflect documented assumptions regarding FDA harmonization implementation pace and health system consolidation velocity. Material shifts in CMS coverage policy for serial troponin testing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Portal Hypertension Management Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Vasculitis Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Angina Market
Cardiovascular
Heart Health Products Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Bifurcation Lesions Market
Cardiovascular
Takotsubo Syndrome Therapeutics Market
Cardiovascular
US Statin Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Stable Angina Management Market
Cardiovascular
Stroke Management Market
Cardiovascular
Peripheral Artery Disease Market