
 Heterozygous Familial Hypercholesterolemia (HEFH) Management Market | 2026-2036
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market Size, Share, and Industry Trends Forecast 2026-2036
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market Foresight
The FDA's cardiovascular outcomes trial mandate is expanding the evidentiary threshold for LDL-lowering therapies, compelling developers to invest in long-term outcome studies. Novartis AG leverages its established cardiometabolic franchise to sustain physician mindshare in the PCSK9 inhibitor class. Amgen Inc. anchors its position through manufacturing scale and competitive pricing contracts with US pharmacy benefit managers.
Heterozygous Familial Hypercholesterolemia management encompasses pharmacological and non-pharmacological interventions targeting pathologically elevated low-density lipoprotein cholesterol resulting from single-allele mutations in LDLR, APOB, or PCSK9 genes, with therapeutic goals typically set below 100 mg/dL for adults and below 130 mg/dL for children. Statins retain the largest patient volume as the foundational oral therapy, though PCSK9 inhibitors capture the fastest-growing revenue pool due to biologic pricing and subcutaneous delivery advantages. Combination therapy segments are deepening as cardiologists layer ezetimibe onto statin non-responders before escalating to injectable biologics.
The FDA, EMA, and national health technology assessment bodies shape market access through divergent evidentiary requirements for cardiovascular outcome claims. The FDA's Breakthrough Therapy designation pathway accelerates review timelines for novel mechanisms, while EMA's conditional marketing authorization permits earlier patient access pending confirmatory data. Stakeholders must monitor evolving payer evidence requirements as gene-editing therapies and oral PCSK9 small molecules advance through clinical pipelines.
Market Dynamics
The FDA's cardiovascular outcomes trial mandate is elevating evidentiary standards for LDL-lowering therapies, forcing developers to commit to multi-year outcome studies before label expansion. This structural pressure is reshaping R&D timelines and capital allocation across the cardiometabolic pipeline.
Growth Catalysts
- EMA Conditional Marketing Authorization:European early-access pathways accelerate patient availability for novel mechanisms pending confirmatory data, compressing commercialization timelines.
- PCSK9 inhibitor delivery innovation:Subcutaneous biologic administration is displacing intravenous infusion in outpatient cardiology settings, improving patient adherence metrics.
- United States payer coverage evolution:Pharmacy benefit managers are expanding prior authorization pathways for specialty biologics in familial hypercholesterolemia, reducing access friction.
Market Restraints
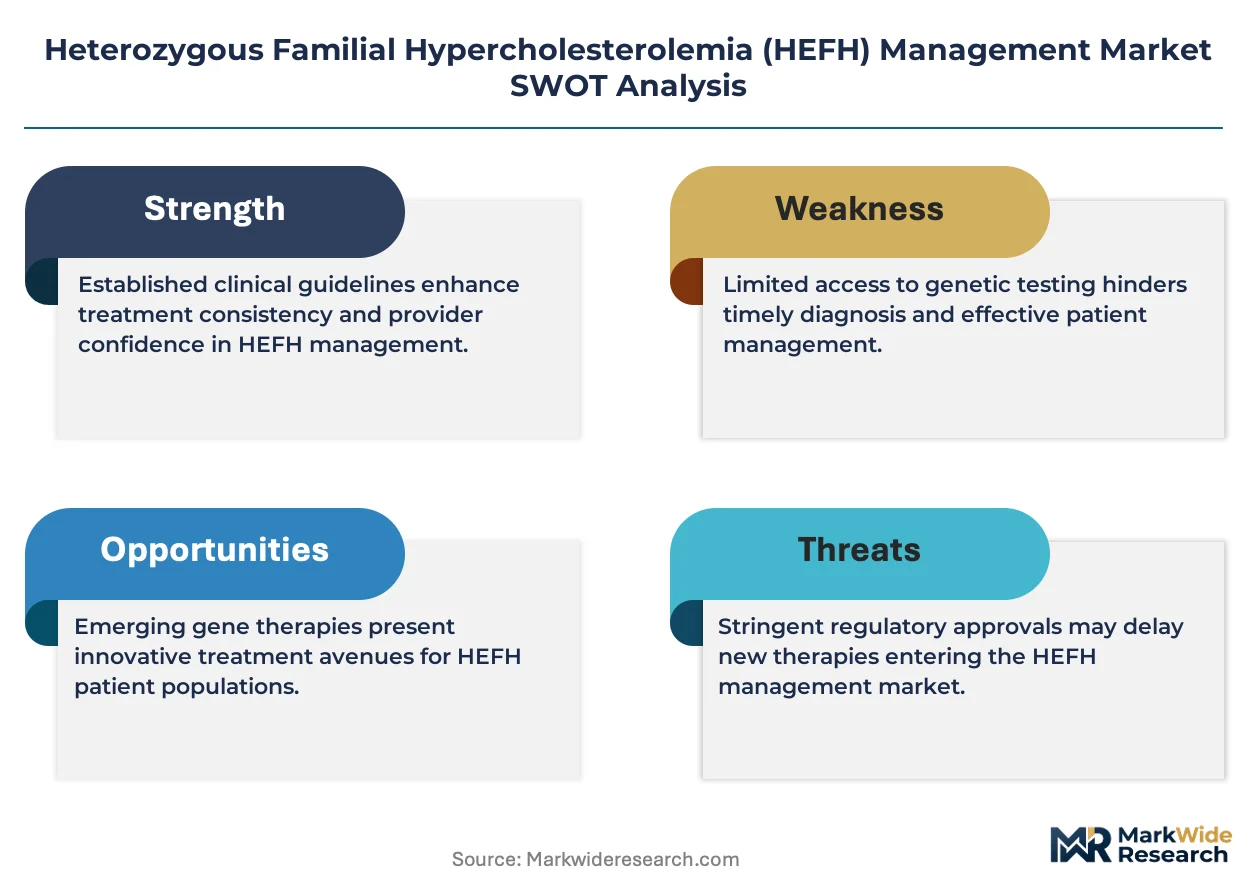
- Biologic manufacturing concentration:Single-source production facilities for monoclonal antibodies create supply vulnerability and price rigidity.
- Statin generic substitution:Low-cost atorvastatin and rosuvastatin formulations capture foundational therapy volume, compressing branded oral margins.
- FDA evidentiary burden:Mandatory cardiovascular outcome trials extend development cycles and inflate clinical costs for novel LDL-lowering mechanisms.
Strategic Opportunities
- Gene-editing pipeline advancement:CRISPR-based LDLR correction therapies target curative intent in pediatric HEFH populations.
- Oral PCSK9 small molecules:Non-biologic alternatives promise reduced cold-chain dependency and pharmacy distribution complexity.
- Combination therapy protocols:Ezetimibe-statin layering before biologic escalation creates protocol-driven demand expansion in academic medical centers.
Industry Challenges
- Lipid specialist workforce scarcity:Board-certified dyslipidemia clinicians remain concentrated in tertiary referral centers, limiting community penetration.
- Reimbursement coding fragmentation:ICD-10 specificity gaps complicate prior authorization documentation for heterozygous versus homozygous phenotypes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heterozygous Familial Hypercholesterolemia (HEFH) Management Market |
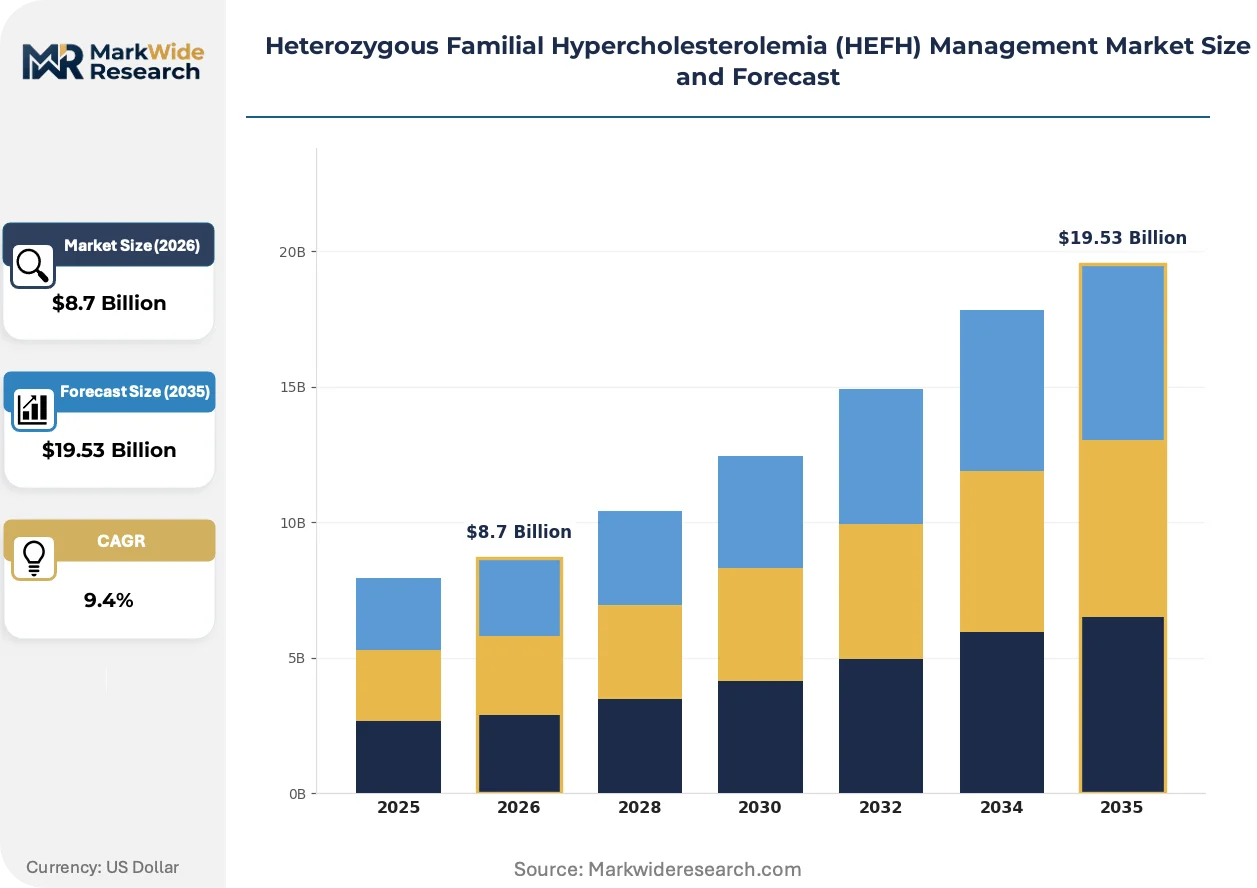
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, PCSK9 Inhibitors, Bile Acid Sequestrants, Ezetimibe Treatment Approach: Combination Therapy, Monotherapy, Lifestyle Modification, Genetic Counseling End User: Cardiologists, Primary Care Physicians, Pharmacists, Patients Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospitals, Specialty Clinics |
| Companies Covered | Novartis AG, Pfizer Inc., Amgen Inc., Esperion Therapeutics, Inc., AstraZeneca plc, Sanofi S.A., Merck & Co., Inc., AbbVie Inc., Regeneron Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market Shifts & Advancements
Cardiovascular risk reduction paradigms are shifting from LDL targets alone to integrated event-prevention frameworks, reshaping how therapies demonstrate value. This evolution is compressing traditional trial endpoints and accelerating mechanistic diversification.
Oral PCSK9 small-molecule programs are decentralizing treatment administration from infusion centers to retail pharmacy settings. Primary care physicians and community cardiologists are adopting these candidates in Phase III pipeline monitoring, anticipating reduced nursing overhead and patient travel burden. This shift is decentralizing specialty care delivery and threatening incumbent biologic infusion revenue pools.
The FDA's Breakthrough Therapy designation pathway is compressing review timelines for novel LDL-lowering mechanisms with preliminary efficacy signals. Developers are prioritizing cardiovascular outcome trial enrollment to satisfy this accelerated track, reallocating resources from expansion indications to confirmatory studies. Pediatric HEFH populations and statin-intolerant adults represent the segments most affected, with sponsors front-loading juvenile study protocols.
Patient advocacy networks are consolidating procurement influence through disease-specific foundations, redirecting formulary negotiations toward total cardiovascular risk reduction rather than LDL decrement alone. Employer-sponsored health plans and regional health systems are responding with value-based contracting pilots. This behavioral shift is most visible in United States integrated delivery networks, where pharmacy and medical benefit alignment is tightening.
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market Segmentation
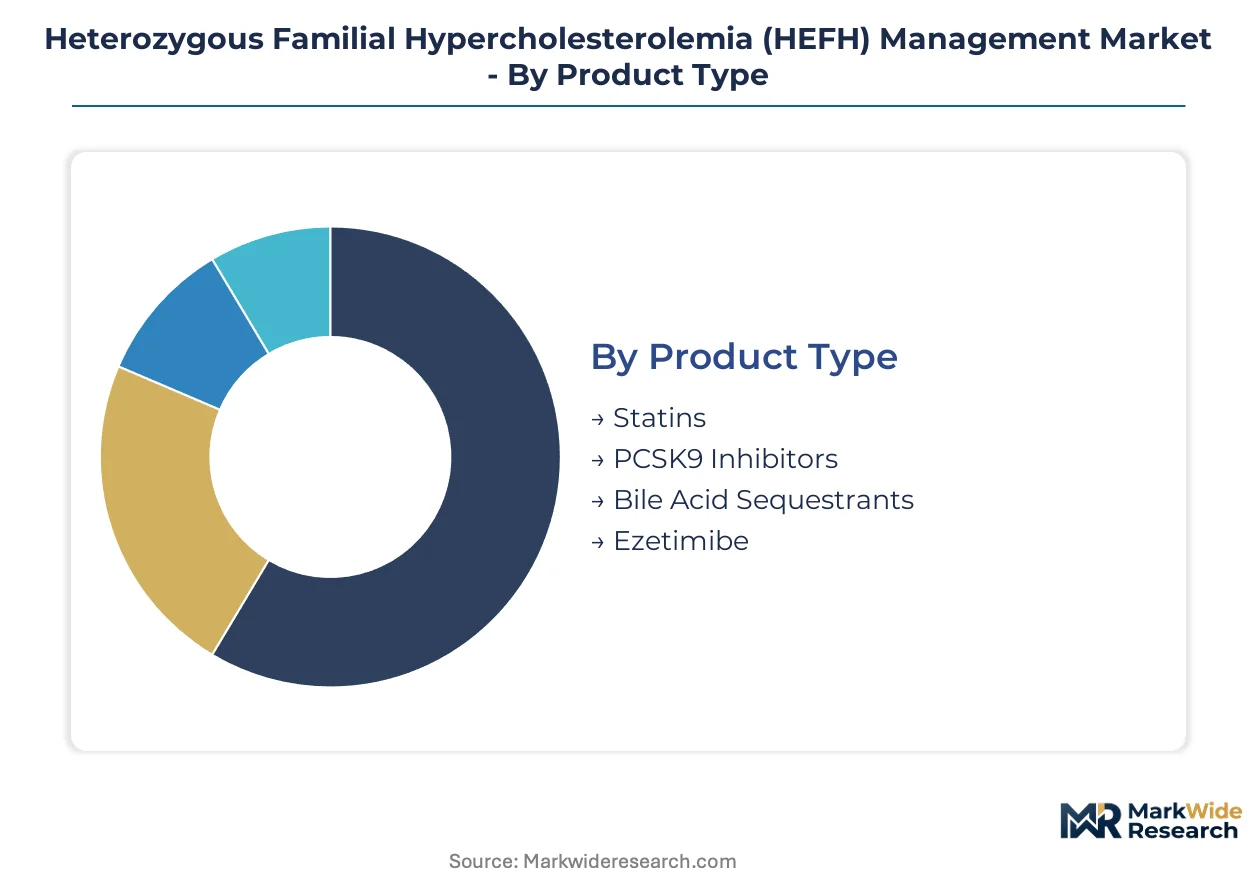
HEFH management segmentation reveals how therapeutic escalation protocols and care delivery settings fragment commercial opportunity. Product type and treatment approach categories dominate capital allocation, while distribution channel evolution determines patient access friction.
Product Type:
Upgrade cycles from oral foundational therapy to injectable biologics define patient lifetime value curves across the HEFH management spectrum.
- Statins:HMG-CoA reductase inhibitors remain the universal first-line intervention, with atorvastatin and rosuvastatin prescribing concentrated in primary care settings where generic substitution has compressed branded margins.
- PCSK9 Inhibitors:Monoclonal antibodies targeting PCSK9 protein degradation of LDL receptors command premium pricing through subcutaneous delivery; United States cardiologists in academic medical centers drive adoption as adjunct therapy for statin non-responders.
- Bile Acid Sequestrants:Resin-based cholesterol absorption blockers serve niche populations with statin intolerance.
- Ezetimibe:Intestinal cholesterol absorption inhibitor layers onto statin therapy before biologic escalation.
Statins sit at the top of the volume ranking, with PCSK9 inhibitors climbing the fastest.
Treatment Approach:
Cost tier stratification separates protocol-driven combination regimens from standalone interventions.
- Combination Therapy:Statin-ezetimibe layering followed by PCSK9 inhibitor addition represents the standard-of-care escalation pathway; United States integrated delivery networks favor this approach for high-risk cardiovascular patients.
- Monotherapy:Single-agent statin prescribing persists in pediatric populations and mild phenotypes where LDL targets remain achievable without biologic intervention.
- Lifestyle Modification:Dietary and exercise counseling accompanies all pharmacological interventions.
- Genetic Counseling:Family screening protocols cascade from index case identification.
Combination therapy commands the highest per-patient revenue, with genetic counseling gaining institutional investment fastest.
End User:
Customer type concentration in cardiology specialists versus primary care generalists shapes detailing strategies and clinical trial enrollment.
- Cardiologists:Subspecialists in preventive cardiology and lipid management prescribe PCSK9 inhibitors and manage complex combination protocols; tertiary referral centers in the United States concentrate this prescriber base.
- Primary Care Physicians:Family medicine and internal medicine practitioners initiate statin therapy and identify candidates for specialty referral.
- Pharmacists:Clinical pharmacists in specialty pharmacy settings manage prior authorization and adherence monitoring.
- Patients:Self-administration of subcutaneous biologics shifts care delivery toward home settings.
Cardiologists anchor biologic prescribing volume, with pharmacists expanding their clinical role fastest.
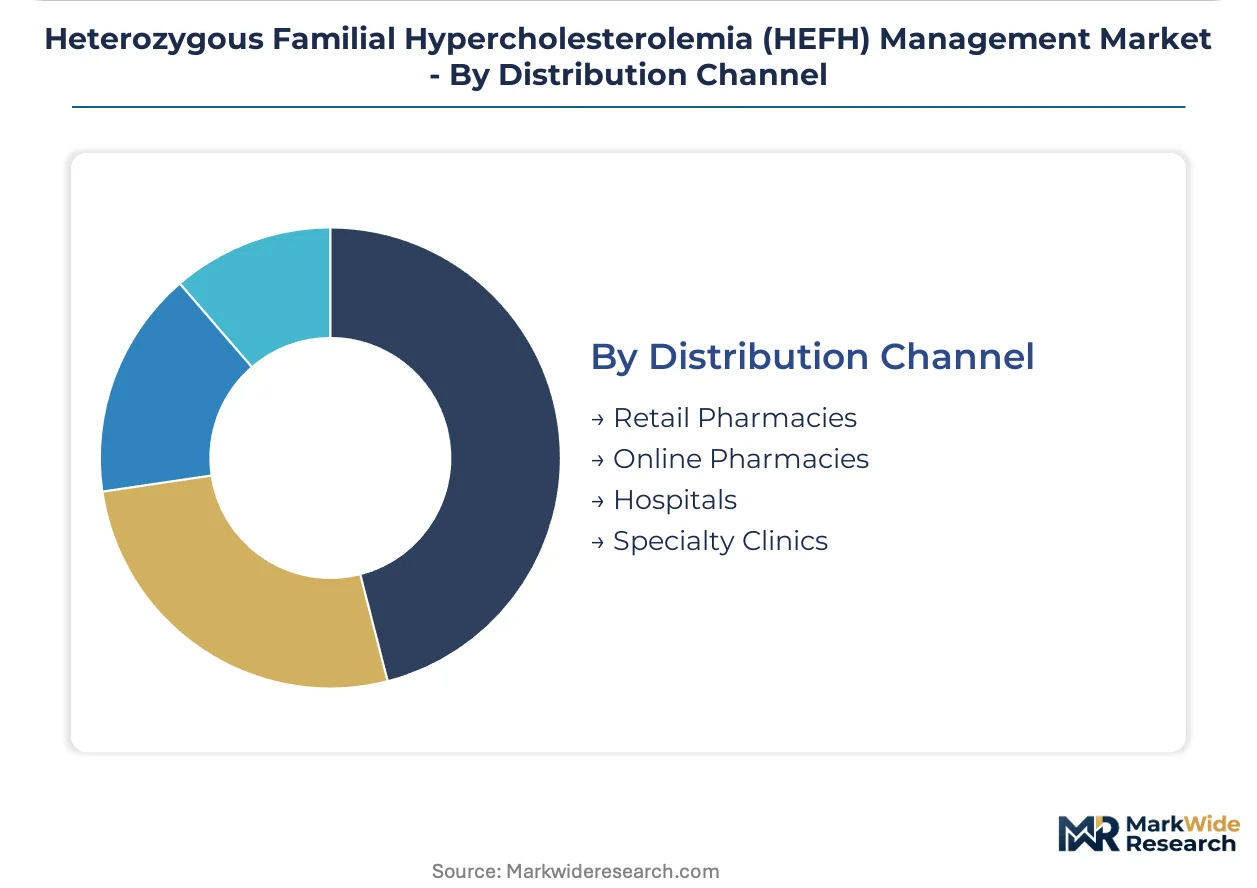
Distribution Channel:
Supply concentration in specialty pharmacy and hospital outpatient settings creates access bottlenecks for novel therapies.
- Retail Pharmacies:Community pharmacy chains dispense generic statins and ezetimibe; CVS and Walgreens locations in the United States capture foundational therapy volume.
- Online Pharmacies:Mail-order distribution reduces patient travel burden for maintenance therapy.
- Hospitals:Inpatient initiation and outpatient infusion centers manage biologic administration.
- Specialty Clinics:Dedicated lipid centers coordinate multidisciplinary care.
Retail pharmacies dominate prescription volume, with specialty clinics capturing the steepest expansion trajectory for biologic delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified lipid specialists cluster in tertiary referral centers across the United States, Germany, Japan, and Switzerland, anchoring regional prescribing patterns for biologic therapies. These concentrations determine market access velocity and prior authorization complexity for PCSK9 inhibitors.
United States
Academic medical centers in Boston, Cleveland, and Houston employ the highest density of preventive cardiologists prescribing combination statin-ezetimibe-PCSK9 protocols. The FDA's Breakthrough Therapy designation pathway accelerates review timelines for novel LDL-lowering mechanisms. CVS Caremark and Express Scripts pharmacy benefit managers in suburban Chicago and northern New Jersey negotiate value-based contracts for specialty biologics.
Germany
University hospitals in Munich and Heidelberg maintain lipidology departments that cascade genetic screening protocols through family networks. The EMA's conditional marketing authorization permits earlier patient access pending confirmatory cardiovascular outcome data. The Rhine-Ruhr metropolitan region concentrates outpatient cardiology practices adopting subcutaneous biologic administration.
Switzerland
Swissmedic's streamlined review processes attract Phase III trial sponsorship for oral PCSK9 small molecules targeting pediatric HEFH populations. Basel anchors Novartis AG's cardiometabolic franchise headquarters and clinical research operations. The Lake Geneva region hosts specialized lipid centers coordinating multidisciplinary care across French and German-speaking cantons.
Japan
PMDA's priority review system compresses approval timelines for therapies demonstrating LDL reduction in statin-intolerant patients. Tokyo's St. Luke's International Hospital and Osaka University Hospital employ dyslipidemia specialists managing complex familial phenotypes. The Kansai region's integrated delivery networks pilot combination therapy protocols before national reimbursement listing.
United Kingdom
NICE technology appraisals determine National Health Service funding for PCSK9 inhibitors in patients with established cardiovascular disease. London's Royal Brompton Hospital and Manchester University NHS Foundation Trust concentrate familial hypercholesterolemia screening programs. The Oxford-Cambridge arc hosts gene-editing research consortia advancing CRISPR-based LDLR correction therapies.
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market Competitive Landscape
Capital-heavy biologic manufacturers compete with asset-light oral small-molecule developers for cardiologist mindshare and pharmacy benefit manager formulary positioning. The market structure consolidates around monoclonal antibody producers with established manufacturing scale and emerging gene-editing platforms. Three archetypes dominate: large-cap pharmaceutical conglomerates with cardiometabolic franchises, mid-cap biotech specialists in lipidology, and gene therapy pioneers targeting curative intent. Competitive intensity centers on manufacturing capacity expansion for cold-chain biologics and strategic partnerships with integrated delivery networks for outcomes-based contracting.
Among large-cap pharmaceutical conglomerates, Novartis AG, Amgen Inc., and Pfizer Inc. occupy positions spanning the statin, PCSK9 inhibitor, and emerging oral small-molecule vectors. Novartis AG exemplifies the established cardiometabolic franchise archetype through its Swiss headquarters and European regulatory navigation capabilities. Amgen Inc. represents manufacturing-scale competitiveness with its biotechnology infrastructure and United States pharmacy benefit manager contracting relationships. Pfizer Inc. anchors the oral therapy diversification strategy as it advances non-biologic alternatives through clinical pipelines.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Amgen Inc. |
| Esperion Therapeutics, Inc. |
| AstraZeneca plc |
| Sanofi S.A. |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Regeneron Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
EMA conditional marketing authorization requirements gate qualified supply for premium-tier PCSK9 inhibitor access, compressing commercialization timelines only for manufacturers with established cold-chain infrastructure and cardiovascular outcome trial data. This regulatory filter concentrates pricing power among large-cap biologic producers while forcing mid-cap developers toward oral small-molecule strategies that bypass infusion center dependencies.
Pricing Analysis
The bundled-versus-unbundled service split separates biologic administration packages from standalone drug acquisition, with United States integrated delivery networks favoring comprehensive per-patient contracts that wrap nursing overhead into pharmacy benefit calculations. Price differentiation hinges on LDL reduction magnitude and cardiovascular outcome trial completion status, with FDA Breakthrough Therapy designation commanding measurable premium positioning. Cost compression in the statin foundational tier intensifies due to generic atorvastatin substitution, while pediatric genetic counseling services show the least price sensitivity among buyer segments.
Supply Chain Analysis
FDA current Good Manufacturing Practice certification gates monoclonal antibody production, with active pharmaceutical ingredient concentration in Switzerland, Ireland, and Singapore creating geographic clustering around Novartis and Amgen manufacturing footprints. Cold-chain logistics draw from specialized biologic distribution networks anchored in United States specialty pharmacy infrastructure, with single-source fill-finish facilities presenting acute supply vulnerability. Distribution runs through hospital outpatient infusion centers and home health nursing services for subcutaneous biologic delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in HEFH management rests on the shift from intravenous infusion to self-administered subcutaneous delivery, stripping nursing overhead from cost structures while preserving biologic pricing premiums.
For Market Incumbents: Extend manufacturing scale advantages into oral PCSK9 small-molecule co-development partnerships, securing capacity reservation agreements with United States pharmacy benefit managers before non-biologic alternatives reach Phase III completion. Anchor defensive positioning through backward integration into gene-editing platform licensing, preempting curative-intent therapies from displacing chronic administration revenue pools.
For New Entrants and Emerging Players: CRISPR-based LDLR correction technologies offer a technology-first wedge into pediatric HEFH populations currently underserved by statin tolerability limitations. Target academic medical center lipidology departments in Germany and Switzerland where EMA early-access pathways accelerate commercial proof points, deploying direct specialist detailing that bypasses primary care gatekeeper friction.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap biotech specialists with Phase II oral PCSK9 assets because FDA evidentiary burdens extend development timelines beyond standalone funding runway. The signal to watch is cardiovascular outcome trial enrollment velocity, with sponsors front-loading pediatric protocols signaling confidence in mechanistic differentiation sufficient to justify multi-year capital commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| PCSK9 Inhibitor Label Expansion | FDA cardiovascular risk reduction pathway accelerates formulary access for statin-intolerant populations. |
| Oral Small-Molecule Development | Non-biologic alternatives reduce cold-chain dependency and decentralize administration to retail pharmacy. |
| Gene-Editing Pipeline Advancement | CRISPR-based LDLR correction targets curative intent in pediatric HEFH with single-dose potential. |
| Integrated Delivery Network Contracting | Outcomes-based agreements with CVS Caremark and Express Scripts lock in biologic volume commitments. |
| Lipid Specialist Workforce Expansion | Board-certified clinician training programs address tertiary center concentration limiting community penetration. |
Research Methodology
Multiple input streams — specialist cardiologist interviews, payer formulary director consultations, regulatory affairs lead discussions, and clinical trial investigator panels — were reconciled against FDA filing databases, EMA assessment reports, ClinicalTrials.gov protocols, and United States pharmacy benefit manager coverage policies. Secondary validation drew from hospital procurement database extracts and specialty pharmacy distribution records. Bottom-up patient-flow modeling and top-down revenue reconciliation anchored segmentation-specific projections.
Historical prescription volume trajectories were cross-referenced against panel-based assumptions for PCSK9 inhibitor adoption curves, statin generic substitution rates, and gene-editing therapy penetration timelines across the projection horizon. Segmentation dimensions encompassed product type, treatment approach, end-user specialty, and distribution channel, with patient population severity and regional regulatory cluster overlays. CAGRs were derived from log-linear trend fitting adjusted for cardiovascular outcome trial readout timing and reimbursement listing decisions.
The model holds under stable FDA evidentiary requirements and EMA conditional authorization continuity; deviation in gene-editing safety signals or oral PCSK9 bioequivalence failures would shift biologic revenue persistence assumptions. Forecasts reflect documented assumptions regarding payer prior authorization relaxation and lipid specialist workforce expansion. A model refresh is warranted upon material change in cardiovascular outcomes trial results or gene therapy regulatory pathway clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Pulmonary Valve Replacement Market
Cardiovascular
Stroke Management Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Global Cardiac Tamponade Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
Ischemic Cerebral Stroke Prevention Therapeutics Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Eisenmenger Syndrome Treatment Market
Cardiovascular
Cardiovascular Enterprise Viewer Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
North America Acute Coronary Syndrome Market
Cardiovascular
Cardiac Troponin Market