
 Mexico Electrocardiograph (ECG) Market | 2026-2036
Mexico Electrocardiograph (ECG) Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Electrocardiograph (ECG) Market Insights
A widening capability gap between multinational capital deployment and local assembly capacity is reorganizing competitive dynamics in the Mexico ECG landscape. Philips Healthcare leverages its established imaging infrastructure to anchor premium system placements in tertiary hospitals. Medtronic competes through specialized cardiac rhythm management integration with diagnostic workflows. BIOMEDICA MEXICANA sustains regional channel control by navigating public procurement cycles across state health systems.
An electrocardiograph captures electrical activity of the heart through surface electrodes, typically sampling at 500 Hz with amplitude resolution of 5 microvolts for diagnostic-grade interpretation. The device serves cardiologists and emergency physicians in detecting arrhythmias, ischemic events, and conduction abnormalities. Portable ECG and wireless ECG configurations are gaining fastest traction as ambulatory and point-of-care settings expand across Mexican healthcare networks. Hospitals remain the dominant end-user segment, though home healthcare is emerging as a structurally important growth corridor driven by remote patient monitoring reimbursement evolution.
COFEPRIS maintains device registration requirements that shape import timelines and clinical validation obligations for ECG manufacturers entering Mexico. NOM standards for electrical safety and electromagnetic compatibility impose additional testing layers that filter supplier participation. The country's national pharmaceutical regulator continues aligning with international harmonization frameworks to reduce redundant certification burdens. Stakeholders must monitor pending updates to medical device vigilance reporting requirements that could reshape post-market surveillance obligations and service infrastructure investments.
Market Dynamics
INSABI framework procurement centralization is consolidating purchasing authority across Mexico's state health systems, compressing vendor negotiation cycles and elevating price transparency requirements for ECG device suppliers.
Growth Catalysts
- COFEPRIS Class II Streamlining:Reduced import clearance timelines for diagnostic devices are accelerating foreign manufacturer market entry and expanding product availability in cardiac clinics.
- Ambulatory Care Expansion:Urgent care centers across central Mexican states are deploying portable ECG configurations to capture emergency cardiac diagnostics outside hospital settings.
- Remote Patient Monitoring Reimbursement:Evolving payment structures for home healthcare services are creating pull-through demand for wireless ECG systems among private insurers.
Market Restraints
- NOM Electromagnetic Compliance Testing:Mandatory electrical safety and EMC validation layers impose additional certification costs and extend product launch timelines for imported devices.
- Capital Equipment Concentration:Tertiary hospital procurement dominance concentrates purchasing power among a limited buyer pool, compressing margin structures for mid-tier suppliers.
- Disposable Electrode Cost Volatility:Silver-silver chloride electrode material price fluctuations create input cost instability for high-volume ECG consumable suppliers.
Strategic Opportunities
- Guadalajara Medical Device Cluster:Jalisco state manufacturing incentives and established supplier ecosystems offer localization pathways to reduce import dependency and COFEPRIS registration friction.
- AI-Assisted Interpretation Convergence:Machine learning diagnostic algorithms integrated with cloud-connected ECG hardware are opening premium pricing tiers for automated arrhythmia detection.
- Direct-to-Provider Distribution:Bypassing traditional medical device distributors through e-procurement platforms is reducing channel markup and accelerating rural clinic access.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortages of certified clinical engineers capable of ECG system validation and maintenance are extending deployment timelines in public hospital networks.
- Legacy EMR Integration Complexity:Proprietary data formats from installed hospital information systems create interoperability friction for new ECG device installations.
- Post-Market Surveillance Infrastructure:Pending COFEPRIS vigilance reporting requirement updates are forcing manufacturers to pre-invest in service networks before obligation clarity emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Electrocardiograph (ECG) Market |
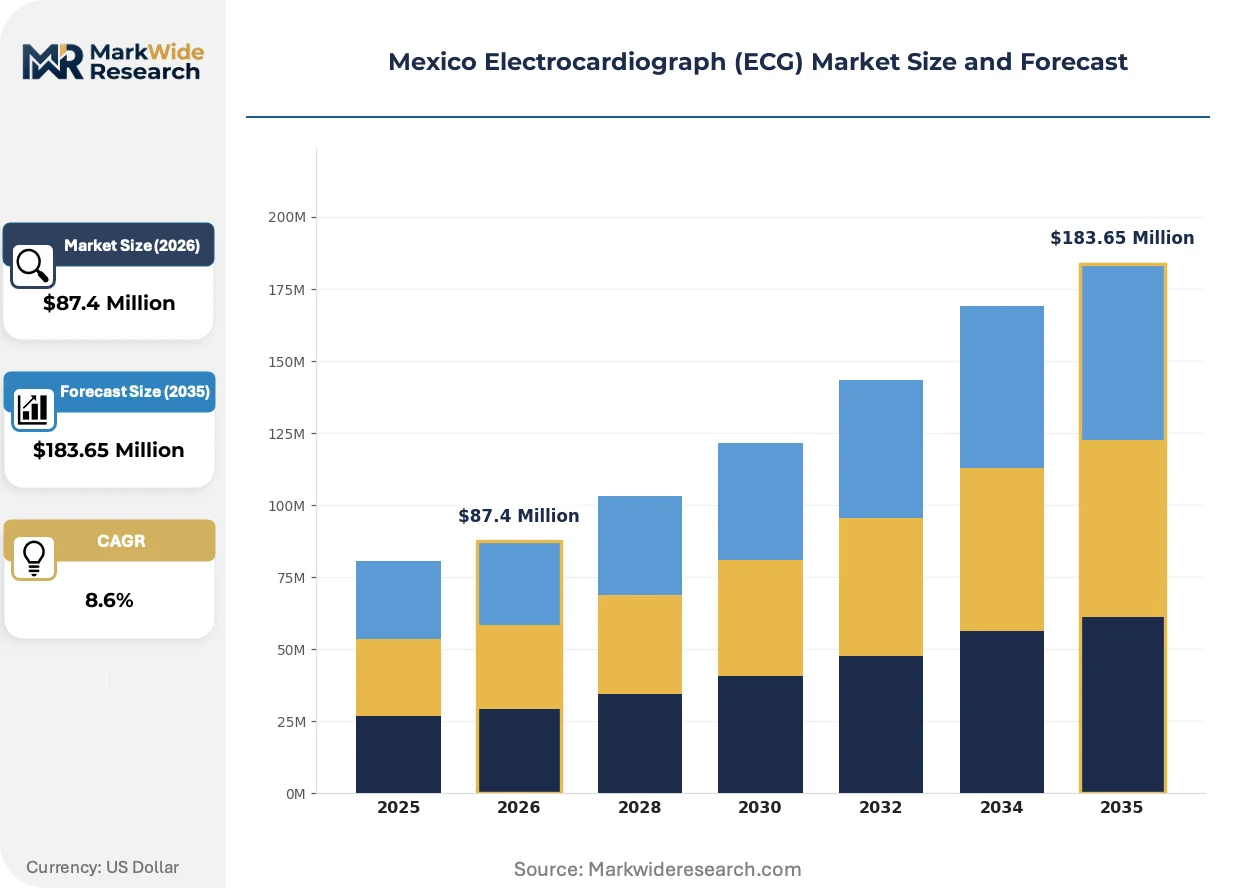
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 12-Lead ECG, Portable ECG, Wireless ECG, Holter Monitor End User: Hospitals, Cardiac Clinics, Urgent Care Centers, Home Healthcare Application: Arrhythmia Diagnosis, Ischemia Detection, Stress Testing, Continuous Monitoring Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Retail Pharmacies |
| Companies Covered | BIOMEDICA MEXICANA, Medstent, Philips Healthcare, Medtronic, GE Healthcare, Nihon Kohden, Johnson & Johnson, Schiller AG, Dragerwerk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Electrocardiograph (ECG) Market Trends and Innovations
Wireless connectivity architectures and AI-augmented diagnostic workflows are restructuring how cardiac electrical data is captured, transmitted, and interpreted across Mexican healthcare delivery settings.
Cloud-native ECG platforms with real-time telemetry capabilities are displacing standalone hardware-centric systems in tertiary hospital networks. Cardiac catheterization labs in Mexico City are piloting these architectures to enable remote specialist consultation during emergency procedures. The shift is compressing capital expenditure cycles while elevating recurring software subscription revenue streams for device vendors.
COFEPRIS alignment with international harmonization frameworks is reducing redundant certification burdens for manufacturers holding FDA or CE markings. The regulatory convergence is shortening registration timelines and enabling faster product refresh cycles in the Mexican market. Class II diagnostic device importers are restructuring quality management systems to leverage mutual recognition pathways.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisition agreements, creating discrete competitive arenas for technical support and maintenance provision. State health system purchasing bodies in central Mexico are driving this disaggregation to improve cost accountability. The pattern is most pronounced in public hospital networks where INSABI framework transparency requirements expose bundled pricing structures.
Mexico Electrocardiograph (ECG) Market Segmentation
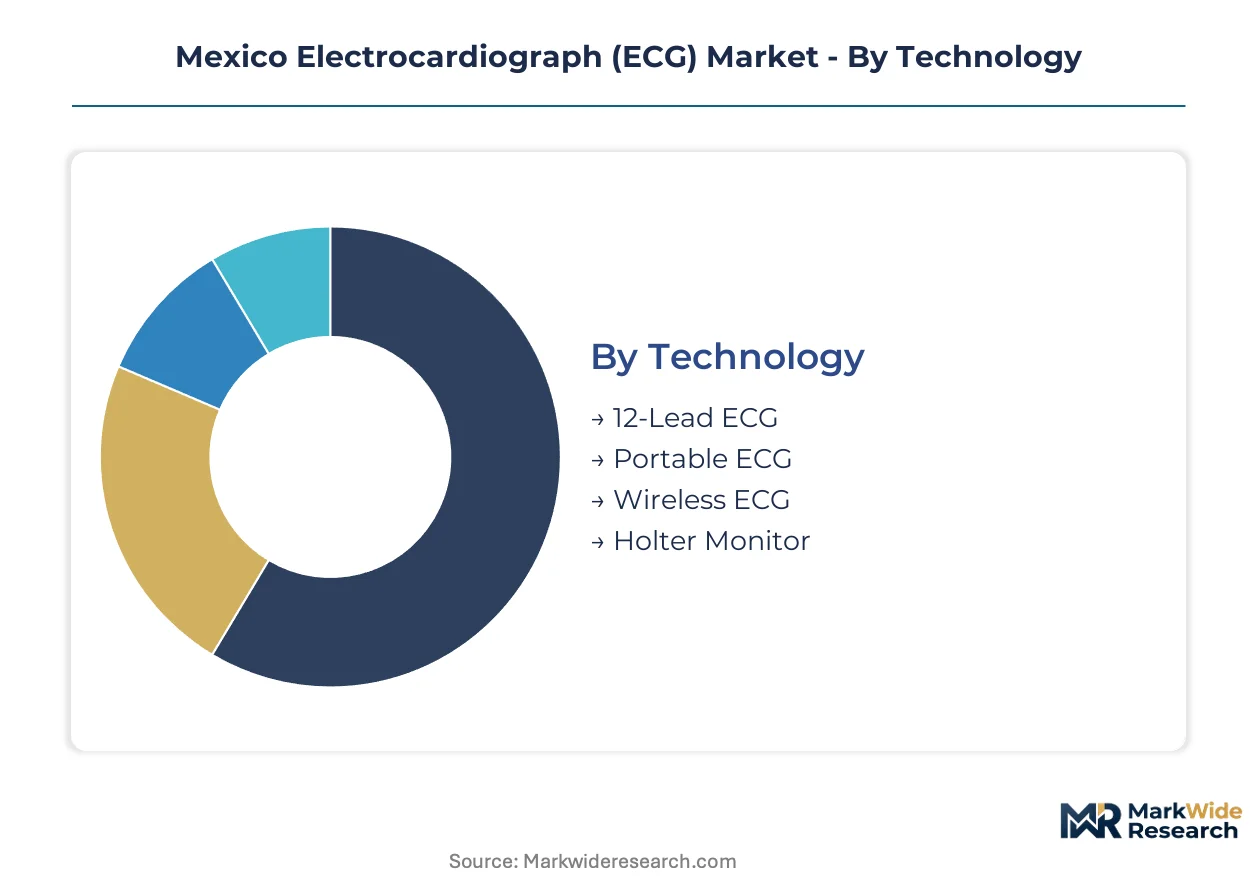
ECG market segmentation in Mexico reflects divergent regulatory pathways and procurement frameworks. COFEPRIS classification tiers and INSABI purchasing authority reshape how technology categories penetrate public versus private healthcare networks.
Technology:
COFEPRIS regulatory differentiation separates Class II diagnostic devices by risk profile and clinical validation requirements, filtering which configurations reach tertiary hospitals versus ambulatory settings.
- 12-Lead ECG:Diagnostic-grade systems with 10-electrode placement capture 12 distinct electrical vectors at 500 Hz sampling. Public hospital networks in Mexico City concentrate procurement under INSABI framework centralization, with COFEPRIS Class II clearance timelines compressing vendor selection cycles.
- Portable ECG:Battery-powered units with integrated thermal printers enable bedside and field deployment without fixed infrastructure. Urgent care centers across Jalisco state deploy these configurations to bypass catheterization lab queues during emergency presentations.
- Wireless ECG:Bluetooth-enabled devices stream data to cloud platforms for remote specialist review.
- Holter Monitor:Ambulatory systems record 24-48 hour continuous tracings for intermittent arrhythmia capture.
12-Lead ECG handles the majority of throughput; Portable ECG is the fastest mover on share.
End User:
Procurement concentration varies sharply across customer types, with public sector purchasing authority consolidating while private channels fragment.
- Hospitals:Tertiary medical centers with catheterization labs and cardiac surgery programs anchor capital equipment demand. Mexico City and Guadalajara metropolitan hospital networks drive multi-unit procurement under state health system agreements.
- Cardiac Clinics:Specialized outpatient facilities focus on diagnostic workup and rhythm management. Central Mexican states concentrate these installations where cardiologist density supports dedicated ECG service lines.
- Urgent Care Centers:Walk-in emergency facilities in Guanajuato and Querétaro deploy rapid-acquisition systems.
- Home Healthcare:Remote patient monitoring providers are expanding wireless ECG integration as private insurer reimbursement structures evolve.
Hospitals command the dominant procurement volume; Home Healthcare is climbing the fastest on expansion trajectory.
Application:
Clinical utility segmentation aligns with reimbursement coding and specialist referral pathways across Mexican healthcare networks.
- Arrhythmia Diagnosis:Detection of atrial fibrillation, ventricular tachycardia, and conduction blocks drives core ECG utilization. Cardiac electrophysiology labs in Mexico City metropolitan hospitals concentrate advanced diagnostic demand.
- Ischemia Detection:ST-segment analysis for acute coronary syndrome identification anchors emergency department protocols. Public hospital networks prioritize 12-lead acquisition speed for chest pain pathway compliance.
- Stress Testing:Exercise or pharmacological provocation with continuous ECG monitoring evaluates coronary reserve.
- Continuous Monitoring:Extended-duration recording captures episodic events outside clinical encounters.
Arrhythmia Diagnosis absorbs the highest procedure volume; Continuous Monitoring is gaining share fastest through remote care expansion.
Distribution Channel:
Channel economics diverge by customer scale and geographic penetration requirements, with digital platforms disrupting traditional medical device distribution.
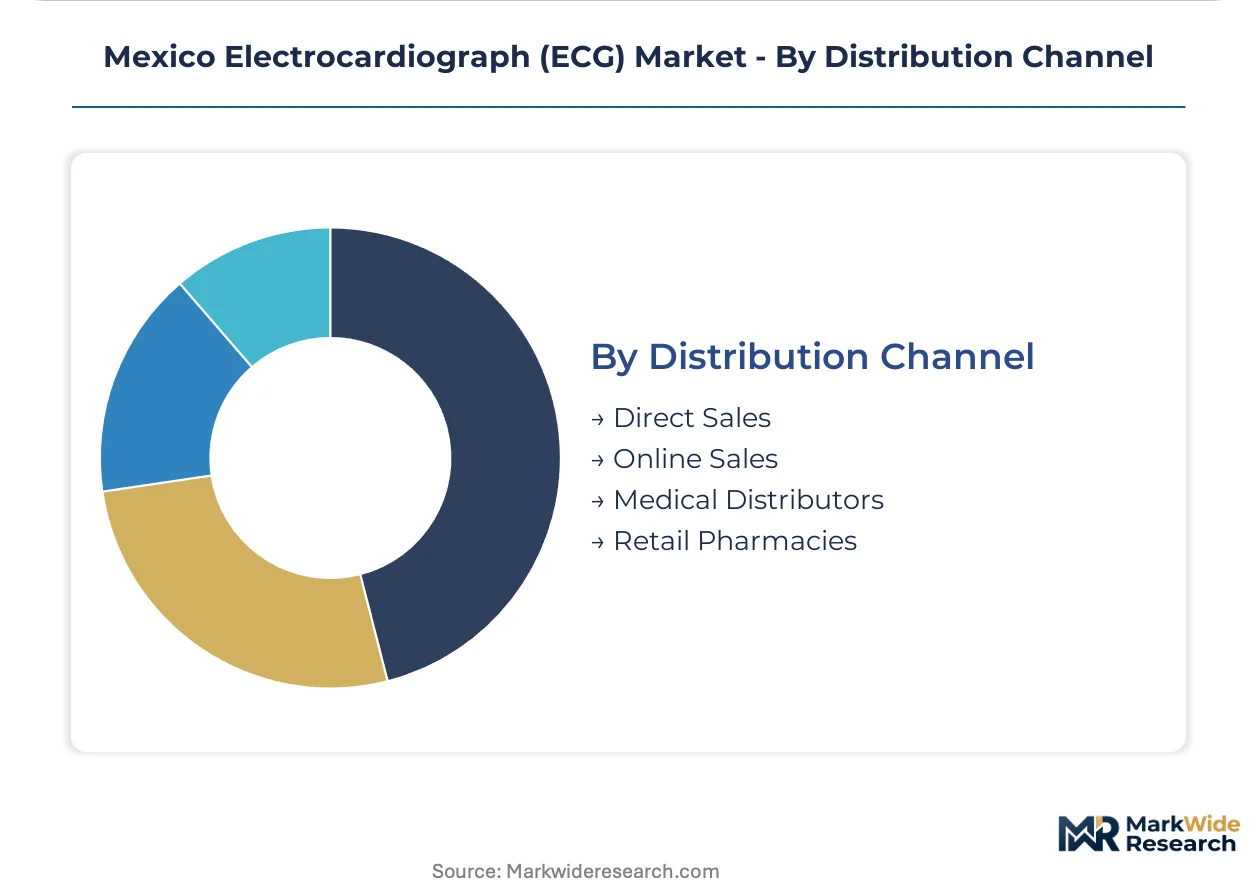
- Direct Sales:Manufacturer field organizations engage large hospital procurement committees for capital equipment placement. State health system centralization under INSABI elevates direct negotiation importance for multi-unit tenders.
- Medical Distributors:Regional warehousing and technical service networks reach secondary cities and rural clinics. Established Mexican distributors maintain relationships with biomedical engineering departments for maintenance contract attachment.
- Online Sales:E-procurement platforms enable price transparency and vendor comparison for standardized configurations.
- Retail Pharmacies:Consumer-accessible channels serve portable ECG demand for patient-directed monitoring.
Medical Distributors still handle the broadest geographic coverage; Online Sales is expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City commands premium pricing leverage against peripheral states where procurement consolidation under INSABI compresses vendor margins and elongates payment cycles.
Mexico City Metro
Public hospital networks in Cuauhtémoc and Benito Juárez boroughs drive multi-unit ECG tenders under INSABI centralization. COFEPRIS maintains its headquarters here, accelerating registration reviews for Class II diagnostic devices. Tertiary cardiac centers in the Polanco medical corridor anchor demand for 12-lead systems with catheterization lab integration.
Jalisco
Guadalajara's metropolitan hospital clusters concentrate urgent care center expansion with portable ECG deployment. State health system purchasing under INSABI frameworks elevates price transparency requirements. The Guadalajara Medical Device Cluster offers manufacturing incentives and supplier ecosystems for localization pathways.
Nuevo León
Monterrey's private hospital networks drive wireless ECG adoption for remote patient monitoring integration. State-level biomedical engineering programs at regional universities address technician scarcity. The Monterrey-Saltillo industrial corridor hosts distributor warehousing for northern Mexico coverage.
Bajío Region
Guanajuato and Querétaro urgent care centers deploy rapid-acquisition ECG systems for emergency cardiac diagnostics outside hospital settings. State health secretariats negotiate consolidated procurement under INSABI guidelines. León's medical device logistics hub serves central Mexican clinic networks.
Northern Border States
Chihuahua and Baja California maquiladora medical device assembly operations supply electrode consumables for high-volume hospital contracts. Cross-border regulatory alignment with FDA frameworks streamlines quality management for export-oriented manufacturers. Tijuana's medical device park concentrates disposable component production.
Mexico Electrocardiograph (ECG) Market Competitive Landscape
Concentration sits with multinational imaging infrastructure anchors and regional procurement specialists. Three strategic archetypes dominate: premium-tier integrated health technology conglomerates, cardiac rhythm management specialists, and local distributors navigating public procurement cycles. Competitive moves center on service contract unbundling from hardware sales and direct-to-provider e-procurement platform development.
Within the premium-tier vector, Philips Healthcare and Medtronic exemplify contrasting integration strategies. Philips occupies a position leveraging established imaging infrastructure for diagnostic workflow anchoring. Medtronic represents cardiac rhythm management convergence with electrophysiology diagnostic pathways. BIOMEDICA MEXICANA sits within the regional specialist tier, channel control through state health system procurement navigation.
| Leading Market Players |
|---|
| BIOMEDICA MEXICANA |
| Medstent |
| Philips Healthcare |
| Medtronic |
| GE Healthcare |
| Nihon Kohden |
| Johnson & Johnson |
| Schiller AG |
| Dragerwerk |
| Others |
Pricing and Supply Chain Analysis
INSABI framework multi-year procurement contracts lock in supply access for ECG device vendors while compressing price visibility across Mexico's state health systems. These centralized purchasing agreements tether foreign manufacturers to volume commitments that stabilize input forecasting but expose margin structures to transparency mandates.
Pricing Analysis
The customization-premium spread separates configured-to-order 12-lead systems with catheterization lab integration from standard portable units sold through medical distributors. A three-tier pricing structure across premium, standard, and economy levels stratifies by COFEPRIS certification tier and after-sales service bundling. Cost compression in the standard tier intensifies because INSABI centralization elevates price transparency requirements. Public hospital procurement committees demonstrate highest price sensitivity, while private cardiac clinics in Mexico City show lowest sensitivity due to workflow integration premiums.
Supply Chain Analysis
China and Malaysia anchor printed circuit board and electrode consumable production for ECG hardware assembly. Silver-silver chloride electrode manufacturing draws from Chilean and Peruvian mining supply chains, while semiconductor components for signal processing modules rest on Taiwan and South Korea fabrication capacity. Single-source vulnerability concentrates in analog front-end chipsets where FDA-cleared suppliers number fewer than five globally. Distribution runs through Guadalajara Medical Device Cluster warehousing for central Mexican coverage, with Monterrey-Saltillo logistics hubs serving northern state hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECG device manufacturers face substitution pressure from AI-augmented wearable cardiac monitors that bypass traditional diagnostic workflows entirely. Incumbents must navigate this threat by anchoring clinical validation advantages.
For Market Incumbents: Shield installed base relationships through backward integration into electrode consumable production, capturing recurring revenue streams that wearable competitors cannot replicate. Deepen service network density across Jalisco and Nuevo León before COFEPRIS vigilance reporting obligations crystallize. Channel control through biomedical engineering training programs extends switching costs for public hospital networks.
For New Entrants and Emerging Players: Differentiate on cloud-native telemetry architectures that enable remote specialist consultation during emergency procedures, a capability gap in legacy installed bases. Target urgent care center deployments in Guanajuato and Querétaro where INSABI procurement centralization remains incomplete. A direct-to-provider e-procurement platform bypasses distributor markups and accelerates rural clinic access.
For Investors and Strategic Acquirers: Regional distributors with INSABI framework navigation expertise and established biomedical engineering service contracts represent the most defensible acquisition targets. Long-term viability hinges on recurring software subscription revenue displacement of hardware-centric business models. Watch for COFEPRIS mutual recognition pathway expansion with FDA as inflection signal for accelerated product refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Acceleration | Mutual recognition with FDA and CE markings compresses market entry timelines for Class II diagnostic devices. |
| AI-Assisted Interpretation Development | Machine learning diagnostic algorithms integrated with cloud-connected hardware open premium pricing tiers. |
| Guadalajara Localization Investment | Jalisco state manufacturing incentives reduce import dependency and COFEPRIS registration friction. |
| Service Contract Unbundling | Discrete technical support competitive arenas improve cost accountability under INSABI transparency requirements. |
| Wireless ECG Platform Launch | Bluetooth-enabled devices with real-time telemetry capture remote patient monitoring reimbursement evolution. |
Research Methodology
The analysis maps 12-lead ECG, portable ECG, wireless ECG, and Holter monitor segments, each validated through cardiologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers across Mexico's central and northern states. Primary interviews with device manufacturers and distributors combined with secondary validation against COFEPRIS registration databases, INSABI procurement records, and hospital equipment census data. Bottom-up and top-down triangulation cross-checks unit shipment estimates against state health system budget allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models technology type, end-user facility tier, application clinical utility, and regional regulatory cluster segmentation dimensions. CAGRs derive from curve-fitting approaches applied to historical procurement trajectories and reimbursement policy evolution, with AI-augmented diagnostic workflow adoption curves and remote patient monitoring penetration rates as industry-specific forecast inputs.
Material uncertainties — COFEPRIS vigilance reporting requirement updates, silver electrode price volatility, and wearable cardiac monitor substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about INSABI centralization continuity and private insurer reimbursement expansion. Recalibration cycles align with material shifts in regulatory harmonization frameworks and public health system procurement authority consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Baby Thermometer Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Pathology Devices Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
North America Electrophysiology Market