
 Cannabis Packaging Market | 2026-2036
Cannabis Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Packaging Market Analysis
The cannabis packaging sector is consolidating around a sharp divergence between premium craft positioning and commodity bulk supply. Berry Global Inc. leverages its thermoforming scale to anchor high-volume plastic jar production for mass-market flower brands. KushCo Holdings differentiates through integrated sourcing of compliant child-resistant closures alongside branded accessories. Sana Packaging competes on plant-based material innovation, occupying a niche among sustainability-focused cultivators in regulated West Coast markets.
Cannabis packaging encompasses primary and secondary containment systems engineered with specific barrier properties—oxygen transmission rates below 0.1 cc per square inch per day for flower preservation, and ultraviolet-opaque substrates to prevent THC degradation—designed to maintain product potency, ensure child safety compliance, and satisfy state tracking requirements. Flexible bags lead volume due to their lightweight shipping economics and adaptability across flower, edible, and concentrate formats, while glass jars command margin pools in premium positioning where tactile quality and reuse value influence dispensary shelf appeal. Child-resistant closure specifications represent the fastest-growing technical sub-segment as jurisdictions expand mandatory testing protocols for senior-friendly yet child-impeding opening mechanisms.
State cannabis regulators in California, Colorado, and Illinois enforce packaging rules that mandate opaque materials, universal THC symbols, and batch-tracked labeling, directly shaping supplier R&D priorities and inventory configurations. The FDA maintains indirect influence through food-contact material standards for infused edible packaging, while ASTM International child-resistance testing protocols provide the functional benchmark for compliance verification across fragmented state regimes. Stakeholders must monitor pending federal rescheduling discussions and their potential to harmonize packaging standards currently Balkanized across state lines.
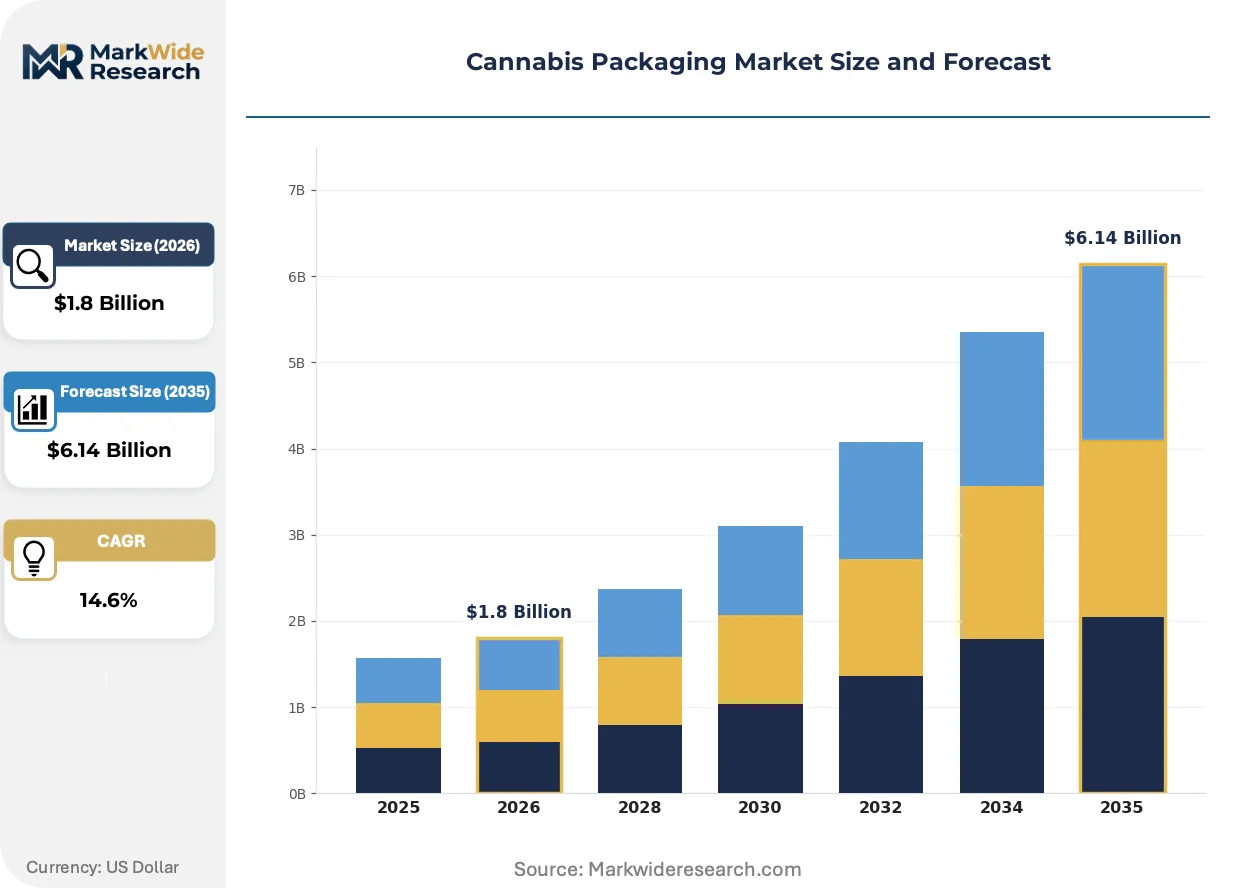
Market Dynamics
State-level compliance fragmentation is the dominant structural force, forcing packaging suppliers to maintain parallel inventory configurations across jurisdictions with incompatible child-resistance testing protocols and labeling mandates.
Growth Catalysts
- ASTM International child-resistance protocols:Mandatory adoption across California, Colorado, and Illinois creates standardized demand for certified closure mechanisms. Dispensaries now specify ASTM D3475-compliant formats as procurement baseline.
- Flower preservation specifications:Oxygen transmission rate requirements below 0.1 cc per square inch per day drive barrier material upgrades. Cultivators prioritize packaging that extends shelf stability for inventory carry.
- Multi-state operator expansion:Consolidated purchasing by vertically integrated cannabis enterprises concentrates volume with suppliers capable of multi-jurisdiction compliance documentation.
Market Restraints
- Resin cost volatility:Petroleum-based polymer feedstock pricing swings compress margin predictability for injection-molded jar producers serving mass-market flower segments.
- Single-source testing laboratory concentration:Limited certified facilities for child-resistance validation in California create bottlenecks for new packaging format approvals.
- Glass weight penalty:Premium tactile positioning of borosilicate jars incurs freight cost disadvantages versus flexible film alternatives in concentrate distribution.
Strategic Opportunities
- Federal rescheduling preparation:Harmonized interstate commerce rules would eliminate redundant state-specific packaging SKUs. Suppliers investing in modular label platforms capture first-mover advantage.
- Plant-based polymer convergence:Hemp-derived bioplastics paired with compostable barrier coatings address sustainability mandates from West Coast cultivators.
- Direct-to-consumer subscription channels:E-commerce fulfillment of compliant child-resistant formats bypasses dispensary intermediaries in jurisdictions permitting delivery.
Industry Challenges
- Child-resistance engineering talent scarcity:Packaging designers with dual expertise in senior-friendly accessibility and pediatric impeding mechanics command premium compensation.
- Batch-tracked serialization integration:State seed-to-sale tracking systems require packaging line retrofits for variable data printing at production speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Bags, Jars, Boxes, Tins Material: Glass, Plastic, Metal, Paper Closure Type: Child-Resistant, Resealable, Snap-fit, Screw Cap Design Style: Transparent, Eco-Friendly, Decorative, Standardized |
| Companies Covered | Berry Global Inc., WestRock Company, Amcor plc, KushCo Holdings, N2 Packaging Systems, Sana Packaging, Dymapak, CCL Industries Inc., Greenlane Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory technology convergence are compressing development cycles for compliant formats while sustainability specifications harden procurement criteria across licensed supply chains.
Active intelligent packaging incorporating humidity-sensing indicators is decentralizing quality assurance from laboratory testing to point-of-use verification. Premium cultivators in Colorado and California embed color-changing inserts that signal terpene degradation, shifting accountability upstream while reducing retail returns. This sensor integration is decentralizing the role of third-party lab certificates in purchase decisions.
ASTM International's expanded D3475 testing matrices for senior-friendly yet child-impeding mechanisms are tightening technical specifications for closure torque and cognitive complexity. Packaging engineers now optimize for dual-demographic accessibility under unified testing regimes. Multi-state operators in Illinois and Michigan accelerate format consolidation to reduce SKU proliferation.
Licensed dispensaries are consolidating supplier relationships around vertically integrated packaging providers capable of closure, container, and label production under single quality systems. Buyers in California now specify turnkey compliance documentation rather than component sourcing. This vendor consolidation is most visible among craft cultivators previously reliant on fragmented supplier networks.
Cannabis Packaging Market Segmentation
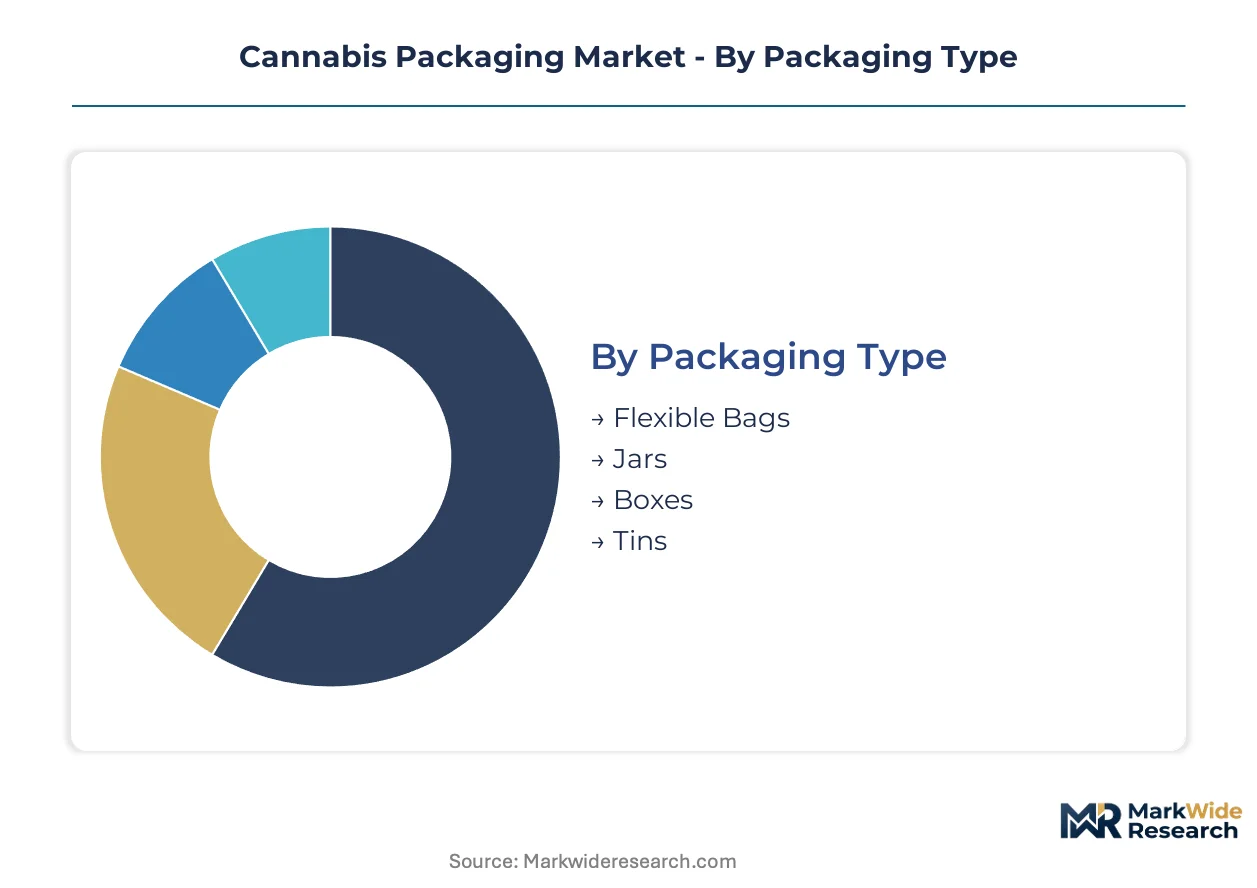
Cannabis packaging procurement cycles accelerate as cultivators replace legacy formats to meet tightening ASTM child-resistance mandates and oxygen barrier specifications. Upgrade decisions hinge on compliance documentation, freight economics, and shelf differentiation requirements across flower, edible, and concentrate applications.
Packaging Type:
Replacement cycles vary sharply by format, with flexible formats commanding shorter procurement horizons than rigid alternatives due to damage rates and compliance refresh demands.
- Flexible Bags:Multi-layer polyethylene and metallized film laminates achieve oxygen transmission rates below 0.1 cc per square inch per day for flower preservation. California and Colorado dispensaries specify these for bulk flower and pre-roll formats where shipping weight minimization overrides tactile premium positioning. The format dominates volume through adaptability across flower, edible, and concentrate SKUs.
- Jars:Injection-molded polypropylene and borosilicate glass constructions support child-resistant closure integration with senior-friendly torque specifications. Illinois multi-state operators prioritize jar procurement for premium flower positioning where reuse value and dispensary shelf presence justify freight cost premiums. ASTM D3475 certification is now mandatory for jar closure combinations in regulated markets.
- Boxes:Folding carton and rigid paperboard formats serve secondary containment and gift set applications with variable data printing for batch-tracked compliance.
- Tins:Metal slip-lid and hinge-lid constructions occupy niche positioning for edible assortments and vintage aesthetic branding in craft cultivator segments.
Flexible bags sit at the top of the volume ranking, with jars climbing the fastest as multi-state operators consolidate around premium positioning formats.
Material:
Cost tier differentiation separates commodity resin supply from certified barrier and sustainable material premiums, with procurement teams balancing unit economics against compliance documentation requirements.
- Plastic:Polypropylene and polyethylene terephthalate dominate mass-market flower through thermoforming scale and closure compatibility. Berry Global anchors high-volume production for multi-state operators with unified quality systems across California, Colorado, and Illinois facilities.
- Glass:Borosilicate and soda-lime constructions command margin pools in premium dispensary channels where tactile quality and terpene preservation justify weight penalties. Colorado craft cultivators specify amber and cobalt variants for ultraviolet opacity.
- Metal:Aluminum and tinplate formats serve concentrate containers and edible tins with barrier properties and decorative embossing capability.
- Paper:Kraft and coated paperboard support secondary packaging and sustainability positioning for West Coast cultivators with compostable certification requirements.
Plastic retains the dominant share position, while glass gains share fastest among formats serving premium shelf positioning.
Closure Type:
Application-specific torque and cognitive complexity requirements drive specification divergence between child-resistant mandates and convenience-oriented formats.
- Child-Resistant:Push-and-turn, squeeze-and-lift, and pinch-and-slide mechanisms undergo ASTM D3475 testing for senior-friendly accessibility combined with pediatric impeding performance. California regulators mandate these for all flower and edible primary containment, creating standardized demand across licensed supply chains.
- Resealable:Zipper and adhesive strip formats serve multi-dose edible and pre-roll applications where repeated access convenience outweighs child-safety priority.
- Snap-fit:Audible closure confirmation supports concentrate and accessory packaging with tamper-evident functionality.
- Screw Cap:Continuous thread and lug finishes occupy bulk oil and tincture applications with dosing precision requirements.
Child-resistant closures command the specification priority ranking, with resealable formats expanding most quickly in edible and pre-roll segments.
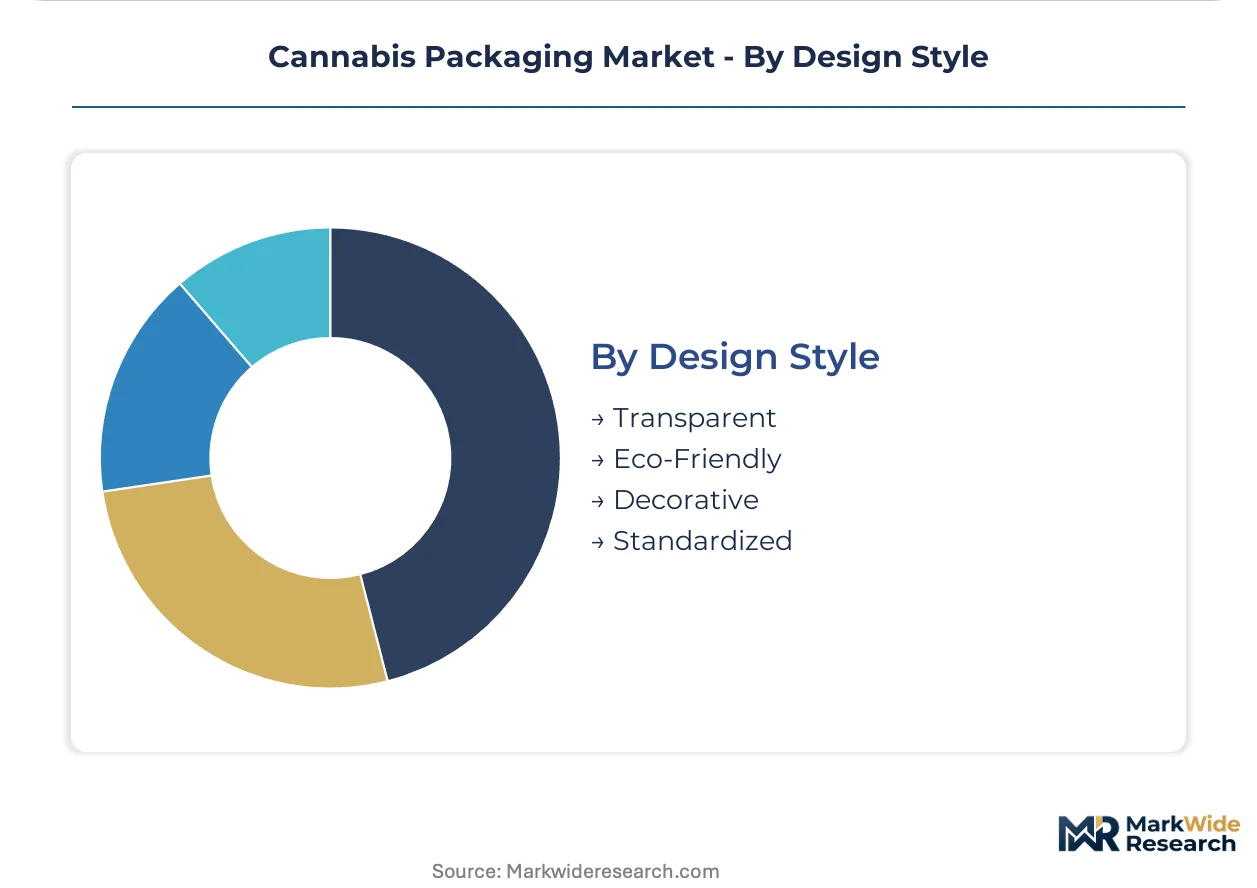
Design Style:
Customer type and geography shape aesthetic procurement, with regulatory mandates constraining transparency and sustainability preferences driving material innovation.
- Transparent:Clear PET and glass formats face regulatory restriction in California, Colorado, and Illinois where opaque mandates prevent THC degradation and minor-appealing presentation. Limited applications persist in concentrate display and inventory verification contexts.
- Eco-Friendly:Hemp-derived bioplastics, post-consumer recycled content, and compostable barrier coatings address sustainability procurement criteria from West Coast cultivators. Sana Packaging occupies this niche with plant-based material systems.
- Decorative:Embossed, foil-stamped, and custom-color formats serve gift and premium positioning where dispensary shelf differentiation commands procurement priority.
- Standardized:Universal THC symbol integration and batch-tracked variable data printing satisfy minimum compliance documentation for multi-state operator efficiency.
Standardized designs anchor procurement volume, with eco-friendly formats gaining specification momentum fastest among sustainability-mandated supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers with dual expertise in child-resistance mechanics and senior-accessibility design concentrate in jurisdictions with the most stringent ASTM testing mandates, creating talent clusters that reinforce regional competitive positioning.
United States
California, Colorado, and Illinois multi-state operators drive specification intensity for oxygen-barrier flexible films and ASTM D3475-certified closures. State seed-to-sale tracking systems mandate batch-tracked variable data printing on all primary containment. Los Angeles and Denver anchor the highest concentration of compliant packaging fabricators serving licensed dispensaries.
Canada
Health Canada regulations for cannabis packaging emphasize child-resistant formats with plain packaging restrictions that limit brand differentiation. Licensed producers prioritize odor-proof barrier properties for dried flower and pre-roll formats. Toronto and Vancouver host the primary supplier networks serving provincial distribution monopolies.
Germany
The BfArM medical cannabis framework drives demand for pharmaceutical-grade primary containment with tamper-evident functionality. Importers specify EU-compliant barrier materials for THC stability during extended distribution cycles. Berlin and Hamburg concentrate the import logistics and secondary packaging operations serving the pharmacy channel.
Netherlands
The Office of Medicinal Cannabis maintains strict packaging protocols for domestic cultivation and export authorization. Dutch suppliers specialize in serialized compliance documentation for intra-EU distribution. The Randstad region houses contract packagers serving German and Italian medical markets.
Australia
The TGA medical cannabis access scheme generates demand for child-resistant formats with stability data supporting tropical climate distribution. Importers specify high-barrier laminates for extended shelf life requirements. Sydney and Melbourne anchor the packaging specification and distribution infrastructure serving Oceania markets.
Cannabis Packaging Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered competitive strata. Thermoforming scale operators anchor high-volume supply for mass-market flower segments, while specialized engineering firms capture premium positioning through ASTM certification depth. The market structures around three archetypes: diversified packaging conglomerates with cannabis-dedicated divisions, pure-play cannabis packaging specialists, and sustainability-focused material innovators. Competitive moves concentrate on multi-jurisdiction compliance documentation capabilities and backward integration into closure manufacturing.
Within the diversified conglomerate tier, Berry Global Inc. and WestRock Company exemplify scale-driven positioning through unified quality systems across multiple production facilities. Among cannabis-specialist operators, KushCo Holdings occupies a position integrating compliant closure sourcing with branded accessories, while Sana Packaging anchors the plant-based material innovation vector serving sustainability-mandated West Coast cultivators.
| Leading Market Players |
|---|
| Berry Global Inc. |
| WestRock Company |
| Amcor plc |
| KushCo Holdings |
| N2 Packaging Systems |
| Sana Packaging |
| Dymapak |
| CCL Industries Inc. |
| Greenlane Holdings |
| Others |
Supply Flow & Price Mechanics
ASTM D3475 certification mandates from California, Colorado, and Illinois regulators force packaging suppliers to absorb testing laboratory bottlenecks and specialized engineering talent premiums, compressing margins on standardized formats while creating pricing power for turnkey compliance providers.
Pricing Analysis
Bundle-unbundle service splits separate component suppliers from turnkey documentation providers. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and closure engineering complexity. Cost compression in commodity resin formats intensifies because petroleum feedstock volatility transfers directly to injection-molded jar producers. Multi-state operators show lowest price sensitivity for ASTM-validated closure-container combinations, while craft cultivators in fragmented supplier networks face highest procurement cost pressure.
Supply Chain Analysis
Freight cost penalties for borosilicate glass jar distribution concentrate procurement decisions on lightweight flexible film alternatives for bulk flower segments. Manufacturing gravity centers on China for metallized barrier films, Germany for pharmaceutical-grade closure mechanisms, and the United States for thermoformed polypropylene containers. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks, Canadian forest products for paperboard secondary packaging, and Brazilian sugarcane for plant-based polymer innovators. Single-source vulnerability sits with California's limited certified child-resistance testing facilities. Distribution runs through licensed dispensary intermediaries in most jurisdictions, with direct-to-consumer channels emerging where state delivery permissions allow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as multi-state operators consolidate procurement around ASTM-validated, oxygen-barrier formats with integrated compliance documentation.
For Market Incumbents: Anchor defensive positioning through captive closure manufacturing capacity and multi-jurisdiction quality system unification. Berry Global-scale thermoforming operators should deepen backward integration into child-resistant mechanism production before testing laboratory bottlenecks worsen. Certification investment in emerging state markets creates switching cost barriers against mid-tier competitors. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription fulfillment models in jurisdictions permitting delivery bypass of dispensary intermediaries. White-space opportunity concentrates in plant-based material systems for West Coast sustainability-mandated cultivators and modular label platforms preparing for federal rescheduling harmonization. Go-to-market angle should emphasize batch-tracked serialization integration at production speed. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized ASTM certification engineering firms and plant-based material innovators possessing scalable barrier coating technology. Long-term viability favors suppliers positioned for interstate commerce harmonization rather than state-specific SKU proliferation. Acquisition target archetype: mid-scale fabricators with dual expertise in child-resistance mechanics and senior-accessibility design. Signal to watch: federal rescheduling legislative momentum as inflection indicator for modular platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM Certification Depth Expansion | Multi-state operators in Illinois and Michigan now specify D3475 compliance as non-negotiable procurement baseline. |
| Plant-Based Material Scale-Up | Sana Packaging-type innovators capture sustainability procurement mandates from California and Colorado craft cultivators. |
| Modular Label Platform Development | Variable data printing capabilities align with seed-to-sale tracking requirements across fragmented state regimes. |
| Direct-to-Consumer Channel Launch | E-commerce fulfillment bypasses dispensary intermediaries where state delivery permissions exist. |
| Backward Integration into Closure Manufacturing | In-house production of child-resistant mechanisms insulates against testing laboratory bottlenecks and talent scarcity. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging procurement managers at multi-state operators, compliance officers at California and Colorado licensed dispensaries, ASTM testing laboratory directors, and plant-based material R&D leads with secondary validation against state regulatory filings, customs trade data for barrier film imports, and SEC disclosures from diversified packaging conglomerates. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates.
Segment-weighting approaches modeled packaging type, material grade tier, closure certification level, and regional regulatory cluster complexity across the projection horizon. CAGRs derived from historical procurement cycle analysis and forward-looking compliance mandate timelines. Industry-specific forecast inputs incorporated resin cost volatility indices and ASTM testing capacity expansion announcements.
Several conditions sit outside the modeled scope, including federal rescheduling legislative outcomes, breakthrough barrier material science discoveries, and sudden state regulatory reversals. Forecasts reflect documented assumptions about compliance mandate adoption curves and testing laboratory capacity growth. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Fashion Accessories Packaging Market