
 Custom Inserts Market | 2026-2036
Custom Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Inserts Market Outlook
Medical-grade specification tier is collapsing into the broader consumer wellness channel as OTC orthotics absorb clinical performance standards. Bauerfeind leverages its rehabilitation heritage to bridge prescription and retail segments. Superfeet Worldwide anchors the outdoor and athletic specialty channel with biomechanically engineered arch profiles. Vionic differentiates through podiatrist-designed footwear integration that extends insert credibility beyond standalone sales.
Custom inserts are engineered components—typically fabricated from EVA foam, thermoplastic polyurethane, or carbon fiber composites through CAD-milled or vacuum-formed processes—that conform to specific anatomical or object geometries to redistribute pressure, stabilize alignment, or protect sensitive surfaces during transit or use. Foam and plastic insert types dominate current production volume, though fully custom and prototype customization levels command disproportionate margin pools due to specialized tooling requirements and shorter production runs. The electronics and healthcare industries generate the most structurally complex demand, with automotive packaging applications growing fastest as EV battery modules require increasingly precise transit protection.
FDA oversight of medical device classifications and the EU MDR framework shape product claims and market access for therapeutic-grade inserts, while REACH compliance governs material composition across European supply chains. Stakeholders must monitor how evolving ESG disclosure rules under CSRD reshape supplier qualification criteria for brand-owner contracts. The decisive question facing participants is whether to build in-house digital foot-scanning capabilities or partner with specialized measurement platforms.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is compressing material choice sets while CAD-milled fabrication is collapsing lead times for fully custom geometries, forcing producers to requalify supply chains simultaneously.
Growth Catalysts
- EU MDR framework:Therapeutic-grade classification pathways are expanding reimbursable indications for podiatric inserts across Germany, France, and Italy.
- EVA foam-to-TPU substitution:Thermoplastic polyurethane formulations are absorbing medical-grade specification tiers previously reserved for carbon fiber composites.
- Germany's precision manufacturing corridor:Concentrated tooling expertise in Bavaria and Baden-Württemberg is shortening prototype-to-production cycles for vacuum-formed orthotics.
Market Restraints
- REACH compliance costs:ECHA substance restrictions on isocyanates and plasticizers are elevating formulation qualification expenses for European producers.
- Carbon fiber supply concentration:Toray, Hexcel, and SGL Carbon control 70% of aerospace-grade precursor output, creating input bottlenecks for high-performance inserts.
- Digital scanning fragmentation:Incompatible file formats between foot-scanning platforms and CAD/CAM systems force redundant data translation steps.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for medical device manufacturing are attracting insert fabricators to Gujarat and Karnataka industrial corridors.
- CSRD disclosure mandates:EU corporate sustainability reporting requirements are creating supplier qualification premiums for ESG-documented foam producers.
- At-home 3D scanning convergence:Smartphone photogrammetry paired with cloud-based CAD processing is opening direct-to-consumer channels previously blocked by clinical gatekeepers.
Industry Challenges
- Biomechanist talent scarcity:Qualified gait analysts capable of translating scan data into corrective geometries are concentrated in academic medical centers, not manufacturing facilities.
- ISO 13485 certification timelines:Medical device quality management system audits are extending 14-18 months for first-time applicants, delaying market access for therapeutic claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Inserts Market |
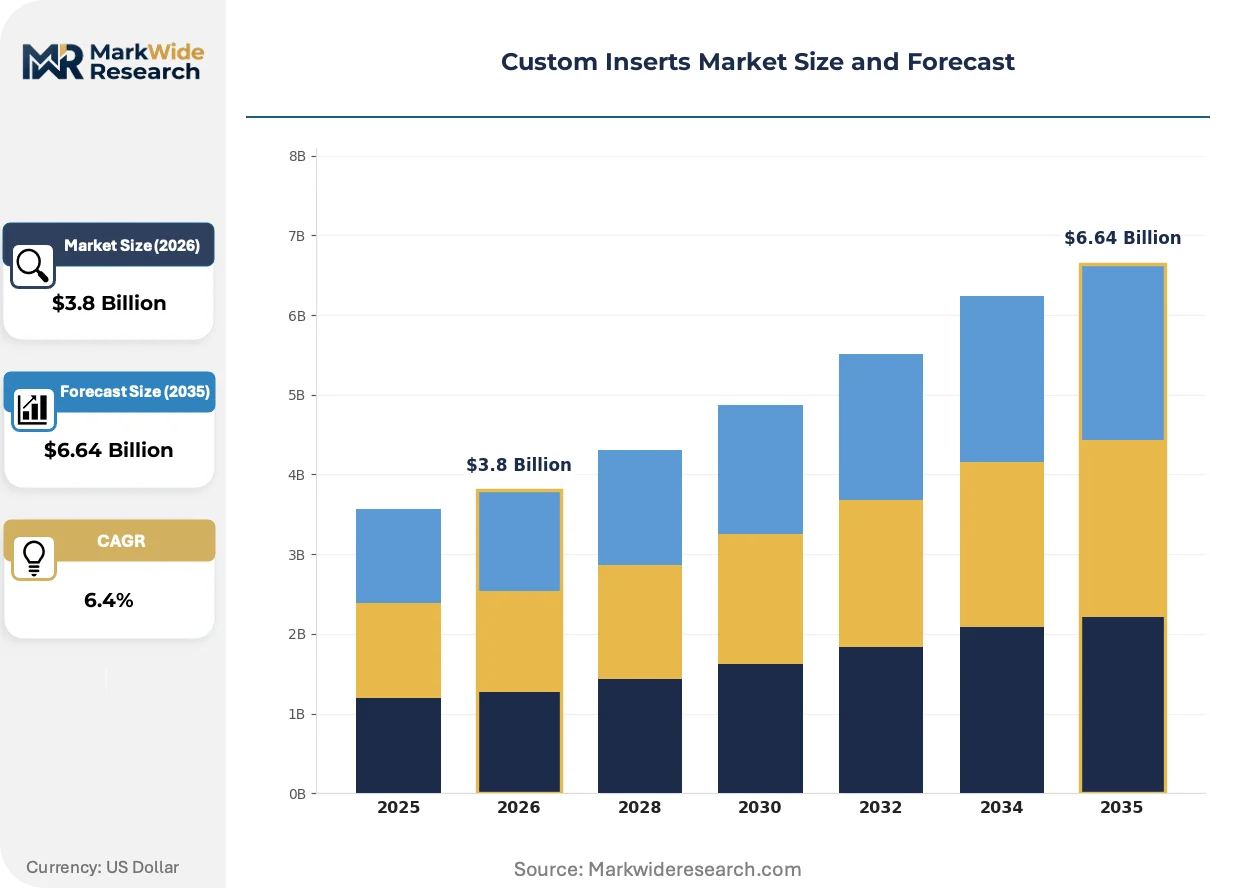
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insert Type: Foam, Plastic, Cardboard, Wood Application: Packaging, Presentation, Protection, Storage Industry: Electronics, Automotive, Consumer Goods, Healthcare Customization Level: Standard, Semi-Custom, Fully Custom, Prototype |
| Companies Covered | Dr. Scholl’s, PowerStep, Vionic, Superfeet Worldwide, Aetrex Worldwide, Bauerfeind, Hanger Inc., Ottobock, Footbalance Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Inserts Market Strategic Shifts
Digital fabrication workflows are compressing the traditional mold-and-cast orthotics paradigm while regulatory disclosure requirements are elevating material provenance as a competitive differentiator.
Generative lattice structures are decomposing the monolithic foam block as the default insert architecture. EV battery pack manufacturers in South Korea and Japan are adopting topology-optimized cushioning geometries that reduce material mass by 40% while maintaining crush resistance. This is decomposing the historical trade-off between protection density and shipping weight that governed automotive packaging specifications.
REACH authorization procedures are tightening scrutiny of persistent organic pollutants in flame-retardant foam additives. German and Dutch converters are accelerating migration to halogen-free TPU formulations ahead of 2026 sunset dates. Electronics packaging applications are most exposed, with smartphone and laptop OEMs now requiring full material substance declarations from insert suppliers.
Podiatry clinics are unbundling measurement services from fabrication, selling scan files directly to patients for third-party production. This disintermediates traditional orthotic laboratories in the United States and Australia, where direct-access legislation has expanded patient control over prescription data. Retail pharmacy chains are capturing the fabrication margin by installing vacuum-forming equipment behind store counters.
Custom Inserts Market Segmentation
Custom inserts serve divergent functional requirements across protective transit, clinical correction, and retail presentation channels. Segmentation reveals where specification tiers collapse into commodity competition versus where specialized tooling sustains margin pools.
Insert Type:
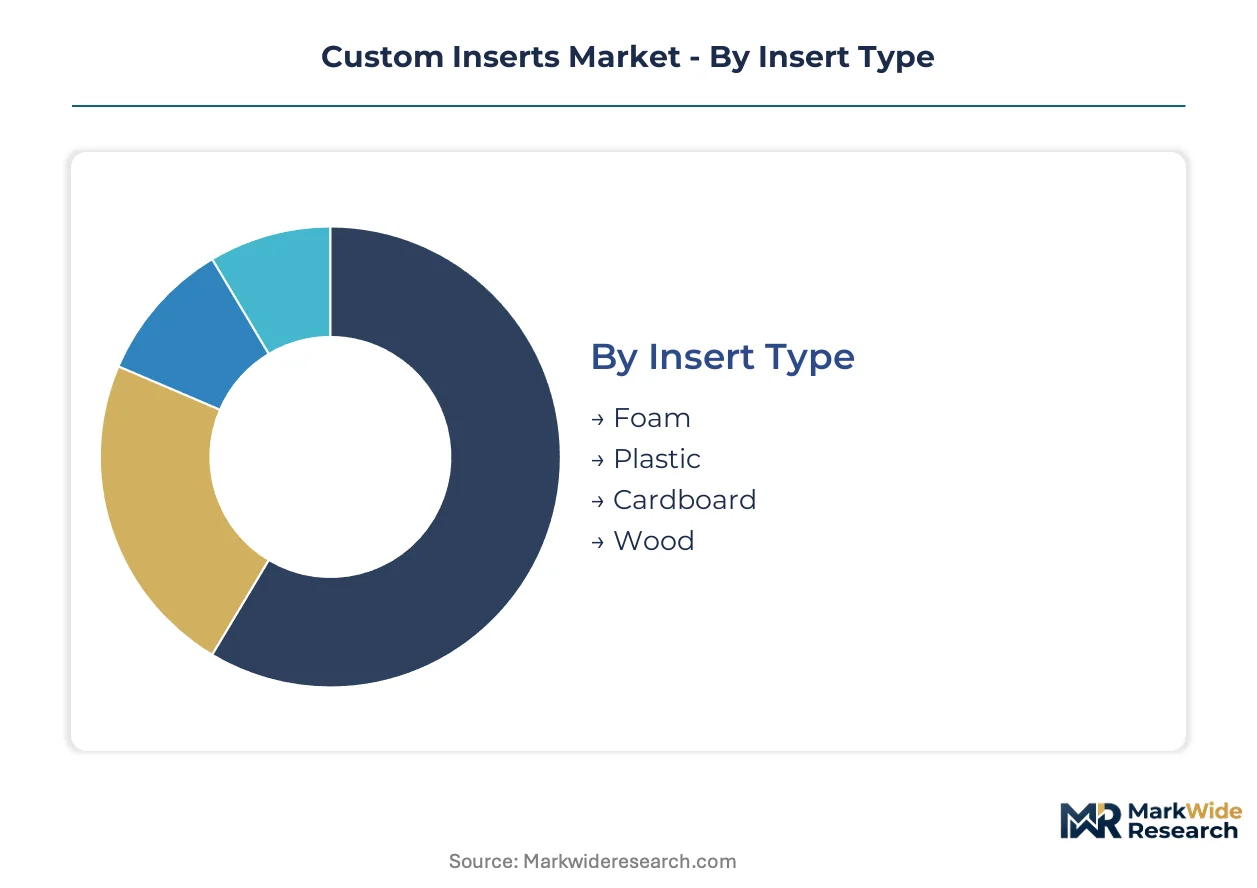
Foam and plastic variants flow through distinct channel architectures—foam dominates high-volume e-commerce fulfillment while plastic concentrates in medical device and automotive OEM supply chains.
- Foam:EVA and polyurethane formulations absorb shock through cell-structured compression, with medical-grade density specifications now migrating into consumer wellness retail. Germany's precision manufacturing corridor processes the majority of European foam orthotic volume.
- Plastic:Thermoformed ABS and TPU shells deliver dimensional stability for electronics packaging and automotive battery transit protection. REACH compliance costs on isocyanate-based formulations are compressing margin structures for European converters.
- Cardboard:Corrugated and solid fiberboard inserts serve presentation and light-duty protection in consumer goods unboxing experiences, with recycled content mandates rising under EU Packaging and Packaging Waste Regulation.
- Wood:Plywood and engineered timber frames anchor heavy industrial machinery crating, concentrated in German and Italian capital goods export corridors.
By volume, foam leads. By growth pace, plastic is ahead.
Application:
Cost tier stratification separates specification-heavy protection applications from commoditized storage and presentation functions.
- Packaging:Transit-optimized geometries for e-commerce and industrial logistics represent the highest volume application, with generative lattice structures reducing material mass by 40% in South Korean EV battery cushioning.
- Protection:Medical device and electronics OEMs demand crush-resistant architectures with full material substance declarations, creating supplier qualification premiums under CSRD disclosure mandates.
- Presentation:Unboxing-optimized inserts for premium consumer goods concentrate margin in short-run digital fabrication workflows.
- Storage:Warehouse racking and archival inserts operate at the lowest specification tier, with price competition from standardized corrugated solutions.
Protection commands the steepest expansion trajectory as EV battery modules and medical devices drive precision requirements.
Industry:
Customer type segmentation separates regulated medical device procurement from automotive OEM supplier qualification systems.
- Electronics:Smartphone and laptop manufacturers require REACH-compliant foam formulations with halogen-free flame retardants, with German and Dutch converters migrating ahead of 2026 sunset dates.
- Healthcare:Podiatric and prosthetic applications operate under FDA and EU MDR frameworks, where ISO 13485 certification timelines extend 14-18 months for therapeutic-grade claims.
- Automotive:EV battery pack cushioning absorbs the fastest-growing demand, with topology-optimized geometries replacing monolithic foam blocks in South Korean and Japanese production.
- Consumer Goods:Retail presentation and footwear orthotics bridge prescription and retail channels, with direct-to-consumer scanning platforms disintermediating traditional laboratories.
Healthcare sustains the highest margin per unit. Automotive is climbing the fastest.
Customization Level:
Supply concentration varies inversely with run length—fully custom and prototype tiers concentrate in Bavaria and Baden-Württemberg tooling clusters while standard inserts disperse across high-volume converters.
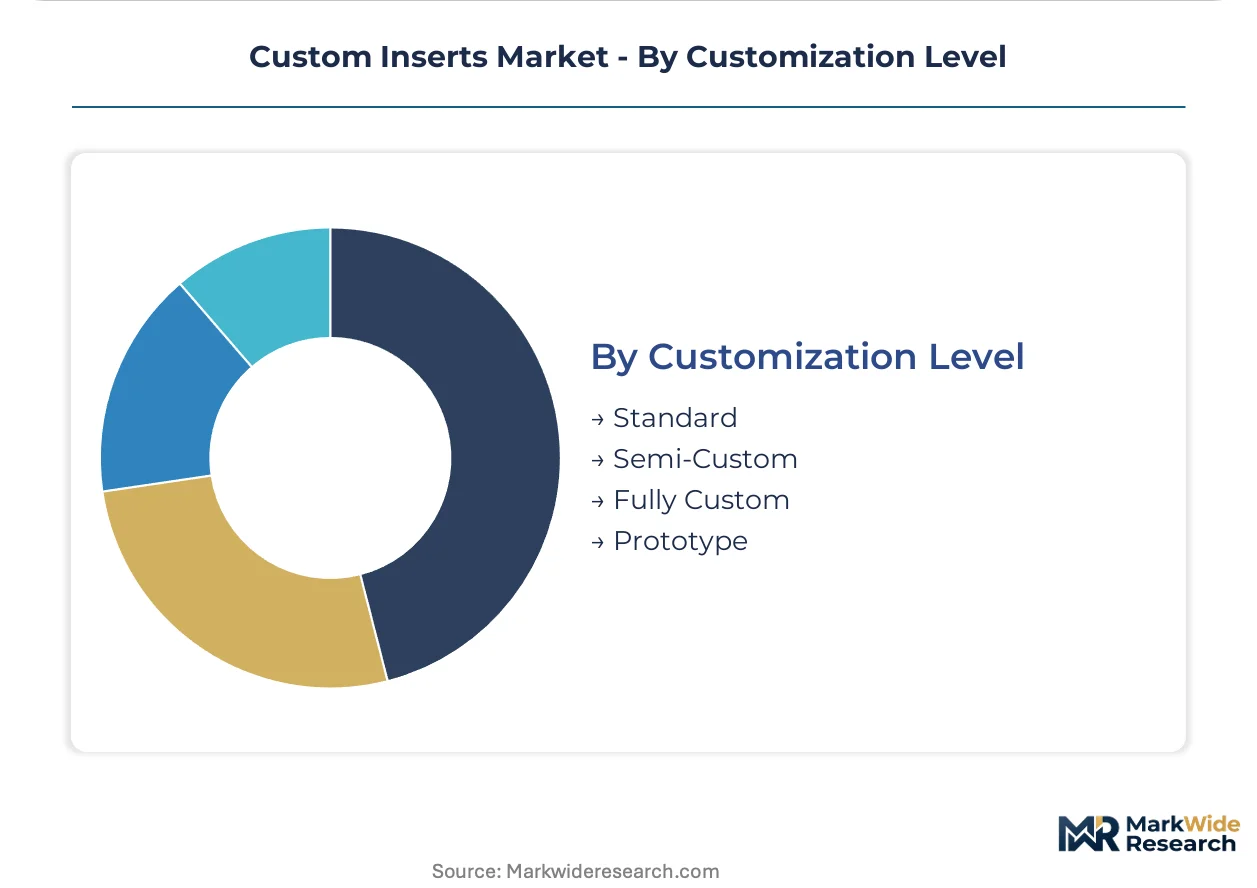
- Fully Custom:CAD-milled or vacuum-formed geometries from patient-specific scans or object digitization command disproportionate margins due to specialized tooling and short production runs, with Germany's precision manufacturing corridor dominating European capacity.
- Prototype:Rapid iteration cycles for automotive and electronics packaging development compress lead times through additive manufacturing and soft tooling, attracting fabricators to India's PLI scheme corridors in Gujarat and Karnataka.
- Semi-Custom:Modular shell systems with adjustable components bridge prescription and retail channels, with retail pharmacy chains capturing fabrication margin through in-store vacuum-forming equipment.
- Standard:Mass-produced arch profiles and cushioning geometries compete on scale economies, with Superfeet Worldwide anchoring outdoor and athletic specialty distribution.
Standard products dominate unit volume. Fully custom is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tooling expertise concentrates in southern Germany's manufacturing belt, with Bavaria and Baden-Württemberg hosting the densest clusters of vacuum-forming and CAD-milling capacity for medical-grade orthotics. This geographic specialization shapes competitive access patterns across European and export markets.
Germany
Precision manufacturing corridors in Bavaria and Baden-Württemberg process the majority of European foam orthotic volume, with concentrated expertise in thermoformed TPU shells and carbon fiber composites. ECHA's REACH authorization procedures on isocyanates and plasticizers are accelerating halogen-free formulation migration ahead of 2026 regulatory deadlines. Stuttgart and Munich anchor prototype-to-production cycles for fully custom geometries serving podiatric and automotive battery protection applications.
United States
Direct-access legislation in multiple states has expanded patient control over prescription scan data, disintermediating traditional orthotic laboratories. FDA oversight of medical device classifications shapes therapeutic-grade product claims and reimbursement pathways. Retail pharmacy chains are capturing fabrication margin through in-store vacuum-forming equipment installations, particularly in metropolitan corridors with high podiatric clinic density.
India
Production-linked incentives under the PLI scheme for medical device manufacturing are attracting insert fabricators to Gujarat and Karnataka industrial corridors. CDSCO regulatory harmonization efforts are streamlining import substitution pathways for domestic producers. Ahmedabad and Bengaluru clusters are developing rapid iteration capabilities for prototype customization serving export markets.
South Korea
EV battery pack manufacturers are adopting topology-optimized cushioning geometries that reduce material mass while maintaining crush resistance. METI-aligned industrial standards on transit protection are elevating specification requirements for automotive OEM supply chains. Seoul-Incheon production basins are displacing monolithic foam blocks with generative lattice structures in battery module packaging.
Japan
PMDA framework alignment with EU MDR standards is facilitating cross-recognition pathways for therapeutic-grade orthotic imports. METI's carbon neutrality roadmaps are pressuring foam converters toward bio-based TPU formulations. Nagoya-Osaka manufacturing belts are integrating smartphone photogrammetry with cloud-based CAD processing for direct-to-consumer channels.
Custom Inserts Market Competitive Environment
Concentration sits with heritage rehabilitation brands and biomechanical engineering specialists that bridge prescription and retail distribution channels. The vendor base organizes around three archetypes: European precision manufacturers with medical device pedigrees, North American consumer wellness platforms with direct-to-consumer scanning capabilities, and Asian automotive packaging specialists leveraging generative design workflows. Competitive moves center on M&A targeting digital measurement platforms and strategic partnerships with retail pharmacy chains for in-store fabrication deployment.
Among heritage European manufacturers, Bauerfeind leverages its rehabilitation heritage to bridge prescription and retail segments. Superfeet Worldwide anchors the outdoor and athletic specialty channel with biomechanically engineered arch profiles. Vionic occupies a position exemplifying podiatrist-designed credibility extension into footwear integration beyond standalone insert sales.
| Leading Market Players |
|---|
| Dr. Scholl's |
| PowerStep |
| Vionic |
| Superfeet Worldwide |
| Aetrex Worldwide |
| Bauerfeind |
| Hanger Inc. |
| Ottobock |
| Footbalance Systems |
| Others |
Value Chain & Pricing Dynamics
Scale economies in Bavarian vacuum-forming clusters compress unit costs for fully custom geometries while elevating price floors for smaller converters lacking CAD-milling capacity. REACH compliance costs on isocyanate-based TPU formulations feed directly into supplier qualification premiums, concentrating margin capture among ESG-documented foam producers serving EU MDR-classified medical device channels.
Pricing Analysis
EU MDR framework dictates the pricing tier structure across therapeutic-grade, medical-grade, and consumer wellness segments. Three-tier pricing structure across premium certification, standard compliance, and economy retail levels separates ISO 13485-certified orthotics from REACH-compliant general wellness products from unregulated mass-market foam inserts. Cost compression in standard-grade EVA formulations is intensifying because Indian PLI-subsidized capacity is absorbing Asian export demand. Retail pharmacy chains exhibit highest price sensitivity due to thin fabrication margins behind store counters, while automotive OEMs tolerate premium pricing for topology-optimized battery cushioning with full material substance declarations.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade carbon fiber precursors dominates inventory strategy among high-performance insert fabricators, contrasting with just-in-time EVA foam procurement in high-volume wellness channels. Raw material sourcing draws from German TPU formulation expertise, South Korean EV battery packaging demand, and Indian PLI-subsidized medical device corridors. Supply chain risk centers on Toray-Hexcel-SGL Carbon concentration controlling precursor output for carbon fiber composites. Distribution runs through direct-to-consumer scanning platforms disintermediating traditional orthotic laboratories, retail pharmacy fabrication counters, and automotive OEM supplier qualification systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Custom inserts sit in early-cycle expansion as smartphone photogrammetry collapses clinical gatekeeping barriers and opens direct-to-consumer channels previously blocked by podiatric prescription control.
For Market Incumbents: Shield fabrication margin from retail pharmacy chain encroachment by securing exclusive digital scanning platform partnerships before at-home 3D scanning reaches mass adoption velocity. Deepen backward integration into halogen-free TPU formulation capacity ahead of ECHA sunset deadlines to lock in supplier qualification premiums under CSRD disclosure mandates. ISO 13485 certification moats delay new therapeutic-grade entrants 14-18 months. For New Entrants and Emerging Players: Differentiate on rapid-prototype iteration cycles for automotive battery packaging applications where topology-optimized geometries displace monolithic foam blocks. India's Gujarat and Karnataka PLI corridors offer the most penetrable geography for medical device manufacturing incentives. Target direct-to-consumer wellness channels with cloud-based CAD processing paired with smartphone photogrammetry, bypassing clinical gatekeeper friction entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital measurement platform operators capturing scan-file licensing fees from disintermediated podiatry clinics. Long-term viability favors fabricators bridging prescription and retail channels with modular shell systems. Acquisition target archetype: vacuum-forming specialists in Baden-Württemberg with existing ESG documentation and automotive OEM supplier status. Watch for inflection when at-home 3D scanning penetration crosses threshold sufficient to trigger retail pharmacy chain consolidation of fabrication capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Measurement Platform Acquisition | Captures scan-file licensing revenue from disintermediated podiatric clinics in direct-access jurisdictions. |
| Halogen-Free TPU Formulation Migration | Locks in CSRD supplier qualification premiums ahead of ECHA 2026 sunset deadlines for electronics OEMs. |
| In-Store Vacuum-Forming Deployment | Retail pharmacy chains capture fabrication margin previously retained by orthotic laboratories. |
| Topology-Optimized Lattice Development | South Korean EV battery manufacturers reduce cushioning mass 40% while maintaining crush resistance standards. |
| ISO 13485 Certification Investment | Extends therapeutic-grade market access timelines for competitors by 14-18 months through audit bottlenecks. |
Study Parameters
Initial hypotheses were tested against primary input from podiatric clinic operators, orthotic laboratory technicians, automotive OEM packaging engineers, and medical device procurement managers and refined through secondary validation against ECHA substance restriction databases, EU MDR classification guidance, FDA 510(k) filing records, and Indian PLI scheme administrative disclosures. Bottom-up demand estimates from end-use industry interviews were triangulated with top-down market sizing from trade flow analysis and production capacity surveys across Bavarian and Baden-Württemberg tooling clusters.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects by modeling insert type, customization level, application tier, and end-use industry as independent segmentation dimensions. CAGRs were derived from logistic adoption curves fitted to digital scanning penetration rates and EV battery packaging specification upgrade cycles. Forecast inputs incorporated REACH authorization timeline probabilities and PLI scheme capacity absorption rates from Gujarat and Karnataka industrial corridor development.
Material uncertainties — regulatory acceleration of ECHA substance restrictions, carbon fiber precursor supply disruptions, and direct-access legislation expansion — sit outside the modeled envelope. Forecasts reflect assumptions about clinical gatekeeper persistence and automotive OEM qualification timeline stability. Revision becomes warranted when smartphone photogrammetry accuracy crosses clinical-grade thresholds sufficient to trigger mass disintermediation of traditional measurement services.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Senior Friendly Packaging Market