
 Eco-Friendly Tea Packaging Market | 2026-2036
Eco-Friendly Tea Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Tea Packaging Market Foresight
Single-source paperboard supply is decoupling from long-term contracts as converters diversify into bamboo and molded fiber networks. DS Smith PLC leverages its European recycled paper infrastructure to secure tea brand partnerships. Mondi PLC anchors its position through kraft-pouch innovation for loose-leaf formats. ProAmpac LLC competes with flexible compostable laminates targeting specialty cafés.
Eco-friendly tea packaging comprises biodegradable or recyclable containers designed to preserve aroma, moisture barrier, and shelf stability without conventional plastics. Manufacturers employ heat-sealable bioplastic films, unbleached kraft paper with PLA windows, and bamboo-derived cellulose formed into pyramid sachets or stand-up pouches. Pouches lead volume due to their lightweight shipping profile and compatibility with nitrogen flushing, while bioplastics capture margin pools from premium organic tea lines seeking petroleum-free credentials. Boxes retain strength in gift and ceremonial segments where structural rigidity and print quality drive selection.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape material approval pathways, with compostability certifications from TÜV Austria and BPI governing market access for biodegradable claims. Japan's Ministry of Economy, Trade and Industry promotes bioplastic commercialization through its Green Growth Strategy, accelerating domestic adoption of plant-based tea sachets. Stakeholders must track evolving home-composting versus industrial-composting certification splits, as mismatched infrastructure renders some bio-based formats non-viable in key consumption regions.
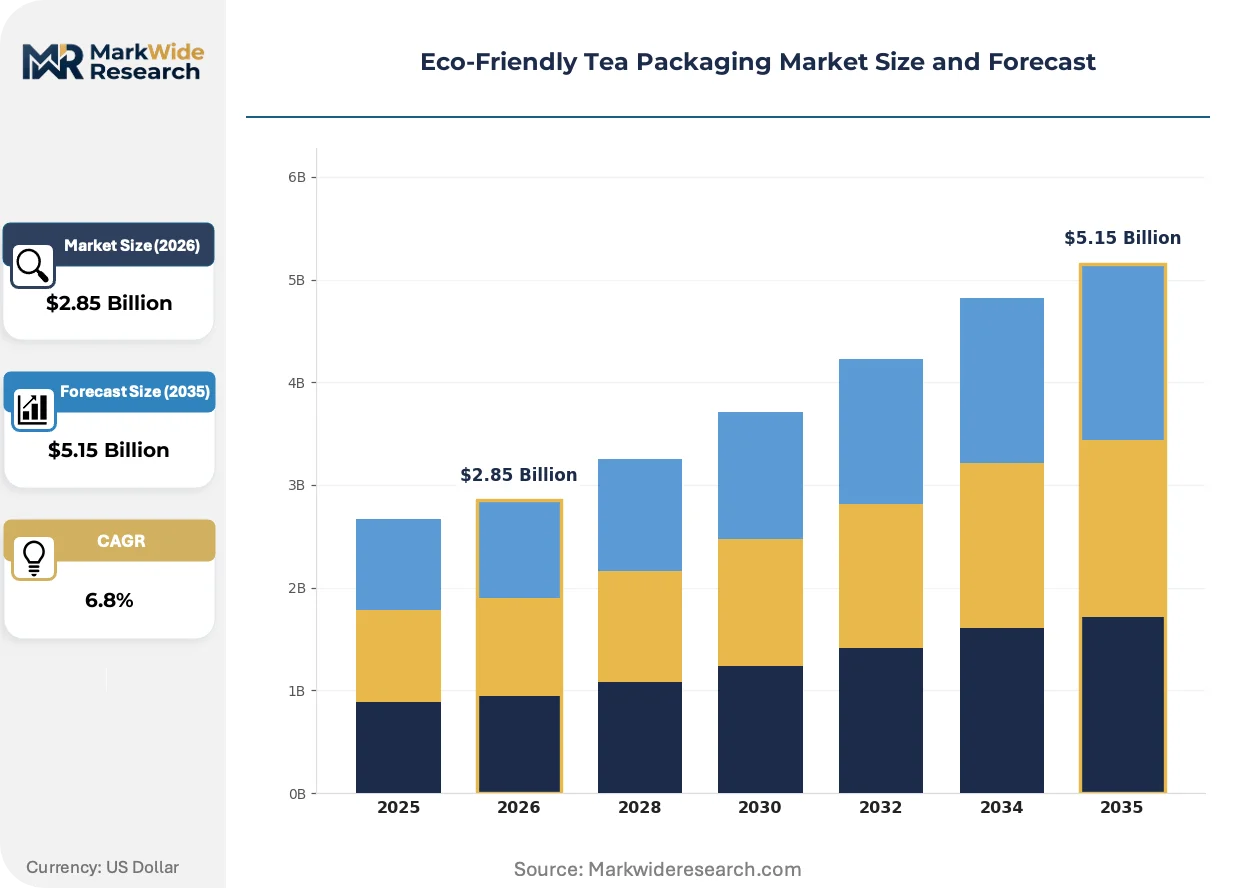
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitution across European supply chains, while municipal composting availability creates stark geographic adoption boundaries for biodegradable formats.
Growth Catalysts
- EU Green Deal Packaging Mandates:The EU Packaging and Packaging Waste Regulation tightens material recovery targets, compelling tea brands to abandon multi-layer plastic laminates for certified compostable alternatives.
- Specialty Café Channel Expansion:Independent cafés in Germany and Japan now require petroleum-free packaging credentials as standard procurement terms, accelerating bioplastic pouch adoption.
- PLA Film Heat-Sealing Advances:Improved polylactic acid barrier properties enable nitrogen flushing compatibility previously limited to conventional plastics, preserving loose-leaf aroma without synthetic layers.
Market Restraints
- Industrial Composting Infrastructure Gaps:Home-compostable certifications from TÜV Austria carry limited value in regions lacking municipal composting facilities, creating market access barriers.
- Bamboo Pulp Supply Concentration:Sichuan and Zhejiang provinces control over 60% of global bamboo cellulose processing, exposing converters to raw material bottlenecks.
- PLA Feedstock Cost Volatility:Corn and sugarcane price swings directly impact bioplastic film economics, compressing margins during agricultural commodity spikes.
Strategic Opportunities
- Japan's Green Growth Strategy Subsidies:METI funding for domestic bioplastic commercialization reduces capital barriers for plant-based sachet manufacturing expansion.
- Direct-to-Consumer Subscription Channels:Specialty tea brands bypass retail shelf constraints through mailed compostable pouches, eliminating the premium-packaging cost burden of gift-box formats.
- Home-Composting Certification Divergence:Early alignment with BPI and TÜV Austria home-composting standards opens positioning advantages as infrastructure catches up in North American municipalities.
Industry Challenges
- Dual Certification Timeline Compression:Securing simultaneous FDA food-contact approval and TÜV Austria compostability validation extends product development cycles by 8-14 months.
- Molded Fiber Equipment Retrofit Costs:Converting legacy paperboard lines to bamboo-fiber compatibility requires capital outlays that mid-size converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Tea Packaging Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Pouches, Boxes, Bottles Material: Bamboo, Bioplastics, Recycled Paper, Glass Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Consumers, Restaurants, Cafés, Retailers |
| Companies Covered | Amcor Plc, DS Smith PLC, ProAmpac LLC, WestRock Company, Mondi PLC, Sonoco Products Company, Crown Holdings, Inc., Novolex Holdings, Inc., Graham Packaging Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Tea Packaging Market Shifts & Advancements
Material science breakthroughs and certification fragmentation are reshaping competitive positioning, with nitrogen-flush compatibility and home-composting claims becoming primary differentiation vectors.
Polylactic acid film with enhanced oxygen barrier properties is integrating into stand-up pouch laminates for organic loose-leaf lines. Specialty tea brands in the United Kingdom and Germany are adopting these formats at accelerated pace to meet retailer sustainability mandates. The technology is integrating aroma preservation standards previously exclusive to aluminum-foil constructions, compressing the performance gap between petroleum-based and plant-derived barriers.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are tightening approval pathways for conventional adhesive layers and printing inks. Industrial consequence includes forced reformulation of heat-seal coatings and migration testing for mineral oil saturated hydrocarbons. Premium organic segments across Germany and France are responding by pre-emptively switching to water-based inks and bio-adhesives ahead of enforcement deadlines.
Buyer certification literacy is reshaping procurement evaluation criteria, with BPI and TÜV Austria logos now required for shelf placement at specialty retailers. The wholesale distributor channel faces disintermediation pressure as brands sell direct with detailed composting instructions. This behavioral shift is most visible in Japanese metropolitan markets, where METI-backed consumer education campaigns have created expectation of industrial-composting guidance on packaging.
Eco-Friendly Tea Packaging Market Segmentation
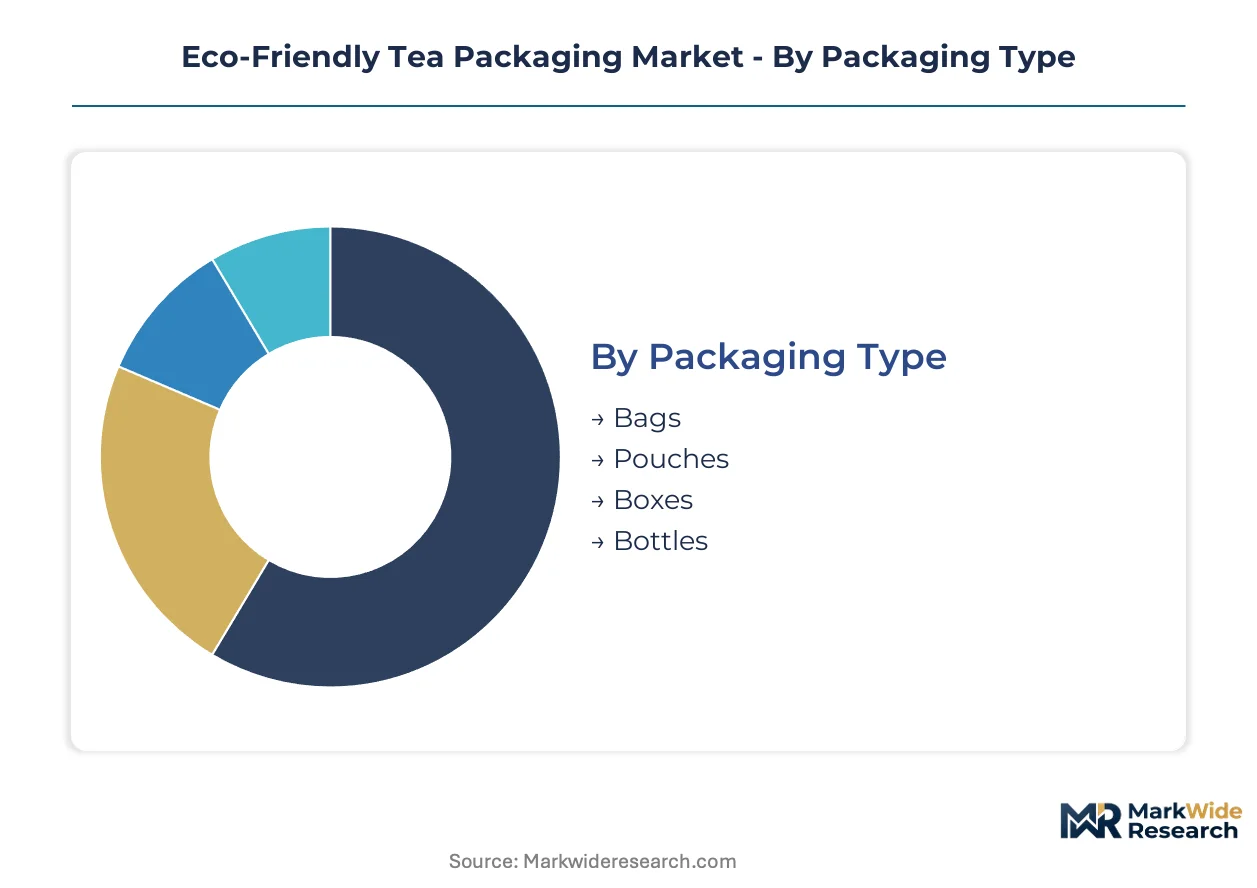
Eco-friendly tea packaging segments diverge sharply in capital requirements and margin profiles. Material choices dictate equipment retrofit costs, while distribution channels determine working capital intensity and brand control.
Packaging Type:
Pouch and box formats demand the heaviest upfront investment in barrier-coating technology and structural printing capabilities.
- Pouches:Stand-up and flat-bottom configurations utilize PLA-laminated kraft paper with nitrogen-flush compatibility. German specialty tea brands and Japanese organic lines concentrate procurement here, driven by lightweight shipping economics and shelf-ready presentation. Pouches absorb the bulk of installed capacity; boxes are expanding most quickly.
- Boxes:Rigid paperboard constructions with molded fiber inserts target gift and ceremonial segments. United Kingdom premium brands favor these for retail visibility, though higher material costs limit penetration in mass-market channels.
- Bags:Pillow and gusseted formats serve commodity tea volumes with minimal barrier requirements.
- Bottles:Glass and bio-based polymer containers capture ready-to-drink and cold-brew applications.
Boxes command premium positioning through structural differentiation; pouches gain share fastest in direct-to-consumer channels.
Material:
Bioplastic and bamboo feedstocks stratify by processing complexity and geographic supply concentration.
- Bioplastics:PLA and PHA films provide heat-seal functionality with petroleum-free credentials. Japanese METI-subsidized facilities and German converters lead capacity expansion, responding to EU Packaging and Packaging Waste Regulation mandates for certified compostable alternatives.
- Bamboo:Cellulose pulp from Sichuan and Zhejiang provinces feeds pyramid sachet and molded fiber production. Supply bottlenecks concentrate risk, though premium organic segments absorb price volatility for sustainability positioning.
- Recycled Paper:Post-consumer fiber with water-based barrier coatings serves cost-sensitive loose-leaf formats.
- Glass:Reusable and recyclable containment for premium bottled tea lines with local distribution models.
Recycled paper holds the widest installed base; bioplastics are climbing the fastest as barrier properties improve.
Distribution Channel:
Channel selection determines certification requirements and margin capture, with specialty retail imposing the strictest sustainability credentials.
- Specialty Stores:Curated tea boutiques and organic grocers mandate BPI or TÜV Austria compostability logos for shelf placement. German and United Kingdom retailers enforce this as standard procurement terms, filtering out conventional plastic formats.
- Online Retail:Direct-to-consumer subscriptions bypass retail slotting fees and enable detailed composting instructions. Japanese metropolitan markets show strongest adoption, supported by METI consumer education campaigns.
- Supermarkets:Mass-market placement demands price-competitive formats with established supply chains.
- Direct Sales:Café and hospitality procurement emphasizes petroleum-free credentials as brand alignment.
Supermarkets move the highest absolute volumes; online retail is gaining share fastest among specialty brands.
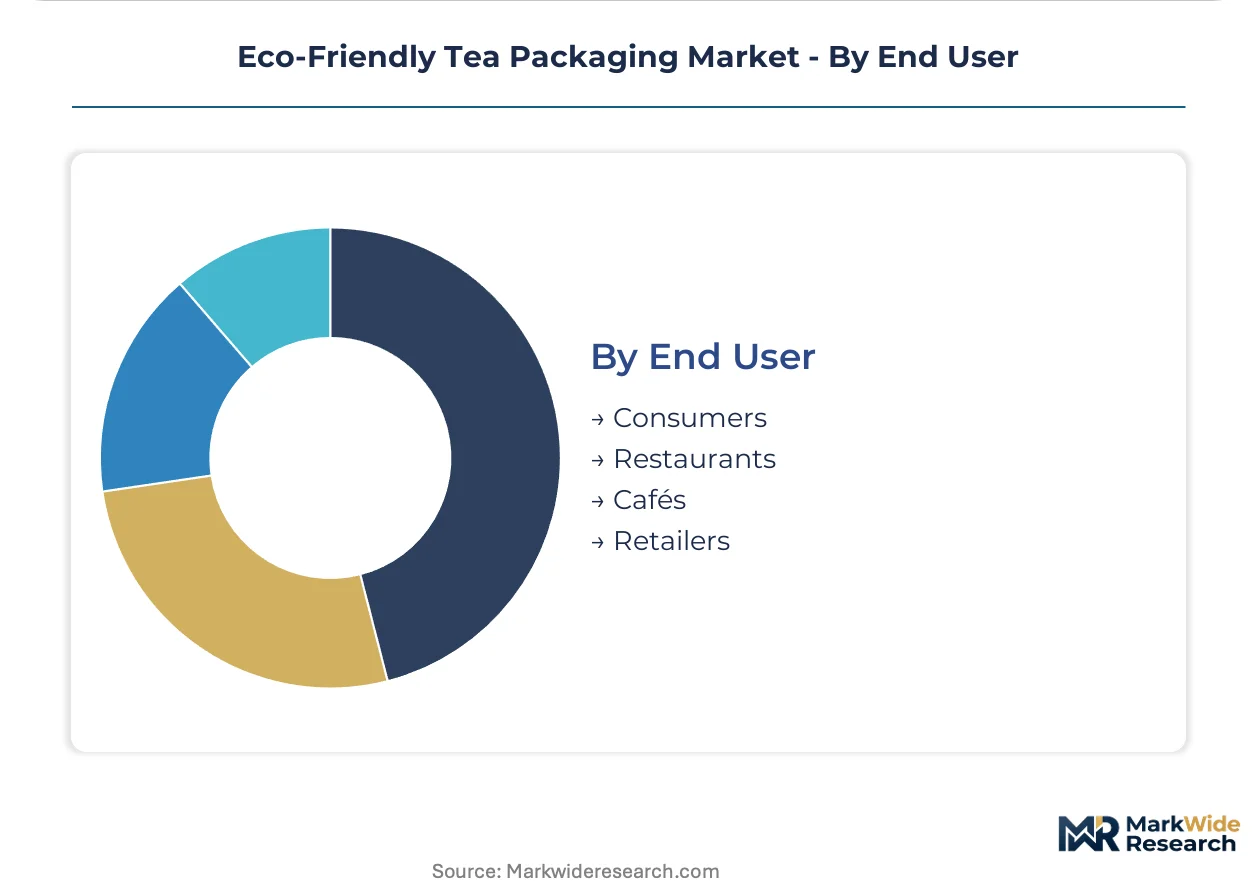
End User:
Café and restaurant procurement operates on shorter decision cycles than retail, accelerating format experimentation.
- Cafés:Independent specialty coffee and tea houses in Germany and Japan require compostable packaging as standard terms. PLA-laminated pouches dominate here, with nitrogen flushing preserving aroma through extended supply chains.
- Consumers:Home brewing segments split between convenience-driven bag users and ritual-oriented loose-leaf purchasers. United Kingdom and Japanese markets show strongest willingness to pay for home-compostable certifications.
- Restaurants:Foodservice tea service prioritizes cost efficiency and operational simplicity over sustainability claims.
- Retailers:Private-label and branded product sourcing responds to regulatory deadlines and consumer pressure.
Consumers represent the largest addressable base; cafés are expanding most quickly as procurement standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters most densely in Germany, the United Kingdom, and Japan where municipal composting infrastructure supports biodegradable format adoption at scale. Specialty tea brands in these markets face immediate procurement pressure from retailer sustainability mandates. Regulatory deadlines across the EU, Japan, and select North American jurisdictions are compressing format transition timelines.
Germany
Specialty cafés in Berlin and Hamburg now require petroleum-free packaging credentials as standard procurement terms, accelerating bioplastic pouch adoption. The EU Packaging and Packaging Waste Regulation tightens material recovery targets, compelling brands to abandon multi-layer plastic laminates. Bavaria and North Rhine-Westphalia host the densest converter networks for PLA-laminated kraft paper production.
United Kingdom
Premium organic tea lines in London and the Southeast show strongest willingness to pay for home-compostable certifications from TÜV Austria. REACH substance restrictions force reformulation of heat-seal coatings and migration testing for mineral oil saturated hydrocarbons. The Midlands and North England concentrate molded fiber equipment retrofits for gift-box ceremonial segments.
Japan
METI's Green Growth Strategy subsidizes domestic bioplastic commercialization, reducing capital barriers for plant-based sachet manufacturing expansion. Tokyo and Osaka metropolitan markets display the strongest consumer expectation of industrial-composting guidance on packaging. Chubu and Kyushu regions anchor bamboo-derived cellulose processing partnerships with Chinese pulp suppliers.
United States
Direct-to-consumer subscription channels from California and the Pacific Northwest bypass retail shelf constraints through mailed compostable pouches. FDA food-contact substance notifications shape material approval pathways alongside BPI compostability certifications. The Northeast Corridor and Colorado Front Range cluster specialty tea brand headquarters demanding nitrogen-flush compatible barriers.
China
Sichuan and Zhejiang provinces control over sixty percent of global bamboo cellulose processing, exposing converters to raw material bottlenecks. Domestic specialty tea brands in Shanghai and Hangzhou absorb price volatility for sustainability positioning. The Yangtze River Delta integrates PLA film production capacity responding to EU and Japanese export demand.
Eco-Friendly Tea Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit legacy paperboard lines for bamboo-fiber compatibility and PLA-laminated pouch production. The vendor base stratifies across three tiers: multinational integrated packaging conglomerates with recycled paper infrastructure, mid-size flexible packaging specialists pursuing compostable laminate innovation, and regional molded fiber converters serving gift-box ceremonial segments. Two competitive moves define current positioning: strategic partnerships between converters and specialty tea brands for co-developed compostable formats, and geographic expansion into Japan and Germany to capture METI subsidies and EU mandate-driven demand.
Among European-based integrated players, DS Smith PLC and Mondi PLC exemplify distinct strategic archetypes within the recycled paper and kraft-pouch innovation vectors respectively. WestRock Company anchors the North American tier through scale-driven supply chain positioning. ProAmpac LLC occupies a specialist position competing with flexible compostable laminates targeting specialty café channels. Amcor Plc represents the multinational conglomerate archetype with cross-regional material science capabilities.
| Leading Market Players |
|---|
| Amcor Plc |
| DS Smith PLC |
| ProAmpac LLC |
| WestRock Company |
| Mondi PLC |
| Sonoco Products Company |
| Crown Holdings, Inc. |
| Novolex Holdings, Inc. |
| Graham Packaging Company |
| Others |
Supply & Pricing Matrix
Corn futures and sugarcane commodity benchmarks cascade directly into PLA film manufacturing costs, splitting the market into petroleum-dependent legacy tiers and bio-based premium tiers that specialty tea brands absorb for EU Packaging and Packaging Waste Regulation compliance.
Pricing Analysis
Volume-driven bag formats compete on minimal barrier specifications while margin-rich pouches and boxes capture premium positioning through compostability certifications. Price differentiation separates TÜV Austria-certified home-compostable formats from industrial-compostable alternatives, with German specialty retailers enforcing the strictest procurement standards. Cost compression in standard kraft-paper tiers intensifies as Chinese converters expand recycled-fiber capacity. Mass-market supermarket buyers exhibit highest price sensitivity; Japanese organic tea brands show lowest sensitivity due to METI subsidy absorption.
Supply Chain Analysis
Japan's Green Growth Strategy domestic-content mandates and EU local-sourcing preferences are reshaping converter location decisions away from pure cost optimization. Raw material supply concentrates in China for bamboo cellulose, Thailand and Brazil for sugarcane-derived PLA feedstock, and Germany for kraft-paper processing infrastructure. The network draws from Sichuan and Zhejiang province pulp mills, corn-processing facilities in the US Midwest, and European recycled-paper collection systems. Single-source vulnerability in bamboo pulp exposes converters to weather-driven harvest disruptions. Distribution runs through specialty retail procurement offices in Berlin, London, and Tokyo, with direct-to-consumer channels bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eco-friendly tea packaging sits in active materials-transition phase, with PLA-laminated nitrogen-flush pouches displacing aluminum-foil constructions that dominated aroma-preservation applications.
For Market Incumbents: Hedge against bamboo pulp supply concentration by securing multi-origin cellulose contracts with Indian and Vietnamese processors before Sichuan province bottlenecks tighten. Accelerate FDA food-contact approval pipelines to compress the 8-14 month dual-certification timeline that delays TÜV Austria compostability validation. Vertical integration into PLA film extrusion insulates margin pools from corn price volatility. For New Entrants and Emerging Players: Small-batch direct-to-consumer subscription brands in the US Pacific Northwest represent the most penetrable buyer archetype, as these operations bypass retail slotting fees and prioritize composting instruction transparency over unit economics. Target home-compostable certification gaps in North American municipalities where infrastructure lags behind European standards. Launch through specialty café procurement channels in Germany that now require petroleum-free credentials as standard terms. For Investors and Strategic Acquirers: The window for entry favors mid-size flexible packaging specialists with existing kraft-paper lamination equipment and regulatory affairs capacity. Long-term viability hinges on certification infrastructure rather than raw material access, as barrier-property improvements democratize PLA film performance. Watch for METI subsidy expansion signals as the inflection indicator for Japanese domestic manufacturing capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | Dual BPI and TÜV Austria approval unlocks shelf placement at German specialty retailers enforcing EU mandate compliance. |
| Bamboo Pulp Supply Diversification | Multi-origin sourcing from Vietnam and India reduces concentration risk in Sichuan and Zhejiang processing corridors. |
| Nitrogen-Flush PLA Lamination Scale-Up | Enhanced oxygen barrier properties enable loose-leaf aroma preservation without aluminum-foil layer dependency. |
| Direct-to-Consumer Channel Development | Subscription models bypass retail slotting fees and enable detailed composting guidance for home-compostable formats. |
| METI Subsidy Capture in Japan | Domestic bioplastic commercialization funding reduces capital barriers for plant-based sachet manufacturing expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with packaging converters, specialty tea brand procurement directors, composting facility operators, and certification body technical auditors. Secondary sources included EU Packaging and Packaging Waste Regulation implementation documents, FDA food-contact substance notifications, METI Green Growth Strategy disbursement records, and BPI certification registries. Bottom-up capacity assessments across German, UK, and Japanese converter networks were triangulated against top-down demand estimates from specialty retail channel audits.
Data-stream reconciliation across material input costs, equipment retrofit capital requirements, and end-user procurement surveys generated volume and value estimates across the projection horizon. Segmentation modeling incorporated packaging type, material substrate, distribution channel, and end-user application dimensions. CAGRs were derived from weighted average growth trajectories of certified compostable format adoption curves, with explicit inputs for PLA film barrier-property improvement timelines and municipal composting infrastructure expansion rates.
Revisions become necessary when regulatory enforcement delays, agricultural commodity price spikes, or certification standard fragmentation materialize beyond modeled scenarios. Forecasts reflect documented assumptions regarding EU mandate adherence timelines and METI subsidy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Cake Box Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Pie Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Seafood Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Global Disposable Plates Market