
 Promotion Bins Market | 2026-2036
Promotion Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Promotion Bins Market Analytics
Asset-light leasing models for retail fixtures is tilting competitive dynamics toward suppliers with balance-sheet capacity to carry inventory risk. Smurfit Kappa Group leverages its corrugated manufacturing network across multiple continents to offer bundled display programs. Pratt Industries anchors its position through integrated recycled paperboard production that controls input costs. Menasha Packaging Company differentiates via structural design capabilities for club-store formats.
Promotion bins are rigid or semi-rigid containers engineered from corrugated fiberboard, injection-molded polypropylene, or steel wire, typically specifying load capacities and footprint dimensions to optimize palletization and point-of-sale placement. Their primary commercial purpose centers on temporary product elevation, inventory organization, and brand messaging within high-traffic retail zones. Stackable bins lead volume within product-type categories due to replenishment efficiency in warehouse club environments, while collapsible formats represent the fastest-growing segment as e-commerce platforms prioritize reverse-logistics cost reduction. Plastic dominates material demand for moisture resistance in beverage and frozen-food applications, though corrugated fiberboard retains margin strength in short-turn promotional campaigns.
FDA food-contact substance regulations govern resin selection for bins deployed in grocery perimeter departments, while EPA recycled-content guidelines under the Comprehensive Procurement Preference program shape federal channel specifications. State-level extended producer responsibility frameworks in California and Oregon are pressuring manufacturers to validate end-of-life recovery pathways. Stakeholders must monitor how retailer sustainability scorecards recalibrate material acceptance thresholds before committing to multi-year tooling investments.
Market Dynamics
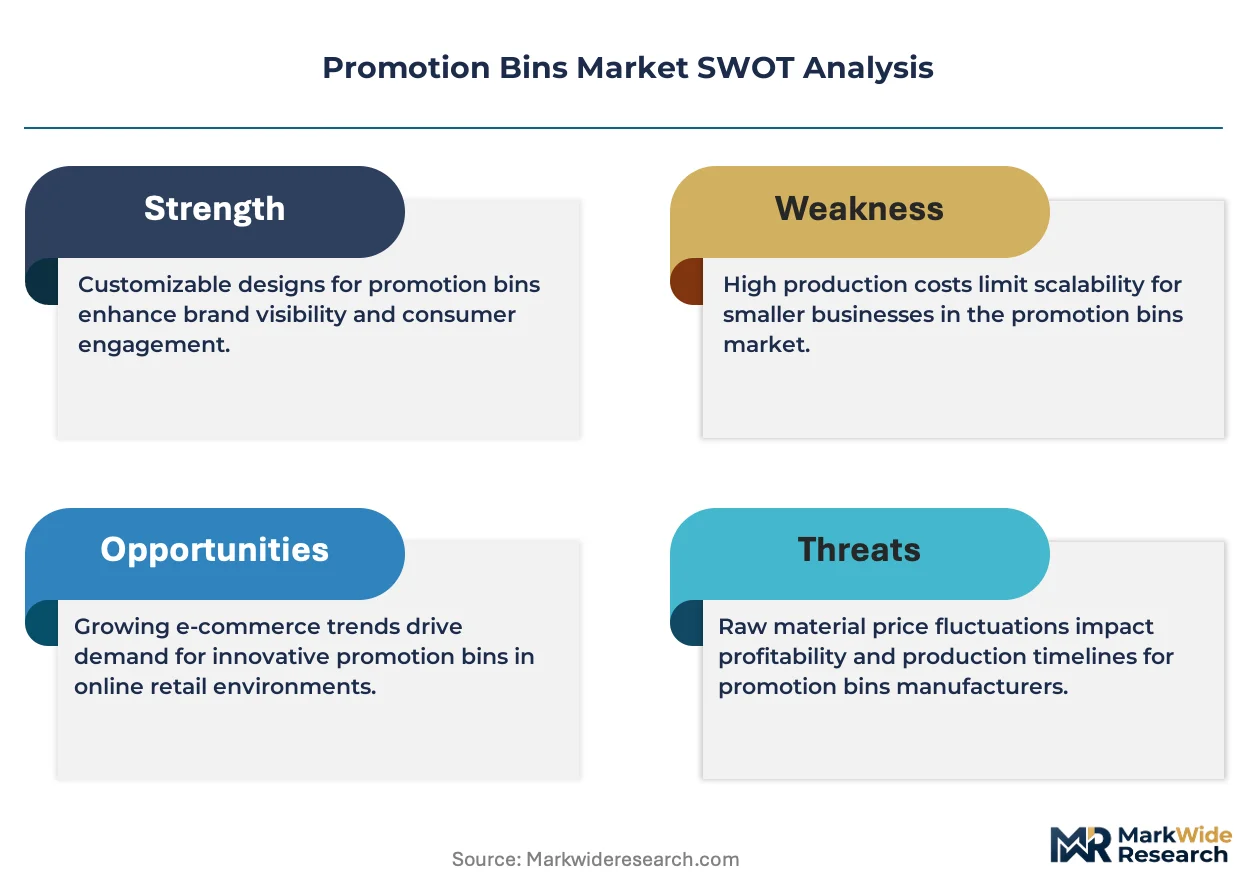
Asset-light leasing models for retail fixtures are compressing supplier margins and concentrating purchasing power among retailers with balance-sheet capacity to offload inventory risk onto manufacturers.
Growth Catalysts
- California SB 54 mandates:State-level extended producer responsibility frameworks require validated end-of-life recovery pathways, accelerating investment in recyclable corrugated fiberboard formulations.
- Club-store format expansion:Warehouse club operators specify stackable bin geometries optimized for palletization density, driving standardization in load-bearing specifications.
- Seasonal merchandising intensity:Big-box retailers refresh floor-based promotional displays quarterly to capture impulse purchases, shortening replacement cycles for temporary fixtures.
Market Restraints
- OCC price volatility:Old corrugated containerboard input costs fluctuate with municipal recycling collection rates, squeezing margins for fiberboard-dependent producers.
- Resin selection constraints:FDA food-contact substance regulations limit polypropylene grades deployable in grocery perimeter departments, restricting material sourcing flexibility.
- Steel wire tariff exposure:Import duties on galvanized wire from concentrated Asian supply bases elevate landed costs for metal-frame bin assemblers.
Strategic Opportunities
- Reverse-logistics optimization:Collapsible bin formats reduce backhaul cube utilization by sixty percent, creating value propositions for e-commerce fulfillment networks.
- Federal procurement preference:EPA Comprehensive Procurement Preference guidelines under the recovered materials program mandate recycled-content thresholds for government channel bids.
- Digital print integration:Direct-to-substrate decoration technologies enable SKU-level customization without plate changeover costs, opening short-run campaign viability.
Industry Challenges
- Structural engineering talent scarcity:Finite pool of designers proficient in load-rack simulation software for club-store pallet patterns limits product development velocity.
- Multi-jurisdictional compliance mapping:Simultaneous adherence to FDA food-contact rules, state recycled-content mandates, and retailer sustainability scorecards fragments quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Promotion Bins Market |
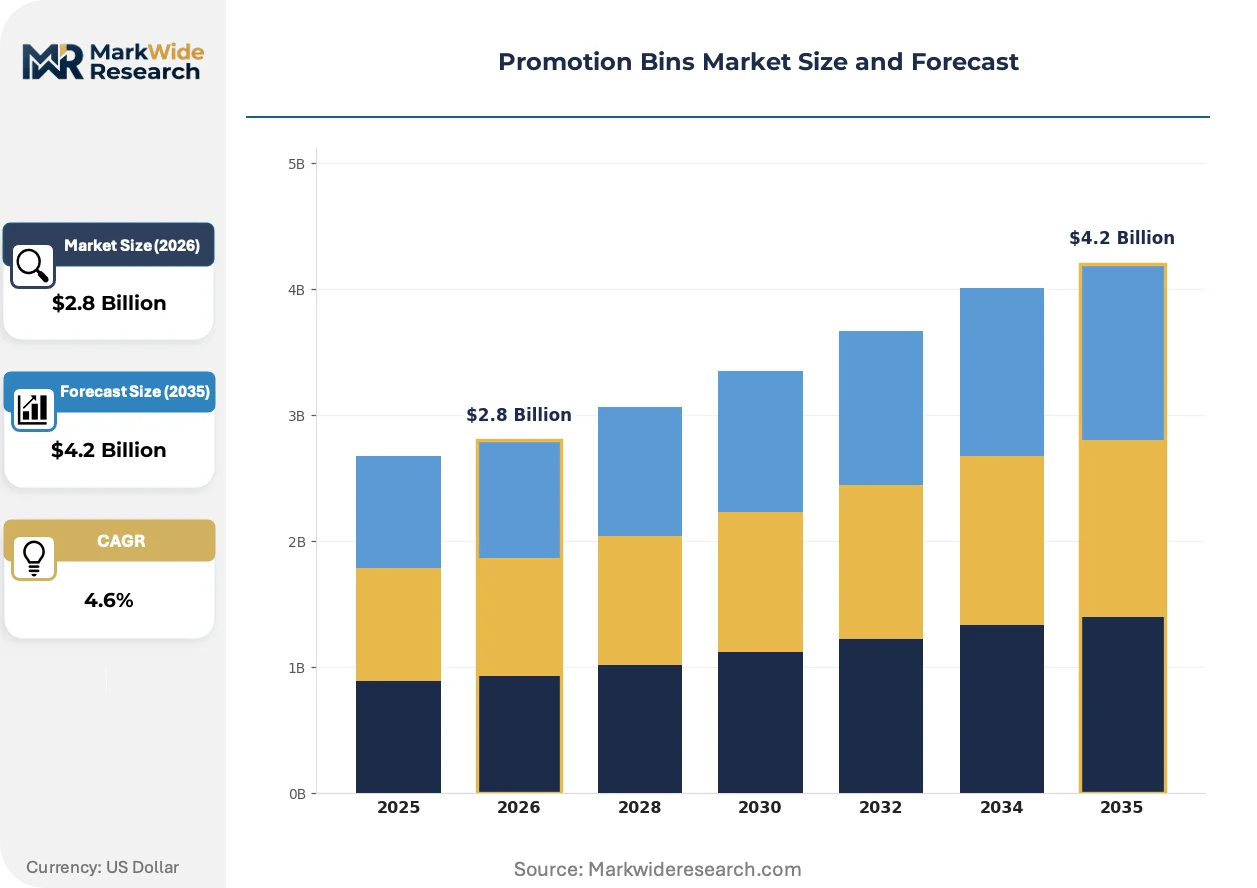
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Compartment Bins, Stackable Bins, Collapsible Bins, Standard Bins Material: Plastic, Metal, Wood, Fabric Application: Retail Displays, Warehouse Storage, Event Marketing, Trade Shows End User: Retailers, E-Commerce Platforms, Event Organizers, Wholesalers |
| Companies Covered | Midway Displays, Inc., Heritage Sign & Display, Henschel-Steinau, WestRock Company, Smurfit Kappa Group, DS Smith, Menasha Packaging Company, Pratt Industries, INDEVCO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Promotion Bins Market Evolving Landscape
Digital workflows and material science advances are compressing design-to-floor timelines while regulatory fragmentation forces modular specification architectures.
Generative design software is virtualizing structural optimization for corrugated bins, allowing engineers to simulate load distribution across hundreds of rib configurations before physical prototyping. Mass merchandisers and grocery chains are adopting these tools to customize footprint dimensions for specific aisle widths. The technology is virtualizing traditional mold-based development cycles, collapsing tooling lead times from weeks to days for promotional campaigns.
REACH substance restrictions on persistent organic pollutants are eliminating certain flame-retardant coatings previously standard in European retail fixtures. Manufacturers serving EU distribution channels must reformulate surface treatments or source alternative barrier technologies. Corrugated fiberboard suppliers with integrated coating capabilities are capturing share from importers unable to certify compliance.
Retailer sustainability scorecards now weight end-of-life recovery pathways above upfront unit cost in vendor selection algorithms. Private-label grocery chains and membership clubs are unbundling fixture procurement from logistics services, awarding separate contracts to specialists in each function. This bifurcation is most pronounced in California and New York, where state mandates accelerate scorecard adoption ahead of national timelines.
Promotion Bins Market Segmentation
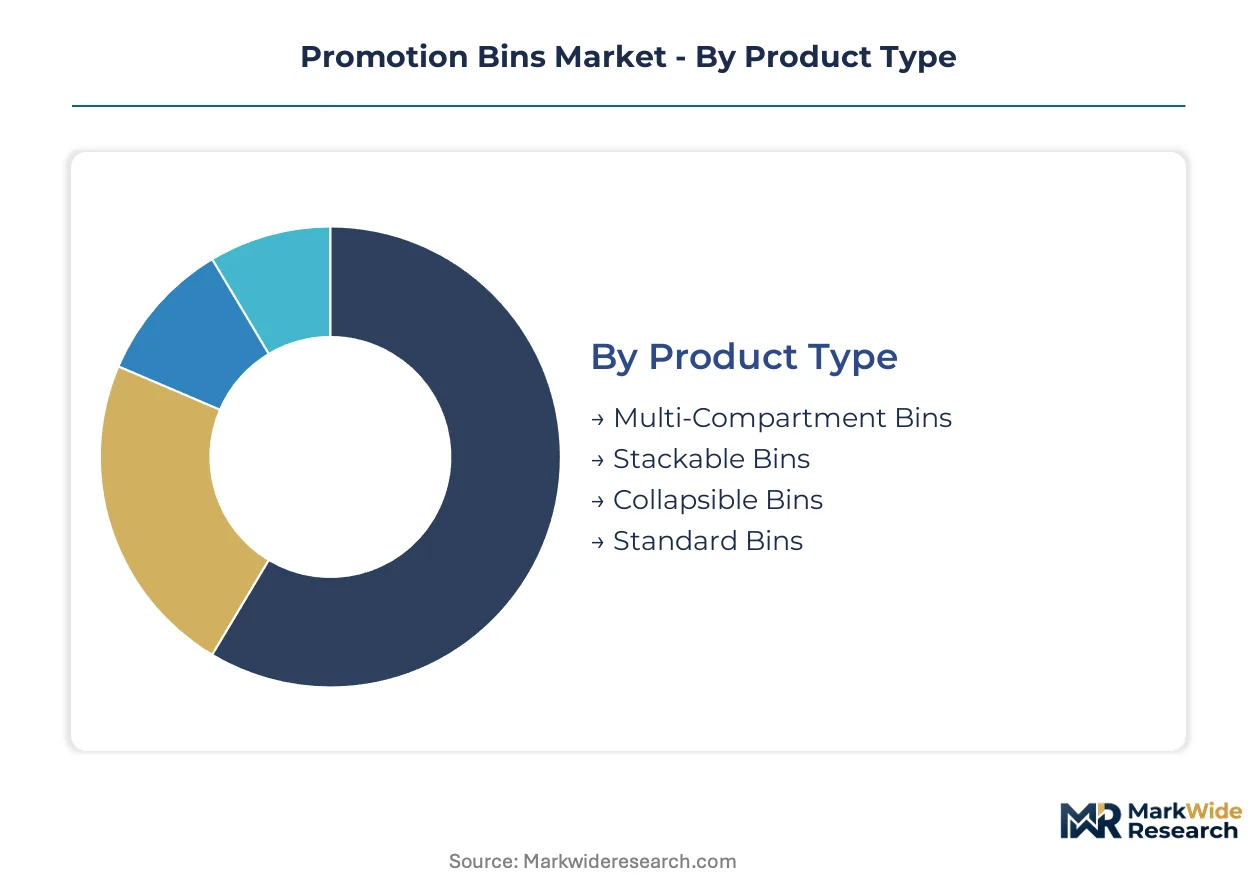
Promotion bins serve divergent operational requirements across retail, logistics, and event verticals. Material selection and structural geometry directly determine palletization efficiency, regulatory compliance, and reverse-logistics economics.
Product Type:
Volume concentration and replenishment velocity separate formats with warehouse-club penetration from those designed for temporary campaign deployment.
- Stackable Bins:Engineered with interlocking rim geometries and specified load capacities for palletization density. Warehouse club operators in the United States specify these for beverage and bulk-grocery aisles where forklift accessibility drives geometry standards.
- Collapsible Bins:Feature hinged sidewalls or nesting profiles that compress cube utilization by sixty percent in backhaul configurations. E-commerce fulfillment networks are adopting these for returns processing and seasonal surge capacity.
- Multi-Compartment Bins:Partitioned internal structures for SKU separation in promotional assortments.
- Standard Bins:Fixed-wall containers for single-product temporary displays.
Stackable bins hold installed capacity. Collapsible bins are rotating up the share rankings.
Material:
Application environment and contact-surface regulations dictate resin selection versus fiberboard or metal specifications.
- Plastic:Injection-molded polypropylene dominates moisture-exposed deployments. FDA food-contact substance regulations restrict resin grades in grocery perimeter departments, forcing validation of migration-compliant formulations for produce and frozen-food applications.
- Metal:Galvanized steel wire frames with powder-coated finishes. Import tariff exposure on Asian wire supply elevates landed costs for domestic assemblers.
- Wood:Pallet-grade hardwoods for heavy-load industrial storage.
- Fabric:Collapsible textile-based containers for lightweight event marketing.
Plastic commands the revenue base. Corrugated fiberboard variants are climbing fastest in sustainability-mandated channels.
Application:
Customer procurement cycles and fixture refresh frequency create divergent margin profiles across use cases.
- Retail Displays:Floor-based promotional fixtures in high-traffic zones. Big-box retailers refresh these quarterly to capture impulse purchases, shortening replacement cycles and sustaining volume for temporary fixture suppliers.
- Warehouse Storage:Semi-permanent inventory organization systems. Club-store format expansion is standardizing load-bearing specifications across pallet patterns.
- Event Marketing:Temporary brand activations with single-use or limited-reuse profiles.
- Trade Shows:Portable exhibition fixtures with collapsibility requirements for freight cost control.
Retail displays anchor manufacturer order books. Warehouse storage applications are expanding most quickly in distribution center buildouts.
End User:
Procurement sophistication and sustainability scorecard adoption separate customer tiers with divergent vendor qualification requirements.
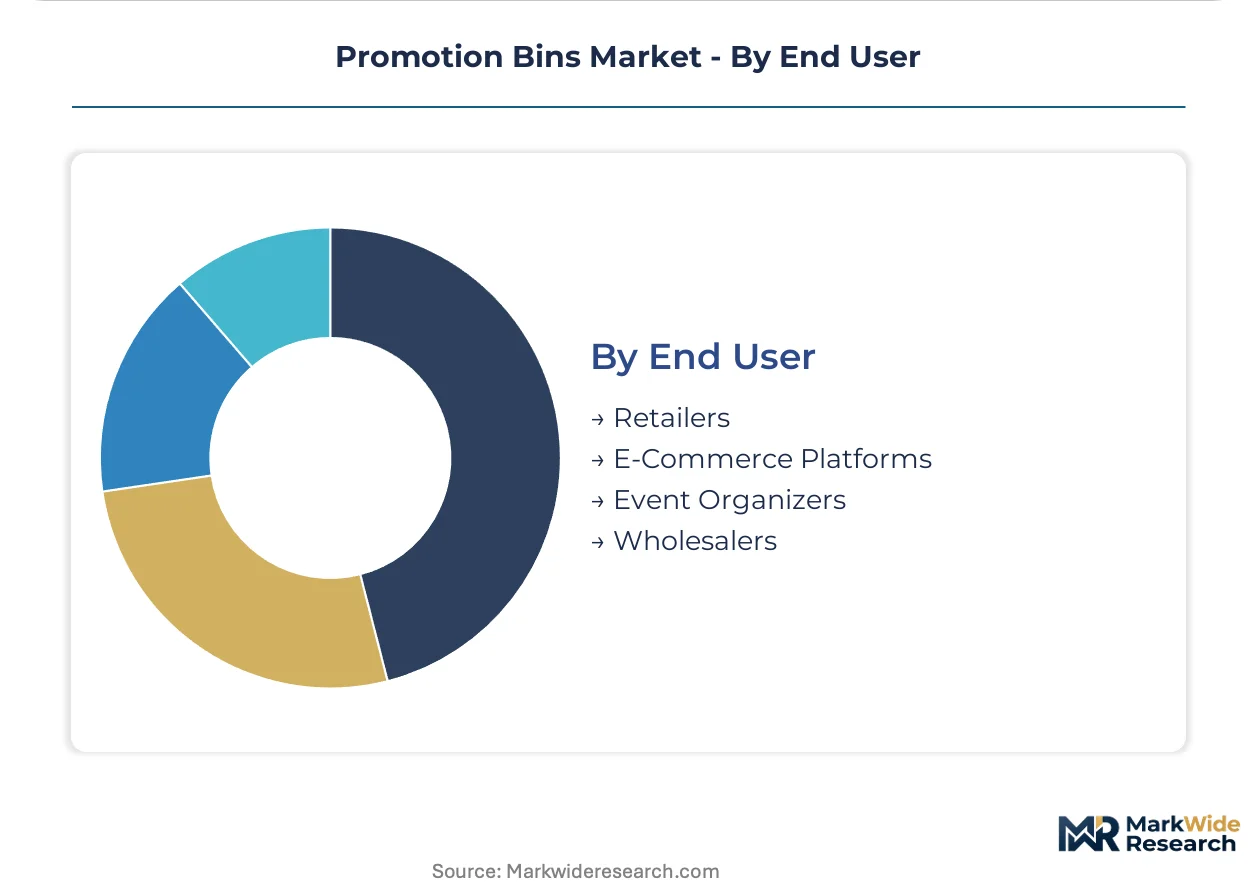
- Retailers:Supermarket chains and mass merchandisers with formalized fixture refresh programs. California and New York state mandates are accelerating sustainability scorecard adoption ahead of national timelines, recalibrating material acceptance thresholds.
- E-Commerce Platforms:Fulfillment networks prioritizing reverse-logistics cost reduction. Collapsible formats reduce backhaul cube utilization, creating procurement preference for nesting geometries.
- Event Organizers:Agencies with project-based procurement and short-lead requirements.
- Wholesalers:Distributors serving fragmented retail accounts with standardized catalog offerings.
Retailers hold installed capacity. E-commerce platforms are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for promotional display fixtures tilt toward net-import positions in Western Europe and North America, while Asian manufacturing clusters supply corrugated fiberboard components to retail chains worldwide. Freight cost inflation and state-level recycled-content mandates are shortening supply lines for North American end-users.
United States
Supermarket chains and big-box retailers drive fixture refresh cycles every 90 days to capture seasonal impulse purchases. California SB 54 and New York state extended producer responsibility frameworks mandate validated end-of-life recovery pathways for temporary displays. The Los Angeles-Long Beach logistics corridor hosts concentrated corrugated converting capacity serving West Coast retail distribution networks.
Germany
Discounters and grocery chains specify reusable display systems with standardized pallet footprints for central warehouse replenishment. REACH substance restrictions on persistent organic pollutants eliminate certain flame-retardant coatings from retail fixture specifications. The Rhine-Ruhr industrial zone anchors integrated paperboard production serving pan-European promotional display demand.
China
Domestic retail expansion and cross-border e-commerce fulfillment networks absorb injection-molded polypropylene bin volumes for moisture-exposed applications. GB standards for food-contact materials govern resin selection in grocery perimeter deployments. The Yangtze River Delta manufacturing belt concentrates corrugated fiberboard and plastic molding capacity for export-oriented display programs.
United Kingdom
Grocery multiples and membership clubs unbundle fixture procurement from logistics services, awarding separate contracts to material specialists. The country's national environmental regulator enforces packaging waste recovery targets that reshape supplier qualification criteria. The Midlands logistics corridor hosts distribution centers specifying collapsible bin formats for reverse-logistics optimization.
India
Modern retail format expansion and quick-commerce fulfillment networks drive demand for temporary point-of-sale fixtures. BIS standards for food-contact materials increasingly influence resin selection in organized grocery channels. The Mumbai-Pune industrial corridor concentrates corrugated converting capacity serving Western India retail distribution networks.
Promotion Bins Market Competitive Landscape
On the supply side, the industry is consolidating around integrated paperboard producers with captive recycled fiber supply and corrugated converters with structural design capabilities. Three archetypes dominate: multinational packaging conglomerates with bundled display programs, mid-scale regional specialists in club-store formats, and asset-light design houses outsourcing manufacturing. Competitive moves center on backward integration into recycled fiber sourcing and geographic expansion through distribution partnerships.
Among integrated North American producers, Pratt Industries exemplifies the recycled-content-focused archetype through its captive paperboard mills. Smurfit Kappa Group occupies a position representing multinational scale with multi-continent corrugated networks. Menasha Packaging Company sits within the structural-specialist tier, anchored in club-store format expertise.
| Leading Market Players |
|---|
| Midway Displays, Inc. |
| Heritage Sign & Display |
| Henschel-Steinau |
| WestRock Company |
| Smurfit Kappa Group |
| DS Smith |
| Menasha Packaging Company |
| Pratt Industries |
| INDEVCO Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Asian corrugated converting capacity is pressuring export pricing into North American channels while simultaneously compressing margins for domestic producers unable to match landed cost structures. This utilization imbalance forces suppliers to choose between absorbing freight inflation or ceding share to integrated producers with captive recycled fiber supply.
Pricing Analysis
Industrial OEM buyers anchor contract structures around corrugated fiberboard spot indices, with three-tier pricing stratification separating virgin-liner premium grades from mixed-pulp standard formulations and test-liner economy tiers. Price differentiation hinges on FDA food-contact certification status and volume commitment scale, with California SB 54 compliance premiums widening spreads as non-compliant suppliers exit state procurement channels. Cost compression in the economy tier is intensifying because OCC collection rate volatility feeds directly into linerboard input costs. Mass merchandisers exhibit highest price sensitivity due to quarterly fixture refresh cycles, while club-store operators prioritize load-rack performance over unit cost.
Supply Chain Analysis
Old corrugated containerboard feedstock draws from municipal recycling streams concentrated in the United States, Germany, and China, with recovered paper quality grading determining finished board strength specifications. Resin selection for injection-molded polypropylene hinges on FDA migration compliance, while galvanized steel wire sourcing rests on tariff-exposed Asian supply bases. Single-source vulnerability in linerboard production elevates risk for converters lacking multi-mill supplier relationships. Distribution runs through retail fixture leasing networks that concentrate purchasing power among big-box operators with balance-sheet capacity to offload inventory risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent point-of-sale fixtures and digital signage represent credible substitution threats that corrugated bin incumbents must navigate through structural design differentiation and sustainability credentialing.
For Market Incumbents: Harden defensibility through backward integration into recycled paperboard production that insulates margin exposure to OCC price volatility. Secure California and New York state regulatory pre-qualification ahead of extended producer responsibility enforcement timelines. Captive fiber supply anchors cost position against Asian import pressure. For New Entrants and Emerging Players: Pursue collapsible bin formats for e-commerce fulfillment networks where reverse-logistics optimization creates procurement preference independent of incumbent retail relationships. Target Midwest distribution center buildouts where seasonal surge capacity demands outstrip existing supplier coverage. Lead with generative design capabilities that compress tooling lead times for short-run promotional campaigns. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across corrugated converting as digital print integration reduces plate-changeover tooling requirements. Mid-scale regional specialists with club-store format expertise represent acquisition targets that fill capability gaps for multinational packaging conglomerates. Watch for retailer sustainability scorecard recalibration as the inflection signal for material acceptance threshold shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber | Captive OCC supply insulates Pratt Industries from linerboard spot volatility. |
| Digital Print Technology Deployment | Direct-to-substrate decoration enables Smurfit Kappa to serve SKU-level customization without plate costs. |
| Collapsible Format Engineering | Hinged sidewall designs reduce backhaul cube utilization for Menasha Packaging's e-commerce clients. |
| State Regulatory Pre-Qualification | California SB 54 compliance certification locks in eligibility for WestRock's retail channel bids. |
| Generative Design Software Adoption | Virtual load-rack simulation collapses structural prototyping timelines for DS Smith's promotional campaigns. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade association data, SEC filings, and customs records, with interviews spanning retail fixture procurement managers, corrugated plant operations directors, sustainability compliance officers at grocery chains, and structural design engineers at display manufacturers. Primary inputs drew from bottom-up shipment tracking across product type, material, and application segments, cross-referenced against top-down demand modeling from retail square footage expansion and fixture refresh cycle data.
Forecast outputs incorporate palletization density specifications, seasonal merchandising intensity indices, and state-level regulatory adoption timelines across the projection horizon. Segmentation dimensions modeled include product type geometry, material compliance tier, end-use procurement cycle, and retailer sustainability scorecard adoption pattern. CAGRs derive from regression analysis against historical replacement volumes and forward-looking retail format expansion plans.
Macroeconomic conditions sit as an overlay; deviation in freight cost indices or OCC collection rates would shift the trajectory for fiberboard-dependent supplier margins. Cross-checking against retail fixture capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Decorative Mylar Balloons Market