
 Gift Packaging Market | 2026-2036
Gift Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Gift Packaging Market Analysis
Artisan paper-folding and structural design talent scarcity is redrawing competitive boundaries in premium gift packaging. Smurfit Kappa leverages its European recycled paperboard infrastructure to anchor sustainable box production at scale. Hallmark Cards sustains brand loyalty through vertically controlled greeting card and wrap ecosystems. DS Smith competes on lightweight corrugated innovation that reduces shipping cube for e-commerce clients.
Gift packaging encompasses containers, wraps, and decorative accessories engineered to protect merchandise while creating anticipatory consumer experience through tactile substrates, color-fast printing, and precision die-cutting. Paper substrates dominate unit volume but fabric and metal formats command margin concentration in luxury channels. The product-type dimension shows boxes and bags capturing structural growth as unboxing content drives social media amplification, while ribbons remain a mature, high-frequency replenishment category. End-user segmentation reveals e-commerce outpacing retail in format innovation as DTC brands demand ship-safe presentation that arrives camera-ready.
FDA indirect food contact rules and EPA recycled fiber standards shape material selection for US-bound gift packaging, while EU REACH and F-Gas Regulation constrain coating chemistry and adhesive formulations. China's GB standards and SAMR labeling mandates determine import compliance for foreign suppliers. Stakeholders must monitor how diverging extended producer responsibility frameworks across jurisdictions will redistribute cost and compliance burdens.
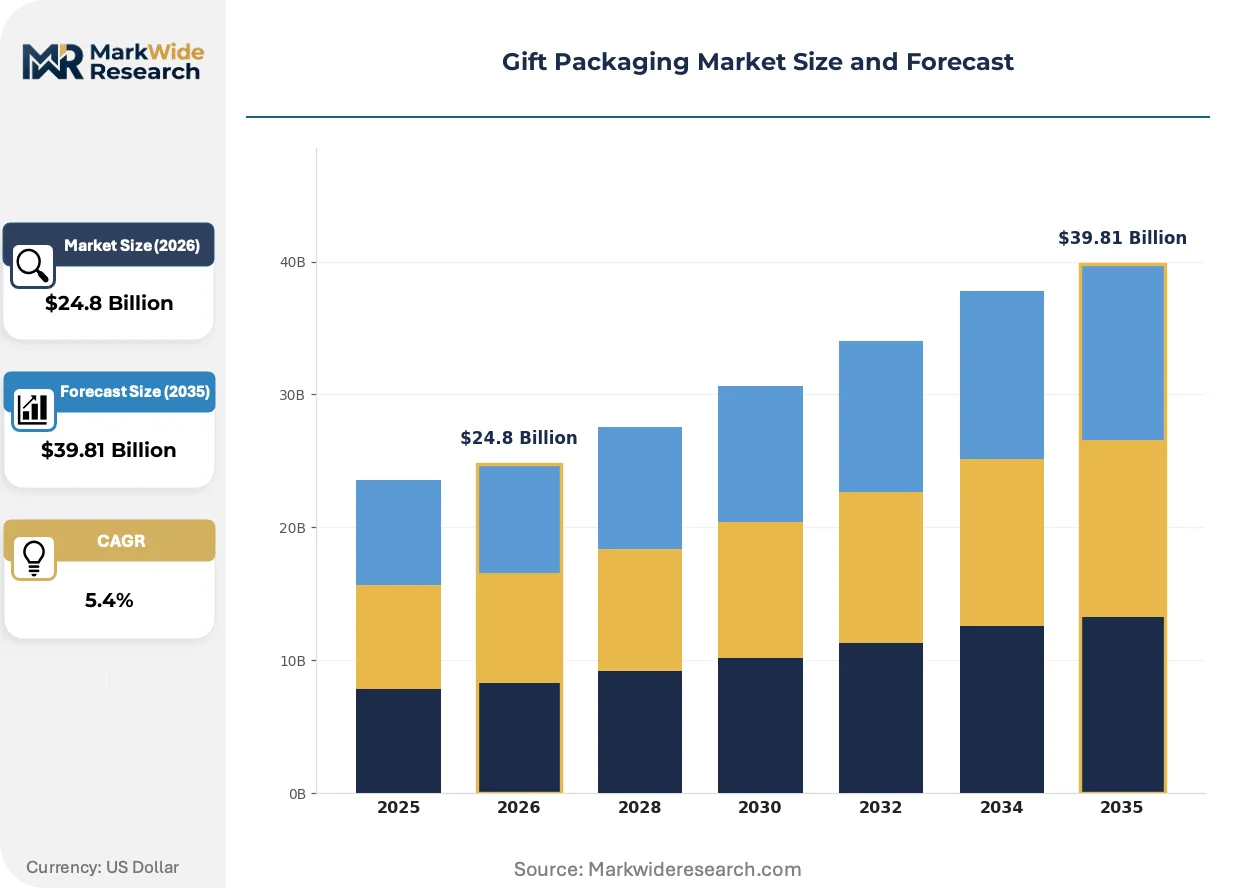
Market Dynamics
Live-stream commerce in China's tier-one cities is compressing design-to-shelf cycles for gift packaging, forcing converters to pre-position inventory around unboxing aesthetics rather than seasonal demand patterns.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled content mandates across member states are pulling fiber-based substrates into premium cosmetic and confectionery applications previously dominated by plastics.
- Live-stream commerce infrastructure:China's tier-one cities now require camera-ready presentation standards that drive replenishment velocity for rigid boxes and decorative accessories.
- Algae-based barrier coatings:Advances in bio-derived moisture resistance are opening food-contact gift packaging segments without fluorochemical treatments.
Market Restraints
- Recovered fiber price volatility:OCC and mixed paper input costs swing with Chinese import quota fluctuations, squeezing converter margins on short-run custom orders.
- Artisan structural design scarcity:Hand-folding talent concentrates in Northern Italy and Japan, limiting premium box production scaling outside these clusters.
- REACH chemical restrictions:EU constraints on adhesive solvents and metallic pigments fragment formulation portfolios, raising SKU complexity for pan-European suppliers.
Strategic Opportunities
- India's tier-two urbanization:Gift-giving customs in cities like Jaipur and Lucknow remain underpenetrated by branded packaging, creating first-mover whitespace for localized design studios.
- Digital print-web finishing convergence:Inline embellishment systems now enable lot sizes below 500 units with foil and embossing, collapsing minimum order thresholds for DTC brands.
- Extended producer responsibility frameworks:Germany's VerpackG and France's AGEC law are creating compliance-service revenue streams for packaging-as-a-service platforms.
Industry Challenges
- Structural origami engineering talent:The pipeline of designers fluent in both paper mechanics and CAD-driven die-line development remains thin across European and North American technical institutes.
- Multi-jurisdiction certification timelines:Simultaneous FDA indirect food contact and EU REACH compliance for metallic substrates stretches product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gift Packaging Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Metal, Fabric Product Type: Boxes, Bags, Wrapping Paper, Ribbons End User: Retail, E-commerce, Corporates, Individuals Theme: Holiday, Birthday, Wedding, Corporate Events |
| Companies Covered | IG Design Group, Hallmark Cards, Smurfit Kappa, Berlin Packaging, Schurman Retail Group, Mondi, Interpak, WestRock Co, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gift Packaging Market Emerging Trajectories
Material substitution and regulatory chemistry constraints are rewriting substrate hierarchies faster than equipment depreciation cycles, forcing converters to bet on finishing flexibility over format specialization.
Water-based barrier coatings is supplanting fluorochemical treatments in premium food-contact gift boxes. Specialty confectionery brands in Switzerland and Belgium are specifying these formulations for chocolate assortments. The shift is compressing the addressable market for legacy grease-resistant papers while opening certified compostable positioning.
EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents are reshaping molded pulp cushioning for fragile gift items. Manufacturers are retrofitting thermal forming lines with CO2-based alternatives. High-end electronics unboxing experiences in Germany and the Netherlands face the steepest cost recalibration.
Subscription box procurement now specifies ship-safe presentation as a core vendor criterion, not a post-negotiation add-on. Beauty and wellness DTC brands in California and New York are consolidating supplier relationships around converters with in-house structural testing labs. This consolidation is most visible in the consolidation of ribbon and tissue vendors into full-service presentation kit providers.
Gift Packaging Market Segmentation
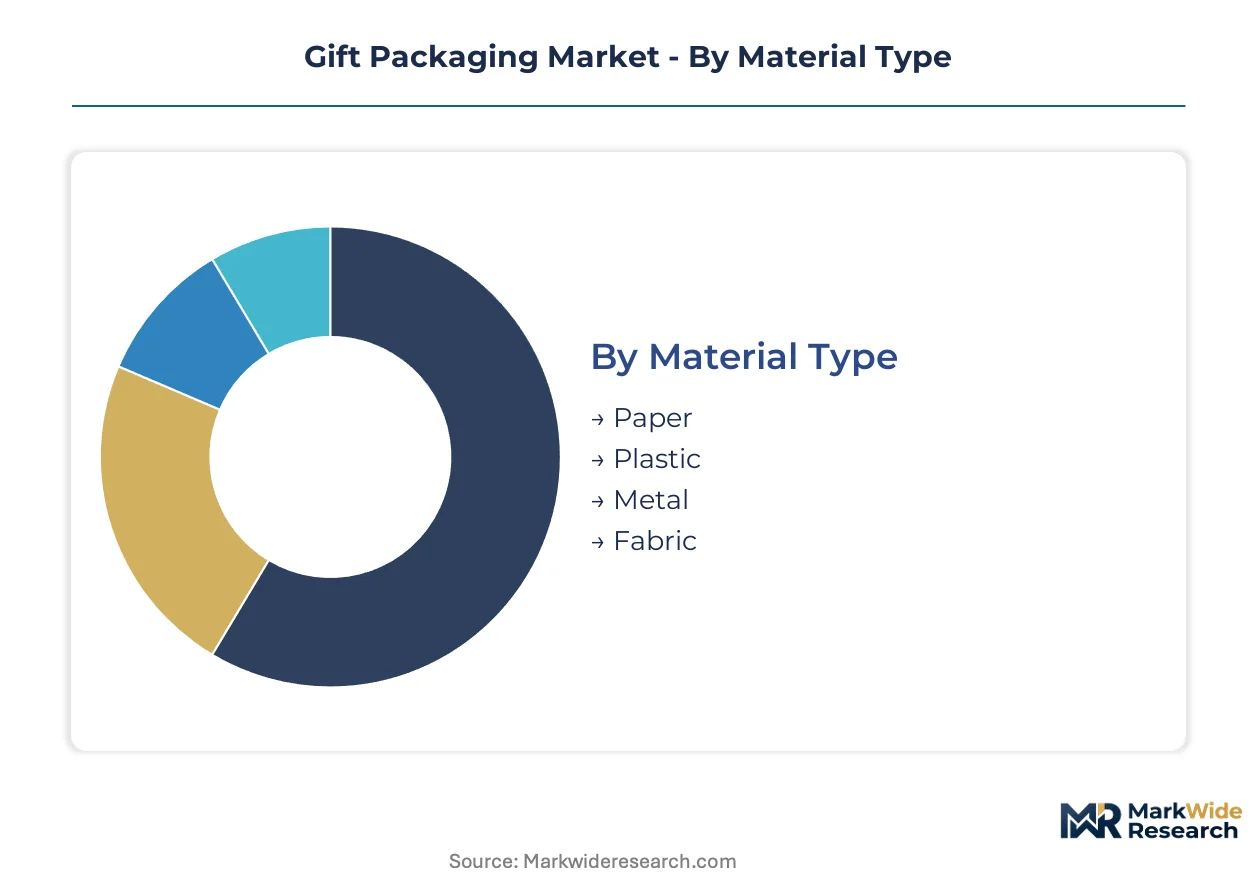
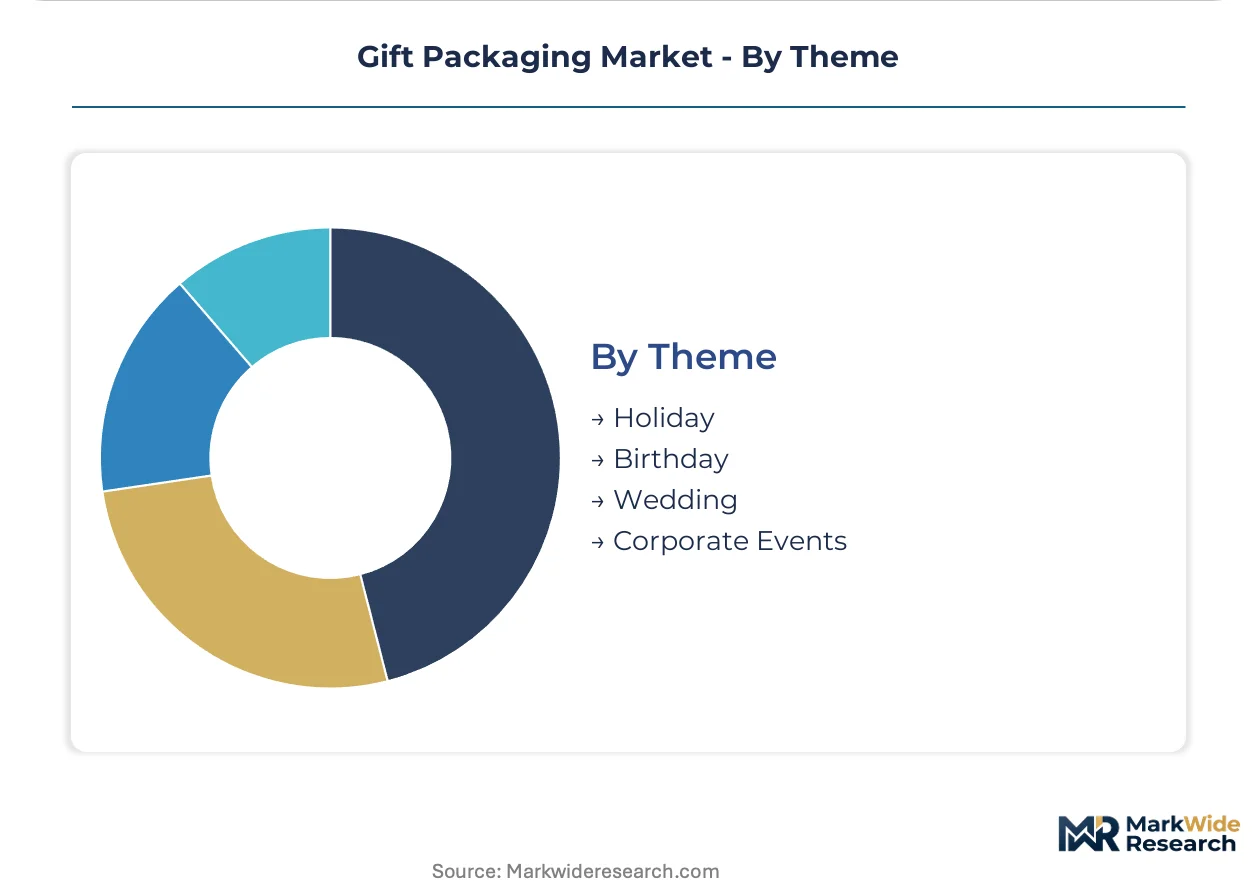
Gift packaging segmentation reveals divergent margin profiles across material hierarchies and channel formats. Understanding these fault lines exposes where converters can defend pricing power versus where commoditization pressures dominate procurement cycles.
Material Type:
Paper formats anchor domestic production in Germany and the United States, while metal and fabric segments concentrate export flows from China and India.
- Paper:Recycled paperboard and kraft substrates constitute the volume foundation, with European converters leveraging FSC-certified fiber streams to meet EU Packaging and Packaging Waste Regulation mandates. German and French premium cosmetics brands now specify minimum 70% recycled content for rigid boxes.
- Plastic:PET and polypropylene formats are contracting in European gift applications as REACH restrictions on additives and EPR fees reshape total cost economics. Chinese manufacturers dominate export supply of transparent rigid boxes for electronics unboxing.
- Metal:Tinplate and aluminum tins command margin concentration in luxury confectionery and spirits gifting, with Swiss and Belgian chocolate houses specifying these for heritage positioning.
- Fabric:Silk and jute pouches serve premium jewelry and artisanal cosmetic segments, with Indian textile clusters in Surat and Varanasi supplying embroidered drawstring formats to UK and UAE retailers.
Paper holds the largest share; momentum sits with fabric as DTC brands seek tactile differentiation.
Product Type:
Structural complexity separates segments by tooling investment requirements, with rigid formats demanding die-line engineering capabilities that concentrate among Northern Italian and Japanese converters.
- Boxes:Rigid setup boxes and folding cartons capture the steepest expansion trajectory as unboxing content drives social media amplification. California and New York beauty DTC brands now require ship-safe structural testing as a core vendor criterion.
- Bags:Laminated paper and non-woven polypropylene formats dominate high-velocity retail replenishment, with Chinese converters in Zhejiang province scaling automated handle-attachment lines for European fast-fashion clients.
- Wrapping Paper:Roll-stock formats face margin compression from digital print substitution, though metallic and holographic finishes retain pricing power in UK and German holiday seasons.
- Ribbons:Grosgrain and satin trims constitute a mature replenishment category with stable demand curves, concentrated among vertically integrated greeting card ecosystems.
Boxes command the highest value-add; bags deliver volume velocity for mass-market penetration.
End User:
Channel procurement patterns split between specification-heavy DTC consolidation and fragmented retail spot-buying, with corporate segments demanding compliance documentation that favors established suppliers.
- Retail:Brick-and-mortar chains in Germany and Japan prioritize shelf-ready packaging with standardized cube efficiency, constraining format innovation to proven die-lines.
- E-commerce:Direct-to-consumer brands in China's tier-one cities and California's Bay Area now specify camera-ready presentation as a non-negotiable vendor criterion, collapsing design-to-shelf cycles.
- Corporates:B2B gifting programs in financial services and technology sectors require batch customization with short lead times, favoring converters with digital print-web finishing convergence.
- Individuals:Consumer-assembled kits and subscription boxes drive replenishment demand for tissue, filler, and accessory components, concentrated in US and UK markets.
Retail maintains volume dominance; e-commerce is climbing the fastest on per-unit value expansion.
Theme:
Seasonal concentration risk varies dramatically, with holiday formats demanding inventory pre-positioning that strains converter working capital while corporate events offer year-round demand smoothing.
- Holiday:Christmas and Lunar New Year formats drive peak capacity utilization, with Chinese converters producing red-and-gold rigid boxes for domestic live-stream commerce and Southeast Asian export.
- Birthday:Age-specific and generational design trends fragment SKU portfolios, though digital print enables economical short runs below 500 units.
- Wedding:Custom monogramming and foil stamping command premium pricing, with Italian and French converters capturing high-end European bridal market share.
- Corporate Events:Branded presentation kits for product launches and employee recognition programs prioritize consistency over novelty, locking in multi-year supplier relationships.
Holiday captures peak revenue concentration; corporate events provide the most stable margin profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium gift packaging commands pricing power in Switzerland and Belgium that outstrips comparable formats manufactured in China's Zhejiang province by margins exceeding forty percent. This asymmetry reflects divergent regulatory burdens, labor specialization, and brand proximity to luxury end-markets rather than raw material costs alone.
United States
Direct-to-consumer beauty brands in California and New York now mandate ship-safe structural testing as a core vendor criterion, collapsing traditional procurement timelines. FDA indirect food contact rules and EPA recycled fiber standards constrain material selection for imported substrates. Converter consolidation concentrates in the Midwest, where digital print-web finishing capabilities cluster around Chicago and Detroit industrial corridors.
Germany
VerpackG extended producer responsibility frameworks create compliance-service revenue streams for packaging-as-a-service platforms serving corporate gifting programs. EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents force retrofitting of molded pulp thermal forming lines. High-end electronics unboxing experiences in Bavaria and North Rhine-Westphalia face steep cost recalibration as CO2-based alternatives displace legacy chemistry.
China
Live-stream commerce infrastructure in Shanghai, Beijing, and Shenzhen compresses design-to-shelf cycles, forcing converters to pre-position inventory around unboxing aesthetics rather than seasonal patterns. SAMR labeling mandates and GB standards determine import compliance thresholds for foreign suppliers. Zhejiang province scales automated handle-attachment lines for European fast-fashion clients while domestic rigid box production concentrates in Guangdong for premium cosmetics.
India
Gift-giving customs in Jaipur and Lucknow remain underpenetrated by branded packaging, creating first-mover whitespace for localized design studios. BIS certification requirements for food-contact materials shape substrate selection for confectionery exporters. Surat and Varanasi textile clusters supply embroidered silk and jute pouches to UK and UAE retailers, anchoring the fabric segment's margin concentration.
Japan
Artisan paper-folding talent concentrates in Tokyo and Osaka, limiting premium box production scaling outside these metropolitan clusters. METI standards for sustainable packaging drive specification of FSC-certified fiber streams in corporate gifting programs. Northern Italian and Japanese technical institutes remain the primary pipelines for designers fluent in both paper mechanics and CAD-driven die-line development.
Gift Packaging Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the gift packaging value chain. The market structure fragments between European converters with recycled paperboard infrastructure, vertically integrated greeting card ecosystems, and Asian fabricators scaling automated production lines. Three archetypes dominate: sustainability-certified substrate specialists, full-service presentation kit providers, and lightweight corrugated innovators. Competitive moves concentrate on M&A to secure structural design talent and strategic partnerships to access live-stream commerce supply chains.
Among European converters, Smurfit Kappa and DS Smith occupy positions as anchors for sustainable box production and lightweight corrugated innovation respectively. Hallmark Cards exemplifies the vertically integrated archetype controlling greeting card and wrap ecosystems. These three companies represent the divergent strategic paths—substrate infrastructure, format specialization, and vertical integration—that define competitive positioning in premium and mass-market segments.
| Leading Market Players |
|---|
| IG Design Group |
| Hallmark Cards |
| Smurfit Kappa |
| Berlin Packaging |
| Schurman Retail Group |
| Mondi |
| Interpak |
| WestRock Co |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
Water-based barrier coatings displacing fluorochemical treatments in premium food-contact gift boxes simultaneously redraws supply geography toward EU-certified converters and compresses pricing power for legacy grease-resistant paper manufacturers. This substitution dynamic concentrates margin capture among Swiss and Belgian specialty confectionery suppliers while forcing cost recalibration across Asian export-oriented producers.
Pricing Analysis
Premium-mid-economy pricing differentiation separates rigid setup boxes from laminated paper bags and roll-stock wrapping formats. Price differentiation hinges on FSC certification grade and structural testing documentation, with California DTC beauty brands paying premiums for ship-safe validation. Cost compression in mid-tier corrugated runs through recovered fiber price volatility tied to Chinese import quota fluctuations. Mass-market retail chains exhibit highest price sensitivity, while luxury cosmetics houses in Germany and France accept substantial premiums for minimum recycled content compliance.
Supply Chain Analysis
China and India anchor global fabrication capacity, with Zhejiang province scaling automated bag production and Guangdong concentrating rigid box manufacturing for premium cosmetics. Raw material flows draw from European FSC-certified fiber streams, Surat silk clusters, and OCC recovered paper markets. Single-source vulnerability concentrates in Northern Italian and Japanese artisan paper-folding talent pools. Distribution runs through packaging-as-a-service platforms serving corporate gifting programs, with DTC brands consolidating vendor relationships around full-service presentation kit providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural origami engineering talent scarcity constrains premium box production scaling outside Tokyo, Osaka, and Northern Italian clusters, creating defendable moats for converters with in-house CAD-driven die-line capabilities.
For Market Incumbents: Consolidate structural design talent through targeted acquisitions of Japanese and Northern Italian technical studios to defend against Asian automated production lines encroaching on premium segments. Deepen backward integration into FSC-certified fiber streams to secure EU Packaging and Packaging Waste Regulation compliance margins. Lock in multi-year supplier relationships with corporate gifting programs through packaging-as-a-service platform investments. For New Entrants and Emerging Players: Compliance-service gaps around Germany's VerpackG and France's AGEC law create whitespace for localized packaging-as-a-service platforms targeting mid-cap corporate clients. India's tier-two urbanization in Jaipur and Lucknow offers the most penetrable geography, with branded packaging penetration lagging gift-giving customs. Pursue digital print-web finishing convergence enabling lot sizes below 500 units to capture DTC brand procurement consolidation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European converters holding recycled paperboard infrastructure but lacking live-stream commerce supply chain access. Long-term viability favors sustainability-certified substrate specialists with regulatory compliance moats across multiple jurisdictions. Watch algae-based barrier coating certification timelines as inflection indicator for food-contact segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Structural Design Studios | Secures scarce origami engineering talent in Tokyo and Northern Italy for premium box scaling. |
| Digital Print-Web Finishing Convergence | Enables sub-500-unit production runs for California and New York DTC beauty brands. |
| Packaging-as-a-Service Platform Launch | Captures VerpackG and AGEC compliance-service revenue streams in Germany and France. |
| Algae-Based Barrier Coating Certification | Opens Swiss and Belgian chocolate confectionery food-contact segments without fluorochemicals. |
| Live-Stream Commerce Supply Chain Partnership | Pre-positions inventory around unboxing aesthetics for Shanghai and Beijing tier-one demand. |
Methodological Framework
Operator-level perspectives from structural packaging engineers, DTC brand procurement leads, converter plant managers, and regulatory compliance officers anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, SAMR labeling mandate databases, FSC certification registries, and customs trade data for paper substrate flows. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from production capacity assessments.
Sensitivity analysis tested forecast outputs against recovered fiber price volatility scenarios and live-stream commerce penetration trajectories across the analysis window. Segmentation dimensions modeled include material type, product format, end-user channel, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating unboxing content amplification effects and extended producer responsibility fee structures. Industry-specific inputs encompassed die-line tooling investment cycles and algae-based coating certification timelines.
Forecasts assume regulatory continuity in EU REACH, FDA indirect food contact, and China GB standards regimes; material policy shifts would require re-modeling. Specific risks include artisan talent pipeline constraints, multi-jurisdiction certification timeline extensions, and Chinese import quota volatility. Recalibration cycles align with material shifts in live-stream commerce infrastructure deployment and extended producer responsibility framework adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Luxury Packaging Market