
 Global in Store Theater Packaging Market | 2026-2036
Global in Store Theater Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global in Store Theater Packaging Market Intelligence
A divergence in capital for high-speed digital printing and automated assembly lines is unwinding the competitive landscape. Large-scale producers like WestRock leverage extensive manufacturing networks to serve multinational consumer goods clients with consistent quality. Smurfit Kappa Group sustains its market position through deep backward integration into corrugated fiberboard production, ensuring supply stability. Meanwhile, DS Smith differentiates through its focus on circular design principles and customized packaging solutions for European retailers.
In-store theater packaging refers to promotional, free-standing display units constructed primarily from materials like corrugated fiberboard. These structures are engineered for temporary use at the point of sale to create a visually impactful product presentation. Corrugated fiberboard remains the dominant packaging material due to its structural integrity, low cost, and superior printability for graphics. Within applications, the snack foods segment commands a significant share, driven by frequent promotional campaigns in supermarkets and convenience stores.
Material selection and safety standards are governed by multiple international bodies. In the United States, the FDA sets guidelines for materials in direct contact with food, while in Europe, regulations like REACH and the Packaging and Packaging Waste Regulation influence material choices and mandate recyclability targets. Future competitive advantage will be determined by a supplier's capacity to navigate these complex regulatory environments while delivering rapid, customized design services.
Market Dynamics
The central dynamic shaping the market is the pressure from sustainability regulations, such as the EU Green Deal. This force mandates a transition to recyclable, fiber-based materials while consumer brands simultaneously demand more visually complex and cost-effective promotional displays.
Growth Catalysts
- Sustainable Material Mandates:Regulations like the EU's Packaging and Packaging Waste Regulation are accelerating the transition to corrugated fiberboard and other recyclable materials, creating demand for compliant display solutions from consumer goods companies.
- Promotional Frequency in Food Retail:The high frequency of new product introductions and seasonal campaigns within the snack foods and confectionery segments drives consistent demand for temporary, eye-catching point-of-sale displays in supermarkets.
- Retail Channel Competition:Intense competition among supermarkets, hypermarkets, and convenience stores, particularly in the United States, supports the use of in-store theater packaging as a key tool for brand differentiation and sales lift.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials, specifically corrugated fiberboard and paper pulp, create margin pressure for manufacturers and unpredictability in project costing for end-clients.
- Digital Advertising Substitution:The increasing use of digital screens and dynamic in-aisle media presents a long-term substitution threat, offering an alternative to physical displays for in-store promotions.
- Complex Food-Contact Regulations:Adherence to stringent food-contact material standards, such as those set by the FDA in the US and REACH in Europe, adds complexity and cost to the design and production process.
Strategic Opportunities
- Interactive Display Integration:The convergence of physical displays with digital technology, such as embedded QR codes or NFC chips, offers an opportunity to create engaging, data-rich consumer experiences at the point of sale.
- Expansion into Non-Food Categories:There is significant opportunity for growth in underpenetrated retail segments like consumer electronics, personal care, and home goods, which are beginning to adopt similar promotional tactics.
- Circular Design Services:Offering specialized design services focused on circularity, including easy disassembly and mono-material construction, provides a value-added differentiator for suppliers targeting sustainability-focused brands.
Industry Challenges
- Capital for Automation:The significant capital expenditure required to invest in high-speed digital printing presses and automated assembly lines creates a barrier to entry and a competitive hurdle for smaller producers.
- Structural Design Talent Gap:A persistent shortage of skilled structural designers who can blend creative aesthetics with the material science of corrugated fiberboard limits innovation and speed to market.
- Logistical Complexities:Managing the just-in-time logistics for delivering bulky, pre-assembled, or kitted displays to geographically dispersed retail locations without damage remains a significant operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in Store Theater Packaging Market |
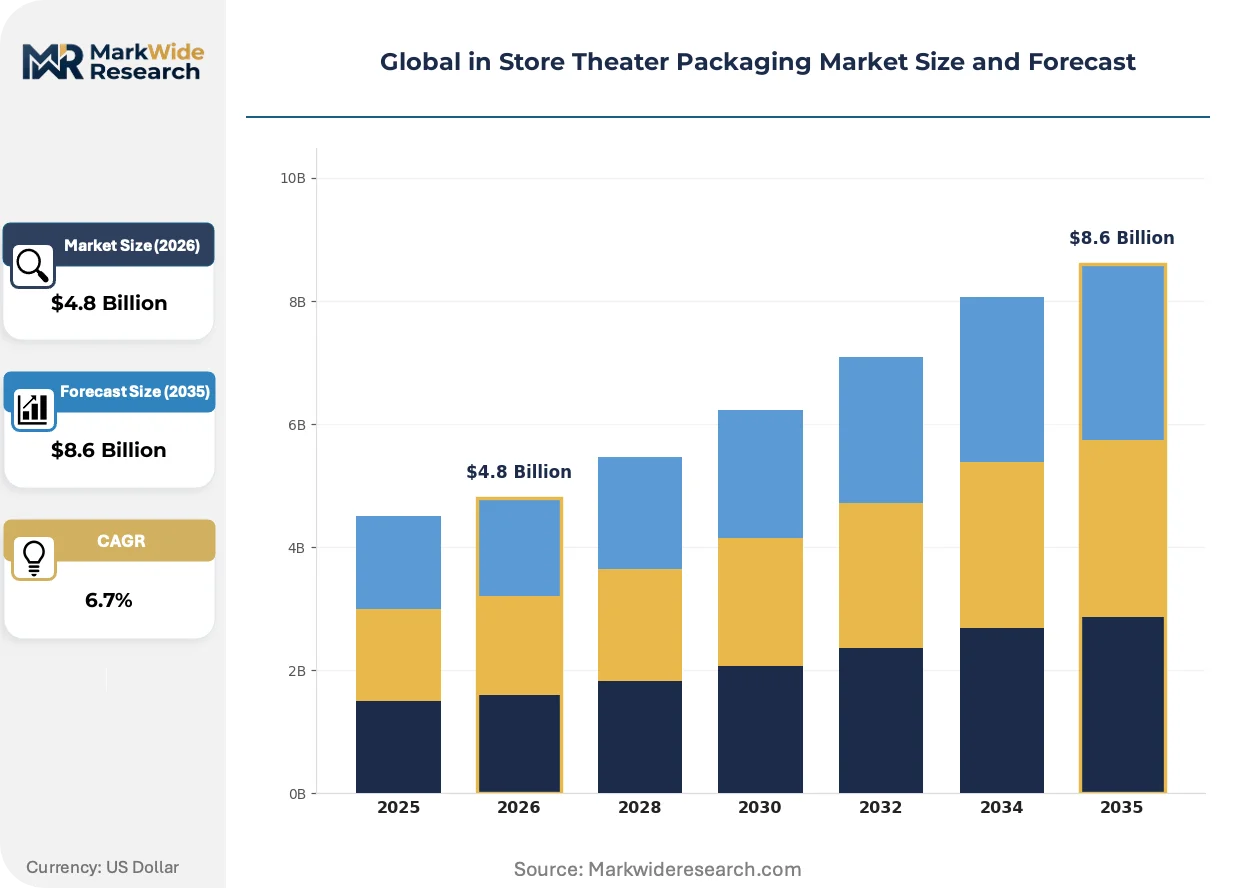
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard Boxes, Plastic Clamshells, Blister Packs, Paper Bags, Foil Wraps Packaging Material: Corrugated Fiberboard, PET Plastic, PVC Film, Aluminum Foil, Kraft Paper Application: Snack Foods, Beverage Containers, Confectionery, Frozen Foods, Ready Meals End User: Supermarkets, Convenience Stores, Specialty Food Stores, Cinema Concessions |
| Companies Covered | Smurfit Kappa Group, DS Smith, WestRock, International Paper, Menasha Packaging, Pratt Industries, Georgia-Pacific, Graphic Packaging International, VPK Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in Store Theater Packaging Market Strategic Shifts & Innovations
Investment in digital workflows and sustainable material science is reshaping design and production capabilities. This shift allows for greater customization and faster turnaround times, aligning with the promotional cycles of fast-moving consumer goods brands and evolving retailer requirements.
High-speed digital printing technology enables the production of short-run, versioned, and personalized graphics directly onto corrugated substrates. Consumer goods brands are rapidly adopting this for targeted regional promotions, retailer-specific campaigns, and new product test marketing. This capability is fragmenting the traditional, long-run analog printing model by making hyper-customization economically viable for promotional displays.
The EU's Packaging and Packaging Waste Regulation (PPWR) establishes aggressive targets for recyclability and the use of recycled content. This directive effectively forces a move away from plastic-laminated or mixed-material displays toward mono-material, fiber-based structures that are easier to recycle. The food and beverage sectors are most affected, actively redesigning their point-of-sale programs to ensure compliance in the European market.
A behavioral shift among large retailers increasingly favors packaging that serves as both a shipping container and a ready-to-display unit on the sales floor. This model disrupts the conventional supply chain where products are shipped in bulk and then loaded into a separate display structure in-store. This trend is most prominent in North American and European grocery channels, driven by the need to improve labor efficiency and speed up shelf replenishment.
Global in Store Theater Packaging Market Segmentation
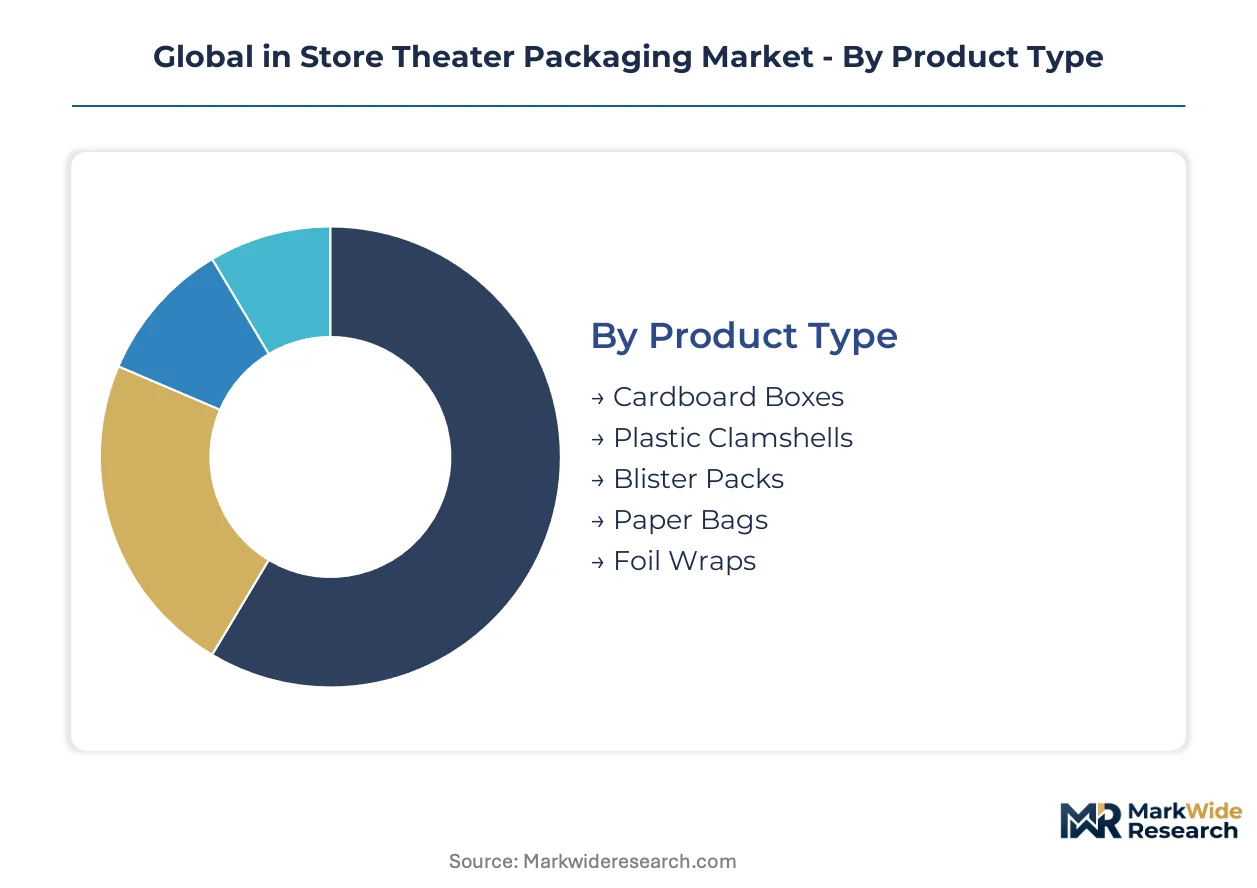
Understanding the segmentation within the global in-store theater packaging market reveals the diverse functional requirements and material preferences across retail environments. This granular breakdown helps identify specific design challenges and opportunities for compliance with evolving sustainability mandates. Each segment reflects unique demands for visual impact, structural integrity, and logistical efficiency at the point of sale.
Product Type:
The product type segmentation highlights areas where traditional physical displays face substitution pressure from digital alternatives or where material innovation creates new display formats.
- Cardboard Boxes:These are constructed primarily from corrugated fiberboard, offering robust structural integrity and superior printability for graphics. Demand concentrates in the snack foods sector, driven by their cost-effectiveness and ease of recycling in European markets.
- Plastic Clamshells:Formed from transparent PET or PVC, these units provide high product visibility and tamper resistance for premium items. Their use is under increasing scrutiny due to single-use plastic regulations, particularly in the United States and Europe.
- Blister Packs:Typically combine a thermoformed plastic bubble with a paperboard backing, common for small consumer goods.
- Paper Bags:Used for lighter promotional items, these offer a recyclable alternative but lack the structural rigidity of fiberboard displays.
- Foil Wraps:Primarily serve as protective packaging for food items within a larger display, offering barrier properties for freshness.
Cardboard Boxes retain volume leadership; Paper Bags hold the steepest expansion curve.
Packaging Material:
The packaging material segment reflects different cost structures and performance attributes, influencing both display durability and sustainability profiles.
- Corrugated Fiberboard:This material forms the backbone of most in-store theater packaging due to its strength-to-weight ratio and excellent print surface. Its adoption is accelerating in the United States and Europe, driven by recyclability mandates.
- Kraft Paper:Valued for its natural aesthetic and recyclability, Kraft paper is increasingly used for sustainable display elements and internal structural components. Demand for this material is rising with circular design principles.
- PET Plastic:Offers transparency and impact resistance, frequently used for windows or full clamshells, though facing regulatory pressure.
- PVC Film:Provides high clarity and rigidity for certain display applications, but its environmental impact limits widespread adoption in Europe.
- Aluminum Foil:Primarily functions as a barrier material within food packaging, often integrated into multi-material display structures.
This segment's evolution is driven by material science advancements and regulatory shifts.
Application:
The application segment illustrates how specific product categories leverage in-store theater packaging for distinct promotional objectives and consumer engagement strategies.
- Snack Foods:This sector commands a significant share, utilizing displays for frequent new product launches and seasonal promotions in supermarkets and convenience stores. Campaigns in the United States heavily rely on these temporary units.
- Confectionery:Brands in this segment frequently employ visually appealing displays to drive impulse purchases and highlight seasonal offerings. Point-of-sale displays are critical for product visibility in European grocery aisles.
- Beverage Containers:Displays for beverages often focus on brand visibility and multi-pack promotions, particularly in hypermarkets.
- Frozen Foods:Requires specialized display solutions that can withstand cold temperatures while maintaining visual appeal in freezer aisles.
- Ready Meals:Packaging for ready meals emphasizes convenience and product differentiation, often integrating into larger store-ready display units.
Promotional frequency and product visibility remain central drivers across these diverse applications.
End User:
The end-user segment differentiates the specific retail environments that deploy in-store theater packaging, each with unique logistical and merchandising requirements.
- Supermarkets:These large-format retailers are primary consumers of in-store theater packaging, leveraging displays for extensive promotional campaigns and seasonal product features. High volume sales in Europe and the United States necessitate efficient display solutions.
- Convenience Stores:Characterized by high foot traffic and impulse purchases, these stores rely on compact, eye-catching displays to maximize product visibility in limited spaces. Competition in the United States drives frequent display refreshes.
- Specialty Food Stores:These outlets use displays to highlight premium, artisanal, or niche products, often with a focus on aesthetic quality.
- Cinema Concessions:Displays here promote impulse purchases of snacks and drinks, designed for quick transactions and high visual impact.
Each end-user channel demands tailored display solutions to optimize consumer engagement and sales conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global in-store theater packaging market exhibits distinct regional demand and supply dynamics. Some countries are net exporters of corrugated fiberboard, influencing display production costs in import-reliant regions. This balance shapes competitive pricing and material availability across continents for promotional displays.
United States
Demand for in-store theater packaging in the United States is driven by intense competition among supermarkets and convenience stores. Frequent promotional campaigns for snack foods and new product launches necessitate visually impactful displays. FDA guidelines for food-contact materials influence design choices, ensuring safety and compliance for consumer goods. Major retail hubs like Chicago and Los Angeles see continuous deployment of these units.
Germany
Germany's market for in-store theater packaging is significantly influenced by the EU Green Deal and its sustainability mandates. Consumer brands prioritize recyclable fiber-based solutions to meet Packaging and Packaging Waste Regulation targets. Manufacturers in regions like North Rhine-Westphalia focus on circular design principles and mono-material construction. This creates demand for compliant, high-quality corrugated displays.
China
China's vast consumer market and expanding retail infrastructure fuel demand for promotional packaging. Brands leverage in-store theater displays for new product introductions and seasonal promotions in hypermarkets. GB standards for packaging materials guide production, ensuring product safety and environmental performance. Manufacturing clusters in the Yangtze River Delta actively produce diverse display solutions.
India
The Indian market for in-store theater packaging is experiencing growth due to the expanding organized retail sector and rising consumer spending. Frequent promotional activities for fast-moving consumer goods, especially snack foods, drive display adoption. BIS standards for paper and paperboard packaging ensure material quality and recyclability. Major metropolitan areas like Mumbai and Delhi witness high deployment of these promotional units.
United Kingdom
In the United Kingdom, retail channel competition and sustainability goals shape the in-store theater packaging market. Brands require eye-catching displays that also comply with evolving recyclability targets set by the UK's packaging regulations. Companies in the Southeast of England focus on rapid prototyping and customized solutions for major grocery chains. This ensures effective point-of-sale engagement for shoppers.
Global in Store Theater Packaging Market Key Industry Players
Concentration sits with large, integrated packaging producers that leverage extensive manufacturing networks. The competitive structure is tiered, featuring multinational corporations alongside specialized regional providers. Dominant strategic archetypes include large-scale integrated producers, offering consistent quality, and agile custom solution providers. Key competitive moves involve capacity expansion in sustainable materials and portfolio diversification into new retail categories.
At the scale-driven end, Smurfit Kappa Group sustains its market position through deep backward integration into corrugated fiberboard production. WestRock, a major US-based producer, leverages its extensive manufacturing network to serve multinational consumer goods clients. DS Smith, a UK-based company, differentiates through its focus on circular design principles and customized packaging solutions for European retailers.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| WestRock |
| International Paper |
| Menasha Packaging |
| Pratt Industries |
| Georgia-Pacific |
| Graphic Packaging International |
| VPK Group |
| Others |
Cost & Logistics Intelligence
Scale economies in corrugated fiberboard production drive market consolidation. This concentration influences pricing power and establishes competitive price floors for display units.
Pricing Analysis
Consumer goods brands anchor project-based transactional pricing for in-store theater packaging. Price differentiation stems from customization levels and geographic delivery costs for bulky displays. Pricing softness reflects intense competition among packaging suppliers, particularly for high-volume orders. Snack food brands are highly price-sensitive, while specialty food stores prioritize aesthetic quality and unique design.
Supply Chain Analysis
The United States and Germany anchor corrugated fiberboard production for in-store theater packaging. The supply chain relies on consistent availability of paper pulp, a key raw material. Commodity price volatility for paper pulp creates a structural risk for manufacturers. Distribution runs through direct-to-retailer logistics, often involving just-in-time delivery of pre-assembled display units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-store theater packaging market presents a fragmentation opportunity, driven by evolving retailer requirements for store-ready displays. This shift creates niches for suppliers offering efficient, customized solutions for diverse retail environments.
For Market Incumbents: Compound extensive manufacturing networks with strategic investments in automated assembly lines to counter rising labor costs. Deepen backward integration into corrugated fiberboard production to mitigate input cost volatility. Invest in capacity addition in Europe to meet increasing demand for compliant fiber-based solutions. This strategy helps defend against digital advertising substitution and margin pressure.
For New Entrants and Emerging Players: Differentiate on rapid, customized design services for emerging non-food categories like consumer electronics. Target underpenetrated segments such as specialty food stores with innovative, aesthetically driven displays. Offer circular design services focusing on mono-material construction to attract sustainability-focused brands. This approach provides a strong go-to-market angle against established players.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors agile custom solution providers with strong digital printing capabilities. The market remains viable for the next 5-10 years, driven by the persistent need for physical point-of-sale engagement. Acquisition targets include firms specializing in interactive display integration and sustainable material science. The signal to watch is increased M&A activity involving companies with advanced digital workflow expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion: Automated Assembly Lines | Enhances production efficiency and reduces labor costs for high-volume display orders. |
| Green Manufacturing Transition | Aligns with EU Green Deal mandates, attracting sustainability-focused consumer brands. |
| Product Launch: Interactive Displays | Creates engaging consumer experiences and generates valuable point-of-sale data. |
| Distribution Channel Expansion: Direct-to-Retailer | Improves logistical efficiency and speed of shelf replenishment for major grocery chains. |
| Strategic Partnership: Material Science Firms | Accelerates development of novel fiber-based solutions for complex regulatory environments. |
Research Approach
The analysis maps product type, packaging material, application, and end user sub-sectors, each validated through primary interviews with brand managers and retail category buyers. Packaging engineers and material suppliers provided further insights into material science advancements. Secondary data from industry association reports, government regulatory documents, and company filings supported this. A bottom-up and top-down triangulation process ensured data accuracy.
Quantitative outputs were validated against external benchmarks, integrating historical trends with future growth projections over the projection horizon. The modeling period considered segmentation dimensions including product type, material, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from market drivers, restraints, and competitive intensity. Key forecast inputs included consumer spending patterns and raw material price forecasts.
Material uncertainties — unforeseen regulatory shifts, rapid technological displacement, or significant global economic downturns — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of analysis. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Specialty Labels Packaging Market