
 Luxury Packaging Market | 2026-2036
Luxury Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Packaging Market Intelligence
Recycled molded fiber is decoupling luxury box economics from virgin paperboard dependence. Amcor Plc leverages its global film and fiber footprint to serve cosmetics houses with certified recyclable structures. WestRock Company anchors North American supply through integrated pulp-to-box manufacturing. DS Smith Plc competes on design-led circularity, embedding take-back logistics into premium retail programs.
Luxury packaging denotes high-value primary and secondary containers engineered to protect, present, and authenticate premium goods through precise material specifications such as heavy-weight folding carton board above 400 gsm, hot-stamped foils, and UV-cured lacquers. Its commercial purpose centers on brand equity transmission, shelf differentiation, and unboxing experience orchestration. Glass bottles for fragrances and spirits command the deepest margin pools among material categories, while eco-friendly design features are expanding fastest as regulatory pressure and buyer preference converge. Custom shapes within the design feature dimension remain a specialist stronghold, requiring die-line engineering capabilities that few converters possess at scale.
The EU Green Deal and REACH frameworks in Europe, alongside China's MEE circular economy directives and the US EPA sustainable materials management priorities, are collectively tightening allowable material footprints and mandating post-consumer recycled content thresholds. These regulations reshape supplier qualification criteria and force reformulation of coatings, adhesives, and decorative finishes. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to build in-house recycling partnerships or outsource compliance to specialized converters.
Market Dynamics
Recycled molded fiber technology is severing luxury packaging economics from virgin paperboard dependence, while the EU Green Deal and China's MEE circular economy directives simultaneously tighten material compliance thresholds and reshape supplier qualification criteria across three continents.
Growth Catalysts
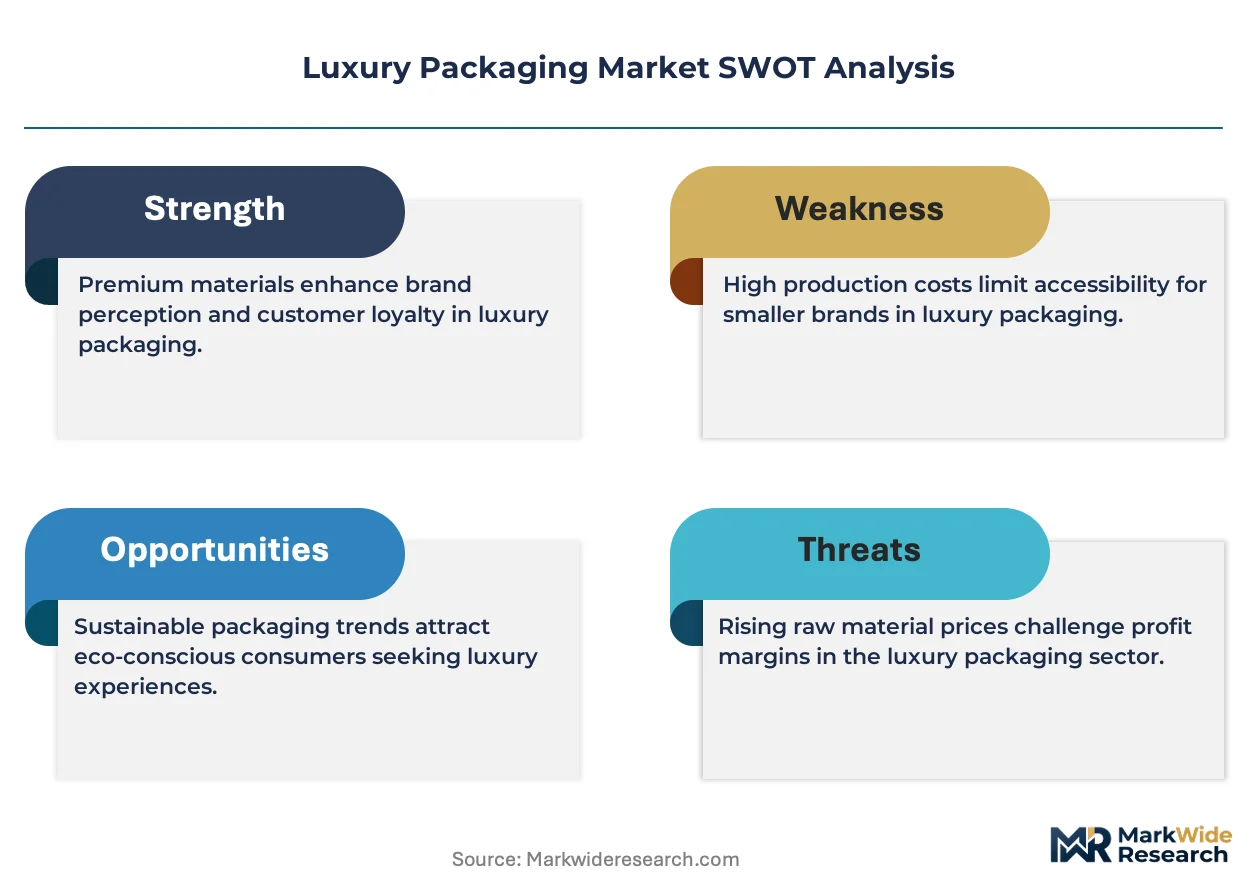
- EU Green Deal material mandates:REACH frameworks and extended producer responsibility schemes force post-consumer recycled content thresholds upward, qualifying converters with certified recyclable structures for premium cosmetics and spirits contracts.
- China's domestic luxury consumption surge:Local packaging innovation accelerates faster than Western Europe as domestic brands demand heavy-weight folding carton board above 400 gsm with embedded authentication features.
- Hot-stamped foil substitution:Metallic transfer films derived from recycled sources displace virgin metallized substrates in fragrance secondary packaging without compromising shelf differentiation.
Market Restraints
- Glass bottle supply concentration:Deep-margin fragrance and spirits container production clusters in Italy and France, exposing brands to energy-cost volatility and single-source risk.
- UV-cured lacquer reformulation friction:ECHA restrictions on photoinitiator chemistry extend coating qualification timelines by 8-14 months for converters serving pan-European cosmetics houses.
- Custom die-line engineering scarcity:Fewer than twelve converters globally possess at-scale capability for complex custom shapes, concentrating pricing power and extending lead times.
Strategic Opportunities
- India's underpenetrated premium cosmetics segment:BIS certification pathways and DGFT import substitution incentives create first-mover advantage for converters establishing local heavy-board converting capacity.
- Take-back logistics integration:DS Smith Plc and comparable design-led competitors embed circular retail programs that capture post-consumer fiber streams for re-entry into luxury box production.
- Digital printing convergence with fiber molding:Variable-data decoration enables batch-size-one personalization for limited-edition fragrance releases without plate-change downtime.
Industry Challenges
- Die-line engineering talent scarcity:Structural packaging designers capable of balancing aesthetic compression with board performance specifications command premium compensation and limited geographic mobility.
- Dual certification complexity:Simultaneous FSC chain-of-custody and EU Green Deal compliance auditing consumes 6-9 months, delaying new supplier onboarding for cosmetics brands with accelerated launch calendars.
- Legacy coating equipment retrofitting:Water-based barrier chemistry transitions require capital-intensive oven modifications that mid-tier converters defer, narrowing qualified supplier pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Packaging Market |
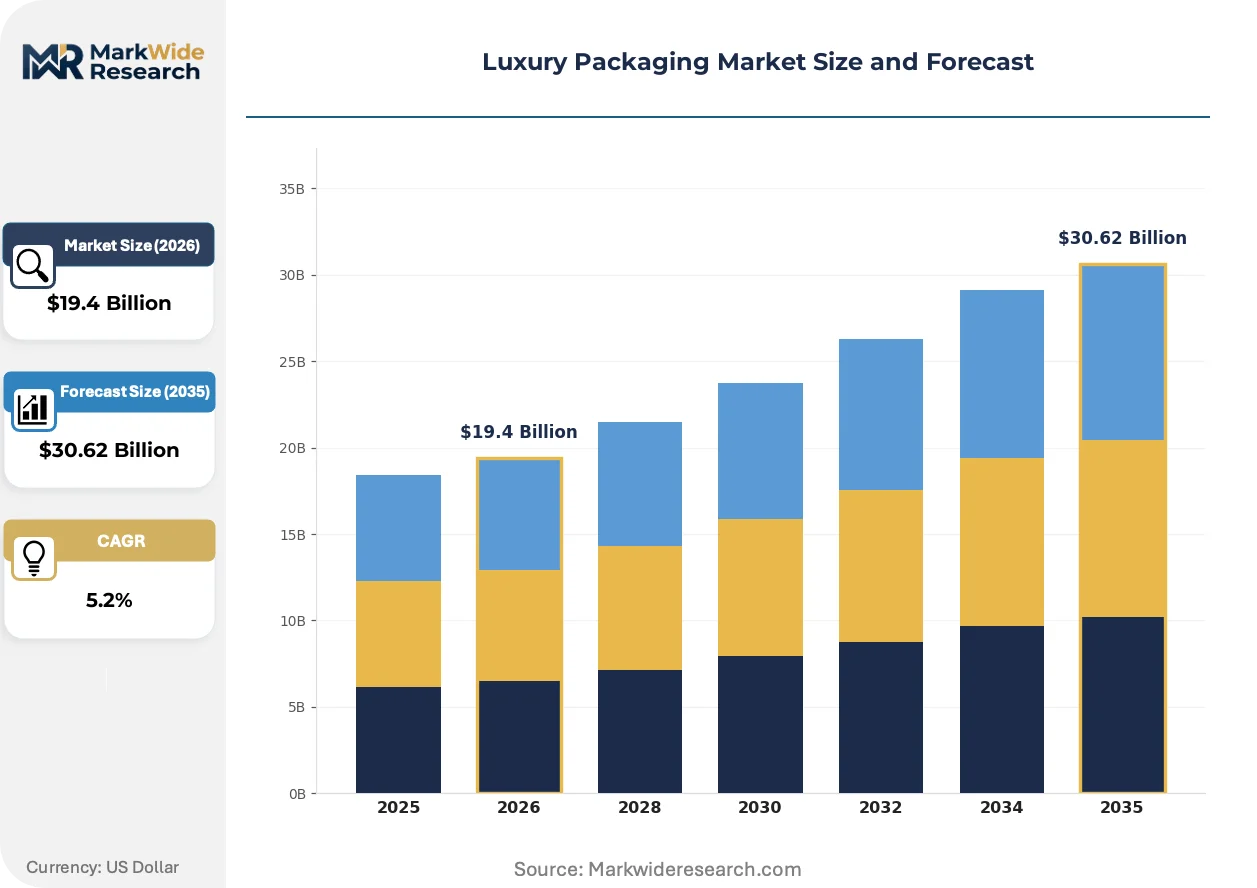
| Market Size in 2026 | $19.4 Billion |
| Market Size in 2035 | $30.62 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bottles, Bags, Labels Material: Glass, Paper, Plastic, Metal End User: Cosmetics, Beverages, Jewelry, Confections Design Feature: Eco-Friendly, Minimalist, Premium Finish, Custom Shapes |
| Companies Covered | Ardagh Group, Luxpac Ltd, Amcor Plc, Lucas Luxury Packaging, GPA Global, WestRock Company, Crown Holdings Inc, Stolzle Glass Group, DS Smith Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Packaging Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory stringency are compressing the innovation cycle for authentication and sustainability features, forcing converters to merge decorative performance with circularity credentials in single-structure solutions.
Recycled molded fiber is unifying structural integrity with surface decoration in luxury primary packaging. Premium cosmetics houses in France and South Korea adopt these certified recyclable structures at accelerated pace for foundation compact and skincare ritual sets. This unifying capability compresses supplier tiers by eliminating separate rigid box and paperboard wrap components.
REACH authorization procedures for bisphenol-derived coatings tighten allowable chemical footprints in EU-sold fragrance packaging. Industrial consequence forces reformulation of UV-cured lacquers and hot-melt adhesives across German and Italian converter bases. Spirits brands with pan-European distribution respond by consolidating procurement with converters holding pre-validated ECHA-compliant material libraries.
Buyer concentration among multinational luxury conglomerates compresses supplier negotiation cycles and unbundles after-sales technical service from unit pricing. Direct procurement teams at LVMH and Kering-level houses displace traditional distributor intermediaries for folding carton and rigid box categories. This disintermediation manifests most visibly in China, where domestic packaging innovation labs co-locate with brand creative studios in Shanghai and Shenzhen.
Luxury Packaging Market Segmentation
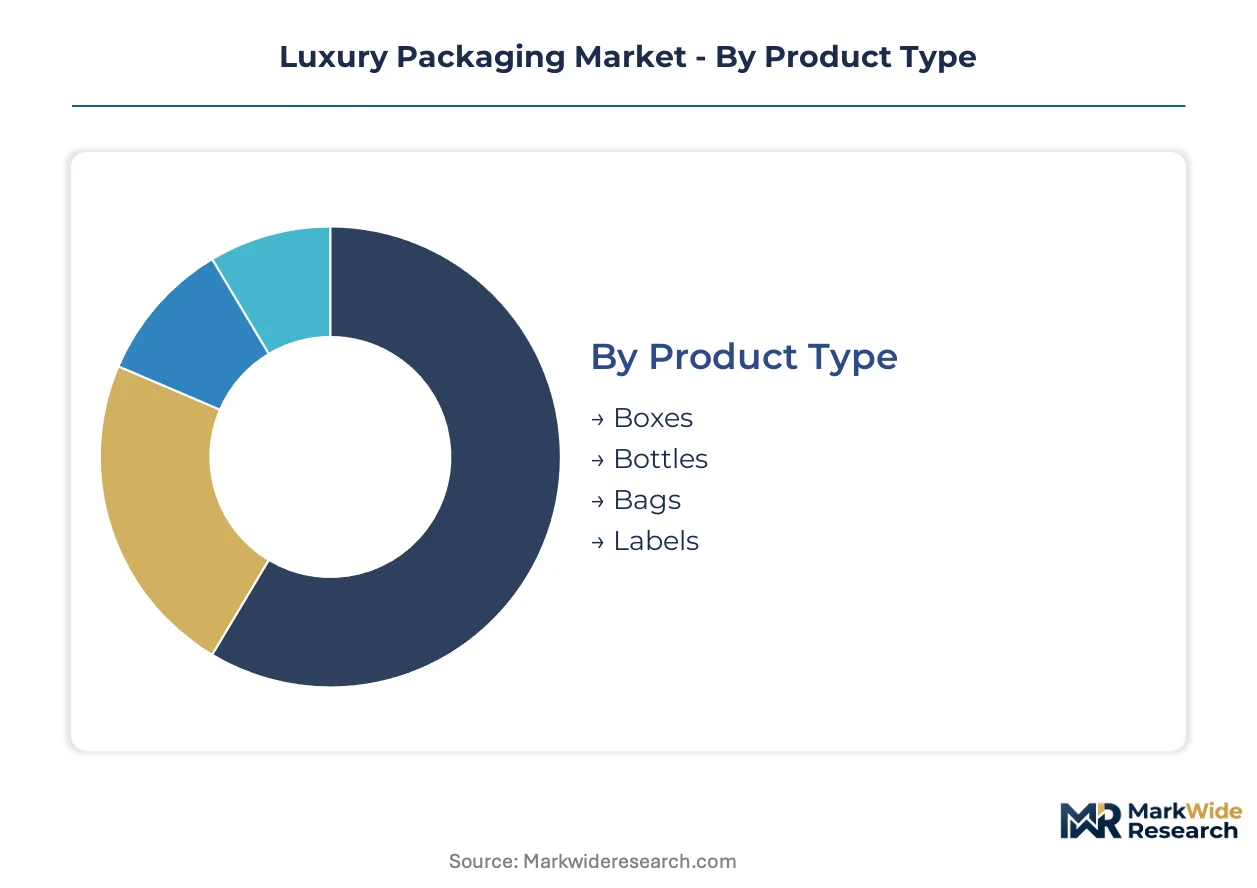
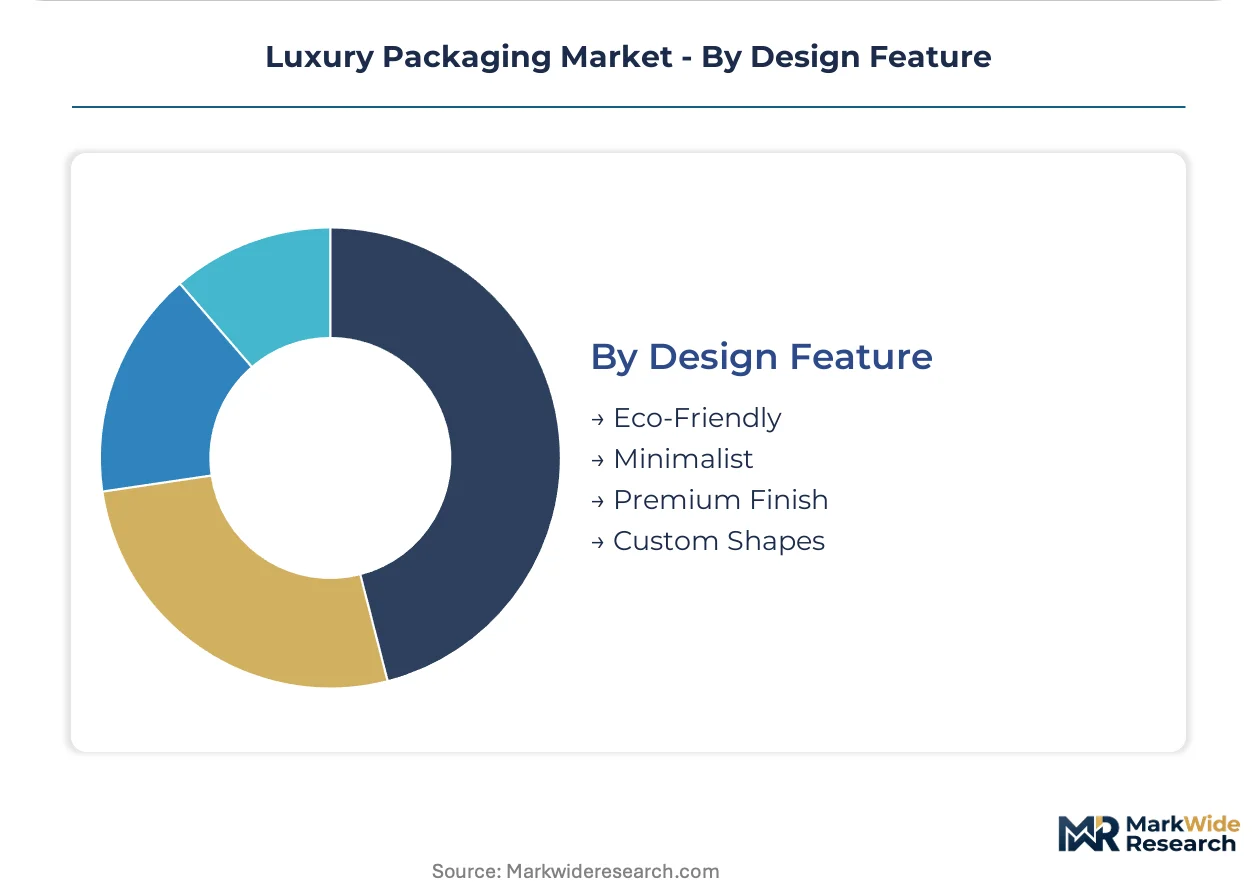
Luxury packaging segmentation reveals how material specifications and design complexity drive supplier qualification tiers. Each dimension carries distinct margin profiles and regulatory exposure that reshape procurement strategies across cosmetics, spirits, and jewelry houses.
Product Type:
Replacement cycles vary sharply across primary versus secondary packaging, with fragrance bottles commanding decade-long design continuity while folding cartons refresh seasonally.
- Boxes:Rigid setup boxes and heavy-weight folding cartons above 400 gsm form the backbone of cosmetics secondary packaging. Demand concentrates in China where domestic brands embed NFC authentication chips within Shanghai-produced rigid structures.
- Bottles:Glass fragrance and spirits containers generate the deepest margin pools in the entire market. Italian and French glassworks face energy-cost volatility that exposes luxury houses to single-source supply risk.
- Bags:Laminated paper and non-woven fabric carry solutions serve jewelry and cosmetics travel retail. Premium weight specifications and magnetic closures differentiate airport-exclusive releases.
- Labels:Pressure-sensitive and wet-glue formats with hot-stamped foil and tactile varnish complete the unboxing sequence. ECHA restrictions on photoinitiator chemistry extend qualification timelines for EU-sold spirits brands.
Boxes sit at the top of the volume ranking, with bottles climbing the fastest as fragrance houses prioritize refillable primary structures.
Material:
Material selection now hinges on circularity credentials rather than purely aesthetic performance, with regulatory thresholds forcing simultaneous reformulation across coating and substrate categories.
- Glass:Soda-lime and borosilicate compositions dominate fragrance and premium spirits. Deep-margin production clusters in Italy's Veneto region and France's Normandy corridor expose brands to concentrated supply risk.
- Paper:Virgin and recycled folding carton board above 400 gsm with FSC chain-of-custody certification anchors sustainable cosmetics commitments. South Korean houses accelerate molded fiber adoption for compact primary packaging.
- Plastic:PETG and rPET structures serve travel-size and sampler formats where shatter resistance outweighs premium perception. REACH frameworks restrict certain phthalate-derived additives in EU distribution.
- Metal:Aluminum and tinplate containers preserve confections and select fragrance formats. Lightweighting imperatives clash with embossing depth requirements for heritage brand identities.
Paper commands the largest volume position, though glass maintains the steepest expansion trajectory as refillable fragrance formats proliferate.
End User:
End-user concentration determines technical service intensity, with cosmetics houses demanding co-located packaging innovation labs that spirits and jewelry brands rarely replicate.
- Cosmetics:Skincare, color cosmetics, and fragrance houses drive specification complexity through seasonal launch calendars. China's domestic luxury consumption surge accelerates local packaging innovation faster than Western Europe.
- Beverages:Premium spirits and champagne producers prioritize heritage glass molds and deep-emboss closures. Extended producer responsibility schemes under the EU Green Deal reshape post-consumer collection logistics.
- Jewelry:Watch and fine jewelry houses demand velvet-lined rigid boxes with magnetic closures and certificate integration. Lower volume per SKU compresses converter margins despite premium pricing.
- Confections:Artisanal chocolate and patisserie packaging balances food-contact compliance with gift-worthy presentation. Seasonal demand spikes strain just-in-time converting capacity.
Cosmetics generates the highest absolute volume, with beverages gaining share fastest as spirits brands consolidate procurement with ECHA-compliant converters.
Design Feature:
Design feature selection increasingly merges decorative performance with circularity validation, forcing single-structure solutions that satisfy both creative directors and compliance officers.
- Eco-Friendly:Certified recyclable structures with post-consumer recycled content and water-based barrier coatings. The EU Green Deal mandates tighten allowable material footprints across German and Italian converter bases.
- Minimalist:Reduced component counts and uncoated board surfaces that communicate sustainability through restraint. South Korean premium cosmetics brands expand these commitments as domestic consumer preference shifts.
- Premium Finish:Hot-stamped foils, UV-cured lacquers, and soft-touch laminations that signal luxury through tactile and visual density. Metallic transfer films from recycled sources now displace virgin metallized substrates.
- Custom Shapes:Die-line engineering capabilities requiring specialized structural designers that fewer than twelve converters possess at scale. Complex forms concentrate pricing power and extend lead times for limited-edition releases.
Premium finish retains the volume leadership position, though eco-friendly specifications are expanding most quickly as regulatory pressure and buyer preference converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Veneto glassmaking corridor anchors global fragrance bottle production, while regulatory divergence between EU Green Deal mandates and China's MEE circular economy directives fragments supplier qualification pathways across three continents.
China
Domestic luxury consumption accelerates packaging innovation in Shanghai and Shenzhen, where local brands demand heavy-weight folding carton board above 400 gsm with embedded NFC authentication. MEE circular economy directives tighten post-consumer recycled content thresholds for imported cosmetics packaging. Pearl River Delta converters co-locate innovation labs with brand creative studios to compress launch timelines.
France
Premium cosmetics houses expand sustainable packaging commitments as REACH frameworks restrict photoinitiator chemistry in UV-cured lacquers. The EU Green Deal's extended producer responsibility schemes reshape post-consumer collection logistics for fragrance secondary packaging. Normandy glassworks face energy-cost volatility that exposes luxury houses to concentrated supply risk.
Italy
Deep-margin fragrance and spirits container production clusters in Veneto and Tuscany, with heritage glass molds commanding decade-long design continuity. ECHA restrictions on bisphenol-derived coatings extend qualification timelines by 8-14 months for pan-European distribution. Italian converters consolidate procurement relationships with ECHA-compliant material libraries to defend contract positions.
South Korea
Premium cosmetics brands accelerate molded fiber adoption for compact primary packaging as domestic consumer preference shifts toward certified recyclable structures. MFDS cosmetic safety regulations intersect with circular economy commitments to reshape material specifications. Seoul-based packaging innovation labs rival Western European capabilities in heavy-board converting and surface decoration integration.
United States
EPA sustainable materials management priorities drive post-consumer recycled content thresholds for imported luxury goods packaging. WestRock Company's integrated pulp-to-box manufacturing anchors North American supply security for cosmetics and spirits brands. California and New York Metro procurement teams displace distributor intermediaries through direct relationships with certified converters.
Luxury Packaging Market Key Industry Players
Global majors compete with regional champions across material certification and design-led circularity, producing a tiered structure where integrated pulp-to-box manufacturers, specialized glassworks, and fiber-molding innovators occupy distinct competitive positions. Three archetypes dominate: scale-driven integrated converters holding FSC chain-of-custody and EU Green Deal dual certification; heritage glass specialists with captive mold libraries and energy-intensive furnace assets; and design-led circularity players embedding take-back logistics into retail programs. Competitive moves concentrate on strategic partnerships for recycled fiber sourcing and geographic expansion into underpenetrated premium cosmetics segments.
Within the integrated converter tier, Amcor Plc and WestRock Company exemplify scale-driven positions spanning film, fiber, and board categories. DS Smith Plc occupies a design-led circularity position. Ardagh Group and Stolzle Glass Group represent heritage glassmaking archetypes with concentrated European production footprints. These five entities collectively illustrate how supplier qualification criteria under tightening EU and Chinese regulatory frameworks favor players with pre-validated material libraries and captive recycling partnerships.
| Leading Market Players |
|---|
| Ardagh Group |
| Luxpac Ltd |
| Amcor Plc |
| Lucas Luxury Packaging |
| GPA Global |
| WestRock Company |
| Crown Holdings Inc |
| Stolzle Glass Group |
| DS Smith Plc |
| Others |
Cost & Logistics Intelligence
Heavy-weight folding carton board index movements cascade through luxury packaging tiers, compressing margins for converters lacking FSC-certified fiber sourcing while amplifying pricing power for integrated pulp-to-box manufacturers serving EU Green Deal-compliant cosmetics houses.
Pricing Analysis
Input-cost pass-through from virgin paperboard and soda-lime glass concentrates in Italian and French glassworks drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on EU Green Deal dual certification status and customization depth for authentication-embedded rigid boxes. Pricing pressure stems from energy-cost volatility in Veneto furnace operations, forcing consolidation toward ECHA-compliant converters. Mass-market cosmetics brands exhibit highest price sensitivity; fragrance houses with decade-long glass mold commitments show lowest.
Supply Chain Analysis
Dual-sourcing requirements mandated by LVMH-level procurement teams fragment supplier relationships across Italy, France, and China, with Pearl River Delta converters gaining share for NFC-embedded folding cartons. Raw material dependencies center on FSC-certified pulp, borosilicate glass batches, and recycled PETG for travel formats. Supply chain risk clusters in single-source Italian glassmaking corridors exposed to natural gas price spikes. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries, particularly in Shanghai and Shenzhen innovation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The luxury packaging market functions as a geographic-arbitrage play where EU Green Deal compliance costs in France and Italy exceed China's MEE circular economy implementation expenses, rewarding converters with pre-validated cross-regional material libraries.
For Market Incumbents: To counter die-line engineering talent scarcity concentrating pricing power among fewer than twelve global converters, incumbents should acquire Seoul-based structural design studios and embed take-back logistics partnerships into premium retail programs. Backward integration into certified recycled fiber sourcing defends margin position against virgin paperboard cost volatility.
For New Entrants and Emerging Players: Enter via India's underpenetrated premium cosmetics segment where BIS certification pathways and DGFT import substitution incentives create first-mover advantage for heavy-board converting capacity. Target domestic Indian skincare brands with localized rigid box production co-located near Mumbai-Delhi logistics corridors, leveraging digital printing convergence for batch-size-one personalization without plate-change downtime.
For Investors and Strategic Acquirers: Asymmetric upside sits with design-led circularity players possessing captive recycling partnerships and ECHA-pre-validated material libraries. Long-term viability favors converters integrating fiber molding with surface decoration in single-structure solutions. Watch for inflection when China's MEE directives tighten post-consumer recycled content thresholds for imported cosmetics packaging, accelerating local production substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Take-back Logistics Integration | DS Smith Plc embeds circular retail programs capturing post-consumer fiber streams for luxury box re-entry. |
| Digital Printing Convergence | Variable-data decoration enables batch-size-one personalization for limited-edition fragrance releases. |
| Recycled Molded Fiber Scale-up | South Korean premium cosmetics brands adopt certified recyclable structures for compact primary packaging. |
| Dual Certification Investment | Simultaneous FSC chain-of-custody and EU Green Deal compliance accelerates supplier qualification timelines. |
| India Manufacturing Footprint | BIS certification pathways and DGFT incentives reward first-movers in heavy-board converting capacity. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with cosmetics brand procurement directors, rigid box plant managers, glassworks furnace operators, and sustainability compliance officers with secondary validation from ECHA substance restriction databases, EU Green Deal implementation trackers, customs trade flows for folding carton board, and SEC filings of integrated packaging converters. Bottom-up demand modeling across authentication-embedded boxes and refillable glass bottles triangulated against top-down market sizing.
Comparable-period anchoring linked projection assumptions to historical reference windows across the analysis window, modeling volume and value trajectories by product type, material specification tier, end-user vertical, and design feature complexity. CAGRs derived from segment-level growth rate reconciliation with macroeconomic indicators and regulatory implementation schedules. Forecast inputs incorporated EU Green Deal extended producer responsibility phase-ins and China's MEE circular economy directive enforcement intensity.
Inputs from ECHA substance restriction databases and customs trade flows were available through the study window; gaps in real-time glass furnace energy cost data introduce uncertainty bands around Italian and French supply projections. Deviation in EU Green Deal material mandate enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Custom Packaging Boxes Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Specialty Plastic Films Market