
 Cannabis Packaging Equipment Market | 2026-2036
Cannabis Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Packaging Equipment Market Outlook
Dispensary procurement of pre-packaged flower and infused products is decoupling from legacy bulk-packaging workflows, forcing equipment suppliers to reconfigure line speeds and batch flexibility. Paxiom leverages its vertical form-fill-seal portfolio to anchor North American cannabis processor accounts. N2 Packaging Systems specializes in nitrogen-flushing jar solutions that extend shelf stability for premium cultivators. The BoxMaker competes through regional manufacturing scale and rapid custom-printed box turnaround for mid-tier brands.
Cannabis packaging equipment encompasses automated machinery engineered to fill, seal, label, and carton regulated cannabis products at throughput rates exceeding 120 units per minute while maintaining child-resistant and tamper-evident compliance. Form-fill-seal systems dominate capital expenditure among high-volume processors, whereas labeling technology captures disproportionate margin pools due to serialization requirements and variable print complexity. Pouch formats lead unit volume across recreational markets, while blister packs remain concentrated in pharmaceutical-grade cannabinoid applications where dose precision governs specification.
The US Food and Drug Administration and individual state cannabis control boards enforce child-resistant packaging standards that directly determine equipment validation protocols and retrofit demand. Health Canada and the European Medicines Agency impose additional barrier-property and labeling requirements that shape export-oriented capital planning. ISO 9001 and cGMP certifications function as gatekeeping criteria for equipment vendors seeking multi-jurisdiction contracts. Stakeholders must monitor how pending federal rescheduling in the United States alters interstate commerce rules and corresponding packaging traceability mandates.
Market Dynamics
State-level track-and-trace mandates are compressing equipment replacement cycles as licensed processors retrofit legacy lines to capture unit-level serialization data. The FDA's evolving labeling requirements and Health Canada's child-resistant packaging standards create overlapping compliance burdens that favor modular, upgradeable machinery architectures over fixed-capital installations.
Growth Catalysts
- California Compliance Cluster:The state's Central Valley cultivation corridor concentrates demand for high-throughput pouch and jar filling systems as large-scale processors expand automated packaging lines to meet child-resistant mandates.
- Nitrogen-Flushing Technology:Premium cultivators are adopting inert-gas packaging solutions to extend shelf stability, driving capital expenditure toward specialized jar sealing equipment with integrated gas displacement.
- Federal Rescheduling Anticipation:Pending reclassification of cannabis under the Controlled Substances Act is accelerating interstate commerce planning, with processors pre-positioning serialized packaging infrastructure for multi-state distribution.
Market Restraints
- Stainless Steel Input Volatility:Equipment fabricators face margin pressure from nickel and chromium price swings, constraining capacity expansion for form-fill-seal system manufacturers dependent on food-grade alloys.
- Single-Source Component Risk:Precision dosing pumps and vision inspection modules concentrate among German and Japanese suppliers, exposing North American integrators to extended lead times and tariff exposure.
- State Regulatory Fragmentation:Incompatible child-resistant testing protocols across California, Colorado, and Illinois force equipment vendors to maintain multiple validation certifications, inflating compliance overhead.
Strategic Opportunities
- Export-Oriented European Cultivators:German and Dutch medical cannabis producers require pharmaceutical-grade blister packaging equipment with EMA-compliant barrier properties, opening premium equipment segments.
- Pre-Roll Automation:The shift from hand-rolled to machine-packed pre-rolls creates demand for integrated weighing, twisting, and child-resistant tube insertion systems not yet saturated by incumbent vendors.
- Blockchain Traceability Convergence:Equipment OEMs embedding serialization hardware with distributed ledger compatibility can capture recurring software revenue from state track-and-trace mandate expansions.
Industry Challenges
- Mechatronics Talent Scarcity:The intersection of precision dosing, vision systems, and regulatory software requires controls engineers with rare cross-functional expertise, elongating commissioning timelines.
- Legacy Line Integration:Brownfield facilities running 2018-era equipment face incompatible communication protocols when adding modern serialization modules, forcing costly middleware development.
- cGMP Certification Burden:Equipment vendors seeking pharmaceutical-adjacent cannabis contracts must maintain simultaneous ISO 9001 and FDA-recognized quality system documentation, stretching quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Packaging Equipment Market |
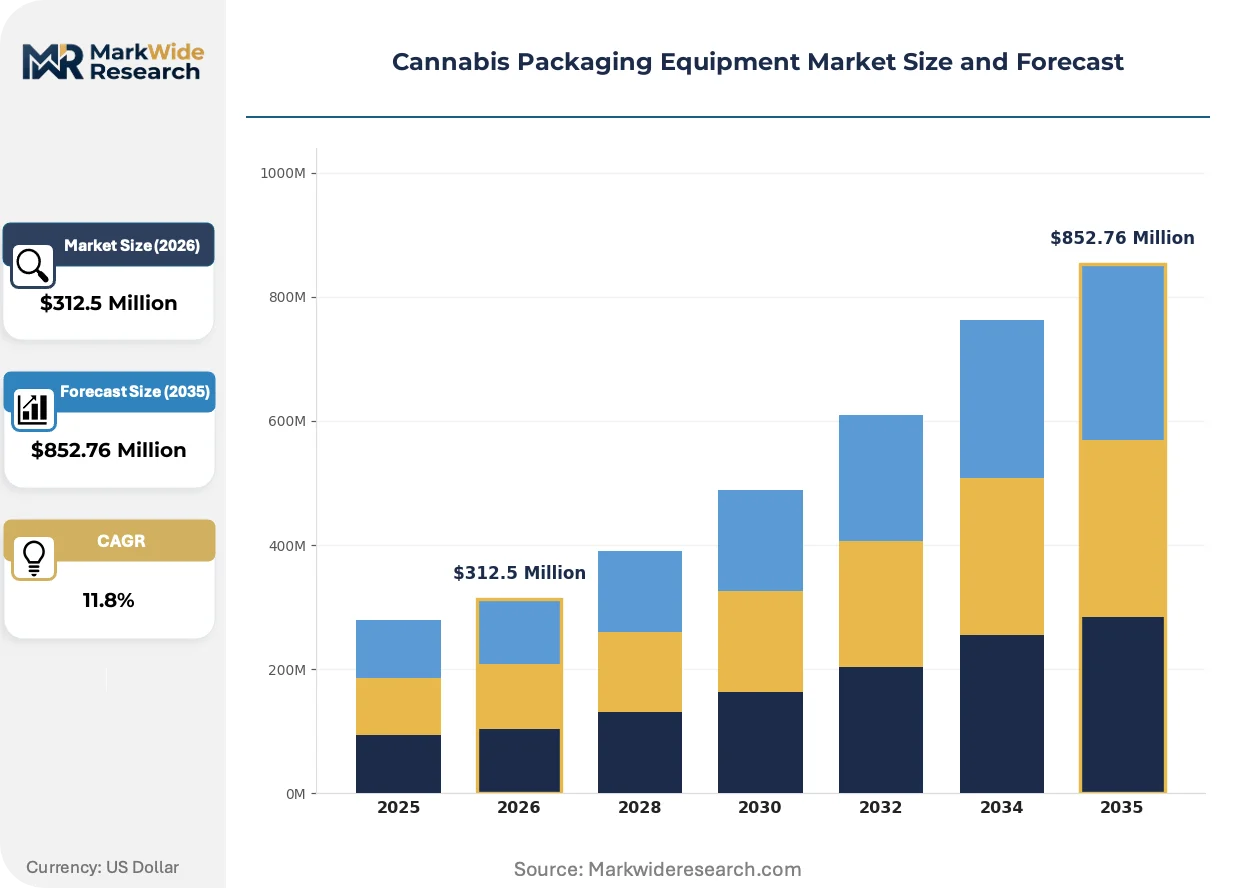
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $852.76 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Package Type: Bottles, Pouches, Jars, Blister Packs Technology: Form-Fill-Seal, Labeling, Shrink Wrapping, Cartoning End User: Dispensaries, Growers, Distributors, Manufacturers Material: Plastic, Glass, Metal, Paper |
| Companies Covered | BrandMyDispo, VerTek, Paxiom, Bingo Bagger, SleekWrapper, The BoxMaker, Swifty Bagger, Mepco Label Systems, N2 Packaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Packaging Equipment Market Strategic Shifts
Equipment architectures are pivoting from fixed-speed bulk processing toward batch-flexible systems that accommodate SKU proliferation without line changeover penalties. This reconfiguration responds to craft cultivator entry and the collapse of single-strain bulk packaging economics.
Machine vision inspection is converging with real-time weight verification to eliminate the traditional separation between leak detection and fill accuracy stations. Mid-tier processors in Oregon and Washington are adopting these integrated modules to reduce footprint and labor headcount. The technology is converging with cloud-based rejection analytics, enabling predictive maintenance contracts that displace traditional break-fix service relationships.
The FDA's draft guidance on hemp-derived cannabinoid labeling is forcing equipment vendors to engineer rapid changeover capabilities for variable print fields including potency statements and allergen warnings. California's Department of Cannabis Control has mirrored this complexity with quarterly label template updates. High-volume infused product manufacturers are responding by specifying thermal transfer overprinters with centralized artwork management rather than pre-printed label inventories.
Dispensary buyers are consolidating procurement around pre-packaged flower SKUs, collapsing the legacy model where retailers handled bulk flower and packaging in-house. This disintermediation concentrates specification authority with licensed processors, who now dictate line speed and format requirements rather than accommodating retail variable demand. The shift is most visible in Colorado's recreational market, where vertically integrated operators have eliminated third-party packaging services entirely.
Cannabis Packaging Equipment Market Segmentation
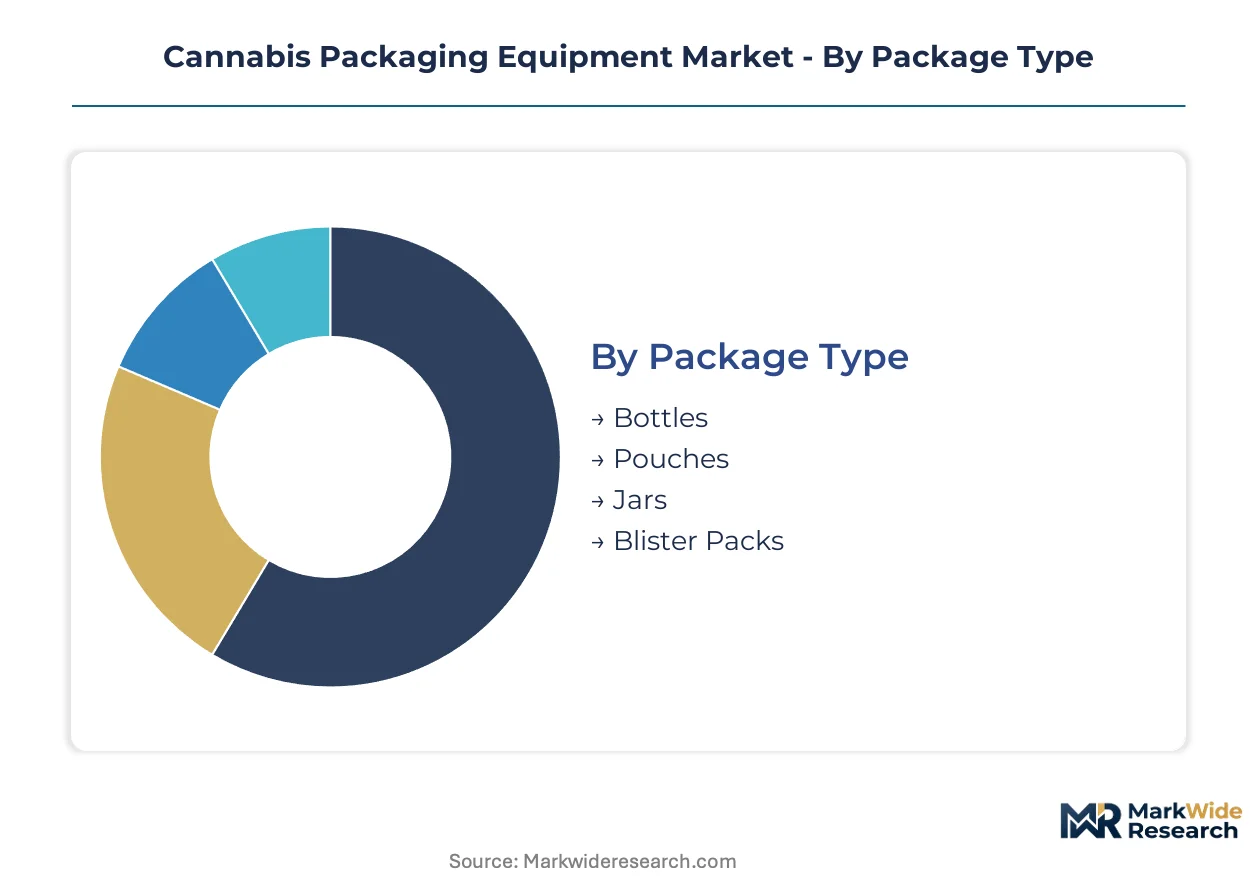
Cannabis packaging equipment specifications diverge sharply across regulatory environments and product formats. Equipment buyers prioritize compliance architecture over throughput alone, forcing segmentation logic to center on validation protocols and changeover flexibility rather than conventional capacity metrics.
Package Type:
Technical specifications for package formats determine sealing pressure curves, barrier property requirements, and child-resistant mechanism integration.
- Pouches:Vertical and horizontal form-fill-seal systems process multi-layer laminates with oxygen transmission rates below 0.5 cc/m²/day. California's Central Valley processors deploy high-speed pouch lines exceeding 150 units per minute for pre-ground flower and infused edibles where shelf visibility matters less than cost efficiency.
- Jars:Rigid container systems integrate nitrogen flushing modules and torque-controlled capping stations to preserve terpene profiles. Premium cultivators in Colorado and Oregon specify jar solutions for craft flower positioning where oxidation sensitivity justifies per-unit packaging premiums.
- Bottles:Blow-fill-seal and desiccant-insertion systems handle tincture and beverage applications with liquid dosing precision.
- Blister Packs:Thermoforming and cold-forming equipment serves pharmaceutical-grade cannabinoid tablets requiring dose uniformity verification.
Mature deployment sits with pouches. Newer deployment is concentrated in blister packs.
Technology:
Capital allocation patterns reflect margin capture potential rather than equipment cost alone.
- Form-Fill-Seal:Integrated systems combine film unwinding, product dosing, and three-side sealing in continuous motion architectures. High-volume processors in Illinois and Massachusetts favor these systems for operational efficiency where SKU proliferation remains limited.
- Labeling:Print-apply and wraparound systems command disproportionate margin pools through serialization hardware and variable data management. State track-and-trace mandates in California and Michigan drive replacement demand as legacy thermal transfer printers lack 2D Data Matrix compliance.
- Shrink Wrapping:Bundling systems for multi-unit retail configurations use polyolefin films with controlled shrink curves.
- Cartoning:End-of-line case packing with glue or tuck-flap closure handles retail-ready assortment building.
Labeling technology captures the steepest expansion trajectory as regulatory complexity compounds.
End User:
Procurement authority is migrating downstream as vertical integration reshapes equipment specification.
- Manufacturers:Licensed processors with cultivation and extraction capabilities specify integrated packaging lines with batch tracking from trim to sealed unit. These buyers dominate capital expenditure in California's vertically integrated market structure.
- Dispensaries:Retail operators with in-house packaging operations favor tabletop fillers and semi-automatic labelers for strain-specific small batches. Colorado's independent retailers maintain this equipment profile despite market consolidation pressure.
- Growers:Cultivation-only operations outsourcing conversion specify minimal packaging infrastructure limited to bulk storage and transport containers.
- Distributors:Third-party logistics providers handling multi-brand portfolios require rapid format changeover capabilities across shared production lines.
Equipment sophistication concentrates with manufacturers. Dispensary procurement is shifting toward pre-packaged finished goods, reducing direct equipment exposure.
Material:
Substrate selection governs equipment compatibility from sealing temperature profiles to barrier testing protocols.
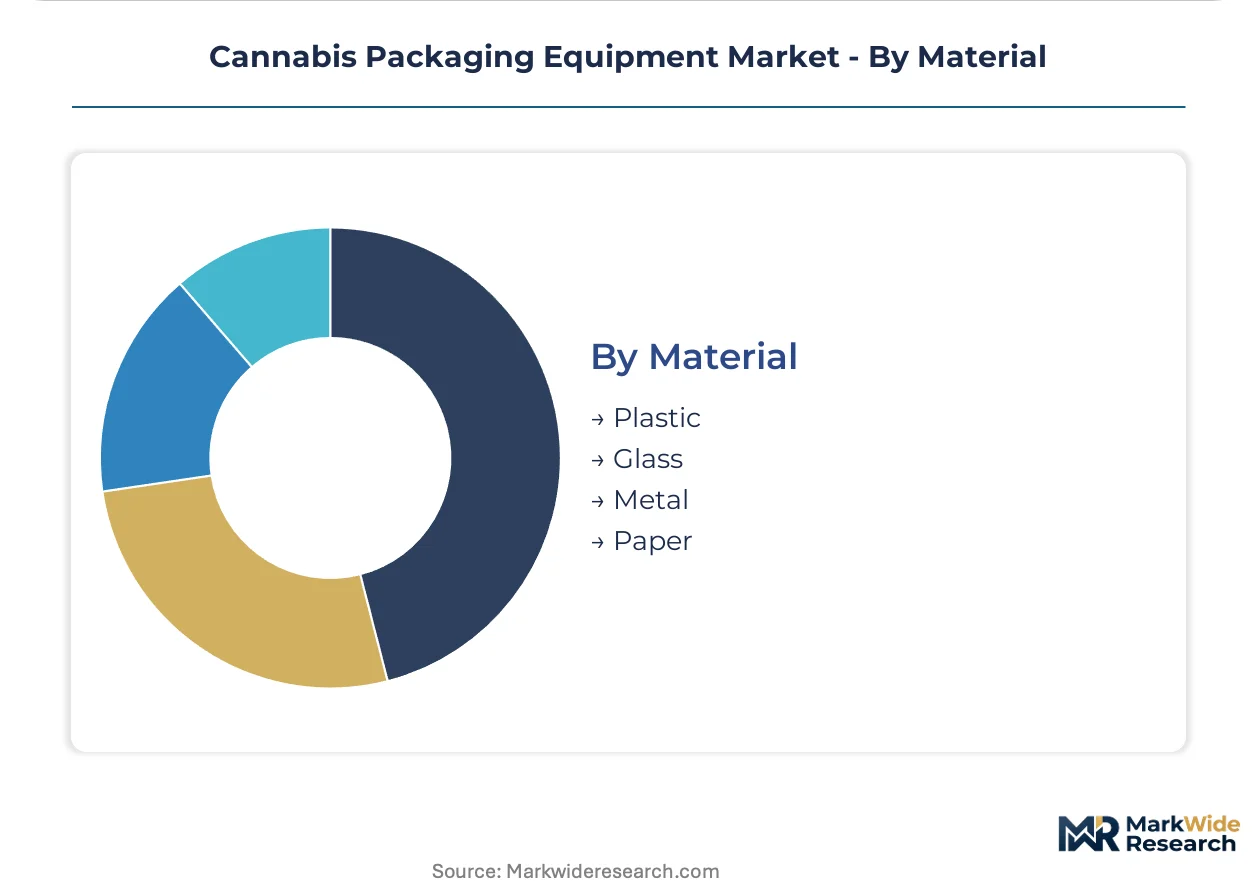
- Plastic:Multi-layer polyethylene terephthalate and polypropylene structures dominate recreational markets with heat-seal compatibility across form-fill-seal platforms. Michigan and Arizona processors specify these materials for cost-optimized flower and concentrate packaging.
- Glass:Borosilicate and amber glass handling systems integrate cushioning conveyors and vacuum-grip transfer mechanisms. Premium positioning in California and Nevada drives glass specification despite weight and fragility penalties.
- Metal:Aluminum and tinplate systems serve concentrate containers and child-resistant tins with embossing capabilities.
- Paper:Fiber-based structures with bio-based barrier coatings require modified sealing parameters and humidity-controlled forming stations.
Plastic substrate equipment represents installed base majority. Paper-compatible system deployment is expanding most quickly as sustainability specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley cultivation corridor functions as the primary demand concentration zone, with state tax incentives for licensed manufacturers accelerating automated line deployment across the American Southwest and Canadian Prairie provinces.
United States
The FDA's evolving labeling requirements and state-level track-and-trace mandates drive equipment replacement cycles among licensed processors. California's Department of Cannabis Control enforces quarterly label template updates that favor thermal transfer overprinters with centralized artwork management. Denver and Portland processors retrofit legacy lines with serialization modules to capture unit-level data for interstate commerce preparation.
Canada
Health Canada's child-resistant packaging standards and PMRA export documentation requirements shape capital planning for Ontario and British Columbia processors. The Prairie provinces concentrate large-scale extraction facilities requiring nitrogen-flushing jar systems for premium flower exports to German medical markets. Toronto-area integrators specialize in modular machinery architectures accommodating simultaneous ISO 9001 and cGMP certification.
Germany
The EMA's pharmaceutical-grade barrier property requirements govern equipment specification for medical cannabis producers in North Rhine-Westphalia and Bavaria. BfArM's cannabis agency mandates dose uniformity verification that favors blister pack thermoforming systems over flexible formats. Frankfurt and Cologne cultivation facilities import North American pouch-filling technology adapted for EU serialization standards.
Netherlands
Dutch Office of Medical Cannabis regulations require integrated batch tracking from cultivation through sealed unit, favoring manufacturers with vertical integration capabilities. The Randstad region hosts contract packaging operators serving German and Scandinavian export markets with rapid format changeover systems. Eindhoven-based automation integrators specialize in vision inspection modules for dose-precision applications.
Australia
The TGA's access scheme for medicinal cannabis products drives demand for pharmaceutical-grade packaging infrastructure in Victoria and New South Wales. The Office of Drug Control enforces strict serialization requirements that mirror European standards, enabling equipment suppliers with EMA experience to enter the market. Melbourne processors concentrate on blister packaging for cannabinoid tablets requiring barrier properties exceeding recreational specifications.
Cannabis Packaging Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated packaging line vendors capturing premium positions in high-throughput processing while regional fabricators serve craft cultivators with semi-automatic configurations. The vendor base concentrates among three strategic archetypes: nitrogen-flushing jar specialists, form-fill-seal platform providers, and custom-printed corrugated integrators. Competitive dynamics center on M&A activity targeting serialization technology assets and strategic partnerships between equipment OEMs and track-and-trace software providers.
Among North American platform vendors, Paxiom occupies a position exemplifying the form-fill-seal archetype, while N2 Packaging Systems represents the nitrogen-flushing specialization tier. The BoxMaker anchors the regional custom-printing segment with rapid turnaround capabilities for mid-tier brand requirements.
| Leading Market Players |
|---|
| BrandMyDispo |
| VerTek |
| Paxiom |
| Bingo Bagger |
| SleekWrapper |
| The BoxMaker |
| Swifty Bagger |
| Mepco Label Systems |
| N2 Packaging Systems |
| Others |
Value Chain & Pricing Dynamics
Captive production of precision dosing pumps and vision inspection modules among German and Japanese suppliers anchors equipment vendors' cost structures and limits their pricing autonomy. This geographic concentration of critical components forces North American integrators to absorb tariff exposure and extended lead times, compressing margins on form-fill-seal systems while creating premium capture opportunities for domestic fabricators with alternative sourcing.
Pricing Analysis
Short lead-time premiums dominate equipment procurement, with California processors paying 15-25% markups for nitrogen-flushing jar systems delivered under eight weeks versus standard twelve-week cycles. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated pharmaceutical-grade lines from recreational-market pouch fillers and tabletop semi-automatic units. Cost compression in mid-tier labeling equipment is intensifying because serialization module suppliers face mechatronics talent scarcity. Craft cultivators in Oregon and Washington exhibit highest price sensitivity, while vertically integrated California manufacturers prioritize compliance validation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Japanese vision inspection module suppliers and German precision dosing pump manufacturers, exposing North American equipment integrators to extended lead times. Stainless steel feedstock draws from Chinese nickel processing, South Korean chromium refining, and domestic food-grade alloy fabrication in Illinois and Ohio. Tariff exposure on mechatronics components represents the dominant structural risk. Distribution runs through direct OEM sales for large California processors, with regional integrators serving mid-tier Colorado and Michigan accounts through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor consolidation is accelerating as state regulatory fragmentation and cGMP certification burdens force sub-scale fabricators toward exit. Compliance overhead inflation is the primary pressure eliminating weaker players unable to maintain multi-jurisdiction validation protocols.
For Market Incumbents: Extend serialization technology portfolios through targeted acquisition of track-and-trace software providers, capturing recurring revenue from state mandate expansions. Deepen backward integration into stainless steel component machining to offset nickel and chromium price volatility threatening form-fill-seal margins. Defend against emerging Asian entrants by accelerating FDA-recognized quality system documentation for pharmaceutical-adjacent cannabis contracts. For New Entrants and Emerging Players: Craft cultivators in emerging state markets represent the most penetrable buyer archetype, with Oklahoma and Missouri processors seeking batch-flexible systems without legacy line retrofit burdens. Pre-roll automation equipment remains underserved by incumbent vendors, creating white-space for integrated weighing and child-resistant tube insertion systems. A go-to-market angle through regional distributor partnerships in the Mountain West bypasses entrenched California supply relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by packaging conglomerates seeking cannabis-specific regulatory expertise and serialization technology assets. Long-term viability favors vendors with simultaneous ISO 9001 and cGMP certification capabilities spanning recreational and pharmaceutical-grade applications. The signal to watch is federal rescheduling implementation, which would trigger interstate commerce infrastructure investment and corresponding packaging traceability mandate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Technology Acquisition | Captures recurring software revenue from California and Michigan track-and-trace mandate expansions. |
| Nitrogen-Flushing System Expansion | Addresses premium cultivator demand for terene preservation in Colorado and Oregon craft flower positioning. |
| Pre-Roll Automation Development | Fills equipment gap for integrated weighing and child-resistant tube insertion systems in unsaturated segment. |
| cGMP Certification Investment | Enables pharmaceutical-grade cannabis contracts requiring FDA-recognized quality system documentation. |
| Regional Manufacturing Footprint | Reduces lead-time premiums and tariff exposure through Illinois and Ohio stainless steel fabrication proximity. |
Study Parameters
Multi-period observation of equipment replacement cycles, state regulatory implementation timelines, and capital expenditure patterns anchored the trend analysis, supplemented by interviews with licensed cannabis processors, packaging line engineers, state compliance officers, and equipment OEM sales directors. Secondary validation drew from FDA labeling guidance documents, Health Canada child-resistant packaging standards, state cannabis control board procurement databases, SEC equipment manufacturer filings, and customs import records for precision mechatronics components. Bottom-up triangulation across processor-level capital budgets converged with top-down equipment vendor revenue aggregation.
Input-output matrix modeling connected segmentation dimensions including package type, technology tier, end-user procurement authority, and material substrate compatibility across the projection horizon. CAGRs were derived from equipment unit shipment trajectories and average selling price evolution, with cross-validation against cultivation license issuance rates and processing capacity expansion in California, Colorado, Illinois, and Michigan. Forecast inputs incorporated state track-and-trace mandate implementation schedules and pending federal rescheduling scenario analysis.
Revisions become necessary when federal rescheduling implementation diverges from baseline assumptions, state regulatory fragmentation intensifies beyond current California-Colorado-Illinois incompatibility, or stainless steel alloy price volatility exceeds historical bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Heat Sealing Equipment Market
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Multihead Weighers Market
Packaging Equipment
Dispensing Sprayers Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market