
 Luxury Boxes Market | 2026-2036
Luxury Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Boxes Market Outlook
Recycled molded fiber is realigning cost structures across rigid packaging tiers. WestRock Company leverages its North American containerboard network to supply premium folding carton substrates for jewelry and cosmetics applications. Smurfit Kappa Group plc anchors European demand through integrated paperboard mills in Ireland and Sweden. DS Smith plc specializes in recycled-content rigid boxes, competing on closed-loop fiber recovery programs with major fragrance houses.
Luxury boxes are structurally engineered enclosures manufactured from paperboard, wood, metal, or glass, typically featuring reinforced corners, magnetic closures, foil stamping, or velvet-lined interiors to protect and present high-value consumer goods. Paperboard gift boxes dominate volume, though wood jewelry boxes command the widest margin pools due to craftsmanship premiums and heirloom positioning. The e-commerce end-user segment is expanding fastest as unboxing experience design becomes a direct customer acquisition tool for direct-to-consumer beauty brands.
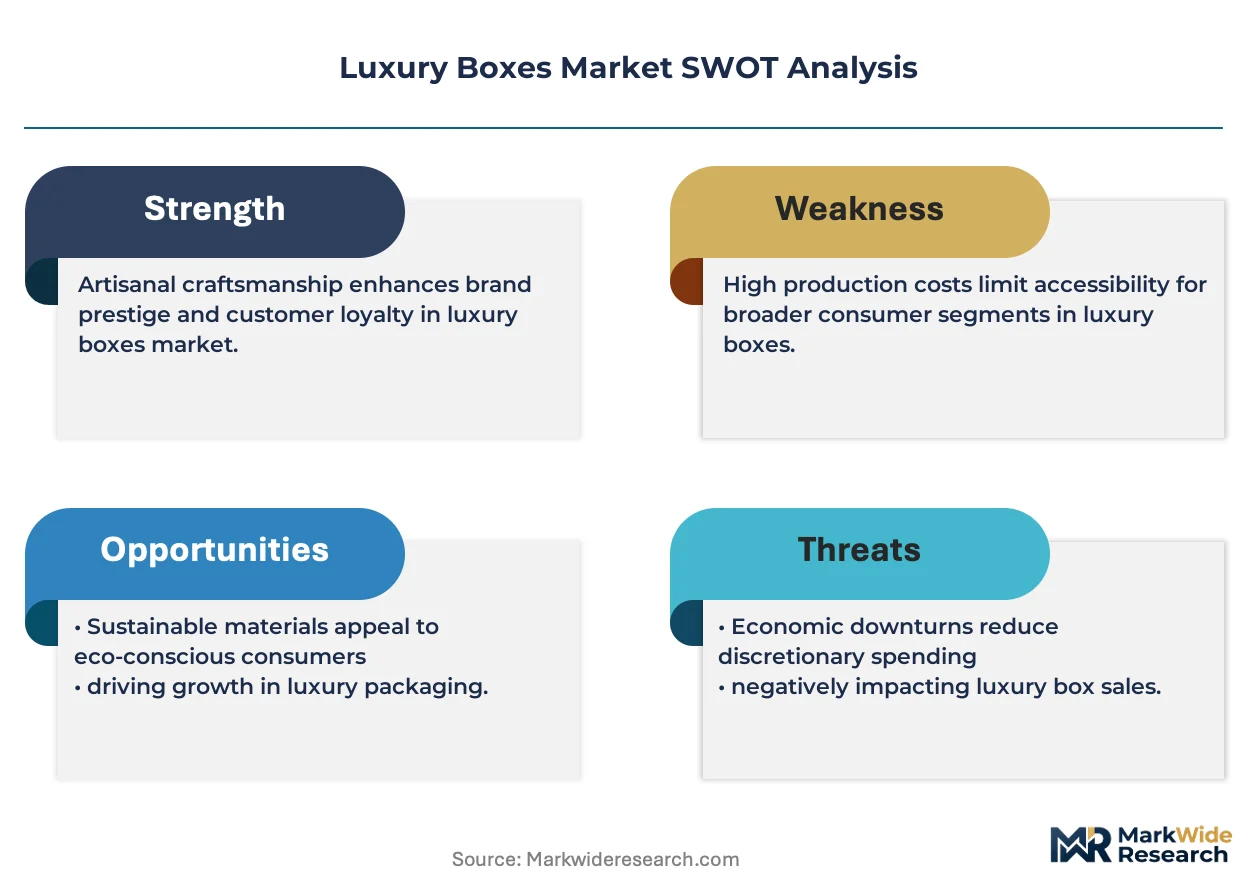
The EU Packaging and Packaging Waste Regulation and the US EPA sustainable materials management framework are mandating extended producer responsibility for packaging waste, forcing luxury brands to certify recyclability or face market access restrictions. China's SAMR national standard GB/T 16716 on packaging reduction applies to imported luxury goods sold through domestic e-commerce channels. Stakeholders must monitor evolving extended producer responsibility fee structures across the EU, US, and China to anticipate cost pass-through requirements and supplier qualification thresholds.
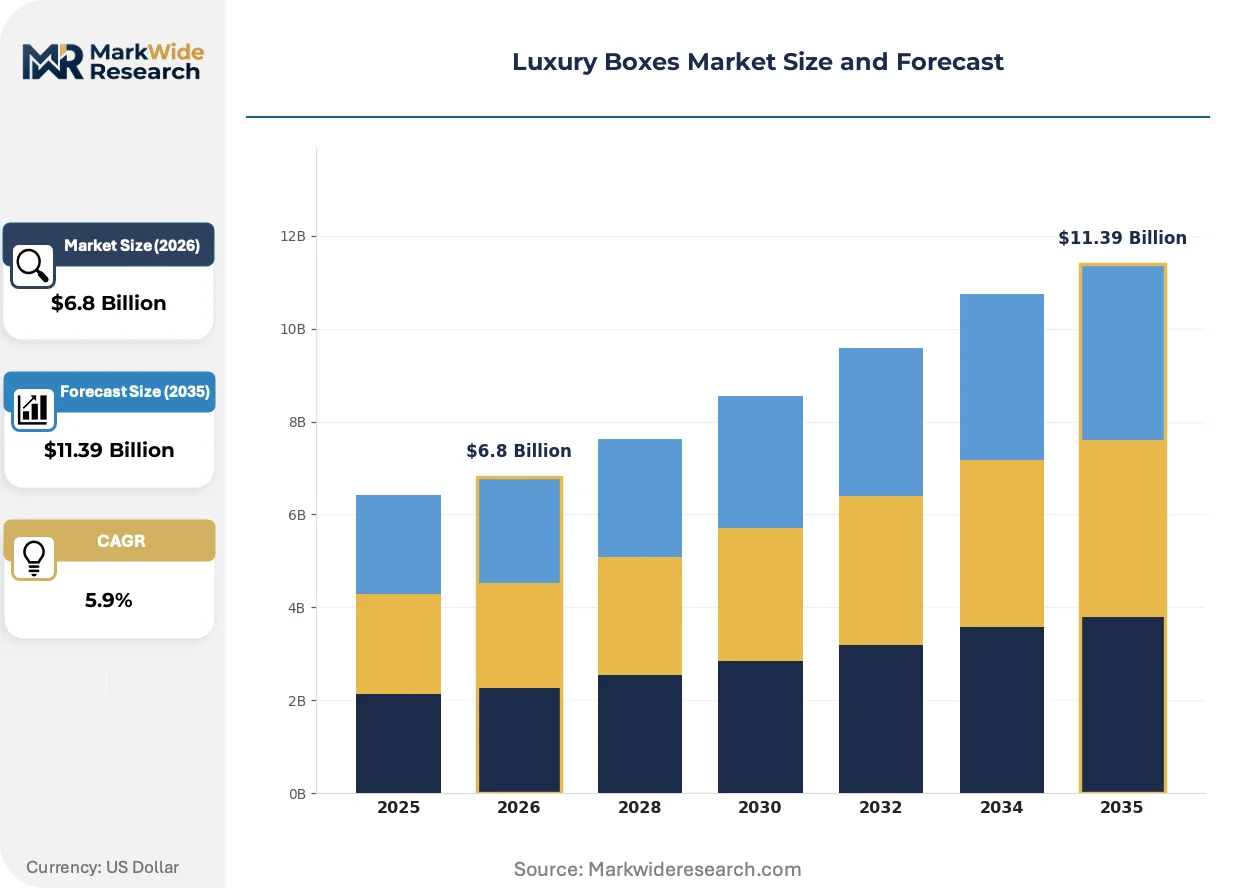
Market Dynamics
Recycled molded fiber is compressing traditional rigid packaging cost structures while EU Packaging and Packaging Waste Regulation mandates force brands to certify closed-loop recovery or lose market access across member states.
Growth Catalysts
- EU extended producer responsibility mandates:The EU Packaging and Packaging Waste Regulation tightens material recovery targets for luxury goods packaging, compelling fragrance houses to redesign boxes for recyclability and certified fiber sourcing.
- E-commerce unboxing experience design:Direct-to-consumer beauty brands in China's tier-one cities deploy rigid paperboard gift boxes as customer acquisition tools, converting packaging from cost center to marketing asset.
- Premium cosmetics expansion:French and Italian cosmetics houses are expanding rigid paperboard programs for limited-edition releases, anchoring volume growth in heritage European manufacturing clusters.
Market Restraints
- Recycled fiber input cost volatility:Post-consumer recovered paper prices fluctuate with municipal collection rates and export demand from Asian packaging converters, squeezing margin predictability for rigid box manufacturers.
- Supply concentration in Nordic paperboard:Integrated mills in Sweden and Finland control premium folding carton substrate supply, creating geographic chokepoints for European luxury packaging procurement.
- Wood jewelry box substitution limits:Heirloom-positioned wooden enclosures face volume ceilings from slow craftsmanship cycles and raw material scarcity in certified sustainable hardwoods.
Strategic Opportunities
- China domestic luxury consumption pivot:Tier-one city demand is outpacing outbound purchasing, creating white space for localized rigid box production serving domestic e-commerce channels under SAMR GB/T 16716 standards.
- Magnetic closure mechanism convergence:Integration of micro-magnet arrays with recycled paperboard substrates enables premium haptic experiences without metal hinge hardware, opening new design territory for cosmetics applications.
- US EPA sustainable materials management tailwind:Extended producer responsibility frameworks emerging at state level create early-mover advantage for brands certifying recyclability ahead of federal harmonization.
Industry Challenges
- Master craftsman scarcity in wood jewelry boxes:Hand-finished heirloom enclosures require specialized joinery and velvet-lining skills concentrated in aging European artisan networks, constraining production scaling.
- Multi-jurisdiction certification complexity:Brands must simultaneously satisfy EU recyclability mandates, US EPA materials management frameworks, and China's SAMR packaging reduction standards, fragmenting compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Boxes Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gift Boxes, Favor Boxes, Wine Boxes, Jewelry Boxes Material: Wood, Metal, Glass, Paperboard End User: Retail, E-Commerce, Corporate, Hospitality Design Style: Elegant, Minimalistic, Vintage, Modern |
| Companies Covered | WestRock Company, Smurfit Kappa Group plc, DS Smith plc, Mondi plc, International Paper Company, Sealed Air Corporation, Stora Enso Oyj, Graphic Packaging Holding Company, Mayr-Melnhof Karton AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Boxes Market Strategic Shifts
Digital printing and structural design software are collapsing prototyping cycles for rigid packaging, enabling fragrance and jewelry houses to test limited-edition box formats without die-cutting tooling investments.
Structural simulation software is unifying design and manufacturing workflows for rigid paperboard enclosures. Premium cosmetics brands in France now iterate magnetic closure geometries and corner reinforcement patterns through finite-element modeling before physical sampling. This compression of development timelines is enabling seasonal packaging refreshes that previously required twelve-month planning horizons.
REACH substance restrictions are forcing reformulation of foil stamping adhesives and metallic transfer films used in luxury box decoration. The European Chemicals Agency's updated candidate list for Substances of Very High Concern now captures several legacy hot-stamping chemistries, compelling converters to qualify alternative bonding agents. Fragrance houses sourcing European-manufactured rigid boxes face accelerated supplier requalification timelines to maintain CE-marked product placement.
Unboxing video content is restructuring procurement priorities for direct-to-consumer beauty brands. Social media-native cosmetics labels now specify rigid box dimensions and interior lining textures based on platform-optimized visual capture rather than traditional retail shelf presence. This behavioral shift concentrates design investment in Chinese and North American digital-first brands where customer acquisition costs are directly tied to shareable packaging moments.
Luxury Boxes Market Segmentation
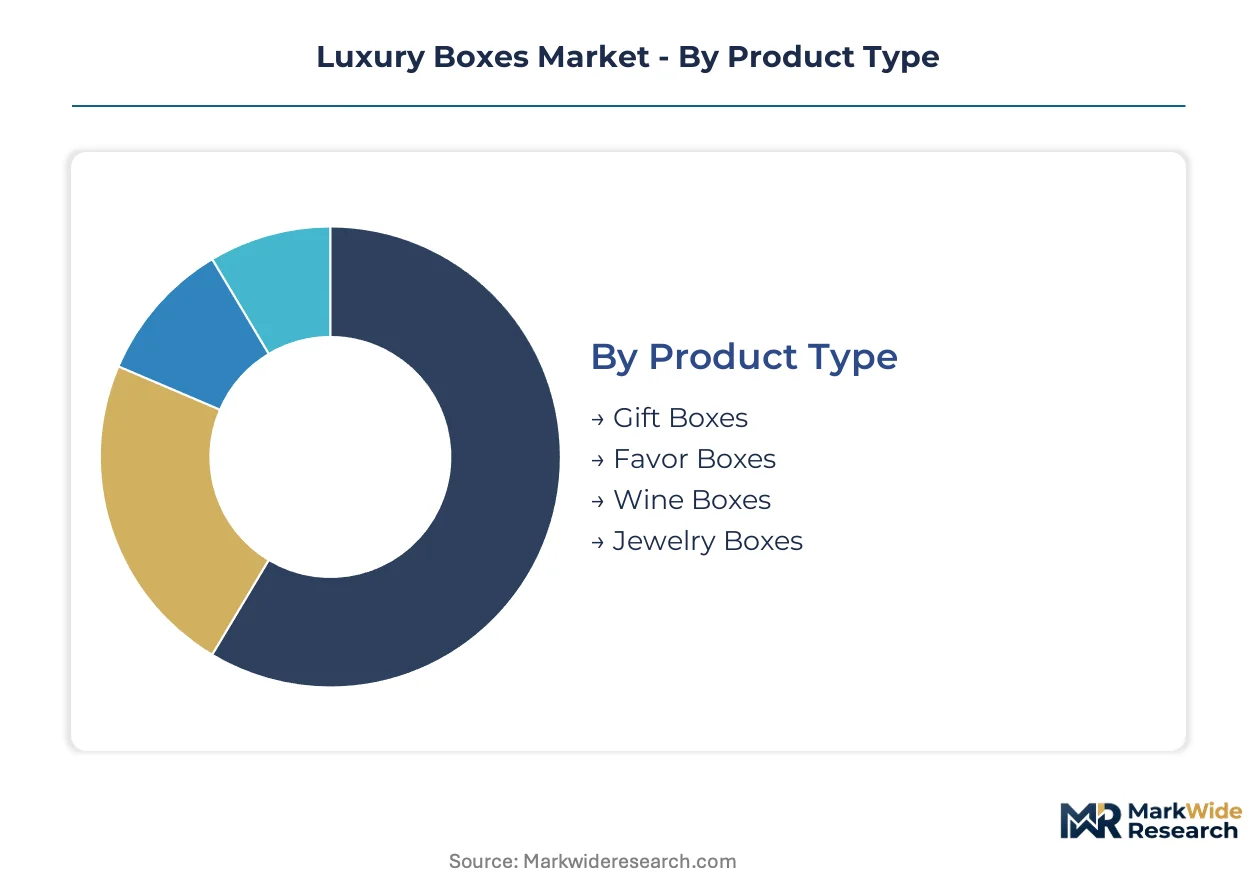
Structural engineering requirements and regulatory certification burdens vary sharply across luxury box segments, forcing procurement teams to qualify suppliers against incompatible standards. Material composition and end-use channel dictate which extended producer responsibility frameworks apply, fragmenting supplier pools and compliance costs.
Product Type:
Gift boxes and jewelry boxes carry the heaviest certification loads under EU Packaging and Packaging Waste Regulation, while wine boxes face additional REACH substance restrictions on interior coatings that contact alcohol vapor.
- Gift Boxes:Rigid paperboard enclosures with magnetic closures and foil-stamped surfaces dominate cosmetics applications. Demand concentrates in China's tier-one cities where domestic e-commerce channels require SAMR GB/T 16716 packaging reduction compliance for imported beauty products.
- Jewelry Boxes:Velvet-lined interiors with reinforced corners and heirloom-grade wood craftsmanship command the widest margin pools. Production bottlenecks in aging European artisan networks constrain scaling despite premium positioning in French and Italian heritage manufacturing clusters.
- Wine Boxes:Specialized structural designs accommodate bottle neck diameters and sediment protection. REACH-compliant interior coatings add regulatory layers absent from dry-goods packaging.
- Favor Boxes:Lightweight paperboard formats for event and hospitality gifting. Volume production favors digital printing workflows that collapse prototyping cycles for seasonal designs.
Leading the category by volume: Gift Boxes. Growing fastest: Jewelry Boxes.
Material:
Cost tiers separate certified sustainable substrates from conventional alternatives, with post-consumer recovered fiber premiums widening the gap between paperboard grades.
- Paperboard:Recycled-content rigid boxes compete on closed-loop fiber recovery programs with major fragrance houses. Nordic integrated mills in Sweden and Finland control premium folding carton substrate supply, creating geographic procurement chokepoints.
- Wood:Heirloom-positioned hardwood enclosures require certified sustainable sourcing and specialized joinery skills. Raw material scarcity and master craftsman aging constrain production scaling for jewelry applications.
- Metal:Hinge hardware and decorative accents face RoHS compliance for electronics-adjacent luxury goods. Magnetic closure arrays increasingly substitute metal mechanisms in cosmetics packaging.
- Glass:Limited to display and preservation applications where transparency outweighs weight penalties. Fragility limits e-commerce adoption despite premium haptic properties.
Highest margin capture: Wood. Steepest expansion trajectory: Paperboard.
End User:
Channel-specific unboxing requirements are restructuring design priorities, with social media-native brands specifying dimensions for platform-optimized visual capture rather than retail shelf presence.
- E-Commerce:Direct-to-consumer beauty brands deploy rigid paperboard as customer acquisition tools, converting packaging from cost center to marketing asset. Unboxing video content dictates interior lining textures and closure mechanics for shareable moments.
- Retail:Heritage cosmetics houses anchor volume in French and Italian manufacturing clusters with limited-edition seasonal refreshes. Twelve-month planning horizons compress through structural simulation software adoption.
- Corporate:Customized gifting programs require flexible minimum order quantities and rapid turnaround. Digital printing enables personalization without die-cutting tooling investments.
- Hospitality:Amenity and welcome packaging prioritizes lightweight logistics and brand consistency across property portfolios. Favor box formats dominate this channel.
Fastest channel growth: E-Commerce. Largest absolute volume: Retail.
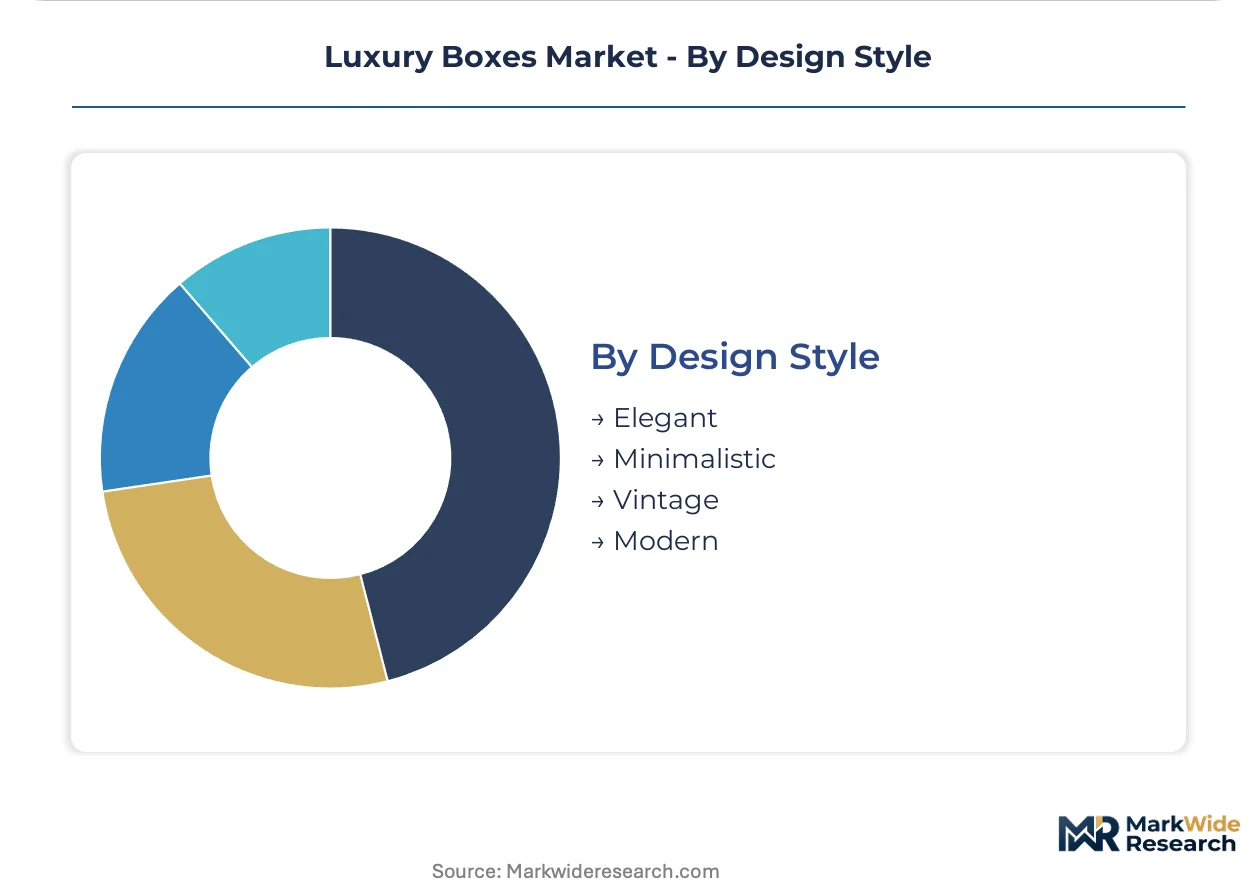
Design Style:
Maturity gradients separate heritage-positioned aesthetics from digitally-native formats, with vintage styling requiring specialized supplier capabilities that resist automation.
- Minimalistic:Clean lines and reduced material volumes align with packaging reduction mandates. Magnetic closures without metal hardware support recyclability certification.
- Elegant:Foil stamping and velvet linings target fragrance and fine jewelry applications. REACH substance restrictions force adhesive reformulation and supplier requalification.
- Modern:Geometric structural engineering and digital-first color palettes dominate Chinese and North American direct-to-consumer brands. Finite-element modeling enables rapid iteration.
- Vintage:Distressed finishes and ornamental hardware require specialized craftsmanship concentrated in European artisan networks. Production scaling faces capability scarcity.
Fastest design growth: Minimalistic. Deepest supplier concentration: Vintage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities concentrate the steepest demand acceleration as domestic luxury consumption displaces outbound purchasing patterns. France and Italy anchor heritage manufacturing clusters for premium cosmetics packaging. The United States and Germany shape regulatory frameworks that cascade through supplier qualification requirements worldwide.
China
Shanghai and Beijing drive volume through domestic e-commerce channels serving beauty brands with unboxing-optimized rigid paperboard formats. SAMR's GB/T 16716 packaging reduction standard applies to imported luxury goods sold through these platforms. The Yangtze River Delta hosts expanding production capacity for localized rigid box manufacturing serving domestic consumption pivots.
France
Heritage fragrance houses in Paris and Grasse anchor rigid paperboard demand for limited-edition seasonal releases. REACH substance restrictions from ECHA force reformulation of foil stamping adhesives and metallic transfer films used in luxury box decoration. The Île-de-France region concentrates converter networks specializing in premium folding carton substrates with magnetic closure integration.
Italy
Cosmetics brands in Milan and Florence expand rigid paperboard programs for premium positioning. EU Packaging and Packaging Waste Regulation mandates drive certified fiber sourcing requirements across supplier networks. The Lombardy and Piedmont regions maintain specialized craftsmanship capabilities for velvet-lined jewelry enclosures with heirloom-grade finishing.
United States
Direct-to-consumer beauty brands in New York and Los Angeles deploy rigid packaging as customer acquisition tools tied to shareable unboxing content. EPA sustainable materials management frameworks at state level create early-mover certification advantages. The Northeast and California corridors concentrate digital-first brands specifying structural dimensions for platform-optimized visual capture.
Germany
Industrial packaging demand from Düsseldorf and Hamburg supports high-specification folding carton substrates for precision-engineered enclosures. Extended producer responsibility fee structures under EU mandates force brands to anticipate cost pass-through requirements. The North Rhine-Westphalia and Bavaria regions host integrated paperboard mills controlling premium substrate supply for European luxury procurement.
Luxury Boxes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated paperboard mills commanding premium substrate supply and independent converters competing on design agility. The vendor base organizes into three tiers: multinational packaging conglomerates with captive fiber networks, regional specialists in heritage craftsmanship, and digital-native converters serving direct-to-consumer brands. Consolidation pressure concentrates among Nordic integrated mills, while fragmentation persists in wood jewelry box artisan networks. M&A activity targets magnetic closure technology capabilities and closed-loop fiber recovery certifications.
Among North American containerboard networks, WestRock Company exemplifies scale-driven substrate supply for jewelry and cosmetics applications. European integrated mills anchor demand through Smurfit Kappa Group plc and DS Smith plc, with the latter representing recycled-content rigid box specialization competing on fiber recovery programs. These three entities occupy positions spanning premium folding carton substrate supply and closed-loop sustainability certification.
| Leading Market Players |
|---|
| WestRock Company |
| Smurfit Kappa Group plc |
| DS Smith plc |
| Mondi plc |
| International Paper Company |
| Sealed Air Corporation |
| Stora Enso Oyj |
| Graphic Packaging Holding Company |
| Mayr-Melnhof Karton AG |
| Others |
Value Chain & Pricing Dynamics
Captive integration into Nordic paperboard mills anchors supply positions and pricing power for premium folding carton substrates. Sweden and Finland control premium substrate flows, forcing converters to accept pass-through terms or face allocation constraints during tight fiber markets.
Pricing Analysis
Gift boxes capture volume leadership while wood jewelry boxes command margin premiums through craftsmanship scarcity. Pricing stratifies across heirloom-grade wood, certified sustainable paperboard, and conventional rigid substrates based on fiber certification tier and artisan labor intensity. Cost compression in recycled-content tiers intensifies as post-consumer recovered paper prices fluctuate with municipal collection rates. Direct-to-consumer beauty brands exhibit lowest price sensitivity, prioritizing unboxing experience over unit cost.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, Île-de-France, and North Rhine-Westphalia coordinate hub-and-spoke fulfillment for tier-one city e-commerce channels. Supply concentrates in Sweden, Finland, and Germany for premium folding carton substrates, while Italy and France anchor heirloom wood craftsmanship. Raw material dependencies include post-consumer recovered fiber, certified sustainable hardwoods, and REACH-compliant foil stamping adhesives. Single-source vulnerability runs through Nordic integrated mills controlling premium substrate allocation. Distribution runs through brand-direct e-commerce platforms and heritage retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a cost-of-compliance barrier that favors incumbents with certified fiber recovery programs and multi-jurisdiction regulatory infrastructure.
For Market Incumbents: Anticipate margin compression from recycled fiber input volatility by securing long-term offtake agreements with Nordic integrated mills. Extend backward integration into closed-loop fiber recovery certifications to defend against emerging converters competing on sustainability credentials. Channel control through direct e-commerce platform relationships represents the priority defensive lever against digital-native entrants.
For New Entrants and Emerging Players: Direct-to-consumer beauty brand procurement teams offer the most penetrable entry point, as these buyers prioritize unboxing experience design over incumbent heritage relationships. Target China's tier-one cities for localized production capacity serving domestic consumption pivots under SAMR GB/T 16716 standards. Magnetic closure mechanism integration with recycled paperboard substrates provides a differentiated go-to-market angle for cosmetics applications.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational packaging conglomerates seeking magnetic closure technology capabilities and closed-loop fiber recovery certifications. Long-term viability favors targets with demonstrated compliance across EU, US, and Chinese regulatory frameworks. Watch for extended producer responsibility fee structure harmonization across EU member states as an inflection signal for consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Fiber Recovery Certification | EU Packaging and Packaging Waste Regulation mandates force brands to certify recyclability or lose market access. |
| Magnetic Closure Technology Integration | Micro-magnet arrays with recycled paperboard enable premium haptics without metal hinge hardware. |
| China Domestic Production Localization | SAMR GB/T 16716 standards apply to imported luxury goods sold through domestic e-commerce channels. |
| REACH-Compliant Adhesive Reformulation | ECHA substance restrictions force supplier requalification for foil stamping chemistries in European manufacturing. |
| Structural Simulation Software Adoption | Finite-element modeling collapses prototyping cycles for seasonal packaging refreshes in French cosmetics houses. |
Study Parameters
Document review covered EU regulatory filings, ECHA substance restriction updates, and SAMR standard publications, complemented by interviews with packaging procurement managers at fragrance houses, converter operations directors, and sustainability compliance officers. Secondary sources included customs trade data for paperboard substrates, SEC filings from integrated packaging conglomerates, and industry association reports from European cartonboard manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across product type, material grade, and end-user channel dimensions.
Segmentation outputs reflect disaggregated modeling across gift box, jewelry box, wine box, and favor box categories, further split by paperboard, wood, metal, and glass material tiers. CAGRs were derived from trend extrapolation calibrated to regulatory milestone timelines and channel shift assumptions. Forecast inputs incorporated e-commerce penetration curves for Chinese tier-one cities and extended producer responsibility fee structure evolution across EU member states.
Caveats apply where REACH substance restriction expansion or sudden Nordic mill capacity constraints could materially shift the outlook for premium substrate availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Custom Packaging Boxes Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Decorative Mylar Balloons Market