
 Poland Container Glass Market | 2026-2036
Poland Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Container Glass Market Analytics
Skilled furnace operators and batch chemists is unwinding capacity expansion timelines across Polish container glass plants. O-I Glass Inc leverages its Poznań-area operations to sustain high-volume supply contracts with multinational beverage clients. Ardagh Glass S A anchors its competitive stance through specialized pharmaceutical vial production at Polish facilities. Verallia Polska Sp z o o differentiates by dominating the premium wine and spirits bottle segment with advanced decoration capabilities.
Container glass refers to hollow glass articles formed from silica sand, soda ash, limestone, and cullet, melted at temperatures exceeding 1500°C in regenerative furnaces and shaped by individual section machines or blow-and-blow processes, serving primarily as chemically inert packaging for consumable and pharmaceutical goods. The bottles category occupies the largest volume share, driven by persistent demand from beer and mineral water bottlers across Central Europe. Amber glass commands premium positioning in the pharmaceutical end user segment, where light-blocking properties protect photosensitive drug formulations. Jars within the food & beverage channel are recording the fastest structural expansion, propelled by the shift toward reusable packaging formats in Polish retail chains.
BIS certification requirements for imported glassmaking machinery and the EU Green Deal's carbon border adjustment mechanisms are reshaping capital expenditure decisions among Polish manufacturers. Poland's national waste management framework, aligned with extended producer responsibility rules, mandates higher cullet recovery rates that directly elevate furnace efficiency benchmarks. Stakeholders must monitor how the EU F-Gas Regulation affects melting furnace emissions controls and whether domestic energy price volatility alters the feasibility of oxy-fuel technology retrofits.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing Polish container glass manufacturers to reconfigure furnace operations around escalating recycled content mandates, compressing batch chemistry tolerances and elevating cullet quality standards across Lower Silesian production clusters.
Growth Catalysts
- EU Green Deal carbon border adjustments:Domestic producers gain cost advantage over importers facing emissions-related tariffs, reinforcing local sourcing preferences among Central European beverage exporters.
- Amber glass demand from pharmaceutical formulators:Light-blocking properties protect photosensitive drug formulations, driving specialized furnace campaigns and premium pricing in the healthcare channel.
- Lower Silesian Voivodeship cluster density:Proximity to German and Czech beverage markets reduces logistics costs for high-volume bottle contracts serving multinational clients.
Market Restraints
- Natural gas price volatility:Regenerative furnaces consume substantial energy inputs, and Polish energy market fluctuations compress margin predictability for oxy-fuel retrofit investments.
- Skilled furnace operator scarcity:Batch chemist and melting specialist talent pools are thinning across Polish industrial regions, extending commissioning timelines for capacity expansions.
- Aluminum can substitution in beer packaging:Lightweight metal alternatives capture share in cost-sensitive segments, particularly among mass-market brewers prioritizing logistics efficiency.
Strategic Opportunities
- Pharmaceutical vial specialization:Type I borosilicate and amber glass formats for injectable drugs remain underpenetrated relative to Western European capacity, offering margin expansion for qualified producers.
- Extended producer responsibility alignment:Poland's national waste management framework rewards higher cullet recovery rates with regulatory compliance advantages and furnace efficiency gains.
- Premium spirits decoration capabilities:Advanced screen printing and embossing technologies command price premiums from craft distillers seeking shelf differentiation in Polish and export markets.
Industry Challenges
- BIS certification timelines for imported machinery:Indian-origin glassmaking equipment faces extended approval cycles, delaying furnace rebuild schedules and automation upgrades.
- F-Gas Regulation compliance for emissions controls:Melting furnace abatement systems must adapt to fluorinated gas restrictions, complicating environmental permitting for brownfield expansions.
- Batch chemistry precision requirements:Higher cullet ratios demand tighter raw material quality control, straining laboratory capabilities at mid-scale Polish plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Container Glass Market |
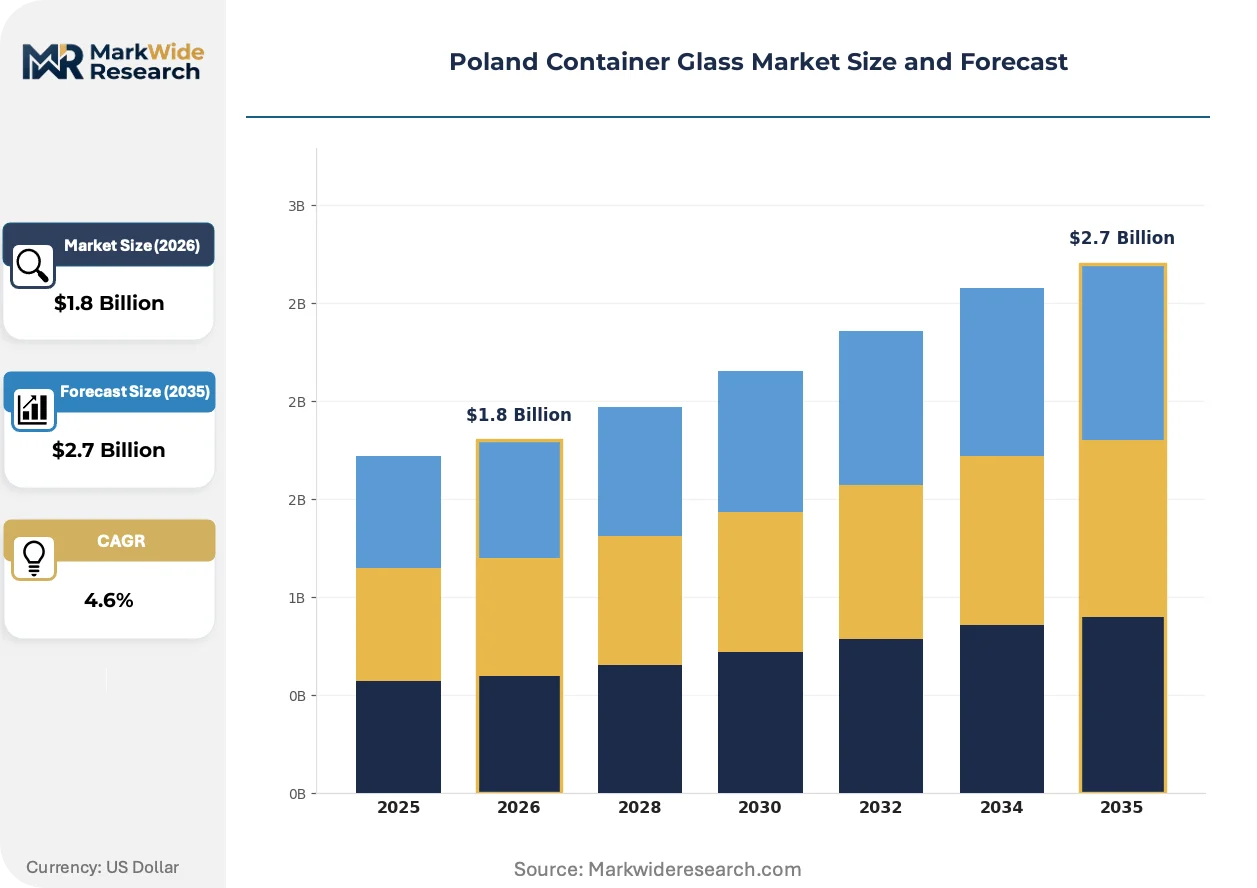
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Size: Small, Medium, Large, Extra Large Color: Clear, Green, Amber, Frosted |
| Companies Covered | O-I Glass Inc, Ardagh Glass S A, BA GLASS POLAND Sp z o o, Stoelzle Glass Group, Gerresheimer AG, Verallia Polska Sp z o o, Presa Sp z o o, Trend Glass Sp z o o, Dekorglass Dzialdowo SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Container Glass Market Evolving Landscape
Oxy-fuel combustion retrofits, digital decoration workflows, and circular packaging mandates are simultaneously elevating capital intensity and reshaping buyer-supplier relationships across Polish container glass value chains.
Electrification of melting furnaces through plasma and induction technologies is fragmenting the traditional natural gas-dependent production model. Pharmaceutical and premium spirits bottlers are piloting these systems at pilot scale, seeking carbon footprint credentials for ESG reporting. The technology is fragmenting furnace engineering vendor relationships as Polish producers evaluate hybrid thermal-electric configurations against full oxy-fuel conversions.
The EU F-Gas Regulation is tightening permissible emissions from industrial thermal processes. Polish manufacturers must retrofit regenerative furnaces with alternative abatement chemistries, elevating maintenance complexity and spare parts inventory requirements. Amber glass pharmaceutical vial producers face the steepest compliance costs given their continuous furnace operating profiles.
Direct procurement relationships between container glass plants and retail private-label beverage brands are compressing traditional distributor intermediaries. Polish supermarket chains are negotiating volume commitments directly with Poznań-area producers, bypassing regional packaging wholesalers. This pattern is most visible in the mineral water and craft beer segments, where shorter production runs and customized bottle designs favor factory-direct coordination.
Poland Container Glass Market Segmentation
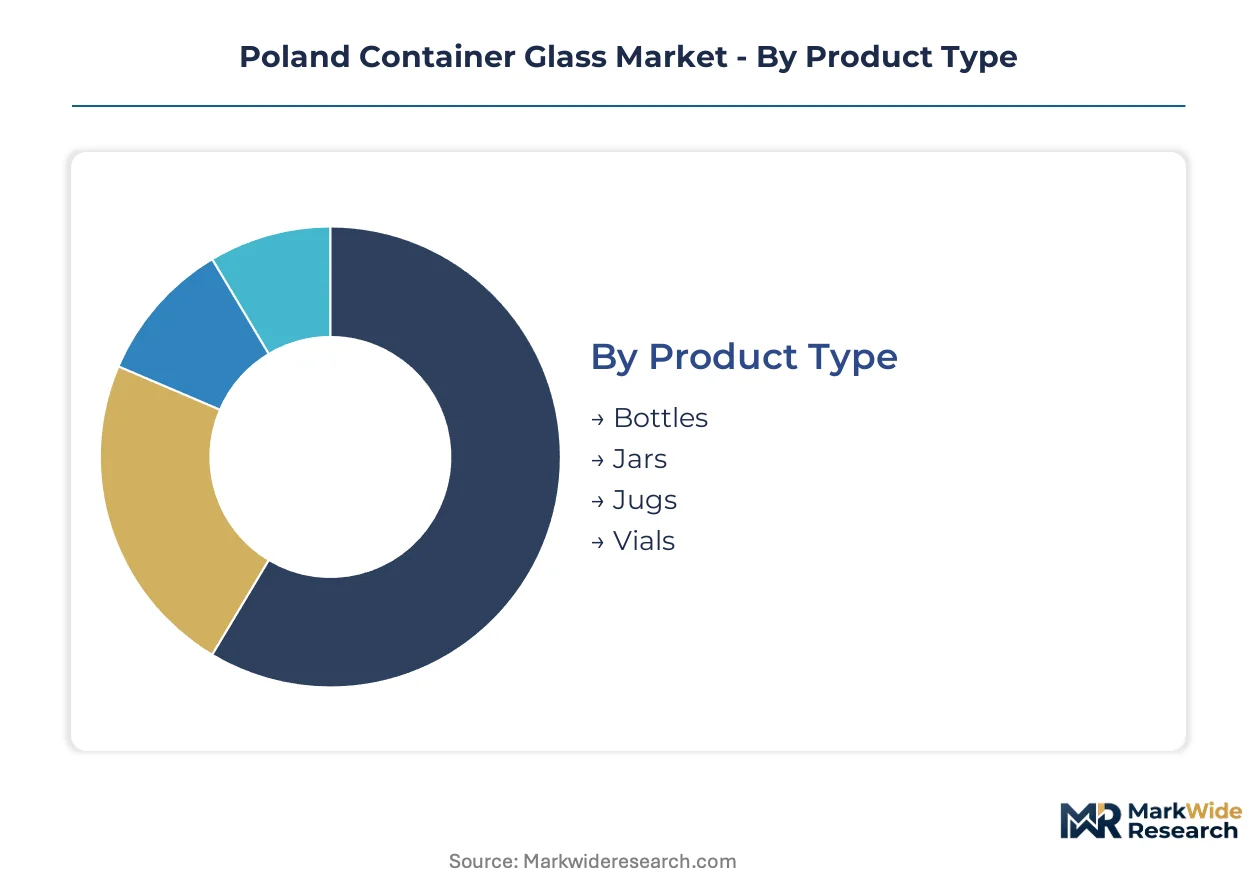
Segmentation in the Poland Container Glass Market reveals how furnace campaigns, cullet chemistry tolerances, and decoration capabilities align with distinct buyer requirements across pharmaceutical formulators and beverage bottlers. Polish manufacturers configure batch recipes and forming speeds differently for each segment, directly affecting energy intensity and compliance with EU Packaging and Packaging Waste Regulation mandates.
Product Type:
The EU F-Gas Regulation imposes divergent abatement obligations across forming methods, with continuous-melt furnaces for high-volume formats facing steeper retrofit costs than batch-operated specialty lines.
- Bottles:Hollow glass containers formed through blow-and-blow or press-and-blow processes, typically 200ml to 1.5L in finished capacity. Polish breweries and mineral water bottlers in the Lower Silesian Voivodeship cluster account for the dominant share of bottle furnace output, driven by export contracts serving German and Czech retail chains.
- Jars:Wide-mouth containers with threaded finishes, produced via press-and-blow forming for dimensional precision in closure compatibility. Polish retail chains are expanding jar procurement for reusable food packaging formats, with private-label brands negotiating direct factory relationships that bypass traditional distributors.
- Jugs:Large-format containers exceeding 2L capacity, typically formed with heavier wall sections for structural integrity. Regional dairy cooperatives and edible oil processors represent the primary demand concentration.
- Vials:Small-diameter pharmaceutical containers requiring Type I borosilicate or neutral glass chemistry for chemical durability. Ardagh Glass S A anchors specialized production at Polish facilities, serving injectable drug formulators with amber and clear variants.
Bottles handle the majority of throughput; Jars are expanding most quickly on share as Polish retailers accelerate reusable packaging commitments.
End User:
Customer procurement patterns fragment across tender-based pharmaceutical supply versus spot-contract beverage sourcing, with divergent quality certification requirements and payment terms.
- Food & Beverage:Beer, mineral water, spirits, and preserved food packagers requiring chemical inertness and CO2 retention properties. Polish craft distillers are driving premium decoration specifications, while mass-market brewers face aluminum can substitution pressure in cost-sensitive segments.
- Pharmaceuticals:Drug formulators requiring USP Type I, II, or III compliance, light-blocking amber variants, and dimensional tolerances for automated filling lines. The EMA's quality guidelines and national pharmaceutical regulator standards enforce batch traceability that elevates laboratory capabilities at qualified plants.
- Cosmetics:Fragrance and skincare brands prioritizing aesthetic differentiation through frosting, metallization, and embossed decoration. Lower volume per SKU favors flexible furnace scheduling.
- Household:Cleaning product and candle container buyers emphasizing cost efficiency over premium finishing. Price sensitivity concentrates procurement among mid-scale Polish producers with excess furnace capacity.
Food & Beverage commands the largest furnace allocation; Pharmaceuticals delivers the steepest margin expansion trajectory for qualified producers.
Size:
Forming machine cavity configurations and mold inventory investments create distinct economies of scale across size categories, with changeover downtime penalizing mixed-schedule operations.
- Small:Formats under 100ml finished capacity, predominantly pharmaceutical vials and cosmetic samples. High cavity counts per machine section maximize output rates for standardized dimensions.
- Medium:100ml to 500ml range covering standard wine, spirits, and sauce bottles. Polish premium spirits producers are expanding medium-format amber glass procurement for brand differentiation in export markets.
- Large:500ml to 1.5L standard beverage and food containers. Mineral water bottlers in the Silesian Voivodeship cluster drive volume concentration for this size band.
- Extra Large:Containers exceeding 1.5L, including water jugs and institutional food service formats. Limited mold availability and higher shipping costs constrain demand growth.
Medium sizes dominate production scheduling flexibility; Small formats are climbing the fastest on unit volume as pharmaceutical packaging expands.
Color:
Batch chemistry variations and furnace campaign transitions impose switching costs that color specialization strategies must recover through pricing premiums or volume commitments.
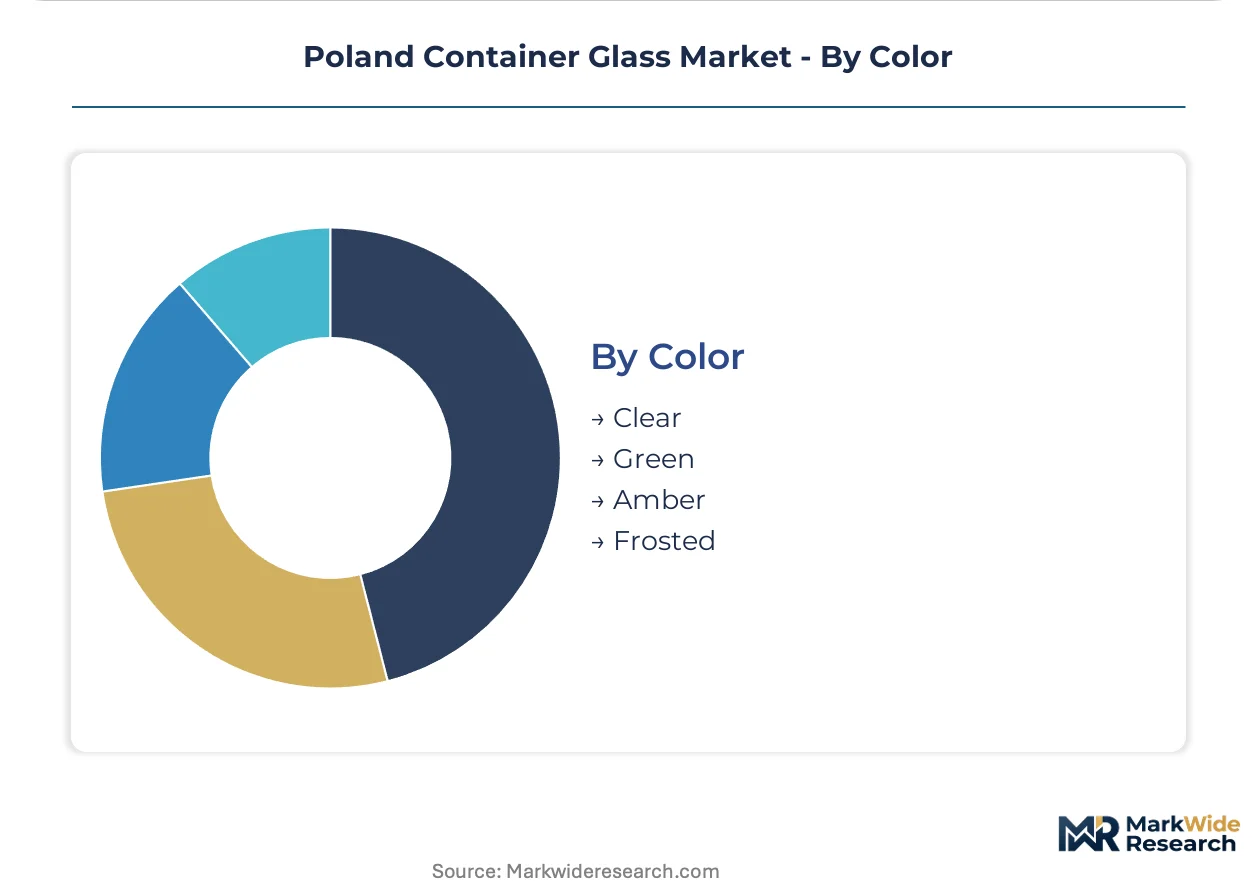
- Clear:Standard flint glass with minimal iron content for maximum clarity and UV transmission. Mineral water and white wine bottlers in Central European export markets represent the core demand base.
- Green:Reduced iron with chromium or copper additions for traditional wine and beer branding. Limited Polish domestic demand concentrates output on Italian and French export contracts.
- Amber:Iron-sulfur chemistry absorbing UV wavelengths below 450nm to protect photosensitive contents. Pharmaceutical formulators and premium spirits bottlers pay substantial premiums for verified light-blocking performance, with specialized furnace campaigns extending lead times.
- Frosted:Acid-etched or molded surface treatments for cosmetic and gift-market differentiation. Secondary processing steps elevate cost structures relative to base glass.
Clear glass absorbs the majority of furnace campaign time; Amber is gaining share fastest as pharmaceutical and premium spirits volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors Poland's container glass sector within a tightening emissions control framework that extends across Central European production clusters. Polish manufacturers navigate this regulatory environment while serving export demand from German and Czech beverage markets.
Lower Silesian Voivodeship
Beer and mineral water bottlers drive furnace output in this southwestern cluster. The EU Packaging and Packaging Waste Regulation mandates escalating recycled content ratios that compress batch chemistry tolerances. Wrocław-area plants supply high-volume contracts to multinational beverage clients with reduced logistics costs to German retail chains.
Silesian Voivodeship
Mineral water bottlers concentrate demand for large-format clear glass containers in this southern industrial zone. Poland's national waste management framework rewards higher cullet recovery rates with regulatory compliance advantages. Katowice-region facilities leverage proximity to Czech and Slovak markets for cross-border supply contracts.
Greater Poland Voivodeship
Poznań-area operations anchor high-volume supply relationships with Central European exporters. The EU Green Deal's carbon border adjustment mechanisms reinforce local sourcing preferences over imports facing emissions-related tariffs. Regional producers invest in oxy-fuel retrofit evaluations amid domestic energy price volatility.
Pomeranian Voivodeship
Pharmaceutical vial specialists serve injectable drug formulators with Type I borosilicate and amber glass formats. EMA quality guidelines enforce batch traceability standards that elevate laboratory capabilities at qualified plants. Gdańsk-region facilities target underpenetrated segments relative to Western European capacity.
Masovian Voivodeship
Warsaw-area distributors face compression as retail private-label brands negotiate direct procurement with glass plants. Extended producer responsibility rules align waste management incentives with furnace efficiency gains. Regional logistics hubs facilitate factory-direct coordination for shorter production runs and customized bottle designs.
Poland Container Glass Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Polish container glass market. The structure consolidates around multinational furnace operators with scale advantages and mid-scale specialists with decoration capabilities. Three archetypes dominate: integrated multinationals with Central European network density, premium specialists with advanced forming and finishing technologies, and regional mid-scale producers serving private-label contracts. Competitive moves concentrate on oxy-fuel combustion retrofits for emissions compliance and direct procurement relationships that bypass traditional distribution channels.
Among multinational operators, O-I Glass Inc and Verallia Polska Sp z o o occupy positions exemplifying scale-driven and premium-tier archetypes respectively. Ardagh Glass S A represents specialization in pharmaceutical formats. These entities anchor the competitive map without exhausting the vendor base, as regional Polish limited liability companies including BA GLASS POLAND Sp z o o and Presa Sp z o o retain positions in standard container segments.
| Leading Market Players |
|---|
| O-I Glass Inc |
| Ardagh Glass S A |
| BA GLASS POLAND Sp z o o |
| Stoelzle Glass Group |
| Gerresheimer AG |
| Verallia Polska Sp z o o |
| Presa Sp z o o |
| Trend Glass Sp z o o |
| Dekorglass Dzialdowo SA |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Lower Silesian furnace operators and Central European beverage exporters lock in both cullet supply security and natural gas cost visibility across multi-year campaign cycles. These arrangements insulate Polish producers from spot market volatility while binding buyers to volume commitments that sustain furnace utilization rates above breakeven thresholds.
Pricing Analysis
Price spreads between Poznań-area producers and Czech import alternatives compress when natural gas futures spike, eroding the logistics advantage that normally protects domestic margins. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade amber glass from mass-market clear bottles and private-label jar contracts. Pricing pressure stems from aluminum can substitution in beer packaging, with mass-market brewers driving hardest bargains. Private-label retail chains exhibit highest price sensitivity; pharmaceutical formulators accept premium positioning for USP Type I certification.
Supply Chain Analysis
Inbound silica sand movements from Ukrainian and Belarusian quarries face extended customs clearance cycles at Polish border crossings, elevating raw material inventory carrying costs. Furnace operations draw from soda ash sourced in Germany, limestone from domestic Silesian deposits, and cullet recovered through Poland's extended producer responsibility framework. Single-source vulnerability concentrates in specialized borosilicate tubing for pharmaceutical vial production. Distribution runs through factory-direct relationships with retail private-label brands, bypassing traditional Warsaw-area packaging wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Poland Container Glass Market functions as a defensive-moat industry where EU F-Gas Regulation compliance costs create regulatory entrenchment that disadvantages new furnace entrants. Switching costs for beverage bottlers—mold investments, filling line calibration, and brand recognition tied to bottle design—protect incumbent positions against substitute packaging formats.
For Market Incumbents: Compound defensive advantages by deepening backward integration into cullet recovery networks across Masovian Voivodeship waste streams, securing feedstock quality for escalating EU recycled content mandates. Accelerate oxy-fuel retrofit completion at Poznań-area facilities before carbon border adjustment mechanisms fully phase in, preserving cost advantage over importers. Aluminum can substitution in mass-market beer represents the most acute threat requiring volume commitment renegotiation.
For New Entrants and Emerging Players: Differentiate on pharmaceutical vial specialization where Type I borosilicate capacity remains underpenetrated relative to Western European supply. Target Pomeranian Voivodeship for greenfield development, leveraging Gdańsk-region logistics for Nordic export markets and proximity to EMA-regulated drug formulators. Pursue toll manufacturing arrangements with established furnace operators to bypass capital-intensive greenfield construction while building batch chemistry credentials.
For Investors and Strategic Acquirers: Mid-scale decoration specialists with advanced screen printing and embossing capabilities offer the most attractive acquisition profile for premium spirits exposure. Long-term viability hinges on furnace fleet electrification readiness and regulatory compliance track records across EU Packaging and Packaging Waste Regulation implementation phases. Monitor oxy-fuel technology cost curves as the critical inflection signal for margin structure shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | Reduces natural gas intensity and positions operators ahead of EU F-Gas Regulation compliance deadlines. |
| Backward Integration into Cullet Recovery | Captures waste stream control and secures feedstock for escalating EU recycled content mandates. |
| Pharmaceutical Vial Specialization | Accesses premium pricing tiers through USP Type I certification and EMA quality guideline alignment. |
| Direct Procurement Relationships | Bypasses distributor intermediaries as Polish retail chains negotiate factory-direct volume commitments. |
| Advanced Decoration Capability Investment | Commands price premiums from craft distillers seeking shelf differentiation in export markets. |
Research Methodology
A standing panel of furnace operations managers, batch chemists, beverage procurement directors, and pharmaceutical packaging engineers provided ongoing calibration against secondary data sources. Primary fieldwork combined structured interviews with plant-level technical staff and validation against customs records, EU ETS emissions disclosures, and national waste management framework implementation reports. Bottom-up volume estimates from individual furnace campaigns triangulated against top-down demand projections from Central European beverage export data.
Consistency checks validated output trajectories against external benchmarks including EU Packaging and Packaging Waste Regulation compliance timelines and EMA quality guideline enforcement patterns. The analytical framework modeled product type, end user segment, color campaign specialization, and regional production cluster dimensions across the projection horizon. CAGRs derived from furnace capacity utilization trends, batch chemistry evolution, and buyer procurement pattern shifts. Industry-specific inputs included natural gas price volatility scenarios and aluminum can substitution elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement, stable Central European export demand, and continued natural gas supply security would require recalibration. Forecasts reflect documented assumptions regarding furnace technology adoption rates and cullet quality improvement trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Mexico Container Glass Market