
 Anti-Counterfeit Clothing and Accessories Packaging Market | 2026-2036
Anti-Counterfeit Clothing and Accessories Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Counterfeit Clothing and Accessories Packaging Market Outlook
Specialized workforce expertise in micro-optics and nanoscale printing is rotating toward authentication packaging as apparel brands escalate anti-fraud investments. Avery Dennison Corporation leverages its materials science depth to dominate RFID inlay production for garment labels. SICPA Holding SA anchors European supply chains with proprietary security ink formulations. Zebra Technologies Corporation competes through integrated printer-encoder systems that streamline tag deployment at scale.
Anti-counterfeit clothing and accessories packaging encompasses engineered materials and devices—holographic films with sub-micron groove resolutions, tamper-evident adhesives, and near-field communication substrates—that verify product authenticity and deter unauthorized replication throughout distribution channels. RFID-enabled labels lead technology adoption among premium brands seeking item-level traceability, while holographic tags sustain margin pools in mid-market accessories where cost sensitivity limits chip-based solutions. Polypropylene dominates material selection for durability in apparel hang tags, though paper substrates gain ground in sustainable packaging mandates.
The EU Green Deal and Digital Product Passport framework compel brands to disclose material provenance, directly expanding demand for traceable packaging architectures. FDA guidance on medical-grade textile authentication indirectly elevates standards for consumer apparel in cross-category manufacturers. China's SAMR enforcement against counterfeit goods intensifies domestic adoption of GB-certified holographic markers. Stakeholders must weigh interoperability investments against fragmented national certification regimes as regulatory divergence accelerates.
Market Dynamics
EU Digital Product Passport mandates are forcing apparel brands to reengineer packaging architectures for full material traceability, compressing supplier qualification timelines and elevating authentication technology to a board-level procurement priority.
Growth Catalysts
- EU Green Deal traceability mandates:The Digital Product Passport framework requires serialized packaging for all textile imports, creating binding demand for RFID and holographic verification systems across European supply chains.
- China SAMR enforcement waves:Intensified counterfeit raids against domestic fashion houses are accelerating GB-certified holographic marker adoption in Hangzhou and Guangzhou manufacturing clusters.
- NFC substrate integration:Near-field communication inlays are penetrating mid-market accessories as smartphone-native verification eliminates dedicated reader hardware requirements.
Market Restraints
- Silver price volatility:Conductive ink formulations depend on silver nanoparticle feedstocks, exposing security printer margins to London Metal Exchange spot fluctuations.
- Micro-optics talent scarcity:Holographic master origination requires sub-micron groove expertise concentrated in Swiss and German technical institutes, limiting replication capacity.
- Regulatory fragmentation:Divergent national certification regimes between EU REACH, US FDA textile guidance, and China GB standards force redundant testing protocols.
Strategic Opportunities
- India apparel export corridor:Tirupur and Surat garment clusters remain underpenetrated by item-level RFID, presenting first-mover advantages as BIS textile traceability rules crystallize.
- Blockchain-NFC convergence:Immutable ledger integration with tamper-evident tags creates auditable custody chains for resale and secondary markets.
- Medical-grade textile crossover:FDA authentication standards for surgical fabrics are migrating into luxury performance wear, opening premium positioning for compliant packaging.
Industry Challenges
- Nanoscale printing skill gaps:Workforce development in diffractive optics lags brand demand, forcing extended training cycles at converter facilities.
- Legacy ERP integration:Serialized packaging data streams require middleware overhauls at heritage fashion houses with decades-old inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Counterfeit Clothing and Accessories Packaging Market |
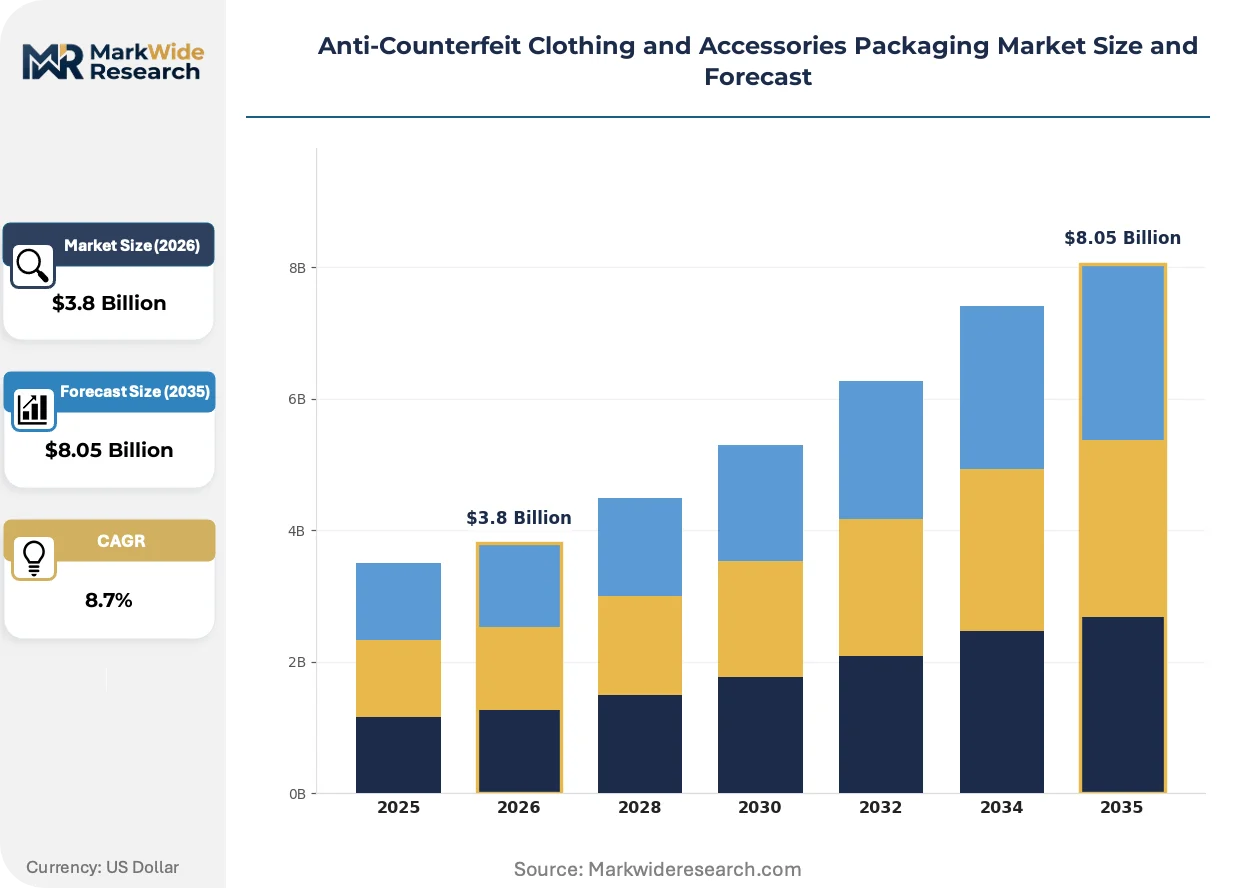
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Labels, Tags, Bottles, Pouches Material: Polypropylene, Polyethylene, Paper, Synthetic Technology: RFID, QR Codes, Holograms, Watermarks End User: Brands, Retailers, Distributors, Manufacturers |
| Companies Covered | Avery Dennison Corporation, SICPA Holding SA, Zebra Technologies Corporation, 3M Company, CCL Industries Inc., SATO Holdings Corporation, De La Rue plc, Authentix Inc., Holostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Counterfeit Clothing and Accessories Packaging Market Strategic Shifts
Authentication packaging is pivoting from passive deterrence to active data infrastructure, with embedded sensors and cloud-verified credentials becoming standard in premium apparel while cost-engineered alternatives penetrate mass-market tiers.
Micro-structured holographic films with sub-micron groove resolutions are displacing conventional foil stamping in luxury handbag authentication. Italian and French leather goods houses are mandating multi-channel diffractive elements at scale. This displacement is compressing commodity holography margins while concentrating value capture among Swiss master origination specialists.
EU Green Deal material disclosure rules are compelling brands to embed carbon footprint data within Digital Product Passport packaging. REACH-compliant adhesive substrates now require full chemical constituent documentation. High-frequency RFID inlays with sensor fusion capabilities are capturing this regulatory tailwind fastest in German and Benelux supply chains.
Direct-to-consumer resale platforms are fragmenting traditional wholesale authentication responsibility. Luxury consignment channels now demand transferable ownership credentials embedded in original packaging. This behavioral shift is most visible in US and UK markets where circular economy participation rates exceed continental European benchmarks.
Anti-Counterfeit Clothing and Accessories Packaging Market Segmentation
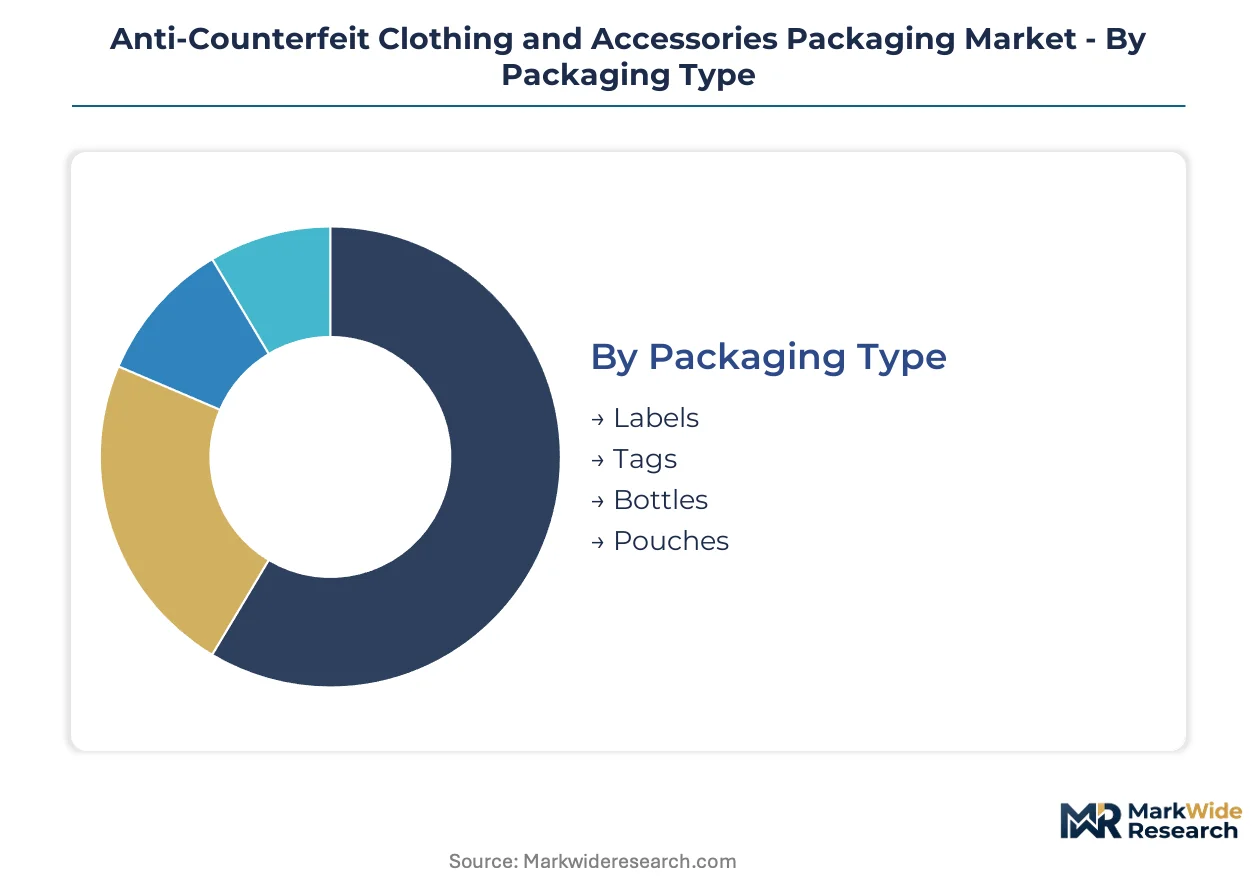
Anti-counterfeit packaging architectures fragment across four critical dimensions. Technology-material combinations determine authentication strength. End-user procurement power shapes pricing structures and deployment velocity.
Packaging Type:
Margin pools concentrate in serialized labels and tamper-evident tags where premium brands absorb per-unit authentication premiums.
- Labels:Pressure-sensitive constructions with embedded RFID inlays or holographic overlays dominate luxury apparel authentication. Demand clusters in Italian leather goods houses and French couture labels seeking item-level traceability under EU Digital Product Passport mandates.
- Tags:Hang tags and swing tickets integrate NFC substrates for smartphone-native verification. Chinese domestic fashion houses in Hangzhou manufacturing clusters are rapidly adopting GB-certified holographic tag formats following SAMR enforcement waves.
- Bottles:Rigid container authentication serves fragrance and cosmetic accessories with tamper-evident closures. Specialty ink formulations from Swiss security printers anchor European supply chains.
- Pouches:Flexible packaging with covert marking systems protects accessories in transit. Polyethylene constructions dominate cost-sensitive mid-market applications.
Labels hold installed capacity. Tags are rotating up the share rankings.
Material:
Cost tier stratification separates durable synthetics from paper-based sustainable alternatives.
- Polypropylene:Biaxially oriented films deliver tear resistance and moisture protection for apparel hang tags exposed to retail handling. German and Benelux supply chains favor this substrate for high-frequency RFID inlay lamination under REACH compliance requirements.
- Polyethylene:Low-density formulations reduce unit costs in mass-market accessories where authentication budgets compress. Surat garment clusters in India show rising polyethylene adoption as BIS textile traceability rules crystallize.
- Paper:FSC-certified substrates gain ground under EU Green Deal material disclosure mandates. Carbon footprint documentation requirements favor recyclable paper constructions in Nordic markets.
- Synthetic:Engineered films with embedded security fibers serve medical-grade textile crossover applications. FDA authentication standards for surgical fabrics elevate synthetic substrate specifications.
Polypropylene dominates volume. Paper is climbing the fastest.
Technology:
Application complexity determines technology selection from passive optical to active electronic verification.
- RFID:UHF and NFC inlays enable cloud-connected item-level tracking throughout distribution channels. Avery Dennison's materials science depth dominates inlay production for garment labels requiring serialized data carriers.
- QR Codes:Two-dimensional barcodes link to blockchain-verified product passports at minimal incremental cost. Direct-to-consumer resale platforms in US and UK markets demand transferable QR credentials.
- Holograms:Micro-structured diffractive films with sub-micron groove resolutions provide overt authentication without electronic infrastructure. Swiss master origination specialists control scarce technical expertise.
- Watermarks:Covert paper-based authentication survives mechanical stress and chemical exposure. Banknote-grade security paper migrates into luxury packaging from currency printing heritage.
Holograms hold installed capacity. RFID is gaining share fastest.
End User:
Customer type shapes procurement centralization and authentication specification authority.
- Brands:Luxury houses mandate authentication packaging specifications across licensed manufacturing networks. Board-level procurement priorities elevate anti-counterfeit technology to strategic sourcing decisions.
- Retailers:Department stores and consignment platforms demand interoperable verification systems for secondary market authentication. Transferable ownership credentials fragment traditional wholesale responsibility.
- Distributors:Logistics intermediaries require tamper-evident seals for custody chain documentation. Blockchain-NFC convergence creates auditable handoff records.
- Manufacturers:Contract producers implement brand-specified authentication under qualification timelines compressed by regulatory mandates.
Brands hold specification authority. Retailers are rotating up the influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforcement against counterfeit goods in China is compressing supplier qualification timelines across Asian supply chains. EU Digital Product Passport mandates are forcing comparable reengineering in European markets. Authentication packaging procurement now sits at board level in both geographies.
China
Hangzhou and Guangzhou manufacturing clusters are accelerating GB-certified holographic marker adoption following intensified counterfeit raids. SAMR enforcement waves have elevated authentication packaging to mandatory procurement status for domestic fashion houses. Pearl River Delta converters are expanding nanoscale printing capacity to meet compressed delivery timelines from premium brands.
Germany
Benelux-adjacent supply chains favor high-frequency RFID inlays with REACH-compliant adhesive substrates. EU Green Deal material disclosure rules are compelling full chemical constituent documentation for serialized packaging. Bavarian technical institutes are concentrating scarce micro-optics expertise to serve holographic master origination demand from Italian and French leather goods houses.
United States
FDA guidance on medical-grade textile authentication is elevating standards for consumer apparel in cross-category manufacturers. Direct-to-consumer resale platforms in New York and Los Angeles are demanding transferable ownership credentials embedded in original packaging. Pacific Northwest technology corridors are driving blockchain-NFC convergence for auditable custody chains.
India
Tirupur and Surat garment clusters remain underpenetrated by item-level RFID as BIS textile traceability rules crystallize. Maharashtra-based converters are positioning for first-mover advantages in polyethylene authentication substrates for cost-sensitive accessories. Karnataka's technology hubs are developing middleware solutions for legacy ERP integration at heritage fashion houses.
Switzerland
Swiss master origination specialists control sub-micron groove expertise concentrated in technical institutes around Zurich and Lausanne. Swissmedic-grade authentication standards are migrating into luxury performance wear packaging specifications. Geneva-based security printers are anchoring European supply chains with proprietary ink formulations for tamper-evident applications.
Anti-Counterfeit Clothing and Accessories Packaging Market Competitive Environment
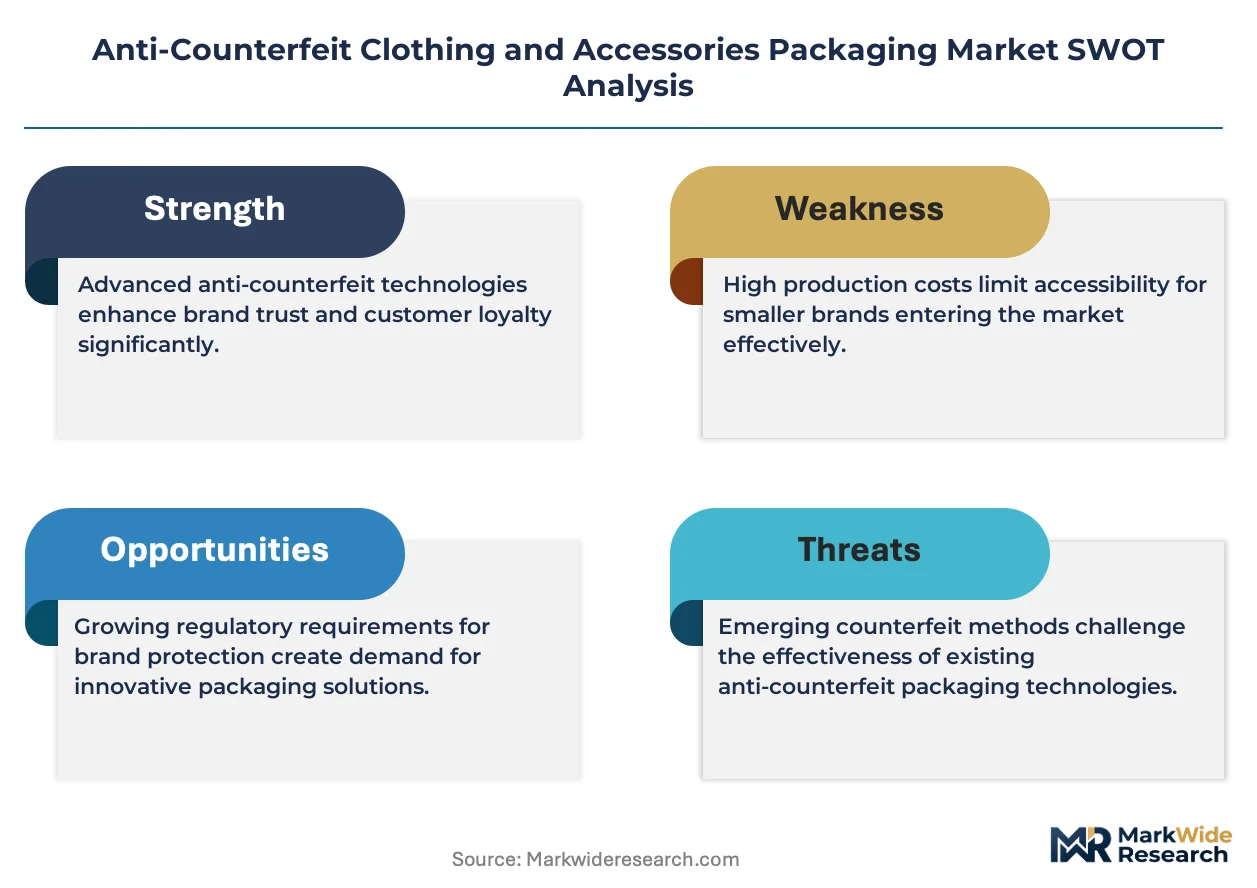
A small set of integrated leaders sits above a broader specialist tier in authentication packaging supply. The upper tier combines materials science depth with serialized data carrier production, while specialists concentrate on holographic origination or security ink formulations. Three archetypes dominate: integrated materials-converter hybrids, Swiss-German optical security specialists, and Asian scale manufacturers. Competitive moves center on backward integration into substrate production and technology licensing partnerships to secure scarce nanoscale printing capacity.
Within the integrated materials tier, Avery Dennison Corporation exemplifies the convergence of adhesive science with RFID inlay manufacturing. SICPA Holding SA anchors European supply chain security through its Swiss-heritage ink formulation capabilities. Zebra Technologies Corporation occupies a position bridging printer hardware with encoder-software integration for streamlined tag deployment. These three represent distinct strategic postures: materials-led authentication, chemical security heritage, and systems-level automation.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| SICPA Holding SA |
| Zebra Technologies Corporation |
| 3M Company |
| CCL Industries Inc. |
| SATO Holdings Corporation |
| De La Rue plc |
| Authentix Inc. |
| Holostik |
| Others |
Value Chain & Pricing Dynamics
EU Digital Product Passport certification gates supplier qualification and simultaneously stratifies price tiers between compliant and non-compliant authentication packaging converters. Brands absorb per-unit premiums for serialized RFID inlays that satisfy REACH documentation requirements, while mid-market buyers face compressed margins on holographic alternatives.
Pricing Analysis
Swiss holographic master origination commands three-to-five-fold premiums over Asian replication facilities due to sub-micron groove expertise concentration. Three-tier pricing structure across premium, standard, and economy levels separates serialized RFID-enabled labels from NFC substrates and commodity holographic tags. Cost compression in mid-market polyethylene hang tags intensifies because Chinese domestic fashion houses drive volume procurement. Mass-market accessories buyers exhibit highest price sensitivity, while luxury leather goods houses absorb authentication premiums without volume negotiation.
Supply Chain Analysis
China, Germany, and Switzerland anchor authentication packaging supply through distinct capability concentrations. Chinese Pearl River Delta converters feed volume holographic replication and NFC substrate lamination. German Benelux-adjacent facilities specialize in REACH-compliant adhesive substrates and high-frequency RFID inlay production. Swiss technical institutes around Zurich and Lausanne control scarce micro-optics talent for master origination. Silver nanoparticle feedstocks for conductive ink formulations draw from London Metal Exchange spot markets, exposing security printer margins to commodity volatility. Distribution runs through licensed converter networks rather than direct brand procurement, creating intermediary margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authentication packaging demand follows apparel inventory restocking cycles, with EU Digital Product Passport enforcement compressing supplier qualification timelines into a cyclical upswing. Procurement centralization at board level elevates vendor selection to strategic sourcing decisions.
For Market Incumbents: Secure nanoscale printing capacity through captive training programs at Bavarian and Swiss technical institutes before micro-optics talent scarcity deepens. Backward integration into polypropylene biaxially oriented film production insulates margin pressure from substrate cost volatility. Defend against Asian scale manufacturers by embedding carbon footprint documentation within serialized packaging data streams ahead of EU Green Deal phase-ins. For New Entrants and Emerging Players: Differentiate on blockchain-NFC convergence for direct-to-consumer resale platform integration, where transferable ownership credentials fragment traditional wholesale authentication responsibility. Target Tirupur and Surat garment clusters in India with cost-engineered polyethylene authentication substrates as BIS textile traceability rules crystallize. Pursue white-label middleware partnerships for legacy ERP integration at heritage fashion houses with decades-old inventory systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates with underutilized security printing divisions and stranded holographic origination capacity. Long-term viability hinges on regulatory tailwind sustainability across EU, China, and India traceability mandates. Monitor SAMR enforcement wave frequency in Hangzhou and Guangzhou manufacturing clusters as inflection indicator for Chinese domestic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive polypropylene film supply insulates Avery Dennison and CCL Industries from REACH-compliant adhesive cost volatility. |
| Micro-Optics Talent Acquisition Partnerships | Swiss technical institute collaborations secure scarce holographic master origination capacity for Italian leather goods authentication. |
| Blockchain-NFC Platform Integration | Immutable ledger verification addresses transferable ownership credential demand from US and UK resale consignment platforms. |
| India Manufacturing Footprint Expansion | Tirupur and Surat cluster proximity captures first-mover advantage as BIS textile traceability rules mandate item-level RFID. |
| Medical-Grade Certification Crossover | FDA authentication standards for surgical fabrics open premium positioning in luxury performance wear packaging specifications. |
Study Parameters
Initial hypotheses were tested against primary input from brand authentication packaging procurement directors, converter plant managers, security ink formulation chemists, and RFID inlay production engineers, then refined through secondary validation. Primary fieldwork encompassed structured interviews across Swiss holographic origination specialists, German adhesive substrate manufacturers, and Chinese Pearl River Delta replication facilities. Secondary sources included customs and trade data for authentication substrate flows, EU Digital Product Passport regulatory filings, SAMR enforcement disclosure records, and SEC 10-K disclosures from listed packaging converters. Bottom-up volume builds across technology-material combinations were triangulated against top-down apparel brand authentication spending estimates.
Variance decomposition across the projection horizon isolates technology adoption curves, regulatory phase-in schedules, and raw material cost trajectories as primary forecast drivers. Segmentation modeling incorporated packaging type, material substrate, authentication technology, and end-user procurement authority dimensions. CAGRs were derived from logistic diffusion curves fitted to historical technology penetration patterns in adjacent traceability markets. Industry-specific inputs included silver nanoparticle spot price volatility bands and micro-optics training pipeline capacity constraints.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and China SAMR raid frequency assumptions; material deviation in either regulatory driver would warrant model refresh. Forecasts embed assumptions regarding interoperability standardization timelines and legacy ERP middleware deployment velocity at heritage fashion houses. Recalibration cycles align with material shifts in EU Digital Product Passport technical specifications and BIS textile traceability rule finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Specialty Labels Packaging Market