
 Specialty Lidding Films Market | 2026-2036
Specialty Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Lidding Films Market Analytics
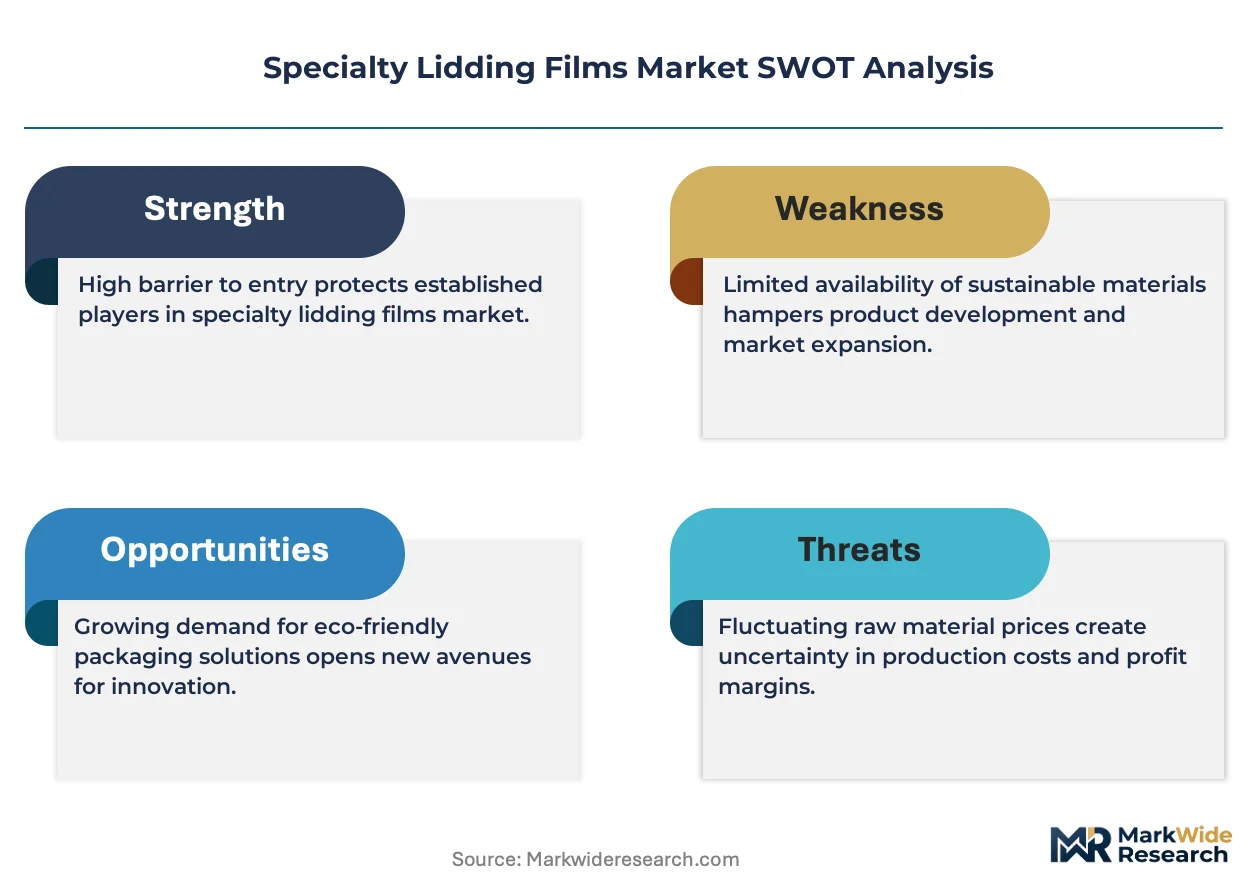
The EU Packaging and Packaging Waste Regulation is shifting demand toward mono-material and recyclable lidding constructions across European food packaging. Amcor leverages its global R&D network to develop certified-recyclable lidding solutions for protein and dairy applications. Mondi Group anchors its position through integrated kraft paper and film operations that serve fresh food segments. Berry Global specializes in high-performance sealant layers that compete on throughput efficiency in automated packaging lines.
Specialty lidding films are multi-layer polymer or coated substrates engineered to provide hermetic sealing, gas barrier, and peelability at thicknesses typically ranging from 20 to 100 microns. These films serve as the primary closure interface for rigid trays and cups in food, medical, and consumer goods packaging. Polypropylene formulations dominate fresh produce and dairy applications due to their clarity and seal range, while PET structures capture premium ready-meal segments where ovenability and high-temperature resistance command margin premiums. Tamper-evident features represent the fastest-growing functional category as pharmaceutical and food safety protocols tighten across retail and institutional channels.
The EU Green Deal and REACH frameworks govern chemical migration limits and recyclability claims, compelling reformulation of adhesives and sealant layers. The FDA maintains parallel standards for lidding films in medical device and food contact applications through 21 CFR compliance pathways. Stakeholders must monitor evolving extended producer responsibility schemes and mono-material certification benchmarks to align product development with compliance and commercial access requirements.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a wholesale material transition across European lidding film supply chains, compelling processors to abandon multi-layer barrier constructions in favor of certified-recyclable mono-material alternatives that maintain hermetic performance.
Growth Catalysts
- EU Green Deal implementation:The framework mandates recyclability benchmarks that accelerate demand for polypropylene and PET mono-material lidding constructions in dairy and ready-meal packaging across Germany, France, and the Netherlands.
- Fresh produce shelf-life extension:Modified atmosphere packaging requirements in retail grocery chains drive adoption of high-barrier lidding films with oxygen scavenging layers for cut vegetables and prepared salads.
- Pharmaceutical serialization mandates:Tamper-evident lidding with integrated authentication features expands as drug packaging regulations tighten traceability standards in institutional and retail pharmacy channels.
Market Restraints
- Ethylene and propylene feedstock volatility:Crude oil price swings transmit directly to polymer resin costs, compressing converter margins and destabilizing annual contract pricing for food processors.
- Adhesive reformulation complexity:REACH chemical migration limits force replacement of conventional solvent-based laminating adhesives, extending R&D timelines and qualifying periods for new sealant chemistries.
- Mechanical recycling contamination:Legacy multi-layer barrier films persist in waste streams, degrading recycled polymer quality and limiting closed-loop supply availability for circular packaging claims.
Strategic Opportunities
- Poland and Czech Republic packaging clusters:Underdeveloped mono-material conversion capacity in Central European dairy processing creates first-mover advantage for integrated film suppliers with certified recycling streams.
- Home-compostable barrier films:Industrial composting infrastructure expansion in Nordic markets opens premium positioning for polylactic acid and cellulose-based lidding with comparable seal performance to conventional polymers.
- Digital printing integration:Variable-data lidding with embedded QR traceability converges with smart packaging demand from protein processors seeking farm-to-fork transparency compliance.
Industry Challenges
- Mono-material certification timelines:Extended laboratory testing and third-party validation cycles for recyclability claims delay product launches by 12-18 months against fast-moving retailer sustainability mandates.
- Barrier-performance trade-offs:Removing ethylene vinyl alcohol or polyamide layers to achieve single-polymer construction degrades oxygen and moisture protection, requiring downstream packaging line speed reductions.
- Converter workforce retraining:Heat-seal optimization for thinner, more temperature-sensitive mono-material films demands upskilling of machine operators across automated tray-sealing operations.
Report Scope
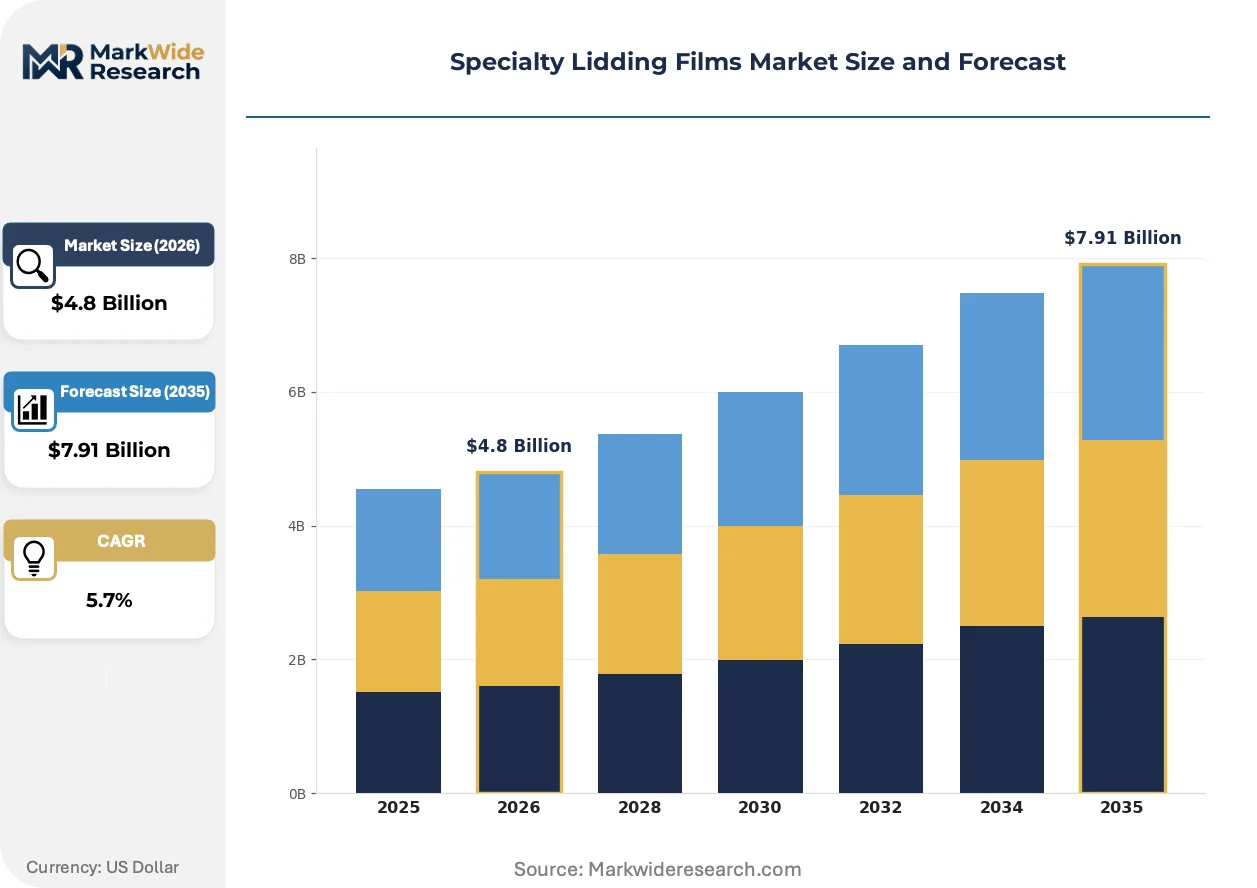
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Lidding Films Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET End Use Industry: Food Packaging, Medical Devices, Personal Care, Electronics Feature: Tamper-evident, Heat-sealable, Moisture-resistant, Recyclable Thickness: Below 30 Microns, 30-50 Microns, 50-100 Microns, Above 100 Microns |
| Companies Covered | Amcor, Mondi Group, Sealed Air Corporation, Toray Plastics, Uflex, Berry Global, ProAmpac, Plastopil Hazorea Company, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Lidding Films Market Evolving Landscape
Active and intelligent packaging functionalities are migrating from premium pharmaceutical applications into mainstream food lidding as sensor costs decline and processor traceability requirements intensify across European retail networks.
Thin-film oxygen scavenging technology is converging with high-clarity polypropylene substrates to create self-venting lidding for microwaveable ready-meals. German and French processors are piloting these constructions for premium protein trays. The convergence is compressing demand for separate absorbent pads and secondary overwrap films.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluoropolymer coatings from paper-based lidding alternatives. Converters in Italy and Spain are accelerating migration to bio-based barrier coatings derived from lignin and chitosan. Fresh bakery and deli segments face the steepest compliance timelines with January 2026 enforcement.
Consolidated retail procurement is concentrating lidding film specification authority into fewer technical buyers at pan-European grocery chains. Regional converters in Portugal and Greece report direct engagement with centralized sustainability teams replacing legacy distributor relationships. This shift compresses supplier margins while demanding faster custom development cycles for private-label packaging programs.
Specialty Lidding Films Market Segmentation
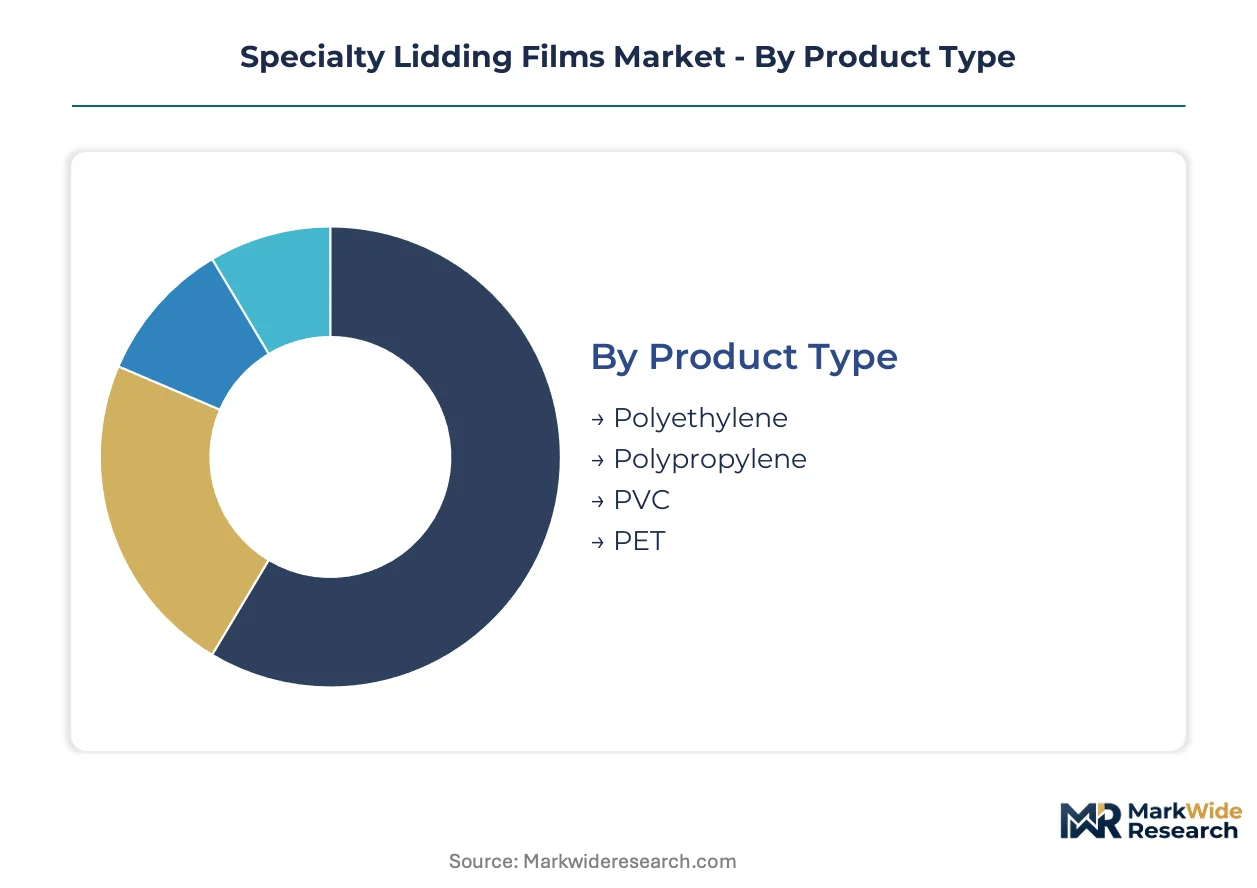
Specialty lidding films serve divergent performance requirements across food safety, medical sterility, and consumer convenience applications. Segmentation reveals how material science investments align with end-use regulatory thresholds and processing economics.
Product Type:
Capital intensity escalates with barrier complexity and conversion precision, positioning polypropylene and PET as the most equipment-intensive segments.
- Polyethylene:Lower-density formulations dominate cost-sensitive fresh produce trays where seal initiation temperatures below 120°C protect heat-sensitive contents. Demand clusters in automated salad packaging lines across Germany and the Netherlands where throughput velocity outweighs premium barrier specifications.
- Polypropylene:Clarified random copolymers and sealant-grade homopolymers require multi-layer coextrusion lines with precise thickness control. Dairy processors in France and Bavaria specify these constructions for extended shelf-life yogurt and cream applications under EFSA migration limits.
- PVC:Calendered and extruded formats persist in medical device blister packaging where thermoformability and clarity meet sterilization compatibility requirements.
- PET:Biaxially oriented structures with amorphous sealant layers command ovenable ready-meal specifications where dimensional stability above 200°C is mandatory.
Polypropylene absorbs the bulk of installed capacity; PET is expanding most quickly.
End Use Industry:
Application-driven margin structures separate commodity food volumes from regulated medical premiums.
- Food Packaging:Modified atmosphere and vacuum skin applications drive specification complexity. German protein processors and French dairy cooperatives dominate procurement volumes under EU Green Deal recyclability mandates.
- Medical Devices:Sterile barrier systems for surgical trays and pharmaceutical blisters demand ISO 11607 compliance with validated seal strength distributions. EMA guidance on packaging integrity elevates technical qualification costs.
- Personal Care:Single-serve cosmetic pods and wipe canisters prioritize peel aesthetics and fragrance retention over oxygen barrier.
- Electronics:Anti-static and moisture barrier films protect semiconductor components and lithium battery cells during transport.
Food packaging commands the dominant share of converter throughput; medical devices deliver the steepest expansion trajectory as serialization mandates proliferate.
Feature:
Functional differentiation determines pricing tiers and customer switching costs.
- Tamper-evident:Fracture patterns and holographic indicators integrate with pharmaceutical track-and-trace systems. EMA serialization deadlines accelerate specification across Central European institutional pharmacy networks.
- Heat-sealable:Sealant layer activation ranges define compatibility with tray materials from PS to PP to CPET, requiring precise rheology matching in high-speed form-fill-seal operations.
- Moisture-resistant:Metallized or ceramic-coated constructions protect hygroscopic pharmaceuticals and dried food ingredients in high-humidity climates.
- Recyclable:Mono-material certification under EU Green Deal benchmarks demands elimination of incompatible adhesive and barrier layers, compressing formulation flexibility.
Heat-sealable films retain the largest installed base; recyclable constructions are climbing the fastest as retailer mandates harden.
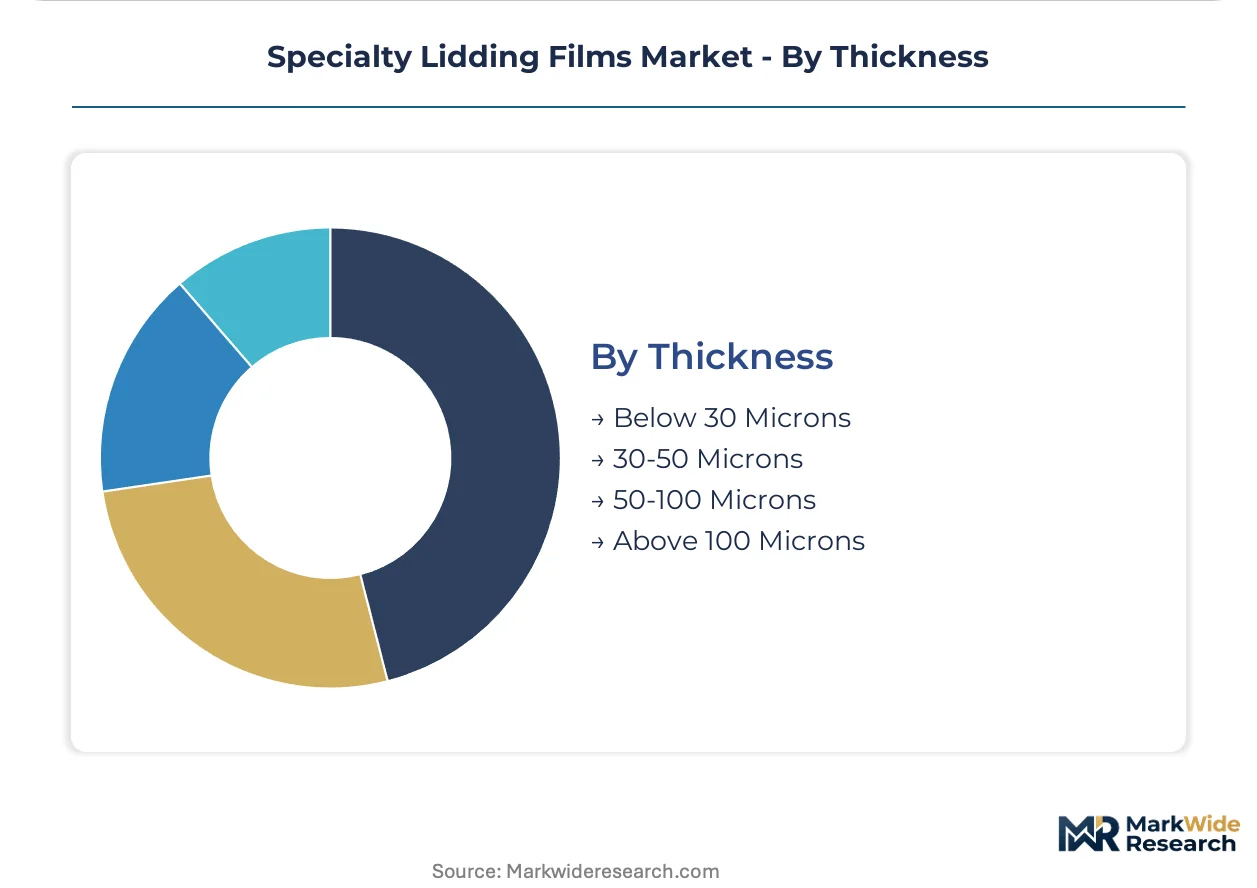
Thickness:
Calender gauge directly correlates with material throughput and unit economics.
- Below 30 Microns:Ultra-thin oriented films reduce polymer consumption in lightweight produce overwrap where mechanical abuse is minimal.
- 30-50 Microns:Standard dairy lidding balances seal integrity with cost efficiency across high-volume yogurt and dessert applications.
- 50-100 Microns:Deep-draw thermoforming compatibility and puncture resistance serve protein trays and medical blisters with demanding handling requirements.
- Above 100 Microns:Heavy-gauge constructions support industrial chemical containment and reusable food service applications with extended duty cycles.
The 30-50 micron range captures the majority of operating capacity; below 30 micron films are gaining share fastest as downgauging pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European specialty lidding film demand through its dense concentration of dairy processing and ready-meal packaging automation. The EU Packaging and Packaging Waste Regulation is redrawing material specifications across national boundaries.
Germany
Bavarian dairy cooperatives and protein processors drive specification volumes for high-barrier mono-material constructions. EFSA migration limits under REACH frameworks govern adhesive reformulation timelines. The Munich-Stuttgart corridor hosts the continent's densest cluster of automated tray-sealing operations converting polypropylene lidding at scale.
France
Parisian retail procurement consolidation is compressing supplier margins while accelerating custom development cycles for private-label programs. EU Green Deal recyclability benchmarks mandate mono-material certification for dairy and prepared salad packaging. The Brittany dairy belt and Lyon ready-meal corridor represent the highest concentration of modified atmosphere packaging specifications.
Netherlands
Rotterdam port logistics and Dutch greenhouse agriculture generate sustained demand for ultra-thin produce lidding with precision seal ranges. ECHA restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings from paper-based alternatives. The Randstad packaging cluster specializes in high-throughput salad and fresh-cut vegetable applications.
Italy
Milan-based fresh bakery and deli segments face steep compliance timelines with January 2026 enforcement of fluoropolymer coating bans. Bio-based barrier coatings derived from lignin and chitosan are accelerating through Lombardian converter R&D pipelines. The Emilia-Romagna food processing corridor represents the critical testbed for industrial composting infrastructure integration.
Poland
Warsaw and Krakow dairy processors are expanding mono-material conversion capacity to capture EU Green Deal compliance premiums. Underdeveloped certified recycling streams in Central Europe create first-mover positioning for integrated film suppliers. The Polish packaging cluster is attracting cross-border investment from German and Austrian converters seeking lower-cost qualified production.
Specialty Lidding Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier complexity and certification depth, with integrated resin-to-film operations commanding pricing power over toll-converting competitors. The vendor base separates into three strategic archetypes: multinational material science conglomerates with captive polymer supply, regional specialists in mono-material certification, and toll converters serving price-sensitive produce segments. Consolidation pressure is intensifying through backward integration into resin compounding and selective acquisition of certified recycling stream operators.
Among diversified packaging conglomerates, Amcor and Mondi Group exemplify the integrated archetype spanning polymer production through finished film conversion. Berry Global occupies a position within the high-performance sealant layer segment where throughput efficiency determines competitive viability. These three anchors represent divergent strategic postures: resin-backed scale, paper-film hybrid integration, and sealant chemistry specialization respectively.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Sealed Air Corporation |
| Toray Plastics |
| Uflex |
| Berry Global |
| ProAmpac |
| Plastopil Hazorea Company |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Mono-material certification requirements under the EU Packaging and Packaging Waste Regulation are compressing formulation flexibility while concentrating pricing power among integrated resin-to-film producers with captive recycling streams. This technology transition simultaneously elevates R&D amortization costs and reduces the supplier base capable of delivering compliant constructions, reshaping margin distribution across converters and brand owners.
Pricing Analysis
Throughput efficiency in automated tray-sealing operations anchors value-based pricing for high-performance sealant layers, with converters paying premiums for films that sustain line speeds above 200 units per minute. Price differentiation separates mono-material certified constructions from legacy multi-layer alternatives, with EU Green Deal compliance tiers commanding 15-25% spreads over uncertified grades. Pricing pressure stems from ethylene and propylene feedstock volatility transmitting directly to resin contracts, compressing margins for toll converters without backward integration into compounding. Small regional processors in Southern Europe exhibit highest price sensitivity due to limited volume scale and distributor-dependent procurement, while pan-European dairy cooperatives prioritize seal reliability over unit cost.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale demand from German and French dairy cooperatives, bypassing distributor markups for certified mono-material volumes. Raw material supply concentrates in Germany, Belgium, and the Netherlands, where integrated polymer producers feed specialized coextrusion lines with clarified random copolymers and sealant-grade homopolymers. The supply chain draws from naphtha crackers and bio-based feedstock pilots for polylactic acid alternatives, with adhesive and coating chemistries sourced from specialty chemical clusters in Switzerland and Northern Italy. Single-source vulnerability sits with ethylene vinyl alcohol barrier resin supply from limited European producers. Distribution runs through converter-owned technical sales teams for qualified accounts, supplemented by regional distributors serving price-sensitive produce segments in Iberia and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation has erected a cost-of-compliance barrier that favors incumbents with validated mono-material portfolios and certified recycling stream access, effectively moating out undercapitalized toll converters.
For Market Incumbents: Extend certification depth into Central European dairy processing clusters before competitor capacity arrives in Poland and the Czech Republic. Prioritize backward integration into resin compounding to defend margin position against feedstock volatility. Acquire certified recycling stream operators to secure circular packaging claims that retailer sustainability teams now mandate. For New Entrants and Emerging Players: E-commerce-enabled technical sampling platforms offer low-friction entry into mid-size French and Italian converters seeking rapid mono-material qualification. Target underpenetrated fresh bakery segments in Lombardy and Emilia-Romagna facing January 2026 fluoropolymer coating bans with bio-based barrier alternatives. Lead with digital print-integrated lidding pilots that converge smart packaging demand with farm-to-traceability compliance. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking European mono-material capacity. Long-term viability favors integrated film suppliers with captive polymer supply and validated recycling partnerships over toll-converting assets. Watch for retailer sustainability mandate acceleration as the inflection signal that compresses valuation multiples for non-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Certification Investment | EU Green Deal compliance unlocks access to pan-European dairy and ready-meal procurement. |
| Backward Integration into Resin Compounding | Captive polymer supply hedges against ethylene and propylene contract volatility. |
| Certified Recycling Stream Acquisition | Closed-loop material claims satisfy retailer extended producer responsibility requirements. |
| Digital Printing Integration Partnership | Variable-data lidding aligns with protein processor farm-to-fork transparency mandates. |
| Central European Capacity Expansion | Polish and Czech dairy clusters offer first-mover positioning before supply saturation. |
Research Methodology
Independent corroboration across converter technical directors, dairy processor packaging engineers, and retailer sustainability procurement leads underwrites the qualitative findings in this analysis. Primary fieldwork encompassed structured interviews with sealant layer R&D heads at integrated film producers, automation specialists at tray-sealing equipment OEMs, and regulatory affairs managers navigating REACH and EU Green Deal compliance pathways. Secondary validation drew from ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation implementation guidance, customs trade data for polymer resin flows, and SEC filings of listed packaging conglomerates. Bottom-up capacity estimates from identified coextrusion lines were triangulated against top-down demand projections from end-use segment consumption patterns.
Comparable-period anchoring established historical reference baselines from pre-regulatory implementation volumes through current mono-material transition phases across the projection horizon. The analytical framework modeled demand across material type, end-use application, functional feature, and thickness segmentation, with additional dimensioning by regional regulatory cluster and certification status. CAGRs were derived from elasticity-adjusted consumption trajectories reflecting substitution effects between multi-layer and mono-material constructions. Industry-specific forecast inputs included dairy processing automation capex cycles, pharmaceutical serialization mandate timelines, and retailer private-label packaging program refresh rates.
The model holds under stable regulatory enforcement trajectories and continued retailer sustainability mandate escalation; deviation in mechanical recycling infrastructure deployment or feedstock price shocks would shift volume and value outputs. Forecasts reflect documented assumptions regarding mono-material certification adoption curves and adhesive reformulation completion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Custom Packaging Boxes Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Speciality Vials Market