
 Specialty Uncoated Paper Label Market | 2026-2036
Specialty Uncoated Paper Label Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Uncoated Paper Label Market Analytics
Direct supply partnerships between substrate mills and label converters is reconfiguring procurement patterns across the specialty uncoated paper label value chain. Mondi Group leverages captive pulp integration to secure fiber traceability for European brand owners. UPM Specialty Papers anchors its position through dedicated calendering lines optimized for pressure-sensitive adhesive compatibility. Fedrigoni competes on aesthetic surface grades targeting wine and spirits applications where tactile quality commands premium positioning.
Specialty uncoated paper labels comprise non-surface-treated cellulose substrates engineered with controlled porosity and formation uniformity for direct printing or adhesive lamination, typically specified in basis weights from 60 to 120 gsm with wet strength additives for durability in moist environments. Their primary commercial purpose centers on variable information printing, brand communication, and regulatory compliance marking across packaged goods. Thermal labels lead volume consumption in logistics and e-commerce fulfillment where scannable permanence is essential, while eco-friendly labels represent the fastest-expanding margin pool as consumer goods manufacturers respond to retailer sustainability scorecards. Pressure-sensitive labels sustain dominant share in food packaging where removability and repositioning properties reduce application waste on high-speed bottling lines.
FDA food contact substance notifications govern substrate purity for labels applied directly to consumable surfaces in the United States, while REACH and the EU Packaging and Packaging Waste Directive shape chemical migration limits and recyclability claims across European supply chains. Japan's METI enforces JIS standards for label permanence in industrial cold-chain applications, creating differentiated compliance thresholds for export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks and fiber certification requirements as these regulatory layers increasingly determine market access rather than merely product specification.
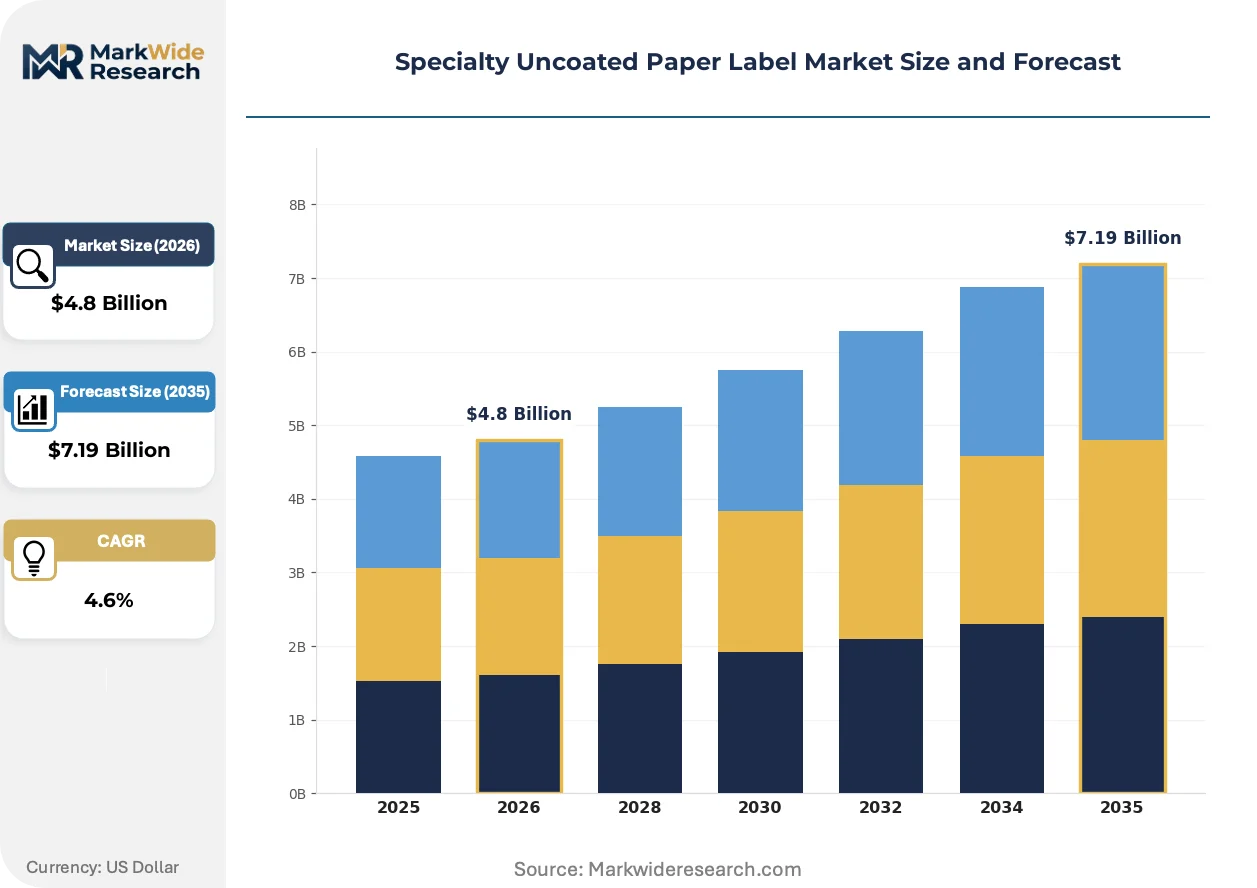
Market Dynamics
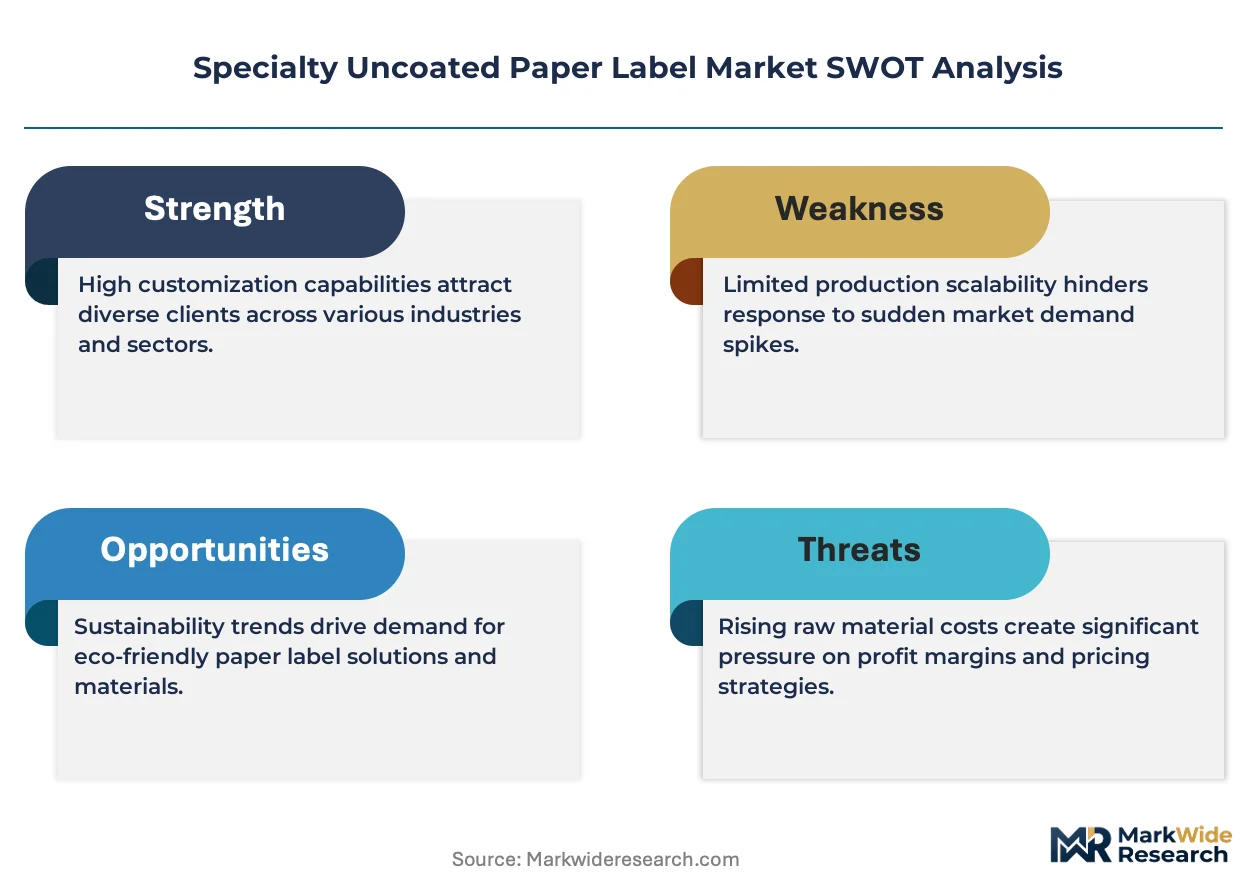
Direct mill-to-converter partnerships are compressing traditional distribution tiers in the specialty uncoated paper label supply chain, with fiber traceability requirements from the EU Green Deal forcing substrate producers to consolidate procurement relationships.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating cold-chain labeling upgrades across European food logistics, driving wet-strength substrate specifications.
- E-commerce fulfillment:Thermal label consumption in automated sortation centers is expanding addressable volume for scannable permanence grades.
- Germany:Premium beverage labeling standards for organic wines and craft spirits are concentrating demand for tactile surface grades with controlled formation uniformity.
Market Restraints
- Pulp cost volatility:Hardwood fiber price swings constrain margin predictability for mid-tier converters without captive pulp integration.
- REACH chemical migration limits:Compliance testing timelines extend product development cycles for labels with direct food contact applications.
- Film label substitution:Polypropylene alternatives encroach on moisture-exposed applications where wet-strength paper carries performance premiums.
Strategic Opportunities
- Extended Producer Responsibility frameworks:EU Packaging and Packaging Waste Directive amendments reward fiber-based solutions with recyclability certification.
- Digital hybrid printing:Convergence of inkjet and flexographic systems enables short-run variable data on uncoated stocks without plate costs.
- Direct-to-brand procurement:Bypassing merchant distributors, substrate mills contract directly with multinational food packagers for sustainability scorecard compliance.
Industry Challenges
- Calendering expertise scarcity:Pressure-sensitive adhesive compatibility requires specialized finishing knowledge concentrated among aging European equipment operators.
- ISO 14001 certification timelines:Environmental management system audits delay market access for Asian substrate entrants targeting EU brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Uncoated Paper Label Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Labels, Pressure-Sensitive Labels, Waterproof Labels, Eco-Friendly Labels Application: Food Packaging, Retail Labels, Industrial Marking, Shipping Labels End User: Consumer Goods, Electronics, Logistics, Healthcare Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Mondi Group, UPM Specialty Papers, Ahlstrom, Sappi, Nippon Paper Industries, Fedrigoni, Lintec Corporation, Delfort Group, Pixelle Specialty Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Uncoated Paper Label Market Evolving Landscape
Substrate engineering and compliance architecture are converging to redefine competitive differentiation in specialty uncoated paper labels, with fiber provenance and print compatibility becoming inseparable purchase criteria.
Water-based barrier coatings are rendering obsolete conventional polyethylene-laminated stocks in chilled food applications. German organic dairy processors and French ready-meal packagers are specifying these treatments at scale. The technology is rendering obsolete legacy moisture-protection approaches that compromised fiber recyclability, compressing the addressable market for film-faced alternatives.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant label treatments. Industrial consequence includes accelerated R&D spending on bio-based barrier chemistries among substrate mills serving the snack food sector. Bakery and confectionery applications in the Netherlands and Belgium are most affected, with converters stockpiling compliant inventory ahead of enforcement deadlines.
Brand-owner sustainability scorecards are consolidating supplier panels around fiber certification holders. Food packaging procurement teams at European retailers now mandate FSC or PEFC chain-of-custody documentation as a threshold qualification. This behavior is most visible in German and Austrian organic food channels, where labeling authenticity supports premium shelf positioning.
Specialty Uncoated Paper Label Market Segmentation
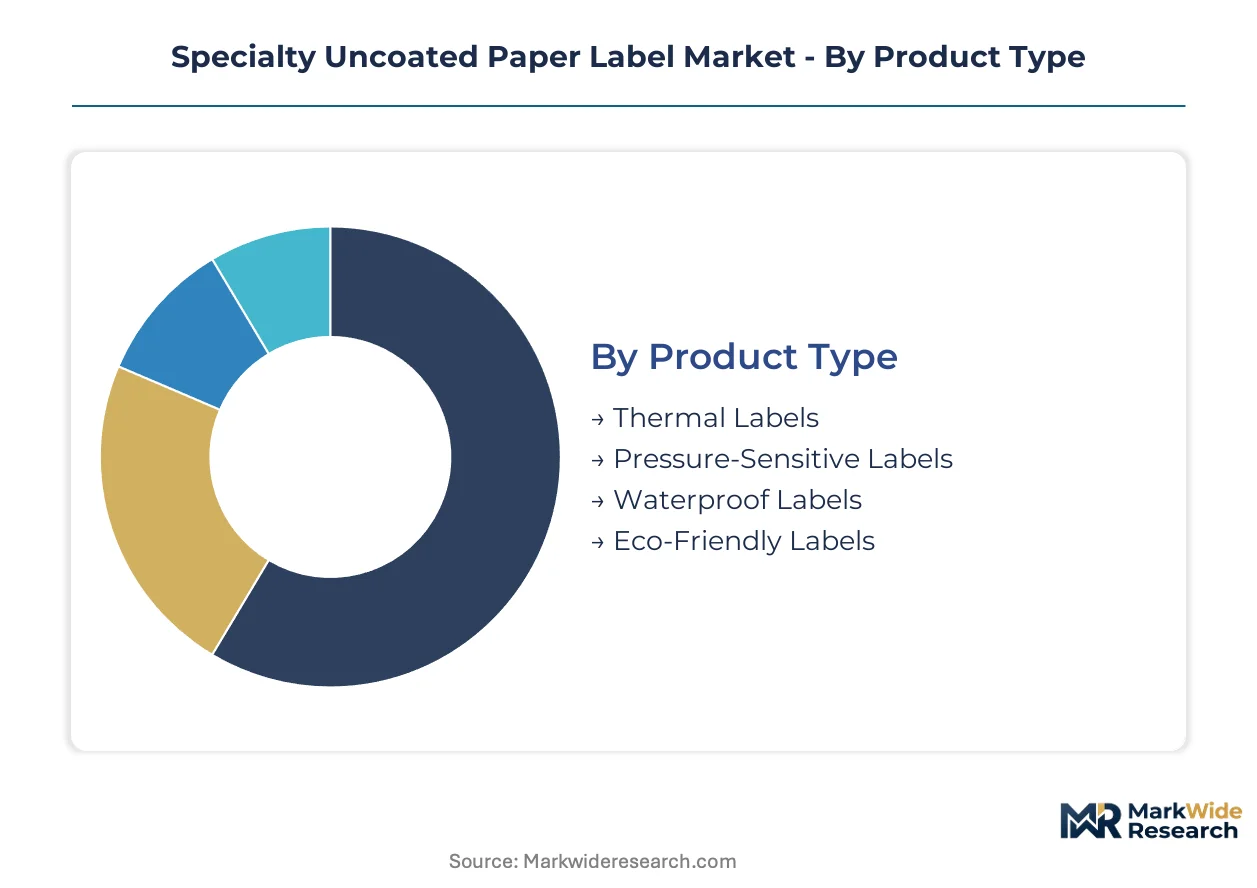
Specialty uncoated paper label procurement diverges sharply across product specifications and end-use requirements. Substrate mills calendering lines, adhesive compatibility testing, and regulatory compliance documentation all vary by segment, creating distinct margin architectures.
Product Type:
Cost tier differentiation separates commodity thermal stocks from engineered pressure-sensitive grades with specialized surface treatments.
- Thermal Labels:Chemically treated substrates with thermochromic coatings enable direct thermal printing without ribbon consumption. Logistics operators in automated e-commerce fulfillment centers specify these for scannable permanence at high print speeds. FDA food contact substance notifications govern direct thermal adhesive migration limits for consumable-facing applications.
- Pressure-Sensitive Labels:Face stocks engineered with controlled release coatings accommodate acrylic or rubber-based adhesives for repositionable application. German beverage bottlers and French dairy packagers dominate procurement of wet-strength variants for high-speed labeling lines where removability reduces waste.
- Waterproof Labels:Synthetic fiber blends or dense hardwood pulping yield moisture-resistant formation for industrial cold-chain exposure.
- Eco-Friendly Labels:FSC-certified substrates with bio-based barrier coatings address retailer sustainability scorecards.
Thermal labels command the established base. The steepest expansion runs through eco-friendly labels.
Application:
Application segmentation tracks regulatory exposure and moisture resistance requirements across packaged goods verticals.
- Food Packaging:Direct food contact applications demand substrate purity compliance under FDA notifications and REACH chemical migration limits. Wet-strength additives and grease-resistant barrier treatments concentrate R&D spending among European substrate mills serving organic food channels in Germany and Austria.
- Retail Labels:Variable information printing for price marking and promotional coding requires thermal transfer compatibility and scuff resistance.
- Industrial Marking:JIS standards for label permanence govern Japanese cold-chain exports, creating differentiated compliance thresholds.
- Shipping Labels:E-commerce volume expansion drives thermal label consumption in automated sortation infrastructure.
Food packaging anchors procurement volume. Industrial marking climbs the fastest on cold-chain infrastructure investment.
End User:
End user segmentation reflects divergent durability specifications and regulatory stringency across vertical supply chains.
- Consumer Goods:Brand authentication and shelf-appeal requirements drive specification of tactile surface grades with controlled formation uniformity. Organic wine and craft spirits labeling in Germany concentrates demand for premium uncoated stocks.
- Electronics:Anti-static treatments and precision die-cutting compatibility characterize specifications for component tracking labels.
- Logistics:Scannable permanence and weather resistance dominate procurement criteria for parcel identification.
- Healthcare:Sterilization resistance and biocompatibility documentation requirements govern substrate selection for medical device labeling.
Consumer goods retains the largest addressable spend. Healthcare gains share fastest on regulatory documentation requirements.
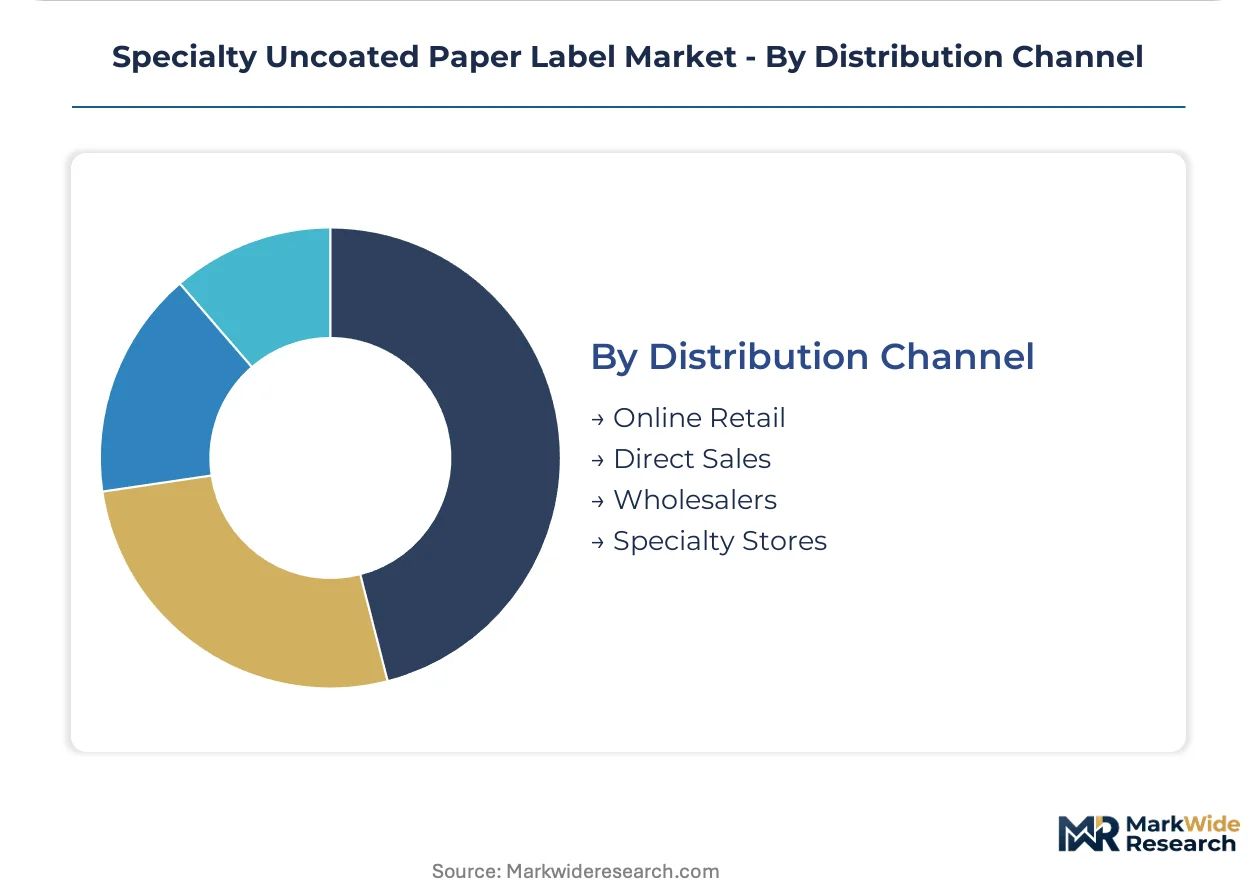
Distribution Channel:
Channel segmentation captures the compression of traditional merchant tiers by direct mill-to-converter contracting.
- Direct Sales:Substrate mills contract directly with multinational food packagers for fiber traceability documentation and sustainability scorecard compliance. The EU Green Deal procurement requirements accelerate this channel's expansion.
- Online Retail:Digital platforms enable small converters to access certified label stocks without minimum order constraints imposed by traditional distributors.
- Wholesalers:Inventory aggregation and technical support services sustain relevance for mid-tier converters lacking direct mill relationships.
- Specialty Stores:Regional distributors with calendering expertise and pressure-sensitive adhesive compatibility knowledge serve niche applications.
Direct sales commands margin expansion. Online retail scales most quickly on small-batch flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand dynamics, with Germany's organic food labeling standards creating concentrated procurement pull for tactile surface grades. Fiber traceability requirements from Brussels reshape supplier relationships across the continent.
Germany
Premium beverage and organic food labeling standards concentrate demand for controlled formation uniformity substrates. The EU Green Deal procurement mandates force direct mill-to-converter contracting for sustainability scorecard compliance. Bavarian organic dairy processors specify water-based barrier coatings at scale, displacing polyethylene-laminated alternatives.
United States
FDA food contact substance notifications govern substrate purity for consumable-facing label applications. E-commerce fulfillment volume expansion drives thermal label consumption in automated sortation infrastructure. Chicago-area logistics operators specify scannable permanence grades for high-speed parcel identification systems.
France
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of grease-resistant label treatments. Bakery and confectionery applications in the Paris basin stockpile compliant inventory ahead of enforcement deadlines. Lyon-based ready-meal packagers specify bio-based barrier chemistries for chilled food labeling.
Japan
METI enforces JIS standards for label permanence in industrial cold-chain applications, creating differentiated compliance thresholds for export-oriented manufacturers. Osaka-Nagoya industrial corridor concentrates wet-strength substrate procurement for seafood logistics. Kanto region electronics assemblers demand anti-static treatments for component tracking labels.
India
BIS certification requirements and FSSAI food contact regulations shape substrate selection for domestic and export-oriented label converters. Maharashtra pharmaceutical clusters drive demand for sterilization-resistant medical device labeling stocks. Gujarat textile and chemical logistics operations expand thermal label procurement for warehouse automation.
Specialty Uncoated Paper Label Market Competitive Landscape
Integrated pulp producers and specialized substrate engineers split the market between fiber security and surface engineering excellence. Three to four major players anchor the premium tier through captive raw material control, while mid-tier converters compete on calendering expertise and adhesive compatibility services. Strategic archetypes include backward-integrated forest products conglomerates, dedicated specialty paper mills with optimized finishing lines, and regional converters with deep technical support capabilities. Competitive moves center on direct contracting with multinational food packagers and certification acquisition for EU sustainability frameworks.
Among European-anchored producers, Mondi Group exemplifies the backward-integrated archetype through fiber traceability offerings, while UPM Specialty Papers occupies a position defined by dedicated calendering infrastructure. Fedrigoni represents the aesthetic-grade specialist tier targeting premium beverage applications where tactile quality commands positioning premiums.
| Leading Market Players |
|---|
| Mondi Group |
| UPM Specialty Papers |
| Ahlstrom |
| Sappi |
| Nippon Paper Industries |
| Fedrigoni |
| Lintec Corporation |
| Delfort Group |
| Pixelle Specialty Solutions |
| Others |
Value Network & Pricing Analysis
German calendering expertise concentration anchors premium-grade pricing power, with Bavarian and Baden-Württemberg substrate mills capturing margin pools downstream through direct contracting with multinational organic food packagers. Pulp cost volatility in hardwood fiber markets feeds back into converter procurement strategies, compressing mid-tier players without captive fiber integration.
Pricing Analysis
European price spreads exceed Asian benchmarks by substantial margins for FSC-certified wet-strength grades. Three-tier pricing structure across premium tactile surface grades, standard thermal stocks, and economy logistics substrates dominates transactional models. Certification tier and volume scale drive price differentiation, with sustainability scorecard compliance commanding substantial premia. Cost compression in mid-tier thermal stocks is intensifying because e-commerce fulfillment operators consolidate procurement around scannable permanence specifications. Logistics converters exhibit highest price sensitivity; German organic beverage bottlers show lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Mondi Group's captive pulp integration, UPM Specialty Papers' dedicated calendering infrastructure, and Fedrigoni's aesthetic-grade finishing lines. Geographic supply concentrates in Finland, Austria, and Germany for premium grades; China and Indonesia for commodity thermal stocks. Hardwood fiber, wet-strength chemical additives, and bio-based barrier coatings constitute critical input dependencies. Single-source vulnerability in European calendering expertise creates structural risk. Distribution runs through direct mill-to-converter partnerships for sustainability scorecard compliance, with merchant distributors serving mid-tier converters lacking direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calendering expertise scarcity defines competitive boundaries, with aging European equipment operators possessing irreplaceable pressure-sensitive adhesive compatibility knowledge that substrate mills cannot replicate through capital expenditure alone.
For Market Incumbents: Build certification moats through FSC chain-of-custody documentation and ISO 14001 environmental management systems. Film label substitution in moisture-exposed applications threatens paper-based margin pools. Defend through backward integration into hardwood fiber sourcing and capacity retention in German finishing corridors where tactile-grade expertise concentrates. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical labeling stocks where BIS certification requirements and FSSAI food contact regulations create compliance barriers for unqualified competitors. Maharashtra sterilization-resistant medical device segments offer penetrable white space. Attack through digital hybrid printing service bundling for short-run variable data applications. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated forest products conglomerates with demonstrated fiber traceability capabilities and established direct contracting relationships with EU multinational food packagers. Long-term viability hinges on EU Green Deal procurement mandate expansion. Watch for REACH Annex XVII enforcement acceleration on per- and polyfluoroalkyl substances as inflection signal for bio-based barrier chemistry R&D spending.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Fiber | Mondi Group's captive pulp sourcing secures traceability documentation for EU Green Deal compliance. |
| Direct-to-Brand Contracting | UPM Specialty Papers bypasses merchant distributors to anchor multinational food packager sustainability scorecards. |
| Digital Hybrid Printing Investment | Fedrigoni's inkjet-flexographic convergence enables short-run wine and spirits labeling without plate costs. |
| Water-Based Barrier Coating Scale-Up | Bavarian organic dairy processor specifications displace polyethylene-laminated stocks in chilled food channels. |
| Calendering Expertise Retention | Austrian substrate mills lock in aging European equipment operators through specialized knowledge transfer programs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with substrate mill technical directors, label converter procurement leads, brand-owner sustainability officers, and European retailer category managers; and secondary validation through EU Packaging and Packaging Waste Directive amendments, ECHA REACH substance restrictions, FDA food contact substance notifications, FSC chain-of-custody databases, and customs trade flow records. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and end-user segmentation dimensions.
Forecast inputs considered pressure-sensitive adhesive compatibility specifications, wet-strength additive formulations, thermal coating chemistries, and fiber certification penetration rates across the analysis window. Segmentation modeling tracked product type, application vertical, end-user durability requirements, and distribution channel evolution. CAGRs derived from regression analysis against e-commerce fulfillment infrastructure deployment, cold-chain logistics investment, and organic food channel expansion metrics.
Sensitivities concentrate around pulp cost volatility, REACH chemical migration limit enforcement timelines, and extended producer responsibility framework adoption velocity. Quarterly review of EU F-Gas Regulation refrigerant phase-down progress, German organic food labeling standard revisions, and Asian substrate mill ISO 14001 certification completion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Custom Packaging Boxes Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Europe Child Resistant Packaging Market