
 Speciality Vials Market | 2026-2036
Speciality Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Speciality Vials Market Analytics
Preventive maintenance contracts for automated visual inspection lines is pivoting the commercial model from unit sales to uptime guarantees. Gerresheimer AG leverages its captive tubular glass furnaces in Europe and North America to secure supply continuity for biologics customers. Schott AG anchors premium borosilicate capacity through proprietary FIOLAX formulations that meet US FDA Type I standards. Stevanato Group differentiates via integrated offerings spanning glass tubing, converted vials, and ready-to-use sterile packaging.
Speciality vials are precision-engineered primary containers manufactured from borosilicate glass or cyclic olefin polymers, designed to maintain sterility, chemical inertness, and dimensional tolerance within ±0.1 mm for automated filling lines. Glass vials retain dominance in high-value biologics due to oxygen barrier performance and regulatory familiarity, while plastic vials gain share in point-of-care diagnostics where breakage resistance and reduced shipping weight matter. Pharmaceutical applications command the deepest margin pools because of validation burdens and long-term supply agreements, whereas diagnostics vials compete on throughput scale and price per thousand units.
US FDA container closure integrity guidance, EU MDR device regulations, and ISO 15378 pharmaceutical packaging standards collectively elevate barrier property documentation and extractables testing requirements. The FDA's emphasis on leachable profiles for novel biologics formats directly shapes material selection and supplier qualification timelines. Stakeholders must monitor evolving USP <665> and <1665> polymer system standards, as these will determine which resin platforms qualify for next-generation cell and gene therapy containment.
Market Dynamics
Pre-sterilized ready-to-use vial formats are compressing fill-finish timelines and forcing glass converters to restructure capacity around captive furnace operations rather than merchant tubing supply.
Growth Catalysts
- Biologics fill-finish automation:mRNA and cell therapy manufacturers are specifying dimensional tolerances within ±0.1 mm to eliminate line stoppages, pulling demand toward precision-converted borosilicate formats.
- EU MDR device regulations:Drug-device combination product rules are mandating enhanced material traceability and extractables documentation, privileging suppliers with integrated tubing-to-vial production records.
- German production clusters:High-volume borosilicate capacity concentrated in the Rhine-Main region is securing supply continuity for pandemic-scale biologics manufacturing.
Market Restraints
- Energy-intensive furnace operations:Natural gas and electricity input costs for tubular glass melting create margin volatility that merchant converters cannot fully pass through under long-term supply agreements.
- Supplier concentration in Central Europe:Captive furnace ownership by integrated manufacturers limits independent access to FIOLAX-grade borosilicate tubing for mid-scale biologics fill-finish operations.
- Polymer oxygen barrier limitations:Cyclic olefin polymer vials remain excluded from oxygen-sensitive biologics despite breakage resistance advantages in diagnostic applications.
Strategic Opportunities
- Point-of-care diagnostics expansion:Plastic vial demand from decentralized testing networks in India and Brazil is creating volume pools where reduced shipping weight outweighs barrier performance trade-offs.
- USP <665> polymer qualification pathway:Evolving standards for plastic pharmaceutical packaging systems will determine which resin platforms capture next-generation cell and gene therapy containment contracts.
- Preventive maintenance service contracts:Automated visual inspection line vendors are pivoting from unit sales to uptime guarantees, embedding recurring revenue into capital equipment relationships.
Industry Challenges
- Extractables testing capacity bottlenecks:Analytical chemistry and toxicology functions required for leachable profile documentation face talent scarcity that extends supplier qualification timelines.
- Legacy fill-finish line retrofit requirements:Automated handling systems designed for legacy vial formats require mechanical recalibration to accommodate ready-to-use sterile packaging dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speciality Vials Market |
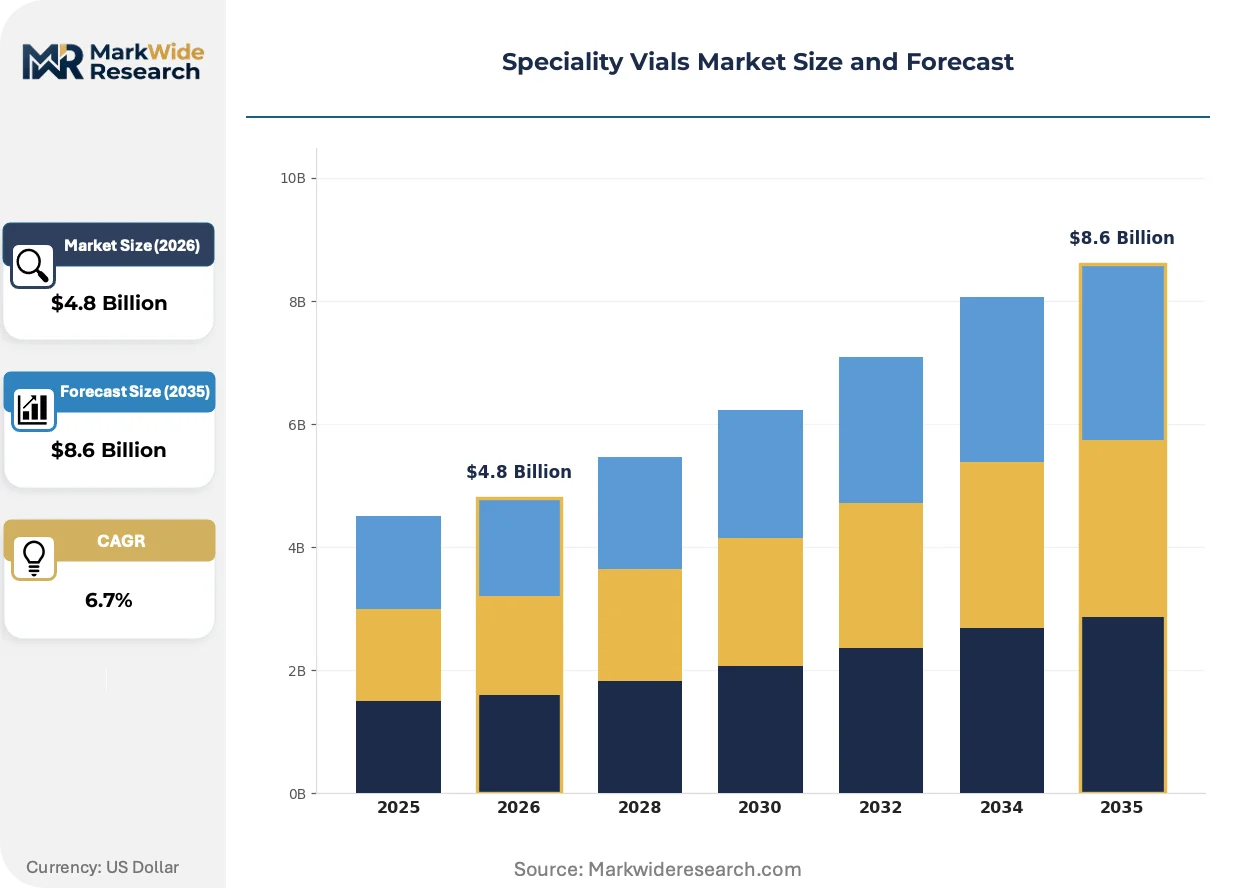
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Multi-dose Vials, Single-use Vials Application: Pharmaceuticals, Biologics, Research, Diagnostics Capacity: 1 ml, 5 ml, 10 ml, 20 ml End User: Hospitals, Laboratories, Pharmaceutical Companies, Contract Manufacturing |
| Companies Covered | Gerresheimer AG, Schott AG, West Pharmaceutical Services, Stevanato Group, Corning Incorporated, Nipro Corporation, Bormioli Pharma, SGD Pharma, Piramal Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speciality Vials Market Evolving Landscape
Material science advances and regulatory documentation requirements are compressing the supplier base while creating tiered service models that separate integrated manufacturers from merchant converters.
Sterile ready-to-use vial platforms are converging with isolator-based fill-finish lines to eliminate human intervention in aseptic processing. Large-molecule biologics manufacturers in Germany and the United States are specifying these combined systems for pandemic preparedness manufacturing networks. This convergence is compressing validation timelines and disqualifying suppliers lacking both converted vial capacity and sterilization infrastructure.
EU MDR requirements for drug-device combination products are tightening extractables testing protocols beyond prior pharmaceutical packaging norms. Manufacturers must now document material traceability across the entire tubing-to-vial conversion chain. High-value biologics applications face the steepest compliance burden, with sponsors in Switzerland and the Netherlands accelerating supplier audits to preempt regulatory scrutiny.
Biologics procurement teams are consolidating supplier relationships around integrated glass tubing and conversion capabilities. Merchant converters without captive furnace access are losing position in long-term supply agreements for mRNA and cell therapy applications. This consolidation is most visible in Germany, where Gerresheimer and Schott have secured decade-long contracts with top-ten pharmaceutical sponsors.
Speciality Vials Market Segmentation
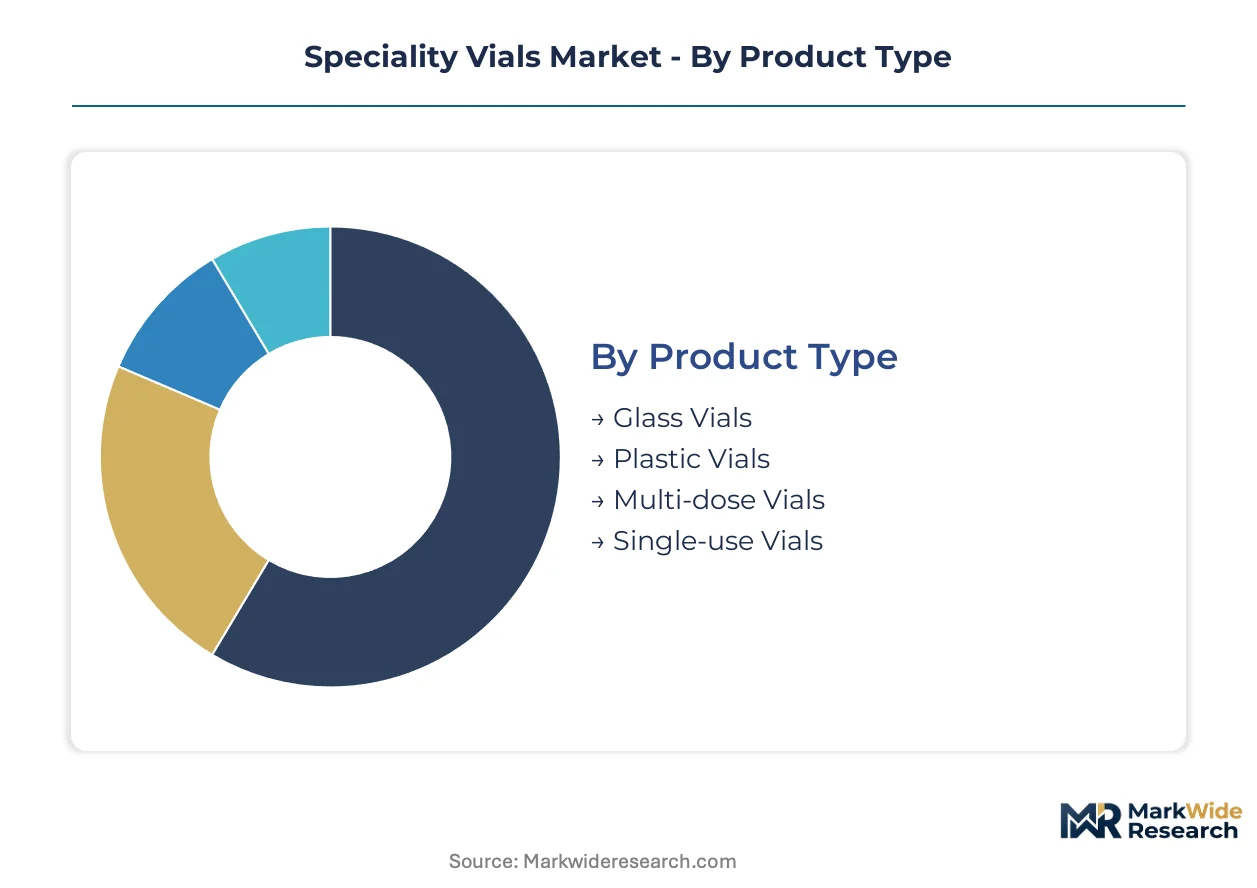
Speciality vials segmentation reflects divergent technical requirements across containment applications. Material selection, dimensional precision, and sterilization compatibility determine supplier qualification pathways and pricing tiers.
Product Type:
Glass and plastic formats anchor opposite ends of the customization-vs-standardization spectrum, with glass demanding furnace-captive supply chains and plastic enabling modular sourcing.
- Glass Vials:Borosilicate Type I construction delivers oxygen barrier performance below 0.1 cc/day and dimensional tolerances within ±0.1 mm for automated fill-finish lines. Demand concentrates in German and US biologics manufacturing clusters where mRNA and cell therapy sponsors require FIOLAX-grade material traceability under EU MDR documentation rules.
- Plastic Vials:Cyclic olefin polymer formulations offer breakage resistance and 40% shipping weight reduction versus glass. Indian and Brazilian point-of-care diagnostics networks are absorbing volume where barrier trade-offs are acceptable for decentralized testing workflows.
- Multi-dose Vials:Rubber-stoppered formats with preservative compatibility for repeat-access formulations.
- Single-use Vials:Pre-sterilized ready-to-use configurations compressing aseptic processing timelines.
Leading the category by volume: Glass Vials. Growing fastest: Plastic Vials.
Application:
Margin concentration varies sharply across end-uses, with validation burdens and long-term supply agreements differentiating pharmaceutical from diagnostic demand patterns.
- Pharmaceuticals:Small-molecule and generic drug containment requiring USP <661> glass compliance and extractables documentation under FDA container closure guidance. Procurement teams in Switzerland and the Netherlands are consolidating supplier relationships around integrated tubing-to-vial capabilities.
- Biologics:Large-molecule, mRNA, and cell therapy applications specifying the tightest dimensional tolerances and oxygen barrier performance. German fill-finish automation investments are pulling demand toward captive furnace supply chains.
- Research:Lower-volume, higher-SKU requirements with flexible specification tolerances.
- Diagnostics:High-throughput, price-sensitive demand where plastic formats gain share through reduced breakage and logistics costs.
Pharmaceuticals capture the deepest margin pools. Biologics is climbing the fastest.
Capacity:
Volume scale and line compatibility drive specification clustering, with automated handling systems favoring standardized formats that minimize mechanical recalibration.
- 1 ml:Precision dosing formats for high-potency biologics and pediatric applications.
- 5 ml:Standard fill volumes for injectable pharmaceuticals and vaccine distribution.
- 10 ml:Workhorse capacity for multi-dose antibiotic and biologics presentations. US and German pandemic preparedness manufacturing networks are standardizing on this format for fill-finish line interoperability.
- 20 ml:Large-volume parenteral and diluent applications with lower automation compatibility requirements.
10 ml dominates procurement volumes. 1 ml shows steepest expansion trajectory.
End User:
Customer type determines contracting structure, with pharmaceutical sponsors locking in decade-long agreements while contract manufacturers prioritize supply flexibility.
- Pharmaceutical Companies:Integrated sponsors in Germany and the United States are signing long-term supply agreements with Gerresheimer and Schott for captive furnace access. FDA and EU MDR compliance documentation requirements extend supplier qualification timelines beyond 18 months.
- Contract Manufacturing:CDMOs serving mid-scale biologics sponsors face constrained access to FIOLAX-grade tubing due to integrated manufacturer prioritization of direct pharmaceutical relationships.
- Hospitals:Direct procurement of ready-to-use sterile formats for compounding pharmacies.
- Laboratories:Research-grade demand with lower regulatory documentation burdens.
Pharmaceutical Companies command supply priority. Contract Manufacturing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German glassmaking clusters while consumption spreads across biologics manufacturing hubs in the United States, Switzerland, and the Netherlands. This geographic split shapes supply chain risk profiles and procurement strategies for mRNA and cell therapy sponsors.
United States
FDA container closure integrity guidance drives extractables testing documentation for biologics fill-finish operations. The agency's emphasis on leachable profiles for novel therapeutic formats extends supplier qualification timelines. Massachusetts and North Carolina biomanufacturing corridors anchor pandemic preparedness networks specifying ready-to-use sterile vial formats.
Germany
EU MDR device regulations mandate material traceability across tubing-to-vial conversion chains for drug-device combination products. The Rhine-Main region hosts captive borosilicate furnace operations supplying FIOLAX-grade capacity to top-ten pharmaceutical sponsors. Gerresheimer and Schott AG have secured decade-long direct supply agreements from these integrated facilities.
Switzerland
Swissmedic oversight of large-molecule biologics accelerates supplier audit cycles for extractables documentation compliance. Basel and Zurich pharmaceutical clusters prioritize integrated tubing-to-vial capabilities under tightened procurement consolidation. Sponsors here disqualify merchant converters lacking captive furnace access from long-term agreements.
India
Point-of-care diagnostics expansion in decentralized testing networks pulls plastic vial demand where breakage resistance outweighs oxygen barrier requirements. CDSCO oversight of pharmaceutical packaging maintains USP alignment for export-oriented manufacturers. Mumbai and Hyderabad clusters specialize in high-throughput diagnostic vial conversion for price-sensitive volume pools.
Netherlands
EMA-coordinated regulatory frameworks privilege suppliers with sterilization infrastructure alongside converted vial capacity. Leiden and Rotterdam biologics manufacturing investments specify isolator-based fill-finish lines converging with ready-to-use platforms. Dutch procurement teams compress validation timelines by pre-qualifying integrated German suppliers.
Speciality Vials Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across furnace ownership versus merchant conversion capabilities. The market structure tiers around captive borosilicate supply chains, integrated sterilization infrastructure, and modular plastic sourcing. Three archetypes dominate: integrated glass manufacturers with in-house tubing production, specialized converters dependent on merchant supply, and polymer-focused diagnostic specialists. Capacity expansion and backward integration into furnace operations constitute the primary competitive vectors as biologics procurement consolidates around supply continuity guarantees.
Among German-integrated manufacturers, Gerresheimer AG and Schott AG exemplify the captive-furnace archetype that secures priority access to FIOLAX-grade borosilicate. Stevanato Group occupies a position spanning glass tubing, converted vials, and ready-to-use sterile packaging within the integrated solutions tier. These three anchors represent divergent strategic postures: furnace-captive supply security, premium formulation material traceability, and end-to-end containment system integration.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| West Pharmaceutical Services |
| Stevanato Group |
| Corning Incorporated |
| Nipro Corporation |
| Bormioli Pharma |
| SGD Pharma |
| Piramal Glass |
| Others |
Value Network & Pricing Analysis
Captive furnace ownership by German integrated manufacturers anchors both supply security and pricing power across the speciality vials market. This backward integration into borosilicate glass melting insulates Gerresheimer AG and Schott AG from merchant tubing volatility while enabling long-term contract premiums under EU MDR documentation requirements.
Pricing Analysis
Margin tightening in standard-grade vials traces to energy input volatility and merchant converter competition, while premium FIOLAX-grade formats command stability through supply continuity guarantees. Three-tier pricing structure across captive-furnace premium, qualified-converter standard, and merchant-economy levels separates biologics sponsors from diagnostic volume buyers. Cost-down pressure on plastic vials accelerates because Indian and Brazilian point-of-care networks prioritize shipping weight reduction over barrier performance. Pharmaceutical companies show lowest price sensitivity due to validation burden lock-in, whereas diagnostic distributors negotiate aggressively on per-thousand-unit metrics.
Supply Chain Analysis
Return flows of rejected vials for furnace reprocessing remain minimal given the irreversibility of glass conversion, though polymer recycling channels are emerging for cyclic olefin diagnostic formats. Geographic supply concentrates in Germany, the United States, and China, with FIOLAX-grade borosilicate drawing from Rhine-Main furnace clusters. Raw material dependencies rest on high-purity sand, boron compounds, and natural gas feedstock. Single-source vulnerability around German captive furnace access creates procurement bottlenecks for mid-scale biologics sponsors. Distribution runs through direct pharmaceutical supply agreements rather than merchant distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR extractables documentation requirements erect regulatory moats that privilege integrated manufacturers with tubing-to-vial traceability capabilities.
For Market Incumbents: Cement supply continuity guarantees through captive furnace capacity expansion in the Rhine-Main region, insulating against merchant converter price erosion. Fortify position by pre-emptively qualifying next-generation polymer platforms under evolving USP standards before regulatory deadlines tighten supplier pools.
For New Entrants and Emerging Players: Direct-to-diagnostic procurement platforms offer lower barrier entry points than pharmaceutical qualification pathways. Target Indian and Brazilian point-of-care networks where plastic vial breakage resistance outweighs oxygen barrier requirements and regulatory documentation burdens remain lighter. Pursue modular polymer sourcing partnerships rather than capital-intensive furnace investments.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated tubing-to-vial manufacturers with sterilization infrastructure and decade-long pharmaceutical contracts. Long-term viability hinges on regulatory compliance depth rather than volume scale alone. Monitor USP polymer qualification timelines as inflection signals for resin platform winners in cell and gene therapy containment.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Furnace Capacity Expansion | Secures FIOLAX-grade borosilicate supply continuity for mRNA and cell therapy sponsors under EU MDR. |
| USP Polymer Qualification Investment | Positions resin platforms for next-generation gene therapy containment before regulatory deadlines. |
| Ready-to-Use Sterile Packaging Integration | Compresses fill-finish validation timelines by converging with isolator-based aseptic processing lines. |
| Preventive Maintenance Service Contracts | Transforms automated visual inspection vendors from unit sellers to uptime guarantee providers. |
| Point-of-Care Diagnostics Distribution Partnership | Captures volume pools in India and Brazil where plastic vial shipping weight advantages dominate. |
Research Methodology
Multi-period observation of fill-finish automation investments, regulatory submission timelines, and furnace capacity utilization anchored the trend analysis, supplemented by interviews with biologics manufacturing executives, regulatory affairs specialists, pharmaceutical procurement directors, and glass converter operations managers. Secondary validation drew from FDA container closure guidance documents, EMA MDR implementation records, ISO 15378 certification databases, and pharmaceutical supply agreement filings. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Segment-weighting across material type, application, capacity, and end-user categories informed the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical capacity expansion patterns and sponsor procurement cycle data. Forecast inputs incorporated biologics pipeline advancement rates and pandemic preparedness manufacturing network investments.
The model holds under stable regulatory enforcement timelines and continuous German furnace operations; deviation in USP polymer standard finalization or Rhine-Main energy supply disruptions would shift competitive positioning. Practitioners should monitor CDSCO and ANVISA diagnostics procurement tenders for early signals of plastic vial share acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Custom Packaging Boxes Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Gift Boxes Market