
 Pillow Boxes Market | 2026-2036
Pillow Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Pillow Boxes Market Analytics
Custom design subscription services is pivoting how packaging vendors monetize pillow box relationships beyond one-time orders. Paper Mart leverages its broad inventory depth to sustain rapid turnaround on custom dimensions. Blue Box Packaging anchors North American e-commerce demand through specialized digital printing workflows. Packlane competes on browser-based design tools that reduce proofing cycles for small-batch buyers.
Pillow boxes are foldable paperboard or cardboard containers with curved top flaps that interlock to form a cushioned profile, typically produced through die-cutting and creasing before flat-pack shipping to minimize logistics cost. Their primary commercial purpose centers on gift, retail, and cosmetic presentation where structural elegance must balance protection with shelf appeal. Kraft pillow boxes lead volume in sustainable retail channels where unbleached fiber signals environmental commitment, while luxury pillow boxes command margin pools in premium cosmetic and jewelry segments where foil stamping and soft-touch laminations justify price premiums. Recycled material grades are gaining fastest in European and North American markets where post-consumer content thresholds shape supplier qualification.
FDA food-contact material standards and EU REACH chemical restrictions govern substrate and ink selections for pillow boxes entering regulated supply chains, with California's Proposition 65 adding state-level disclosure burdens for products sold into the United States. China's GB standards for packaging and printing establish mandatory testing for heavy metal migration in exported paperboard containers. Stakeholders must monitor evolving extended producer responsibility frameworks that shift recycling accountability upstream to brand owners and converters.
Market Dynamics
E-commerce unboxing experiences are restructuring demand toward digitally-printed, short-run pillow box formats that compress traditional proof-to-delivery cycles from weeks to days.
Growth Catalysts
- EU REACH chemical restrictions:Material compliance mandates in Europe are accelerating substrate innovation toward water-based inks and bio-adhesives that qualify for premium retail placement.
- Shenzhen-Dongguan packaging clusters:Concentrated die-cutting and creasing capacity in China's Pearl River Delta enables rapid scaling of custom dimensions for cross-border e-commerce fulfillment.
- Digital inkjet workflows:Browser-based design-to-print pipelines are collapsing minimum order quantities, unlocking small-batch access for independent cosmetic and jewelry brands previously excluded from custom packaging.
Market Restraints
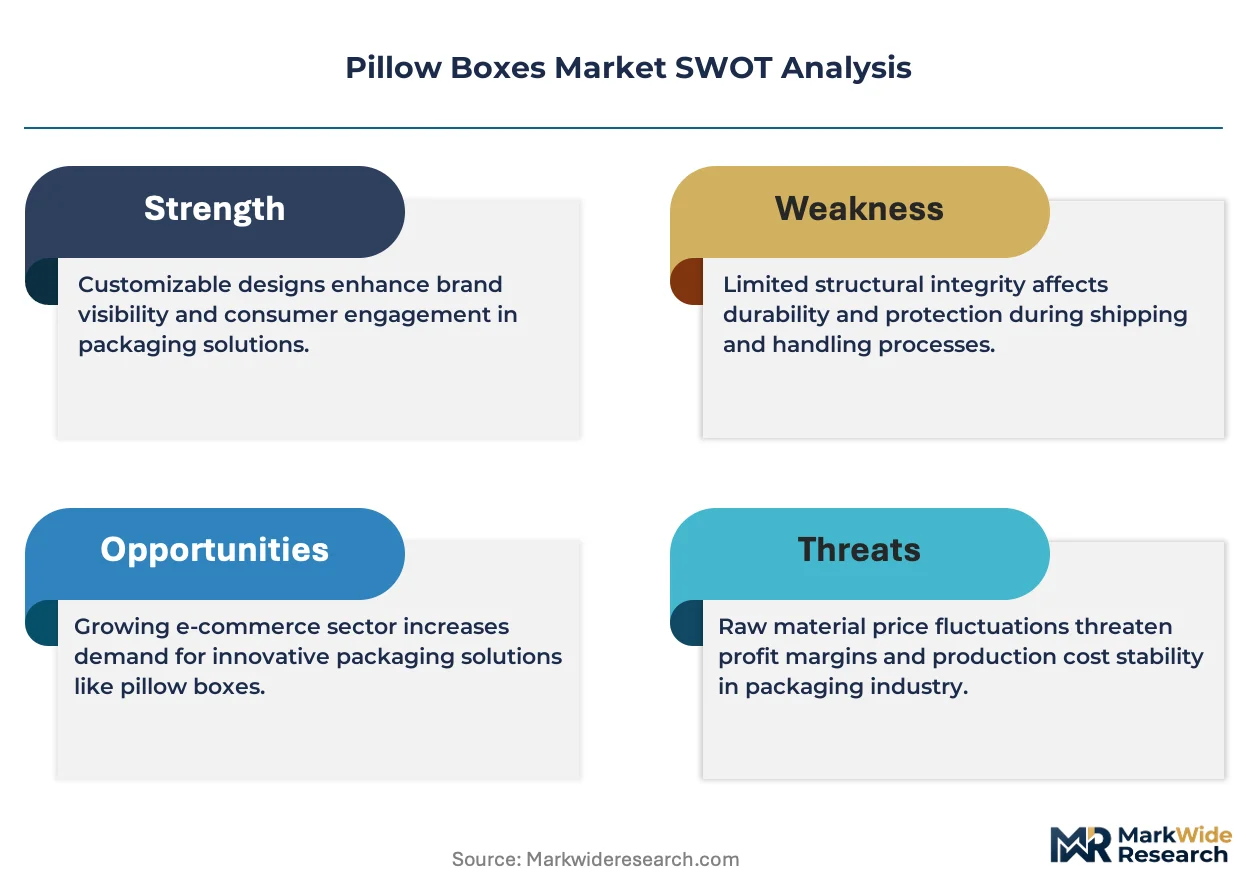
- Kraft pulp price volatility:Unbleached fiber feedstock costs swing with Nordic pulp mill capacity, squeezing margin on sustainable-grade pillow boxes positioned at price-sensitive retail tiers.
- Single-source hot foil stamping equipment:German and Japanese manufacturers control precision die production, creating supply bottlenecks for luxury cosmetic packaging requiring metallic embellishment.
- California Proposition 65 disclosure burdens:State-level chemical labeling requirements add compliance overhead for pillow boxes entering US West Coast distribution, deterring smaller exporters.
Strategic Opportunities
- India's PLI scheme for packaging machinery:Domestic production incentives are drawing die-cutting equipment investment, creating localized supply alternatives to Chinese import dependence for South Asian e-commerce platforms.
- Soft-touch lamination + QR code integration:Converging tactile finishing and connected packaging technologies opens premium tier repositioning for cosmetic brands seeking post-purchase engagement.
- Extended producer responsibility frameworks:EU packaging waste directives shifting recycling accountability upstream create service-revenue potential for converters offering closed-loop collection programs.
Industry Challenges
- Short-run digital color management:Consistent Pantone matching across scattered print locations demands specialized pre-press talent scarce outside major packaging hubs.
- Flat-pack logistics optimization:Balancing crease depth for automated assembly against stacking density for ocean freight requires iterative tooling investment that strains mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pillow Boxes Market |
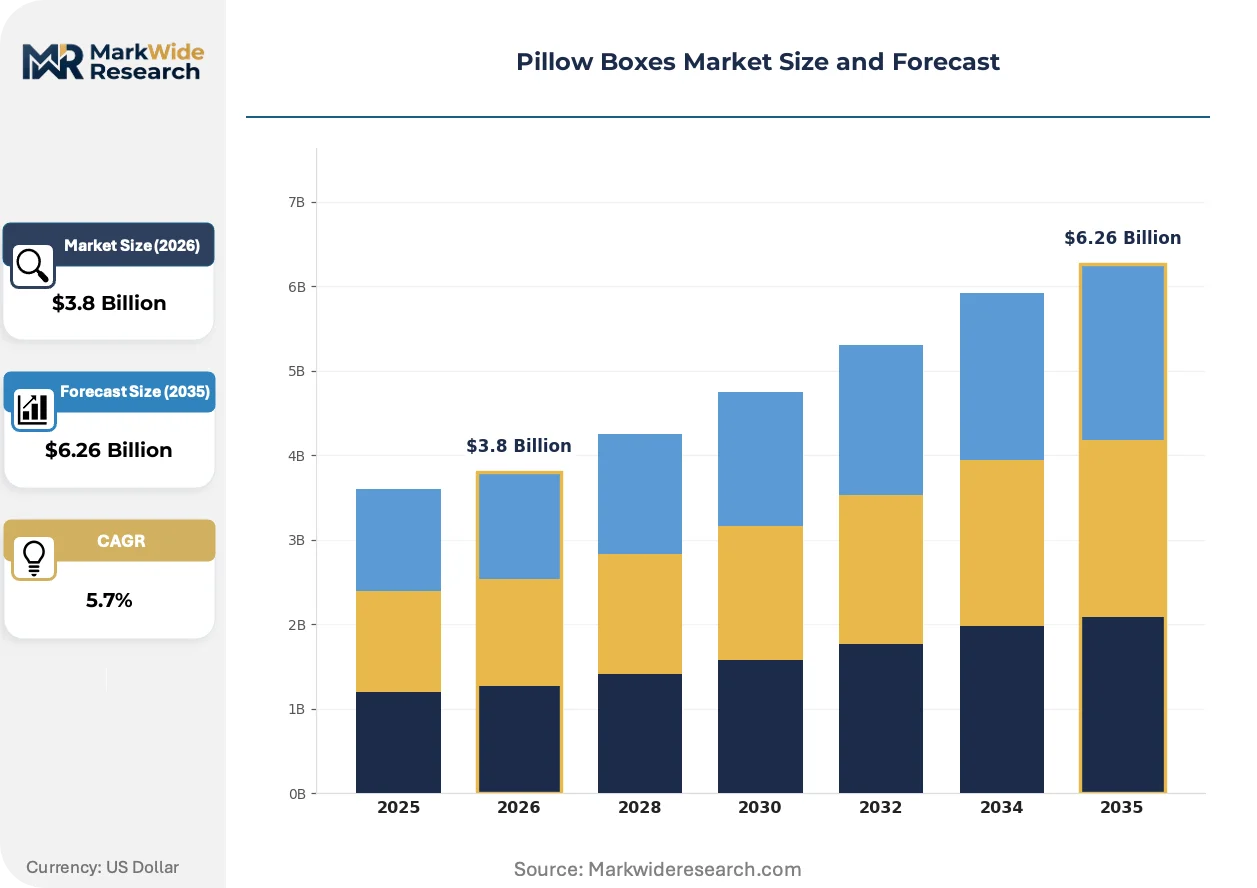
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom Pillow Boxes, Corrugated Pillow Boxes, Kraft Pillow Boxes, Luxury Pillow Boxes Material: Plastic, Paperboard, Cardboard, Recycled Material Application: Gift Packaging, Retail Packaging, Food Packaging, Cosmetic Packaging End User: Retailers, E-commerce, Manufacturers, Event Planners |
| Companies Covered | Paper Mart, Blue Box Packaging, Packlane, PakFactory, Boxes.com, The Custom Boxes, Best4U, Custom Packaging Solutions, IMH Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pillow Boxes Market Evolving Landscape
Automation in pre-press and finishing is compressing the economics of mass customization, eroding the volume advantage that once protected long-run offset specialists.
AI-driven nesting algorithms are rewriting die-layout efficiency for irregular pillow box dimensions. Specialty cosmetic brands in France and South Korea are adopting these tools for seasonal limited editions with sub-500-unit runs. The technology is compressing pre-press labor content and enabling geographic dispersal of production without yield penalties.
China's GB standards for heavy metal migration in paperboard containers are tightening testing protocols for exported packaging. Shenzhen testing laboratories report extended certification timelines for new substrate formulations. European jewelry and cosmetic importers are responding by pre-qualifying regional converters with in-house GB compliance documentation.
Subscription-box procurement models are displacing spot-market purchasing for recurring cosmetic and wellness shipments. Direct-to-consumer brands in California and New York are locking annual pillow box contracts with indexed volume flexibility. This shift is most visible among Series B-funded e-commerce operators seeking to stabilize unit economics against input cost swings.
Pillow Boxes Market Segmentation
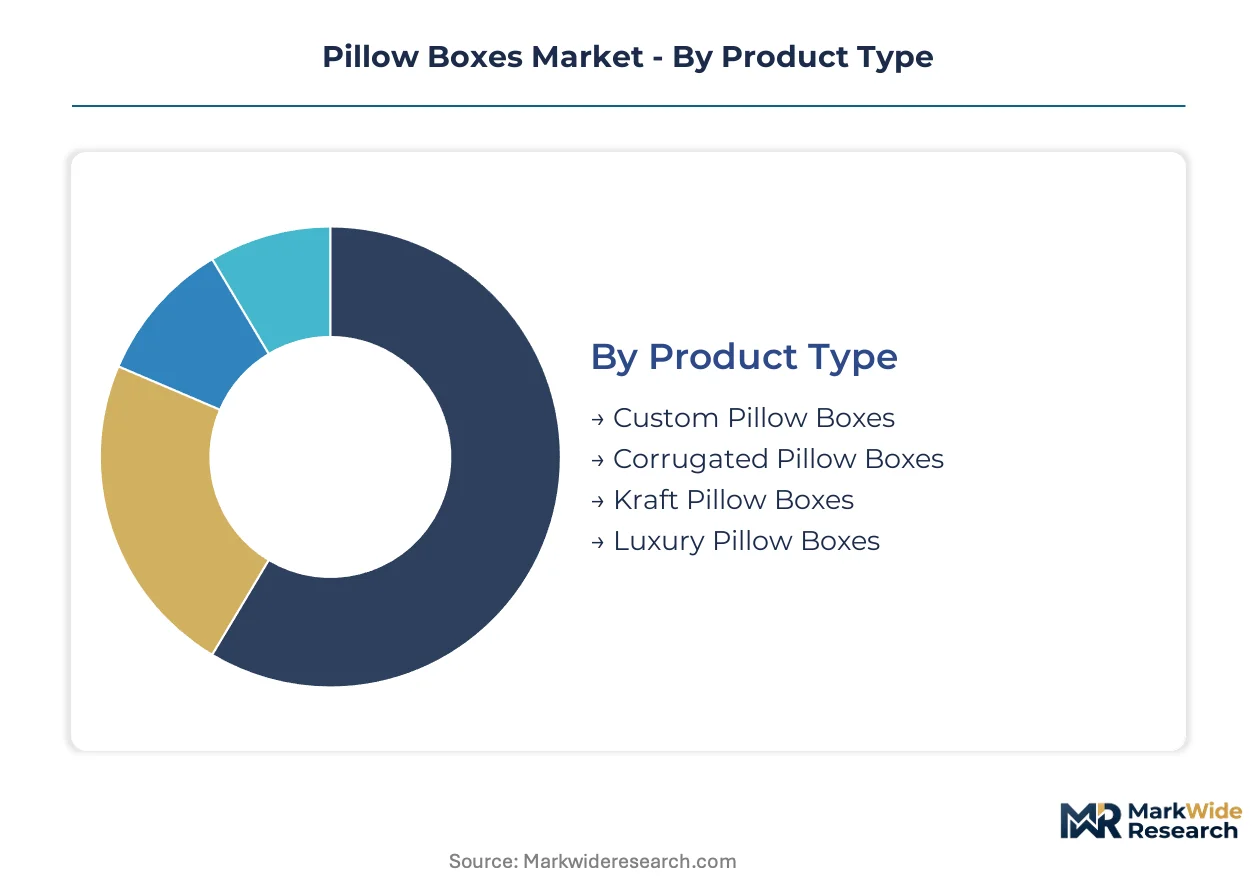
Pillow box segmentation reveals divergent margin structures across material grades and fulfillment channels. Volume concentration in standardized formats contrasts with premium capture in customized, short-run production.
Product Type:
Volume leadership sits with utilitarian formats, while premium positioning concentrates in embellished, short-run variants.
- Custom Pillow Boxes:Die-cut to client specifications with variable dimensions and print finishes. Demand concentrates among California and New York direct-to-consumer cosmetic brands seeking unboxing differentiation through browser-based design-to-print pipelines.
- Luxury Pillow Boxes:Feature foil stamping, soft-touch laminations, and rigid board construction for jewelry and premium cosmetic presentation. European importers pre-qualify Shenzhen converters with in-house GB compliance documentation to bypass extended certification timelines for metallic embellishment.
- Kraft Pillow Boxes:Unbleached fiber construction signals environmental commitment in sustainable retail channels.
- Corrugated Pillow Boxes:Fluted board provides structural protection for e-commerce fulfillment of fragile goods.
Mature deployment sits with Kraft and Corrugated formats. Newer deployment is concentrated in Custom and Luxury segments.
Material:
Substrate selection governs regulatory pathway and end-market access across FDA, REACH, and GB compliance frameworks.
- Paperboard:Bleached virgin fiber delivers consistent print surface for high-resolution cosmetic graphics. French and South Korean specialty brands drive specification toward lightweight calipers compatible with AI-driven nesting algorithms for sub-500-unit seasonal editions.
- Recycled Material:Post-consumer content grades are gaining share fastest in European and North American markets where content thresholds shape supplier qualification. California Proposition 65 disclosure burdens deter smaller exporters from mixed-fiber formulations.
- Cardboard:Heavier basis weight provides rigidity for gift and retail presentation without laminates.
- Plastic:Clear PET and PP variants serve food-contact applications requiring visibility and moisture barrier.
Steepest expansion trajectory belongs to Recycled Material specifications. Baseline volume remains with Paperboard grades.
Application:
End-use differentiation drives finishing requirements and order cadence, from annual contracts to spot-market procurement.
- Cosmetic Packaging:Requires Pantone-matched color consistency and tactile finishing for shelf differentiation. Short-run digital workflows from Packlane and Blue Box Packaging collapse proof-to-delivery cycles for independent brands excluded from offset minimums.
- E-commerce Gift Packaging:Subscription-box procurement models displace spot purchasing for recurring wellness shipments. Series B-funded operators index annual contracts with volume flexibility to stabilize unit economics.
- Retail Packaging:Mass merchant programs demand flat-pack logistics optimization for automated assembly at distribution centers.
- Food Packaging:FDA food-contact standards and EU REACH chemical restrictions govern ink and adhesive selections for regulated supply chains.
Contractual maturity sits with Retail Packaging. Platform-driven disruption is concentrated in Cosmetic and E-commerce Gift segments.
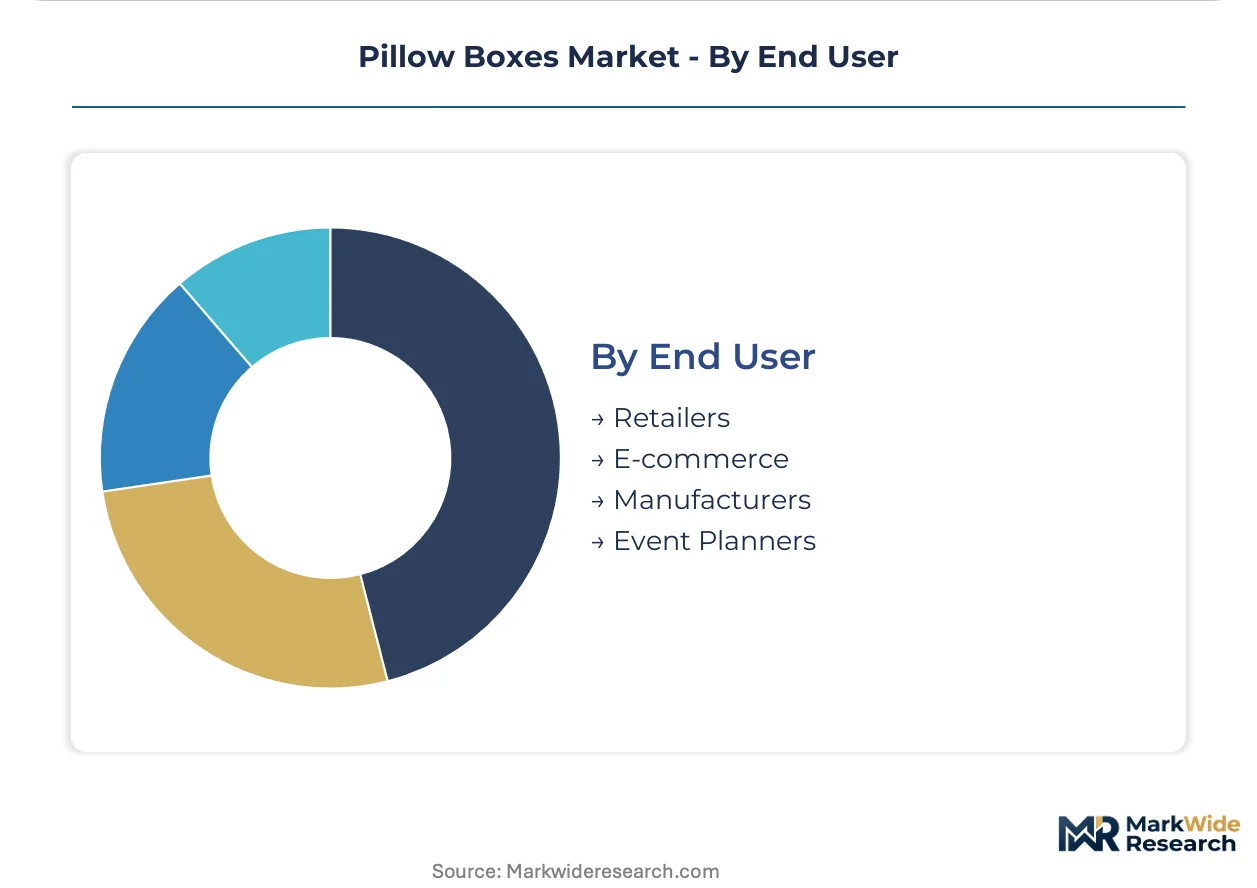
End User:
Procurement sophistication varies from automated vendor-managed inventory to design-naive spot buyers.
- E-commerce:Browser-based design tools and indexed annual contracts dominate fulfillment strategy. Shenzhen-Dongguan clusters supply both domestic Chinese platforms and cross-border export orders with rapid custom dimension scaling.
- Retailers:National chains leverage inventory depth for rapid turnaround on seasonal programs, with Paper Mart sustaining broad SKU availability.
- Manufacturers:OEM pillow box integration into product kits requires GB standard compliance for heavy metal migration in exported paperboard.
- Event Planners:Fragmented, time-sensitive demand for wedding and corporate gifting favors digital short-run accessibility.
Scale concentration sits with Retailers. Fastest capability upgrading is concentrated in E-commerce procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pillow box production concentrates in China's Pearl River Delta, while consumption spreads across North American and European e-commerce corridors. This geographic split shapes trade flows and regulatory compliance requirements.
China
Shenzhen and Dongguan packaging clusters supply die-cutting capacity for cross-border e-commerce fulfillment. GB standards for heavy metal migration in paperboard containers mandate extended testing protocols at Shenzhen laboratories. Dongguan converters pre-qualify substrate formulations to bypass certification delays for European jewelry and cosmetic exporters.
United States
California and New York direct-to-consumer brands drive demand for browser-based design-to-print pipelines. FDA food-contact material standards govern substrate selections for wellness and cosmetic packaging entering regulated supply chains. West Coast fulfillment centers optimize flat-pack logistics for automated assembly at distribution hubs.
Germany
EU REACH chemical restrictions accelerate substrate innovation toward water-based inks and bio-adhesives. ECHA compliance documentation shapes supplier qualification for premium retail placement. Bavarian and North Rhine-Westphalia converters specialize in foil stamping equipment for luxury cosmetic packaging.
India
Domestic e-commerce platforms seek localized supply alternatives to Chinese import dependence. PLI scheme incentives for packaging machinery draw die-cutting equipment investment toward Maharashtra and Gujarat. Mumbai and Ahmedabad clusters develop capacity for South Asian subscription-box fulfillment.
France
Specialty cosmetic brands in Paris and Lyon adopt AI-driven nesting algorithms for sub-500-unit seasonal editions. ANSM and CNIL frameworks intersect where connected packaging integrates QR codes with personal data collection. Provence-Alpes-Côte d'Azur converters serve Mediterranean luxury jewelry exporters.
Pillow Boxes Market Competitive Landscape
Top-tier vendors anchor premium customization services, while mid-cap specialists compete on rapid turnaround and inventory depth. The vendor base stratifies across three functional tiers: browser-based design platforms, broad-line distributors with custom capabilities, and precision converters for metallic embellishment. Two dominant competitive moves are emerging: geographic diversification to bypass tariff exposure, and vertical integration into pre-press automation to compress proofing cycles.
Within the broad-line distribution tier, Paper Mart exemplifies inventory-heavy positioning that sustains rapid turnaround on custom dimensions. Packlane and Blue Box Packaging occupy the digital-native vector, with Packlane representing browser-based design tool specialization and Blue Box Packaging anchoring North American e-commerce demand through digital printing workflows. These three companies collectively illustrate how procurement sophistication is splitting between design-naive spot buyers and automated vendor-managed inventory systems.
| Leading Market Players |
|---|
| Paper Mart |
| Blue Box Packaging |
| Packlane |
| PakFactory |
| Boxes.com |
| The Custom Boxes |
| Best4U |
| Custom Packaging Solutions |
| IMH Packaging |
| Others |
Value Network & Pricing Analysis
Digital inkjet workflows collapsing minimum order quantities are simultaneously compressing per-unit economics and dispersing production geography, fragmenting pricing power from Shenzhen-Dongguan clusters toward browser-based design platforms serving California and New York direct-to-consumer brands.
Pricing Analysis
Cost-down pressure on sustainable-grade kraft pillow boxes accelerates because Nordic pulp mill capacity swings squeeze converters at price-sensitive retail tiers. Three-tier pricing structure across premium, standard, and economy levels separates luxury foil-stamped cosmetic packaging from unbleached fiber retail formats from corrugated e-commerce fulfillment grades. Certification investment for EU REACH and FDA food-contact compliance commands 15-25% premia over non-qualified substrates. Independent cosmetic brands exhibit highest price sensitivity, while European jewelry importers pre-qualifying Shenzhen converters with GB documentation show lowest.
Supply Chain Analysis
Flat-pack ocean freight economics from Shenzhen and Dongguan to California distribution centers hinge on crease-depth optimization balancing automated assembly speed against container stacking density. Raw material draws from Nordic unbleached pulp mills, German and Japanese hot foil stamping equipment, and South Asian recycled fiber grades. Single-source dependency on precision die manufacturers in Bavaria and North Rhine-Westphalia creates embellishment bottlenecks for luxury cosmetic packaging. Distribution runs through cross-border e-commerce fulfillment platforms and vendor-managed inventory systems at national retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pillow box vendors are racing to capture upstream pre-press automation and downstream closed-loop collection services, with backward integration into die-cutting equipment and AI-driven nesting algorithms emerging as the decisive capability differentiator.
For Market Incumbents: Cement category ownership in browser-based design-to-print pipelines by acquiring Packlane-caliber interface capabilities and indexing annual contracts with volume flexibility for Series B-funded e-commerce operators. Defend against Shenzhen-Dongguan cluster encroachment through California Proposition 65 compliance documentation and rapid-turn inventory depth. Prioritize in-house GB standard testing to bypass extended certification timelines for European jewelry exporters. For New Entrants and Emerging Players: Launch via subscription-box procurement models targeting South Asian e-commerce platforms seeking alternatives to Chinese import dependence, leveraging India's PLI scheme for packaging machinery investment in Maharashtra and Gujarat clusters. White-space concentration sits with sub-500-unit seasonal editions for French and South Korean specialty cosmetic brands adopting AI-driven nesting algorithms. Go-to-market angle: browser-based Pantone-matched proofing with sub-72-hour delivery commitments. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by broad-line distributors seeking digital-native design capabilities, with financial sponsor interest in pre-press automation specialists. Long-term viability favors converters with captive GB compliance documentation and indexed annual contract portfolios. Watch India's PLI scheme draw rates as the inflection signal for South Asian supply reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pre-Press Automation | AI-driven nesting algorithms compress labor content and enable geographic production dispersal without yield penalties for sub-500-unit runs. |
| Closed-Loop Collection Program Launch | EU packaging waste directives shifting recycling accountability upstream create service-revenue potential beyond unit sales for compliant converters. |
| GB Compliance Documentation Pre-Qualification | Shenzhen laboratories report extended certification timelines, creating first-mover advantage for converters with in-house heavy metal migration testing. |
| Browser-Based Design Platform Acquisition | Packlane and Blue Box Packaging demonstrate how interface capabilities collapse proof-to-delivery cycles and lock in recurring cosmetic brand relationships. |
| Indexed Annual Contract Structuring | Series B-funded e-commerce operators in California and New York seek volume flexibility to stabilize unit economics against kraft pulp price volatility. |
Research Methodology
Trade association filings, customs and logistics databases, and regulatory submission records formed the secondary backbone, cross-referenced against primary interviews with packaging machinery procurement leads, e-commerce supply chain directors, Shenzhen-Dongguan converter operations managers, European cosmetic brand packaging specifiers, and North American retail category buyers. Bottom-up and top-down triangulation validated volume estimates across material grades and fulfillment channels.
Bottom-up modeling built from substrate cost curves, die-cutting capacity utilization, and digital print run economics, while top-down analysis anchored in e-commerce fulfillment growth trajectories and subscription-box penetration rates across the projection horizon. Segmentation dimensions included product type, material grade, application, and end-user procurement sophistication. CAGRs derived from iterative reconciliation of supply-side capacity expansion and demand-side unboxing experience investment, with explicit modeling of EU REACH compliance cost pass-through and California Proposition 65 disclosure overhead.
Kraft pulp price volatility, GB standard certification timeline extensions, and PLI scheme implementation delays in India are the dominant revision risks to baseline assumptions. Stakeholders should weight assumptions against their own operating context and contract portfolio exposure to indexed versus fixed pricing structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Child Resistant Packaging Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Specialty Lidding Films Market