
 Fashion Accessories Packaging Market | 2026-2036
Fashion Accessories Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fashion Accessories Packaging Market Foresight
Capital-intensity divergence between automated rigid-box manufacturers and hand-finish specialists is redrawing competitive boundaries in fashion accessories packaging. Brimar Packaging leverages high-volume lithographic lines to dominate North American jewelry box contracts. Novel Box Company sustains artisanal finishing capacity that anchors its position in European luxury watch cases.
Fashion accessories packaging encompasses protective and presentational enclosures for jewelry, handbags, watches, and leather goods, typically constructed from rigid paperboard, molded pulp, or formed plastics with velvet or foam inserts to prevent abrasion. Paper-based materials lead volume owing to recyclability alignment with brand sustainability pledges, while magnetic closure mechanisms command premium positioning in luxury channels due to their tactile permanence and reuse value. Fabric-wrapped rigid boxes concentrate margin pools in the jewelry segment where unboxing rituals drive consumer lifetime value.
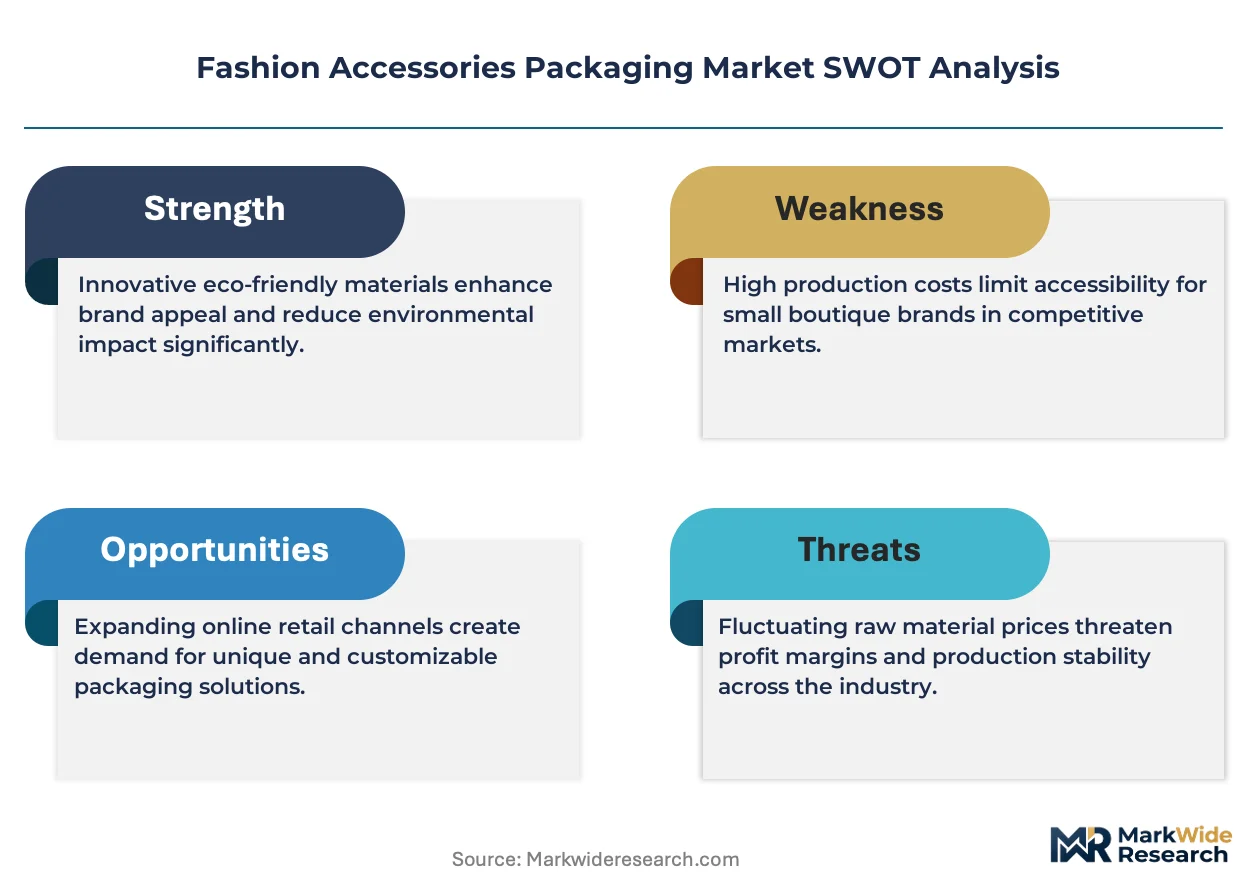
REACH restrictions on heavy metals in packaging substrates and the EU Green Deal's packaging waste reduction targets are forcing material substitutions across European supply chains. The US EPA and state-level extended producer responsibility frameworks are reshaping domestic sourcing requirements for plastic-intensive handbag packaging. Stakeholders must monitor regulatory divergence between California's SB 54 implementation and EU CSRD disclosure mandates to avoid compliance fragmentation.
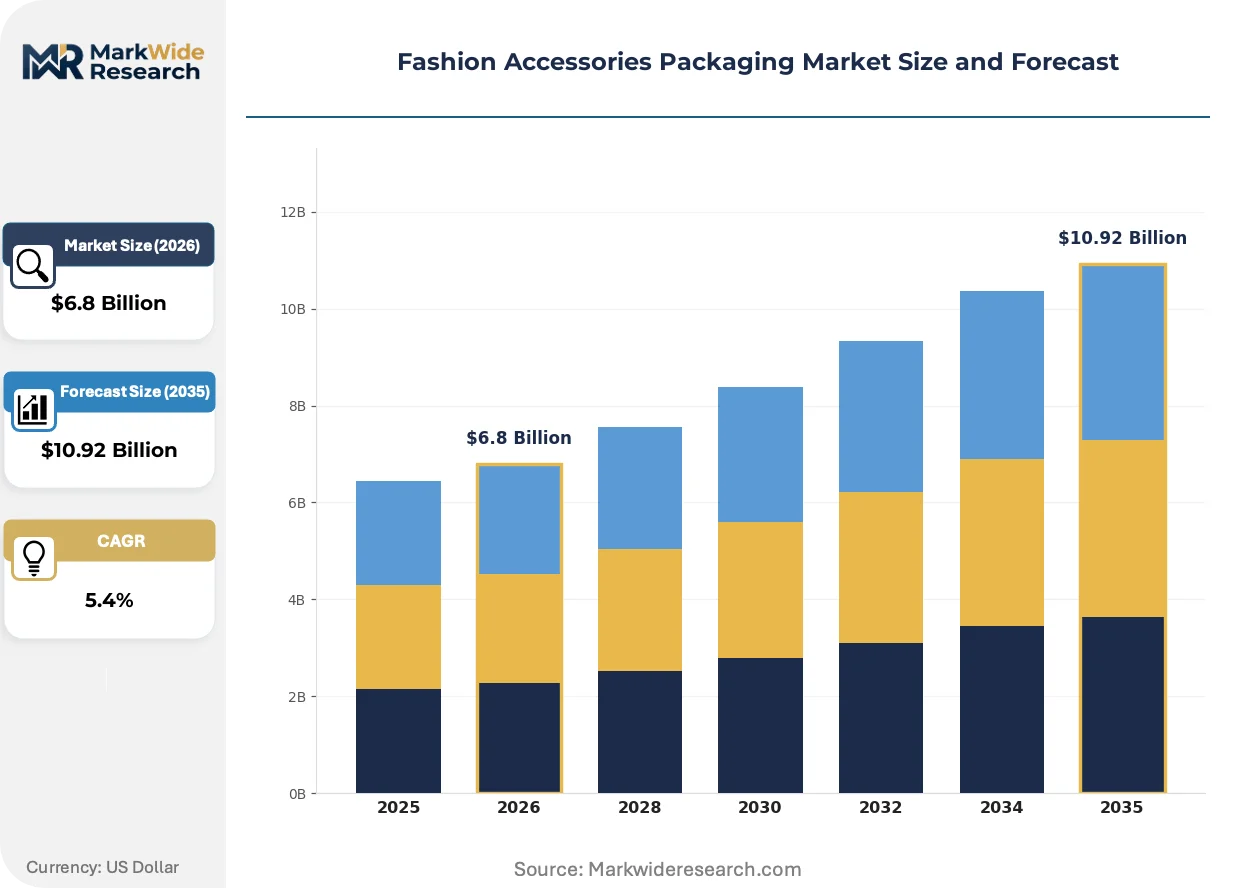
Market Dynamics
REACH restrictions on heavy metals and the EU Green Deal's packaging waste targets are forcing material substitutions across European supply chains, while luxury jewelry houses expand unboxing investments that reshape margin structures.
Growth Catalysts
- Milan-Tuscany packaging corridor:Concentrated artisanal capacity in northern Italy draws luxury watch and jewelry brands seeking hand-finished rigid boxes with magnetic closures.
- EU Green Deal packaging mandates:Binding waste reduction targets accelerate demand for recyclable paperboard substrates and velvet alternatives in handbag enclosures.
- Unboxing ritual investments:Luxury houses allocate capital to tactile presentation layers that extend consumer lifetime value through reuse and social sharing.
Market Restraints
- Cellulose pulp price volatility:Rigid paperboard producers face margin compression when wood fiber input costs spike, squeezing mid-tier jewelry box manufacturers.
- Italian artisan concentration:Hand-finish specialist capacity clusters in Tuscany, creating bottleneck risk for European luxury watch case orders.
- Magnetic closure technical limits:Ferrite magnet supply constraints restrict scaling of premium closure mechanisms in high-volume handbag packaging.
Strategic Opportunities
- India leather goods export packaging:Underpenetrated demand for protective molded pulp enclosures serves outbound handbag shipments from Chennai and Kolkata manufacturing zones.
- Digital printing-textile wrapping convergence:Combining variable-data lithography with fabric lamination enables mass-customized jewelry boxes for direct-to-consumer brands.
- California SB 54 extended producer responsibility:State-level plastic waste frameworks create first-mover advantage for paper-intensive packaging suppliers serving US handbag brands.
Industry Challenges
- Artisan skill attrition:Hand-finishing techniques for velvet-lined watch cases face generational transfer gaps in European manufacturing clusters.
- Multi-material certification timelines:Composite rigid boxes combining paperboard, magnetics, and fabric layers require sequential REACH and FDA food-contact approvals that extend launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fashion Accessories Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Metal, Fabric Product Type: Jewelry Boxes, Handbag Packaging, Watch Cases, Belt Holders Design Style: Luxury, Minimalistic, Vintage, Eco-Friendly Closing Mechanism: Magnetic Closure, Zipper, Snap Button, Latch |
| Companies Covered | Brimar Packaging, Novel Box Company, PakFactory, Prime Line Packaging, Allure Box & Display, Richpack, Cedar Box Company, Deluxe Packaging, Taylor Box Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fashion Accessories Packaging Market Shifts & Advancements
Material science advances and regulatory compression are reconfiguring how fashion accessories packaging delivers both protection and brand narrative, with three distinct vectors now dominating supplier R&D priorities.
Molded pulp technology is decomposing traditional plastic insert dominance in handbag and jewelry protective layers. Mid-market accessories brands in Germany and France are adopting thermoformed fiber trays at accelerated pace, replacing polyurethane foam. This substitution is decomposing the historical cost advantage of petroleum-based cushioning, compressing plastic converter margins while opening capacity for agricultural fiber processors.
REACH Annex XVII heavy metal restrictions are tightening substrate compliance requirements across European jewelry packaging supply chains. ECHA enforcement actions against cadmium and lead content in printed paperboard are redirecting converter sourcing toward mineral-oil-free inks and controlled wood certifications. Italian rigid-box manufacturers serving luxury houses face the steepest reformulation timelines, with Q4 2025 deadlines accelerating supplier audits.
Direct-to-consumer brand procurement is consolidating formerly fragmented packaging specification processes. Emerging accessories labels in South Korea and the United States now contract integrated design-to-delivery vendors who control structural engineering, material selection, and fulfillment logistics. This consolidation is most visible in Los Angeles and Seoul, where venture-backed handbag brands bypass traditional broker networks to capture speed-to-market advantages.
Fashion Accessories Packaging Market Segmentation
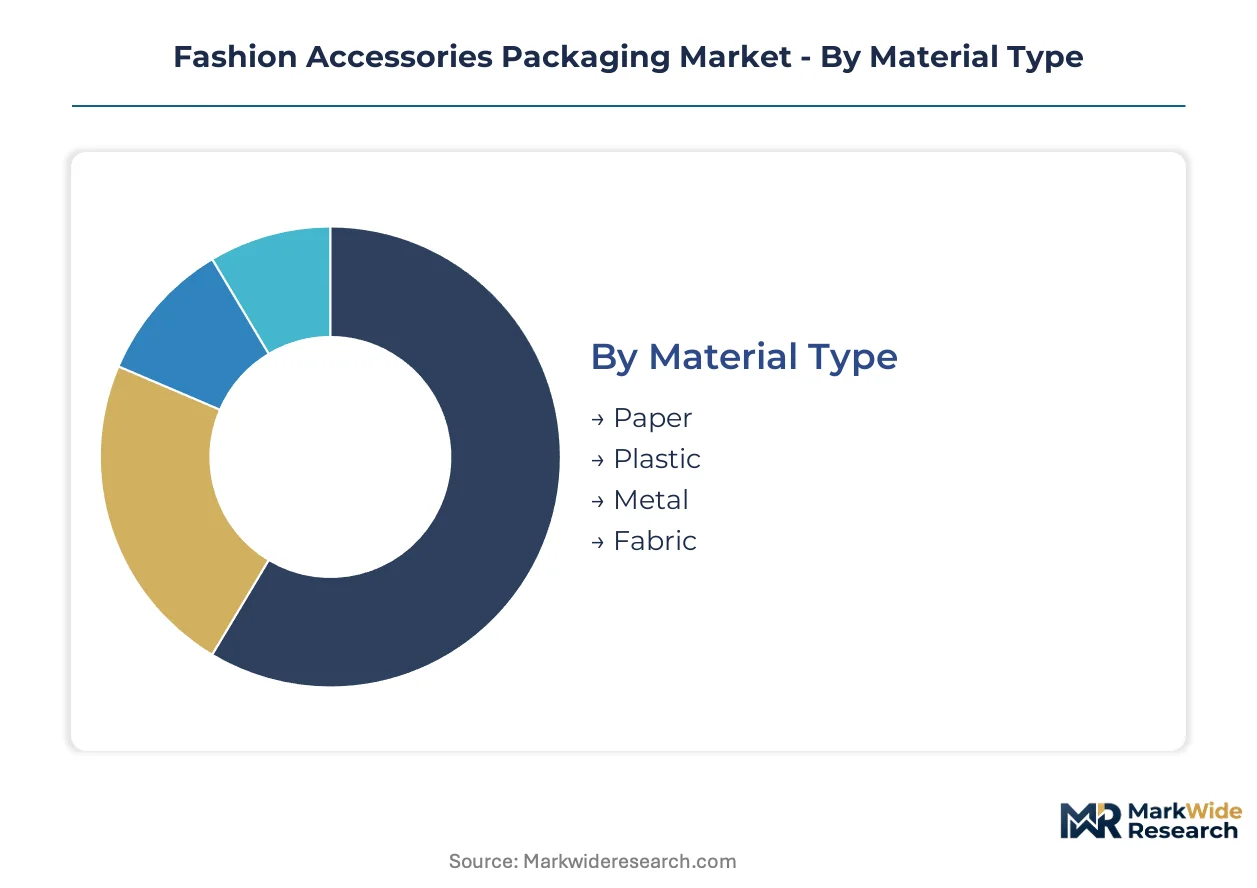
Segmentation in fashion accessories packaging reveals how material choices and closure mechanisms map to distinct supply chain configurations. Brand procurement teams use these categories to align packaging specifications with regional regulatory requirements and unboxing experience investments.
Material Type:
Paper-based substrates dominate domestic European supply chains serving Milan-Tuscany luxury houses, while plastic and metal components concentrate in export-oriented Asian manufacturing.
- Paper:Rigid paperboard with velvet or foam inserts forms the backbone of recyclable jewelry box construction. Italian converters in the Milan-Tuscany corridor command premium positioning for hand-finished rigid boxes serving European luxury watch brands under REACH compliance timelines.
- Plastic:Thermoformed PET and polyurethane foam inserts retain cost advantages in high-volume handbag protective layers. Demand concentrates in German and French mid-market accessories brands accelerating molded pulp substitution to meet EU Green Deal waste reduction targets.
- Metal:Tinplate and aluminum enclosures serve premium fragrance-adjacent jewelry presentations with magnetic closure integration. Export-led demand from Gulf luxury retail clusters drives specification complexity around ferrite magnet supply constraints.
- Fabric:Silk, linen, and synthetic textile wrapping enables tactile differentiation in direct-to-consumer unboxing rituals. South Korean and Los Angeles venture-backed handbag brands contract integrated vendors for mass-customized fabric-laminated rigid boxes.
Paper holds the largest share; momentum sits with fabric as direct-to-consumer brands prioritize tactile presentation layers.
Product Type:
Cost tier stratification separates artisanal hand-finish capacity from automated lithographic production across product categories.
- Jewelry Boxes:Fabric-wrapped rigid boxes with magnetic closures concentrate margin pools where unboxing rituals drive consumer lifetime value. European luxury houses anchor demand in the Milan-Tuscany corridor, though cellulose pulp price volatility squeezes mid-tier manufacturers.
- Handbag Packaging:Molded pulp enclosures and protective inserts serve outbound shipments from Chennai and Kolkata manufacturing zones. California SB 54 extended producer responsibility frameworks create first-mover advantage for paper-intensive suppliers serving US brands.
- Watch Cases:Velvet-lined rigid construction requires hand-finishing techniques facing generational transfer gaps in European manufacturing clusters. Artisan skill attrition threatens bottleneck risk for luxury orders.
- Belt Holders:Compact rigid or folding carton formats serve accessories retail display requirements with lower structural complexity. Volume production concentrates in automated lithographic lines serving mass-market apparel brands.
Jewelry boxes hold the largest share; handbag packaging is climbing the fastest on Indian export growth and molded pulp substitution.
Design Style:
Application context determines whether sustainability certification or heritage narrative drives specification decisions.
- Luxury:Multi-layer presentation construction with fabric wrapping and magnetic closure mechanisms commands premium positioning. REACH Annex XVII heavy metal restrictions redirect converter sourcing toward mineral-oil-free inks for Italian rigid-box manufacturers.
- Minimalistic:Reduced material count and structural simplicity align with circular economy pledges from Scandinavian and Japanese accessories brands. Digital printing integration enables variable-data production without decorative excess.
- Vintage:Distressed finishes and heritage typography serve heritage house repositioning and limited-edition collections. Specification complexity increases with multi-material certification timelines across paperboard, magnetics, and fabric layers.
- Eco-Friendly:Agricultural fiber substrates and water-based coatings respond to EU Green Deal packaging waste mandates. German and French mid-market brands adopt thermoformed fiber trays at accelerated pace.
Luxury holds the largest share; eco-friendly is gaining share fastest on regulatory compression and brand sustainability pledges.
Closing Mechanism:
Volume scale separates precision-engineered magnetic systems from commodity zipper and snap configurations.
- Magnetic Closure:Ferrite and neodymium magnet integration delivers tactile permanence and reuse value in premium jewelry and watch packaging. Supply constraints restrict scaling in high-volume handbag applications.
- Zipper:Coil and metal zipper systems serve soft-sided handbag dust bags and travel cases with functional durability requirements. Specification concentrates in Asian textile manufacturing clusters.
- Snap Button:Metal and plastic snap closures balance cost and reusability in mid-tier accessories presentations. Volume production aligns with automated assembly lines in North American contract packaging.
- Latch:Mechanical clasp mechanisms reinforce heritage positioning in luxury watch cases and jewelry armoires. Hand-assembly requirements limit capacity expansion in European artisan clusters.
Magnetic closure holds the largest share; latch mechanisms show steepest expansion trajectory on heritage house unboxing investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian and French buyers exhibit minimal price elasticity for hand-finished rigid boxes, while German mid-market brands and Indian exporters prioritize molded pulp cost efficiency. This demand-elasticity contrast shapes regional procurement patterns and supplier investment priorities.
United States
California SB 54 extended producer responsibility frameworks reshape domestic sourcing for plastic-intensive handbag packaging. The EPA coordinates with state regulators on packaging waste reduction timelines. Los Angeles venture-backed accessories brands contract integrated design-to-delivery vendors, bypassing traditional broker networks.
Italy
Luxury jewelry houses anchor demand for fabric-wrapped rigid boxes with magnetic closures in the Milan-Tuscany corridor. REACH Annex XVII heavy metal restrictions redirect converter sourcing toward mineral-oil-free inks. Tuscan artisan clusters face Q4 2025 compliance deadlines that accelerate supplier audits.
Germany
Mid-market accessories brands adopt thermoformed fiber trays at accelerated pace to meet EU Green Deal waste reduction targets. ECHA enforcement actions against cadmium content in printed paperboard tighten substrate compliance. Stuttgart and Munich manufacturing zones concentrate molded pulp capacity expansion.
India
Outbound leather goods shipments from Chennai and Kolkata manufacturing zones drive underpenetrated demand for protective molded pulp enclosures. DGFT export incentive schemes support packaging supplier localization. Maharashtra and Gujarat textile hubs supply fabric wrapping materials for domestic converter integration.
South Korea
Seoul-based direct-to-consumer accessories labels consolidate formerly fragmented packaging specification processes. The country's national environmental agency implements extended producer responsibility frameworks parallel to EU models. Gyeonggi-do province hosts integrated vendors combining digital printing with fabric lamination capabilities.
Fashion Accessories Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with automated lithographic producers competing against hand-finish artisans for luxury contracts. The structure fragments across three strategic archetypes: high-volume rigid-box manufacturers, artisanal finishing specialists, and integrated design-to-delivery platforms. Competitive moves concentrate on geographic expansion into underpenetrated export corridors and backward integration into captive substrate supply.
Within the integrated vendor tier, Brimar Packaging and Novel Box Company occupy distinct positioning vectors. Brimar represents high-volume lithographic production serving North American jewelry contracts, while Novel Box exemplifies artisanal finishing capacity anchoring European luxury watch cases. PakFactory sits within the emerging platform archetype, consolidating design, material selection, and fulfillment logistics for direct-to-consumer brands.
| Leading Market Players |
|---|
| Brimar Packaging |
| Novel Box Company |
| PakFactory |
| Prime Line Packaging |
| Allure Box & Display |
| Richpack |
| Cedar Box Company |
| Deluxe Packaging |
| Taylor Box Company |
| Others |
Supply & Pricing Matrix
REACH Annex XVII heavy metal restrictions gate supplier qualification and price differentiation simultaneously, with ECHA enforcement timelines compressing margins for non-compliant converters while mineral-oil-free ink certification opens premium positioning for Italian rigid-box manufacturers serving luxury jewelry houses.
Pricing Analysis
After-sales reuse value and social sharing potential drive lifetime value in fashion accessories packaging. Three-tier pricing structure across premium, standard, and economy levels stratifies by hand-finishing intensity and magnetic closure integration. Cost compression in mid-tier jewelry boxes is intensifying because cellulose pulp price volatility squeezes rigid paperboard producers. German and French mid-market brands exhibit highest price sensitivity; Milan-Tuscany luxury houses show minimal elasticity for artisanal capacity.
Supply Chain Analysis
Tuscan artisan cluster concentration creates bottleneck risk for European luxury watch case orders. Raw material flows draw from Italian paperboard mills, Chinese ferrite magnet processors, and Indian textile hubs. Single-source vulnerability runs through hand-finishing skill pools facing generational transfer gaps. Distribution feeds from integrated design-to-delivery platforms in Los Angeles and Seoul to direct-to-consumer brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards converters who control scarce hand-finishing capabilities and magnetic closure integration, with generational skill transfer gaps threatening supply security for European luxury houses.
For Market Incumbents: Secure captive substrate supply through backward integration into mineral-oil-free ink production and controlled wood certification chains. Defend against molded pulp substitution threats by embedding reuse value into magnetic closure mechanisms that resist disassembly. For New Entrants and Emerging Players: Lead with digital printing-textile wrapping convergence targeting South Korean and Los Angeles venture-backed handbag brands. The most penetrable white space sits in mass-customized jewelry boxes for direct-to-consumer channels, accessed through integrated vendor platforms bypassing traditional broker networks. For Investors and Strategic Acquirers: EU Green Deal packaging waste mandates reshape the acquisition landscape toward agricultural fiber processors and thermoformed fiber tray specialists. Long-term viability centers on converters with dual capability in automated lithographic lines and artisanal finishing cells. Watch ECHA enforcement action frequency as inflection indicator for compliance-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral-Oil-Free Ink Supply | REACH Annex XVII compliance secures qualification for Milan-Tuscany luxury contracts. |
| Artisan Skill Transfer Program Investment | Generational pipeline protects European watch case capacity against bottleneck risk. |
| Molded Pulp Capacity Expansion in Stuttgart Zone | EU Green Deal alignment captures German mid-market brand substitution demand. |
| Digital Printing-Textile Lamination Platform Buildout | Mass customization capability penetrates Seoul and Los Angeles direct-to-consumer channels. |
| Magnetic Closure Mechanism Patent Portfolio Development | Ferrite supply constraints favor vertically integrated reuse-value engineering. |
Research Methodology
Initial hypotheses were tested against primary input from packaging procurement managers at luxury jewelry houses, rigid-box manufacturing plant directors, textile wrapping material suppliers, and ECHA regulatory compliance officers, and refined through secondary validation against customs trade records, SEC filings of listed packaging converters, EU packaging waste directive implementation reports, and Italian industrial association production surveys. Bottom-up capacity assessments triangulated with top-down brand procurement spend estimates.
Variance decomposition across material type, product category, design style tier, and closing mechanism complexity shaped the analytical framework. CAGRs derived from segment-level volume trajectories and value-per-unit elasticity models. Industry-specific forecast inputs incorporated REACH compliance cost pass-through rates and molded pulp substitution curves in German and French mid-market segments.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement intensity and stable cellulose pulp input costs would require recalibration. Practitioners should keep alternative scenarios live as ECHA audit frequency and Indian export incentive scheme revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Cannabis Packaging Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Specialty Plastic Films Market
Specialty Packaging
Holographic Foils Market
Specialty Packaging
Specialty Lidding Films Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Mil-Spec Packaging Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Global in Store Theater Packaging Market