
 Veterinary Dietary Supplements Market | 2026-2036
Veterinary Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Dietary Supplements Market Intelligence
Companion animal owners are reorganizing their spending toward preventive wellness solutions over reactive treatments. Mars Petcare leverages its veterinary clinic partnerships to secure preferred shelf placement in professional channels. Nutramax Laboratories anchors its position through science-backed joint health formulations trusted by veterinarians. Virbac competes with a focused portfolio targeting skin and coat conditions in dogs and cats.
Veterinary dietary supplements comprise formulated nutritional additives containing vitamins, amino acids, probiotics, and fatty acids manufactured to specific purity grades for animal consumption. These products address physiological gaps in commercial pet food or support therapeutic outcomes under veterinary supervision. Probiotics and joint health applications command the deepest margin pools due to repeat purchase patterns and clinical validation requirements. The online retail channel is expanding fastest as direct-to-consumer brands bypass traditional veterinary gatekeepers with subscription models. Dogs represent the dominant animal type segment, though equine formulations sustain premium pricing through specialized distribution.
The FDA Center for Veterinary Medicine governs ingredient safety and labeling claims for animal supplements in the United States, while the EU's Feed Additives Regulation imposes strict authorization requirements for products entering European markets. The National Animal Supplement Council operates a voluntary quality seal program that shapes retailer procurement standards and consumer trust thresholds. Stakeholders must monitor evolving regulatory distinctions between feed, supplements, and unapproved drugs as enforcement priorities shift toward claims substantiation and adverse event reporting.
Market Dynamics
Veterinary dietary supplements face a structural squeeze between FDA ingredient disclosure mandates and pet owner insistence on clinical-grade validation, forcing manufacturers to rebuild supply chains around transparent sourcing while maintaining margin structures.
Growth Catalysts
- Pet Humanization Trajectory:Companion animal owners now apply human wellness standards to preventive care purchases, expanding the addressable base for premium formulations beyond traditional therapeutic applications.
- REACH Authorization Pathways:The EU's Feed Additives Regulation creates a predictable regulatory ceiling that compliant manufacturers leverage as competitive moats against unvalidated competitors.
- Veterinary Clinic Dispensing:Specialty practices are building captive pharmacy programs that lock supplement purchases into treatment protocols, securing recurring revenue streams.
Market Restraints
- Active Ingredient Concentration:Marine-derived omega-3 supply chains cluster around Peruvian and Norwegian fisheries, exposing formulators to catch-quota volatility and price spikes.
- FDA Enforcement Ambiguity:The Center for Veterinary Medicine's shifting position on structure-function claims creates compliance uncertainty, forcing conservative labeling that limits differentiation.
- Generic Probiotic Substitution:Human-grade probiotic strains from contract manufacturers undercut veterinary-specific formulations on price, eroding margin pools in the fastest-growing application segment.
Strategic Opportunities
- Equine Specialty Channel:Horse owners demonstrate price inelasticity for joint and digestive formulations, with distribution through veterinary practices and trainer networks sustaining premium positioning unavailable in companion animal mass markets.
- Subscription Direct-to-Consumer:Digital-native brands bypass veterinary gatekeepers through automated replenishment models, capturing lifetime value from millennial pet owners who research independently.
- National Animal Supplement Council Quality Seal:Voluntary certification programs are becoming de facto procurement requirements for major retailers, creating first-mover advantages for early adopters.
Industry Challenges
- Veterinary Formulation Expertise Scarcity:The intersection of animal physiology, nutraceutical science, and regulatory compliance demands specialized talent that outpaces graduate program output.
- Clinical Validation Timelines:Peer-reviewed efficacy studies require multi-year investment before claims withstand FDA scrutiny, compressing R&D ROI windows.
- Legacy ERP Integration:Batch-level traceability mandates collide with decades-old manufacturing software, forcing costly system overhauls for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Dietary Supplements Market |
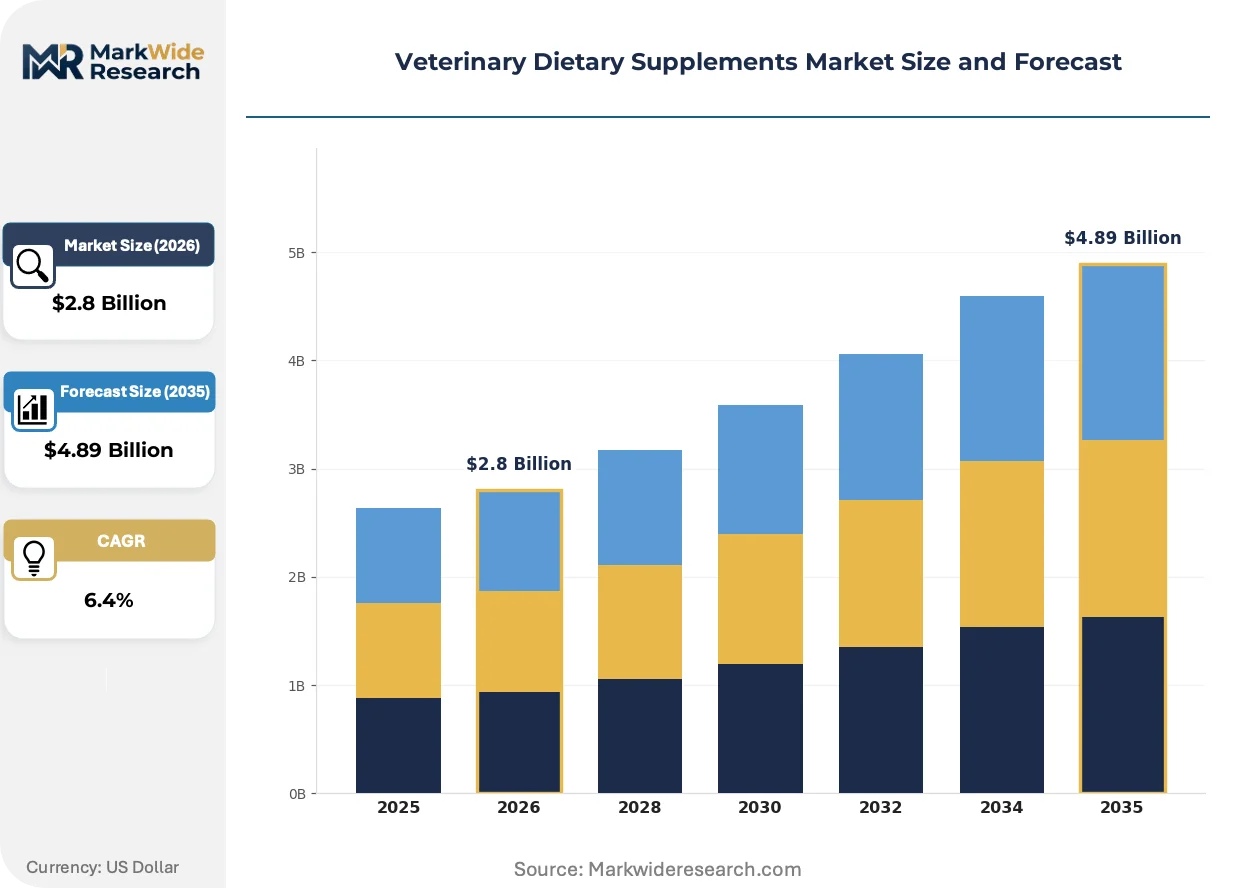
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Amino Acids, Probiotics, Fatty Acids Application: Joint Health, Digestive Health, Skin & Coat Health, Immune Support Animal Type: Dogs, Cats, Horses, Livestock Distribution Channel: Veterinary Clinics, Pet Stores, Online Retail, Distributors |
| Companies Covered | Nestlé Purina PetCare Company, Mars Petcare, Nutramax Laboratories, Virbac, Zoetis, Elanco, H&H Group, Vetoquinol, Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Dietary Supplements Market Strategic Shifts & Innovations
Microbiome science and precision dosing technologies are recalibrating how veterinary supplements demonstrate value, shifting competitive advantage from marketing claims to measurable physiological outcomes.
Synbiotic formulations combining targeted probiotics with prebiotic substrates are displacing single-strain products in premium positioning. Veterinary dermatology practices are adopting these combinations for atopic dogs at accelerating rates. The technology is displacing conventional antibiotic adjunct therapies in chronic skin management protocols.
The FDA Center for Veterinary Medicine's adverse event reporting modernization is tightening post-market surveillance obligations. Manufacturers must now maintain pharmacovigilance infrastructure previously reserved for pharmaceutical registrants. Small and mid-size suppliers in the United States are consolidating to spread compliance costs across broader portfolios.
Pet owner research behavior now precedes veterinary consultation, with online reviews and ingredient databases shaping purchase decisions before clinic visits. This pattern is compressing the traditional veterinarian-as-gatekeeper model. Subscription commerce platforms in North America and Western Europe capture these self-directed buyers through educational content funnels.
Veterinary Dietary Supplements Market Segmentation
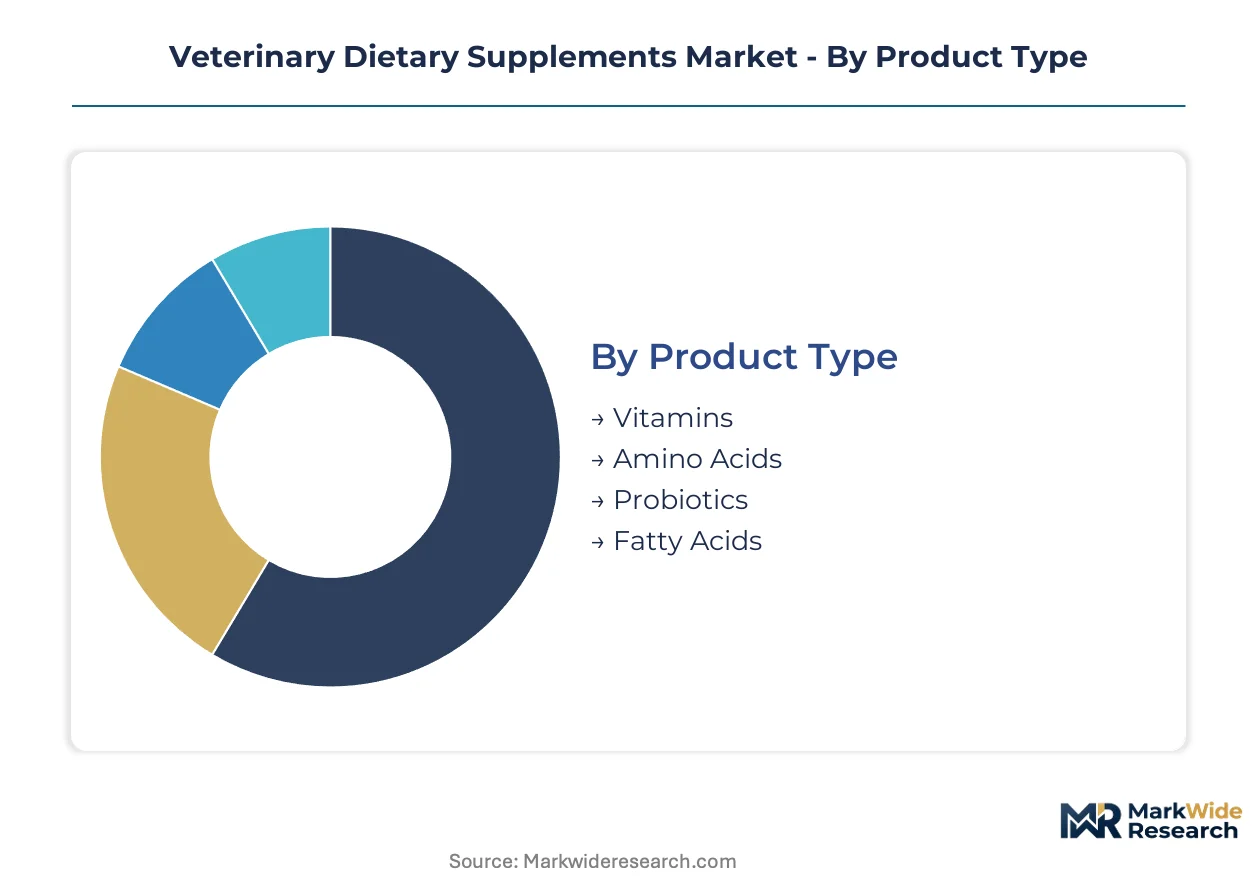
Veterinary dietary supplements fragment across four intersecting dimensions that determine formulation specifications, regulatory pathways, and margin structures. Product chemistry and animal physiology dictate manufacturing investments, while channel access controls price realization and customer loyalty mechanics.
Product Type:
Probiotics and fatty acids concentrate production in North American and European facilities serving export markets, while vitamins and amino acids source from integrated chemical manufacturers with global distribution networks.
- Vitamins:Synthetic and natural vitamin complexes address nutritional deficiencies in commercial feed formulations. Demand clusters in Midwestern US livestock operations and Scandinavian aquaculture facilities where deficiency correction protocols are mandatory.
- Amino Acids:Lysine, methionine, and taurine supplements optimize protein utilization in high-performance animals. Brazilian poultry integrators and Thai shrimp farming cooperatives drive volume procurement through long-term supply contracts.
- Probiotics:Multi-strain bacterial formulations with defined CFU counts support gastrointestinal resilience. German and Danish veterinary practices prescribe these for post-antibiotic recovery protocols in companion animals.
- Fatty Acids:Marine and plant-derived omega-3 and omega-6 concentrates target inflammatory modulation. Norwegian salmon producers and California equine rehabilitation centers sustain premium pricing for high-EPA formulations.
Vitamins command the established base. The steepest expansion runs through probiotics.
Application:
Joint health and digestive health applications generate recurring purchase patterns that subscription platforms exploit, while skin and immune formulations concentrate in seasonal demand spikes.
- Joint Health:Glucosamine, chondroitin, and MSM combinations target osteoarthritis progression in aging animals. US specialty veterinary clinics bundle these into senior wellness protocols for large-breed dogs.
- Digestive Health:Enzyme and probiotic formulations address antibiotic-associated dysbiosis and dietary transitions. French and Italian pet owners purchase these through pharmacy channels with veterinary prescriptions.
- Skin & Coat Health:Essential fatty acid and biotin supplements manage atopic dermatitis and shedding. Australian and UK groomer networks recommend these for show-quality coat maintenance.
- Immune Support:Antioxidant and beta-glucan formulations support vaccination response and stress recovery. Japanese cat breeders utilize these during quarantine and transport protocols.
Joint health retains the revenue core. Digestive health climbs the fastest.
Animal Type:
Canine and feline segments dominate value capture in developed markets, while equine and livestock applications sustain margin through specialized formulation requirements and professional oversight.
- Dogs:Formulations span size-specific dosing from toy breeds to giant breeds, with chewable delivery systems dominating retail channels. Urban US and Canadian households drive premium positioning through humanization spending patterns.
- Cats:Palatability engineering addresses finicky consumption, with liquid and powder formats preferred over tablets. European and Japanese markets show particular price tolerance for renal and urinary support variants.
- Horses:Joint, digestive, and respiratory supplements target performance and longevity in competition and breeding stock. Kentucky and Newmarket racing circuits maintain dedicated veterinary nutrition programs.
- Livestock:Feed-additive formats integrate vitamins, minerals, and rumen modifiers for production optimization. Iowa cattle feedlots and Netherlands dairy cooperatives purchase through integrated nutrition services.
Dogs anchor the value base. Horses deliver the steepest margin expansion.
Distribution Channel:
Veterinary clinics and online retail capture divergent customer segments—clinics secure protocol-driven compliance while digital platforms harvest self-directed researchers.
- Veterinary Clinics:In-house dispensing programs integrate supplements into treatment plans with professional endorsement. US and Australian specialty practices build recurring revenue through automated refill programs.
- Pet Stores:Mass-market and specialty retailers stock visible-shelf formats with consumer-friendly labeling. German Fressnapf and US Petco chains curate premium assortments through exclusive brand partnerships.
- Online Retail:Direct-to-consumer and marketplace platforms bypass geographic constraints with subscription mechanics. UK and South Korean millennial pet owners research independently before purchasing through Chewy and local equivalents.
- Distributors:Veterinary and agricultural supply wholesalers serve rural practices and production facilities with bulk logistics. Brazilian and Argentine distributors consolidate fragmented farm-gate demand.
Veterinary clinics defend the professional segment. Online retail scales the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific supply chains for marine-derived omega-3 ingredients, while Rotterdam's petrochemical corridors process synthetic vitamin precursors serving European formulators.
United States
Pet humanization spending concentrates in urban coastal markets from Seattle to Miami. The FDA Center for Veterinary Medicine enforces structure-function claim boundaries through warning letters and import alerts. Kansas City distribution clusters serve Midwestern veterinary practice networks with refrigerated probiotic logistics.
Germany
German pet owners demonstrate exceptional price tolerance for veterinary-prescribed digestive formulations. EFSA and the Feed Additives Regulation impose batch-level documentation requirements for synbiotic products. Munich and Hamburg host specialized contract manufacturers serving Nordic export markets.
China
Domestic companion animal ownership expansion drives demand for imported joint health formulations. SAMR and NMPA coordinate cross-border e-commerce enforcement for animal supplement imports. Shanghai Yangshan port facilities process growing volumes of Australian and New Zealand-sourced omega-3 concentrates.
United Kingdom
Post-Brexit regulatory divergence complicates EU product recognition for Northern Irish distributors. The Veterinary Medicines Directorate maintains distinct adverse event reporting protocols from continental systems. London and Manchester veterinary specialty practices drive premium supplement dispensing volumes.
Brazil
Equine performance nutrition sustains margin pools unavailable in mass-market companion animal segments. ANVISA's evolving supplement classification creates compliance uncertainty for imported probiotic formulations. São Paulo state integrates veterinary nutrition services into large-scale breeding and racing operations.
Veterinary Dietary Supplements Market Key Industry Players
Listed leaders compete with private specialists across channel access and clinical validation depth. The vendor base stratifies into three tiers: multinational consumer packaged goods conglomerates with veterinary clinic networks, mid-cap pharmaceutical-animal health hybrids, and single-category specialists with science-backed positioning. Strategic archetypes include prescription-anchored dispensers, direct-to-consumer subscription platforms, and equine-focused premium formulators. Capacity expansion and veterinary practice acquisition represent the dominant competitive moves.
Within the multinational tier, Nestlé Purina PetCare Company and Mars Petcare exemplify consumer packaged goods conglomerates leveraging veterinary clinic partnerships for protocol-driven dispensing. Nutramax Laboratories occupies a position as a science-anchored specialist, while Virbac and Zoetis represent pharmaceutical-animal health hybrids with regulatory infrastructure advantages. These five entities collectively illustrate the competitive tension between mass-market scale and clinical-grade credibility.
| Leading Market Players |
|---|
| Nestlé Purina PetCare Company |
| Mars Petcare |
| Nutramax Laboratories |
| Virbac |
| Zoetis |
| Elanco |
| H&H Group |
| Vetoquinol |
| Colgate-Palmolive Company |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day inventory cycles for marine-derived omega-3 concentrates compress margin buffers when Peruvian catch quotas tighten, concentrating pricing power with Norwegian processors who maintain strategic stockpiles. This lead-time volatility forces formulators to choose between premium sourcing contracts and economy-tier substitutions that sacrifice clinical-grade purity claims.
Pricing Analysis
Volume-discount tiering structures separate veterinary-exclusive formulations from mass-market retail equivalents through National Animal Supplement Council certification requirements. Three-tier pricing stratification across clinical-grade, professional-grade, and consumer-grade levels reflects batch-level testing documentation and cold-chain logistics investment. Pricing pressure stems from generic probiotic substitution by human-grade contract manufacturers undercutting veterinary-specific margins. Large-scale livestock integrators in Brazil and Iowa exhibit highest price sensitivity, while Kentucky equine rehabilitation centers demonstrate lowest elasticity for joint health formulations.
Supply Chain Analysis
Just-in-time inventory strategies dominate probiotic manufacturing where shelf-life constraints limit strategic stockpiling, while fatty acid formulators maintain six-month strategic reserves against Peruvian anchovy quota volatility. Marine omega-3 supply concentrates in Peru, Norway, and Chile, with synthetic vitamin precursors sourcing from Chinese and Indian chemical manufacturers. Raw material dependencies include Antarctic krill oil, fermented probiotic strains, and corn-derived dextrose carriers. Single-source vulnerability runs through Peruvian marine fisheries exposed to El Niño disruption. Distribution runs through Kansas City cold-chain hubs serving Midwestern veterinary networks and Rotterdam petrochemical corridors supplying European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary dietary supplements function as a service-attach opportunity where subscription-based automated refill programs and veterinary protocol compliance monitoring expand faster than one-time product transactions.
For Market Incumbents: Consolidate captive distribution through specialty veterinary practice acquisitions that lock supplement dispensing into treatment protocols. Deepen backward integration into probiotic strain development to defend against human-grade substitution threats. Prioritize National Animal Supplement Council quality seal investment as procurement gatekeeping tightens among major retailers.
For New Entrants and Emerging Players: Lead with direct-to-consumer subscription models targeting millennial pet owners who research independently before veterinary consultation. Capture white-space in feline renal support formulations where palatability engineering barriers deter mass-market competitors. Deploy educational content funnels through veterinary dermatology influencers to establish synbiotic credibility.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because subscription attach rates and protocol-driven refill compliance generate predictable cash flows resistant to economic cyclicality. Target mid-cap specialists with established veterinary clinic dispensing relationships and validated clinical study portfolios. Watch FDA adverse event reporting modernization timelines as inflection indicators for compliance cost consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Practice Acquisition | Captures protocol-driven dispensing relationships that lock recurring supplement revenue into treatment plans. |
| Clinical Validation Investment | Peer-reviewed efficacy studies satisfy FDA Center for Veterinary Medicine structure-function claim requirements. |
| Subscription Platform Launch | Automated replenishment models bypass traditional veterinary gatekeepers for digitally-native pet owners. |
| Cold-Chain Logistics Expansion | Refrigerated distribution infrastructure protects probiotic viability through Kansas City hub networks. |
| Synbiotic Formulation Development | Combined probiotic-prebiotic combinations displace conventional antibiotic adjunct therapies in dermatology protocols. |
Research Approach
Operator-level perspectives from veterinary practice owners, supplement procurement managers at specialty clinics, contract manufacturing executives, and National Animal Supplement Council quality auditors anchored the qualitative base. Primary interview insights combined with secondary validation from FDA Center for Veterinary Medicine warning letter databases, EFSA feed additive authorization registers, and customs trade records for omega-3 concentrate imports. Bottom-up demand modeling across product type, application, animal species, and distribution channel segments triangulated against top-down market sizing.
Sensitivity analysis tested forecast outputs against regulatory enforcement intensity scenarios and raw material price volatility assumptions across the projection horizon. Segmentation dimensions modeled include product chemistry class, therapeutic application, animal physiology, and channel access tier. CAGRs derived from historical growth pattern analysis adjusted for pet humanization spending trajectory and veterinary clinic dispensing program expansion rates. Forecast inputs incorporated probiotic strain patent expiration timelines and marine fishery quota allocation patterns.
Underlying assumptions cover regulatory enforcement continuity, pet ownership demographic stability, and ingredient supply chain integrity, with deviation risk concentrated in FDA structure-function claim reinterpretation and Peruvian anchovy biomass fluctuations. Revision becomes warranted when FDA adverse event reporting mandates trigger compliance cost spikes exceeding mid-tier manufacturer absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Pet Herbal Supplements Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Detox Products Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Ipriflavone Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Glucosamine Supplements Market