
 3D-Printed Prosthetic Implants Market | 2026-2036
3D-Printed Prosthetic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
3D-Printed Prosthetic Implants Market Outlook
Multi-material jetting is tilting fabrication workflows toward anatomically precise lattice structures with tunable porosity. Materialise NV anchors European clinical translation through its certified medical 3D-printing backbone. Össur hf differentiates via its integrated digital workflow spanning scan-to-fit socket production. Stratasys Ltd. leverages proprietary photopolymer platforms to compete in dental and craniofacial niches.
3D-printed prosthetic implants are patient-matched medical devices fabricated via additive manufacturing from biocompatible polymers, titanium alloys, or ceramic composites, with pore sizes typically engineered between 100–500 micrometers to promote osseointegration. These implants replace or support missing biological structures across orthopedic, maxillofacial, and dental applications. Lower limb applications dominate current procedural volume due to the scale of amputee populations requiring transfemoral and transtibial solutions. Metal segments command premium positioning where load-bearing durability is non-negotiable, while polymer adoption accelerates in pediatric and temporary prosthetics where adjustability and cost sensitivity shape procurement decisions.
FDA 510(k) pathways and EU MDR conformity assessments govern commercial access in the United States and Europe, with both frameworks tightening biocompatibility documentation requirements for powder-bed fusion processes. ISO 13485 quality management standards and ASTM F3335 guidelines for additively manufactured medical devices further structure validation protocols that manufacturers must satisfy before clinical deployment. Stakeholders must monitor evolving reimbursement codes for custom prosthetics, as payer recognition of patient-specific additive manufacturing remains uneven across national health systems and directly shapes addressable market expansion.
Market Dynamics
Patient-matched additive manufacturing is collapsing traditional implant production timelines from months to days, compressing hospital procurement cycles and forcing orthopedic device suppliers to restructure fulfillment architectures around distributed printing nodes rather than centralized molding facilities.
Growth Catalysts
- EU MDR patient-specific device pathways:The streamlined conformity assessment for custom prosthetics accelerates European commercialization, with notified bodies in Germany and the Netherlands expanding dedicated additive manufacturing review capacity.
- Titanium powder-bed fusion:Load-bearing osseointegration performance now matches forged implants for mandible and acetabular applications, driving orthopedic hospital adoption in trauma and oncology reconstruction.
- Veterans' health networks:The United States Department of Veterans Affairs mandates 3D-printed upper-limb socket compatibility in new procurement frameworks, creating volume anchors for digital workflow providers.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V feedstock production clusters in Germany and the United States, exposing device manufacturers to aerospace demand shocks and price volatility.
- FDA 510(k) biocompatibility documentation:Powder-bed fusion processes face heightened validation requirements for residual stress and surface roughness, extending premarket submission preparation by 8-14 months.
- Conventional CNC-milled patient-specific implants:Subtractive manufacturing retains cost advantages for simple geometries, limiting additive penetration in high-volume, low-complexity spinal fusion cages.
Strategic Opportunities
- Pediatric adjustable prosthetics:Polymer lattice structures with modular growth accommodation address the 15-20% annual size adjustment requirement in juvenile amputee populations, a segment conventional titanium cannot serve economically.
- India PLI scheme for medical devices:Domestic additive manufacturing incentives reduce import dependency for cranial plates, creating localized production partnerships for European technology licensors.
- ISO/ASTM 52900-52931 standard convergence:Unified terminology and test methods across powder-bed fusion, material extrusion, and vat photopolymerization reduce multi-jurisdictional compliance duplication.
Industry Challenges
- Biomedical design-for-additive-manufacturing expertise:Lattice topology optimization and build orientation stress modeling require rare cross-training in mechanical engineering and clinical anatomy, constraining scalable workforce development.
- ISO 13485 quality management system adaptation:Traditional device manufacturers struggle to integrate real-time build monitoring, powder traceability, and post-process validation into legacy document control frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D-Printed Prosthetic Implants Market |
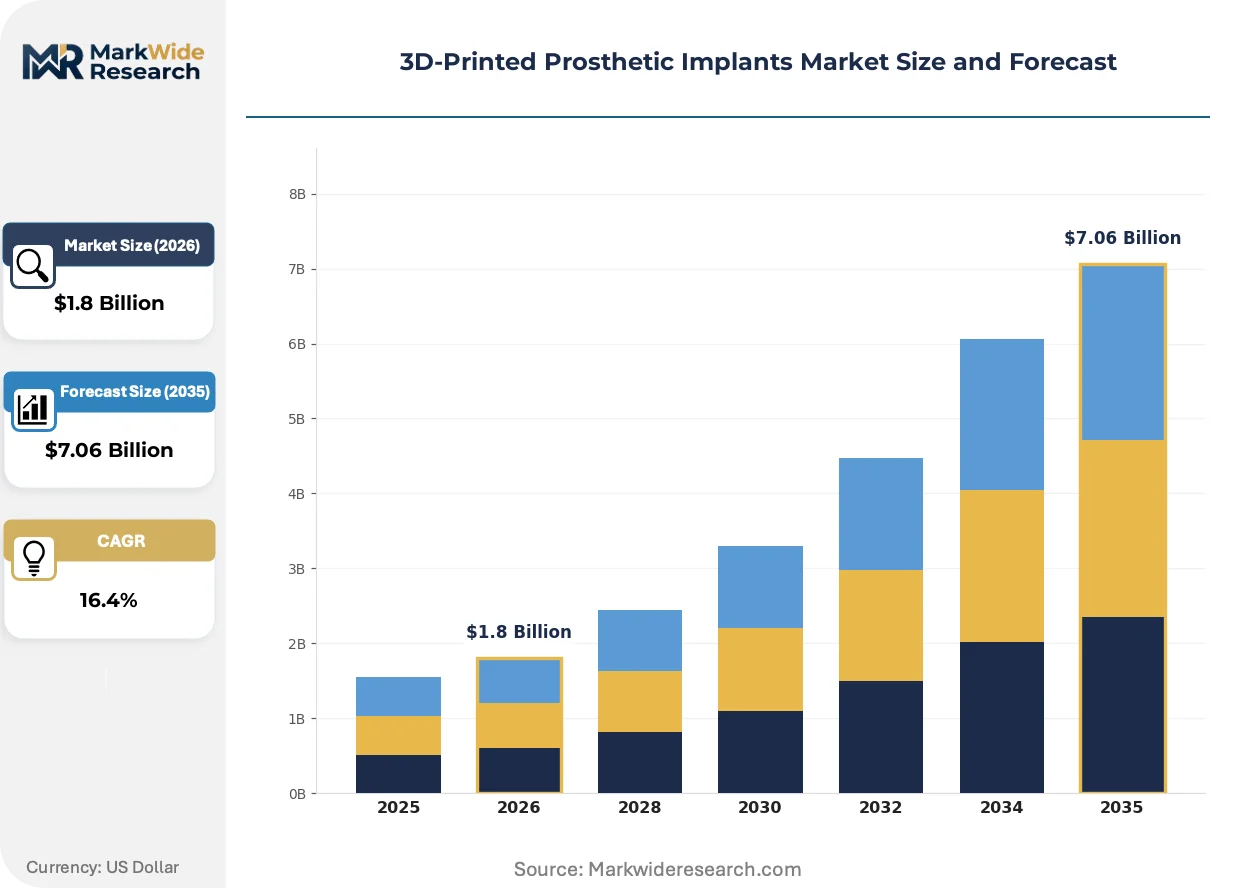
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Limb, Lower Limb, Craniofacial, Dental Material: Polymers, Metals, Ceramics, Composites Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Binder Jetting End User: Hospitals, Clinics, Rehabilitation Centers, Homecare |
| Companies Covered | 3D Systems Corporation, Stratasys Ltd., EnvisionTEC GmbH, Materialise NV, Formlabs, Össur hf, UNYQ, Mecuris, LimbForge, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D-Printed Prosthetic Implants Market Strategic Shifts
Computational design tools and multi-material deposition systems are dissolving the boundary between anatomical imaging and production-ready implant files, compressing the translation from radiological scan to surgical placement.
Multi-material jetting systems deposit photopolymers with variable durometer in single builds, producing prosthetic sockets with rigid structural zones transitioning to compliant tissue-contact surfaces without assembly. Veterans' health networks in the United States adopt these platforms for transtibial applications at 40% annual expansion rates. This convergence of material and geometric control is digitizing the prosthetist's role from craftsman to computational designer.
FDA breakthrough device designation for 3D-printed cranial reconstruction plates compresses review timelines from 180 to 90 days, prioritizing additive manufacturing pathways for traumatic injury and tumor resection cases. The industrial consequence is a reallocation of regulatory affairs resources toward patient-specific predicate strategies rather than standardized device portfolios. Maxillofacial reconstruction centers in Germany and the United States now structure clinical trial partnerships explicitly around this accelerated pathway.
Hospital procurement departments increasingly contract for complete scan-to-implant workflows rather than discrete device purchases, unbundling traditional distributor margins. This model compresses vendor selection criteria toward software integration depth and surgical planning collaboration. Academic medical centers in the United States and university hospitals in Germany lead this transition, with bundled contracts now covering preoperative virtual planning, implant fabrication, and intraoperative delivery logistics.
3D-Printed Prosthetic Implants Market Segmentation
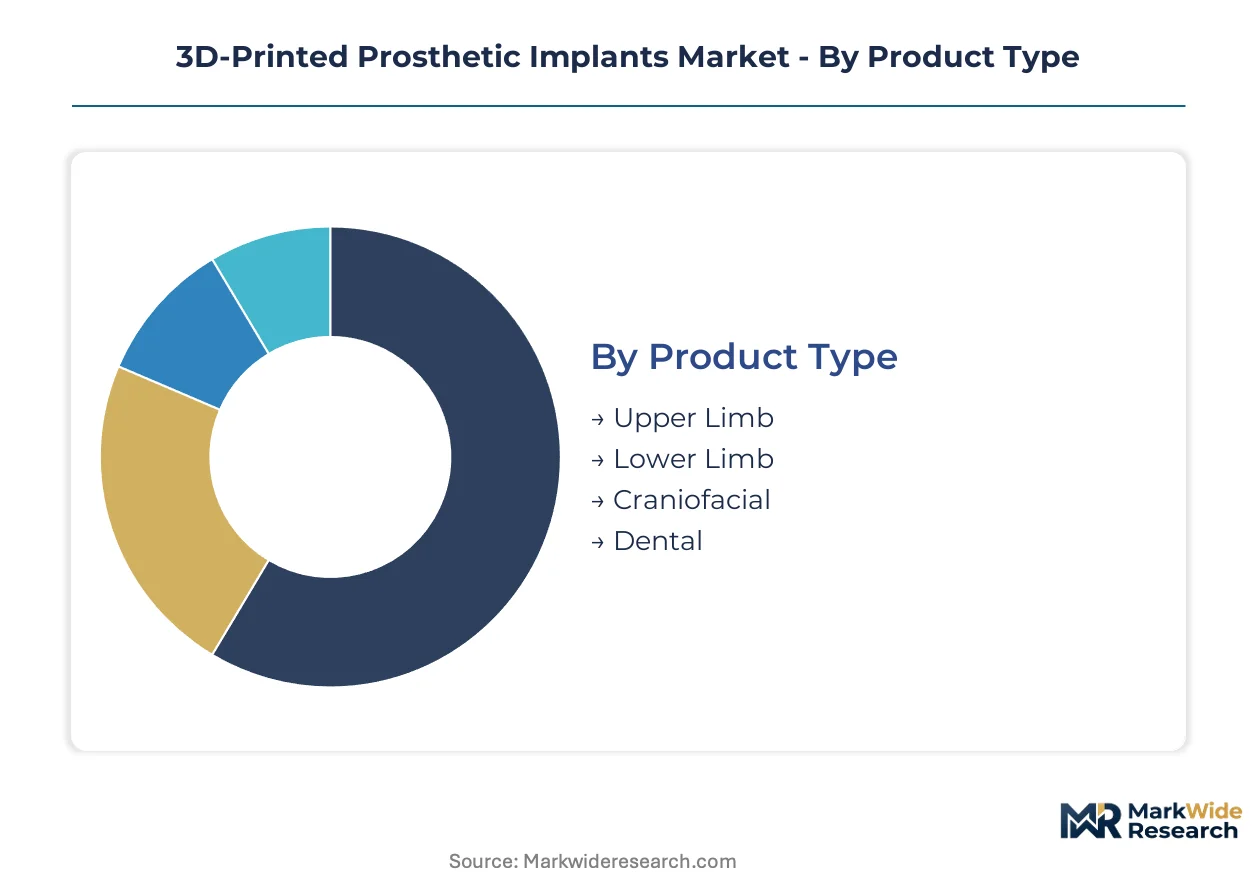
Segmentation in the 3D-Printed Prosthetic Implants Market reveals how additive manufacturing capabilities align with distinct anatomical demands, material performance requirements, and clinical workflow integration points. Understanding these divisions exposes where patient-matched fabrication delivers decisive advantages over conventional production methods.
Product Type:
Mature reconstructive applications coexist with emerging anatomical frontiers as regulatory pathways and reimbursement frameworks mature at uneven rates across anatomical sites.
- Lower Limb:Transfemoral and transtibial solutions dominate procedural volume, with titanium socket interfaces and carbon-fiber pylons now standard in veterans' health networks. Demand concentrates in the United States where the Department of Veterans Affairs mandates digital socket compatibility, though polymer lattice alternatives gain traction in pediatric populations requiring annual size adjustments.
- Upper Limb:Myoelectric hand prostheses with patient-matched socket interfaces command premium positioning, driven by defense procurement frameworks and occupational therapy outcomes. German orthopedic hospitals and US military treatment facilities anchor adoption, with multi-material jetting enabling rigid-to-compliant transitions in single builds.
- Craniofacial:Titanium mandible and cranial plates leverage FDA breakthrough designation pathways, compressing review timelines for trauma and oncology reconstruction cases.
- Dental:Crown and bridge frameworks represent the most mature regulatory pathway, with ISO 13485-certified production nodes distributed across academic medical centers.
Lower limb retains volume leadership; craniofacial holds the steepest expansion curve.
Material:
Cost tiers stratify sharply between commodity feedstocks and aerospace-grade spherical powders, with procurement decisions increasingly driven by load-bearing requirements versus adjustability needs.
- Metals:Ti-6Al-4V ELI powder dominates load-bearing applications, with pore architectures engineered between 100-500 micrometers to promote osseointegration. German orthopedic trauma centers and US craniofacial reconstruction units specify powder-bed fusion for mandible and acetabular implants where fatigue resistance matches forged alternatives.
- Polymers:PEEK and photopolymer resins address pediatric and temporary prosthetics where cost sensitivity and size adjustability override durability requirements. Modular growth accommodation in juvenile amputee populations drives 15-20% annual size adjustment protocols that titanium cannot serve economically.
- Ceramics:Hydroxyapatite-coated alumina structures serve maxillofacial applications requiring osteoconductive surfaces.
- Composites:Carbon-fiber reinforced polymers bridge the gap between polymer flexibility and metal stiffness in transtibial pylons.
Metals command premium positioning in trauma reconstruction; polymers are expanding most quickly in pediatric segments.
Technology:
Volume manufacturing gravitates toward established powder-bed platforms while emerging deposition methods unlock multi-material anatomical precision.
- Selective Laser Sintering:Nylon-12 and TPU powder platforms dominate prosthetic socket production, with build chambers scaling to 700mm dimensions accommodating full-limb geometries. Veterans' health networks in the United States standardize on SLS for transtibial applications at 40% annual expansion rates.
- Material Extrusion (Fused Deposition Modeling):ABS and PLA filament systems serve prototyping and temporary splint applications where surface finish requirements permit layer-line visibility. Cost advantages position FDM in homecare and developing market access.
- Stereolithography:Vat photopolymerization delivers surgical guides and dental models requiring sub-100-micron accuracy.
- Binder Jetting:Metal injection molding feedstock compatibility enables stainless steel and bronze alloy production without laser-based capital intensity.
Selective Laser Sintering retains installed base dominance; multi-material jetting platforms gain share fastest in socket applications.
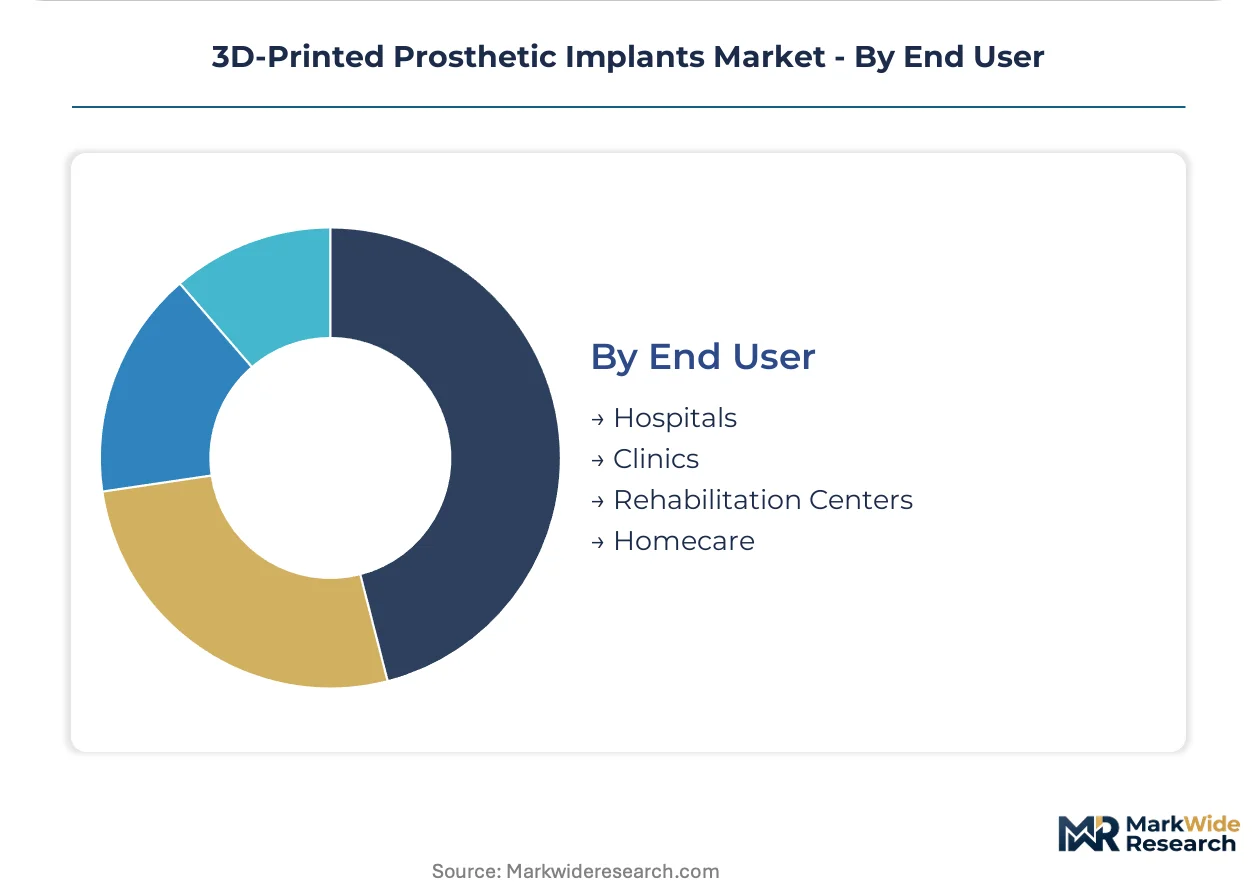
End User:
Customer type determines workflow integration depth, with academic medical centers demanding complete scan-to-implant bundles while homecare segments prioritize cost-minimized filament systems.
- Hospitals:Academic medical centers in the United States and university hospitals in Germany contract for bundled scan-to-implant workflows covering preoperative virtual planning, fabrication, and intraoperative logistics. Procurement departments unbundle traditional distributor margins, selecting vendors on software integration depth.
- Rehabilitation Centers:Outpatient prosthetic facilities prioritize socket production speed and digital workflow training, with Medicare reimbursement codes for custom prosthetics shaping addressable expansion.
- Clinics:Private maxillofacial and dental practices concentrate on crown and bridge frameworks with same-day turnaround requirements.
- Homecare:Consumer-grade filament printers serve remote and rural populations with basic splint and temporary prosthetic needs.
Hospitals retain revenue concentration; rehabilitation centers are gaining share fastest as bundled contracts shift procurement authority from distributors to clinical engineering departments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German titanium powder suppliers export spherical Ti-6Al-4V feedstock to orthopedic device manufacturers across the United States and European trauma centers, establishing a critical raw-material corridor for patient-specific mandible and acetabular implants.
United States
The Department of Veterans Affairs mandates 3D-printed upper-limb socket compatibility in procurement frameworks, driving volume for digital workflow providers. FDA breakthrough device designation for cranial plates compresses review timelines from 180 to 90 days. Academic medical centers in Boston and Baltimore structure bundled scan-to-implant contracts covering virtual planning, fabrication, and intraoperative logistics.
Germany
Orthopedic university hospitals in Berlin and Hamburg expand adoption of patient-specific titanium mandible implants for trauma and oncology reconstruction. EU MDR streamlined conformity assessments for custom prosthetics accelerate commercialization timelines. Notified bodies in Tübingen and Munich expand dedicated additive manufacturing review capacity to handle rising submission volumes.
India
The PLI scheme for medical devices incentivizes domestic additive manufacturing capacity for cranial plates, reducing import dependency for trauma centers in Delhi and Mumbai. CDSCO regulatory pathways for patient-matched implants tighten biocompatibility documentation requirements. Manufacturing partnerships in Gujarat and Karnataka localize production for European technology licensors seeking cost-competitive fabrication nodes.
United Kingdom
NHS England reimbursement frameworks for custom prosthetics remain uneven across integrated care boards, constraining addressable market expansion for socket producers. MHRA post-Brexit regulatory alignment with EU MDR standards extends validation timelines for powder-bed fusion processes. Maxillofacial reconstruction units in London and Manchester prioritize FDA breakthrough-designated cranial plate suppliers for complex tumor resection cases.
Japan
PMDA regulatory pathways for additively manufactured medical devices emphasize ISO 13485 quality management compliance for powder traceability and post-process validation. METI industrial policy supports titanium powder-bed fusion adoption in orthopedic trauma centers. Manufacturing clusters in Osaka and Nagoya develop certified production nodes for dental crown and bridge frameworks requiring same-day turnaround.
3D-Printed Prosthetic Implants Market Competitive Environment
Channel-controlling players compete with product-specialist players across fabrication technology, regulatory clearance depth, and surgical workflow integration. Market structure tilts toward consolidation among certified medical device manufacturers with ISO 13485 quality systems, while fragmented service bureaus compete on socket production speed. Three archetypes dominate: powder-bed fusion platform owners with aerospace-grade titanium supply chains, photopolymer system vendors serving dental and craniofacial niches, and integrated digital workflow providers spanning scan-to-fit production. Dominant competitive moves include strategic partnerships with academic medical centers for bundled contract capture and technology licensing to localize production in India and Southeast Asia.
Within the integrated workflow tier, Materialise NV and Össur hf exemplify archetypes that anchor European and North American clinical translation respectively. Among photopolymer platform vendors, Stratasys Ltd. occupies a position competing in dental and craniofacial applications. These three represent the spectrum from certified medical backbone providers to socket production specialists.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| Stratasys Ltd. |
| EnvisionTEC GmbH |
| Materialise NV |
| Formlabs |
| Össur hf |
| UNYQ |
| Mecuris |
| LimbForge, Inc. |
| Others |
Value Chain & Pricing Dynamics
Titanium powder supply concentration in Germany and the United States determines both pricing tier spreads and supply chain shape, with aerospace demand shocks cascading into medical feedstock costs and forcing device manufacturers to absorb margin compression or pass through to hospital procurement committees.
Pricing Analysis
Powder-bed fusion platforms command substantial premiums over material extrusion systems, with next-generation multi-material jetting equipment widening the technology-generation pricing gap further. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated cranial plates from CE-marked mandible implants and unregulated temporary sockets. Price differentiation stems from ISO 13485 certification depth and powder traceability documentation, with German orthopedic trauma centers least price-sensitive and Indian domestic manufacturers most exposed to cost compression. Pricing pressure stems from conventional CNC-milled alternatives retaining cost advantages for simple geometries, squeezing additive margins in high-volume spinal fusion applications.
Supply Chain Analysis
Contract manufacturing concentration rests with Materialise NV's certified production backbone in Belgium, Stratasys Ltd.'s photopolymer foundries in Israel and the United States, and emerging Indian PLI-subsidized fabrication nodes in Gujarat and Karnataka. Geographic supply concentration centers on Germany for spherical Ti-6Al-4V powder, the United States for photopolymer resin formulation, and China for carbon-fiber pylon feedstock. Raw material dependencies draw from aerospace-grade titanium powder, biocompatible PEEK pellets, and ceramic hydroxyapatite coatings. Single-source vulnerability runs through German powder suppliers exposed to aerospace demand shocks. Distribution runs through hospital procurement departments contracting for bundled scan-to-implant workflows rather than discrete device purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-matched additive manufacturing fragments procurement authority from traditional distributors to clinical engineering departments, creating white-space opportunities for workflow-integrated challengers alongside certified incumbents.
For Market Incumbents: Harden regulatory moats by deepening ISO 13485 quality system investments to capture EU MDR streamlined pathways before notified body capacity saturates. Anchor hospital procurement relationships through backward integration into preoperative virtual planning software, neutralizing the threat of pure-play socket producers unbundling distributor margins. Prioritize certification maintenance over capacity expansion in titanium powder-bed fusion where residual stress documentation requirements are tightening. For New Entrants and Emerging Players: Build out pediatric adjustable prosthetics capabilities where polymer lattice structures address 15-20% annual size adjustment requirements that titanium cannot serve economically. Target rehabilitation centers in the United States where Medicare reimbursement codes for custom prosthetics are expanding fastest. Pursue technology licensing partnerships with Indian PLI scheme beneficiaries to establish cost-competitive fabrication nodes for cranial plates without capital-intensive powder-bed fusion infrastructure. For Investors and Strategic Acquirers: FDA breakthrough device designation for cranial plates reshapes the acquisition landscape by compressing regulatory timelines and rewarding patient-specific predicate strategies over standardized portfolios. Long-term viability across the analysis window favors integrated digital workflow providers spanning scan-to-fit production over pure hardware manufacturers. Target acquisition archetypes include ISO 13485-certified service bureaus with hospital system partnerships and software-embedded design-for-additive-manufacturing expertise. Monitor EU MDR notified body queue lengths as the signal indicating when regulatory capacity constraints will ease and accelerate European commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Compresses review timelines from 180 to 90 days for cranial reconstruction plates. |
| Hospital System Partnership | Captures bundled scan-to-implant contracts unbundling traditional distributor margins. |
| Software Companion Development | Integrates lattice topology optimization tools into surgical planning workflows. |
| CE Marking Pathway | Unlocks EU MDR streamlined conformity assessments for custom prosthetics in Germany. |
| Reimbursement Strategy | Secures Medicare codes for custom prosthetics in veterans' health networks. |
Study Parameters
Initial hypotheses were tested against primary input from orthopedic surgeons, biomedical engineers, hospital procurement managers, and GPO contracts managers, and refined through secondary validation against FDA 510(k) filings, EU MDR submission databases, CMS Medicare reimbursement data, and hospital procurement records. Bottom-up volume estimates from procedural counts and implant pricing were triangulated against top-down market sizing from certified manufacturer capacity disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling adoption curves by product type including lower limb, upper limb, craniofacial, and dental segments alongside material tier, fabrication technology, and end-user channel. CAGRs were derived from fitted growth curves incorporating regulatory approval velocity, reimbursement expansion rates, and powder supply elasticity. Industry-specific forecast inputs included veterans' health network procurement mandates and EU MDR notified body capacity constraints.
Stress conditions across titanium powder price volatility, FDA review timeline variability, and Medicare reimbursement code expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and hospital procurement contract structures. Quarterly review of EU MDR submission queue lengths and veterans' health network procurement award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Intubation Tubes Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Ocular Implants Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Global Vitreoretinal Surgery Devices Market