
 UAE Spinal Surgery Devices Market | 2026-2036
UAE Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Spinal Surgery Devices Market Analytics
Buyer concentration among Dubai and Abu Dhabi's largest hospital groups is recalibrating procurement dynamics across the UAE spinal surgery devices landscape. Medtronic Meta FZ-LLC leverages its regional distribution infrastructure to sustain premium positioning in implantable systems. Johnson & Johnson UAE anchors its presence through deep relationships with Ministry of Health-affiliated facilities. Stryker ESCS BV competes aggressively on navigation-integrated surgical platforms.
Spinal surgery devices encompass implantable hardware, precision instrumentation, and biomaterial adjuncts engineered from titanium alloys, PEEK polymers, and bone graft substitutes to restore vertebral stability and neural decompression. These systems must meet exacting biomechanical load-bearing specifications and biocompatibility standards to ensure long-term osseointegration and patient mobility outcomes. Implants and instrumentation currently occupy the largest revenue pools, while robotic-assisted surgery and minimal invasive techniques represent the fastest-expanding technology segments as surgeons prioritize reduced recovery times and operative precision. Biomaterials command outsized margins due to limited regional manufacturing and dependence on imported advanced graft matrices.
MOHAP, the Dubai Health Authority, and the UAE's adoption of GCC-wide medical device harmonization standards govern product registration, post-market surveillance, and clinical evidence requirements for spinal implants. These frameworks elevate barriers for new entrants while reinforcing quality benchmarks that favor established multinationals with robust regulatory affairs capabilities. Stakeholders must monitor how impending localization incentives and compulsory health insurance expansions reshape volume flows across public and private delivery channels.
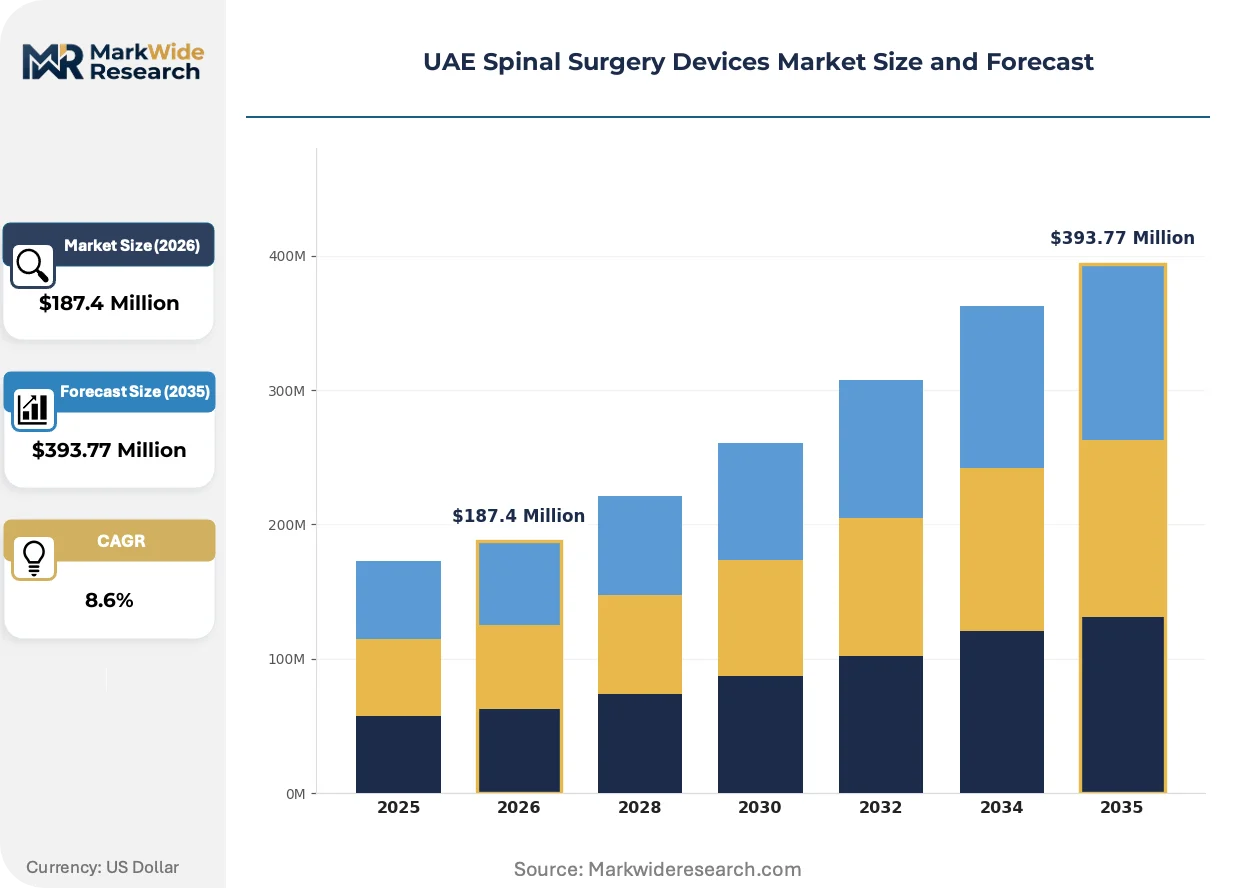
Market Dynamics
MOHAP's tightening device registration requirements for implantable spinal systems is restructuring competitive access across the UAE, privileging multinationals with established regulatory affairs infrastructure while elevating compliance costs for newer entrants.
Growth Catalysts
- Robotic-Assisted Surgery:Navigation-integrated surgical platforms are accelerating adoption among tertiary care hospitals in Dubai's medical corridor, compressing operative timelines and improving vertebral placement precision.
- GCC Medical Device Harmonization:The UAE's alignment with regional standards is streamlining cross-border product registration, reducing time-to-market for established implantable hardware manufacturers.
- Aging Demographics:Rising orthopedic referral volumes among UAE nationals are expanding the addressable patient pool for degenerative disc disease and spinal stenosis interventions.
Market Restraints
- Import Dependence for Biomaterials:Advanced bone graft matrices and PEEK polymers rely on limited foreign suppliers, exposing margins to currency volatility and shipping disruptions.
- MOHAP Registration Complexity:Post-market surveillance requirements and clinical evidence mandates for implantable systems extend commercialization timelines by 18-24 months for non-established players.
- Reimbursement Compression:Compulsory health insurance expansions are tightening procedure coverage limits, pressuring device pricing across public and private delivery channels.
Strategic Opportunities
- Abu Dhabi Medical City Expansion:New orthopedic specialty centers in the capital are creating concentrated demand for minimal invasive instrumentation and navigation platforms.
- Localization Incentives:Pending domestic manufacturing subsidies for medical devices could reduce import duties and accelerate regional supply chain development.
- AI-Enabled Preoperative Planning:Convergence of machine learning algorithms with 3D patient imaging is enabling personalized implant sizing and surgical simulation workflows.
Industry Challenges
- Neurosurgeon and Orthopedic Specialist Shortage:Limited fellowship-trained spine surgeons in the Emirates constrains surgical volume expansion despite installed device capacity.
- Legacy Hospital Information System Integration:Robotic navigation platforms require costly interoperability upgrades with existing electronic medical records and imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Spinal Surgery Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Implants, Instrumentation, Surgical Tools, Biomaterials End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Application: Decompression, Fusion, Disc Replacement, Fracture Repair Technology: Robotic-assisted Surgery, Navigation Systems, 3D Printing, Minimal Invasive Techniques |
| Companies Covered | Medtronic Meta FZ-LLC, Stryker ESCS BV, Johnson & Johnson UAE, Karl Storz UAE, Fujifilm Middle East FZE, Globus Medical, B. Braun Melsungen AG, NuVasive Inc., Matrix Meditec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Spinal Surgery Devices Market Evolving Landscape
Spinal surgery in the UAE is pivoting toward precision automation and value-verified outcomes, with technology vendors and hospital groups recalibrating around reduced recovery metrics and bundled procedure economics.
Navigation-integrated robotic platforms are unifying preoperative imaging, intraoperative guidance, and implant placement verification into single-workflow systems. Dubai's largest hospital groups are deploying these systems in dedicated spine centers, compressing operative time and reducing revision rates. This unification is shifting competitive differentiation from hardware durability to software-enabled surgical accuracy and training support.
MOHAP's adoption of GCC-wide medical device harmonization standards is elevating post-market surveillance obligations for implantable spinal systems. Manufacturers must now maintain active adverse event registries and submit periodic safety updates. High-risk implant categories face the steepest compliance burden, with established multinationals leveraging existing quality management systems to accelerate approvals.
Hospital procurement committees are consolidating vendor relationships around full-procedure contracts that bundle implants, instrumentation, and technical support. Dubai's medical corridor leads this consolidation, with tertiary centers reducing supplier panels from twelve to four preferred partners. Abu Dhabi's Ministry of Health-affiliated facilities are following, prioritizing outcome guarantees and surgeon training commitments over standalone device pricing.
UAE Spinal Surgery Devices Market Segmentation
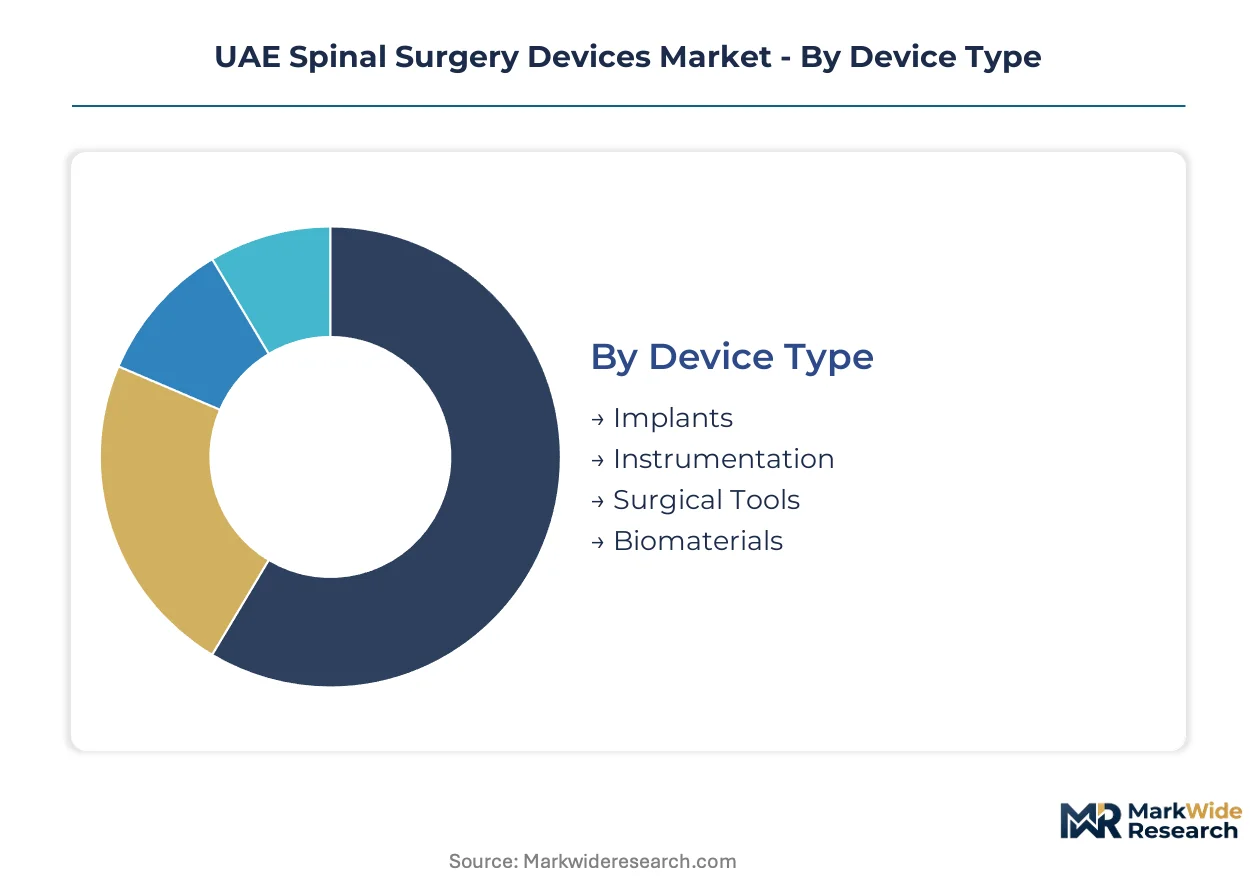
Segmentation in the UAE spinal surgery devices market reveals how regulatory requirements, clinical workflows, and procurement priorities diverge across product categories and care settings. Understanding these divisions enables manufacturers to align certification strategies with the specific compliance burdens each segment carries.
Device Type:
MOHAP registration complexity escalates with implant permanence—permanent implants demand extensive clinical evidence and active adverse event registries, while consumable instrumentation faces lighter surveillance obligations.
- Implants:Titanium alloy and PEEK polymer constructs engineered for permanent vertebral stabilization must satisfy biomechanical load-bearing specifications and long-term biocompatibility standards. Dubai's tertiary hospitals concentrate demand for these systems as surgical volumes for degenerative conditions expand.
- Instrumentation:Precision surgical tools including retractors, distractors, and fixation drivers support implant placement accuracy. Abu Dhabi's orthopedic specialty centers prioritize navigation-compatible instrument sets that integrate with robotic platforms.
- Surgical Tools:Disposable and reusable instruments for tissue manipulation and exposure.
- Biomaterials:Bone graft substitutes and advanced matrices imported from limited foreign suppliers.
Leading the category by volume: Implants. Growing fastest: Biomaterials.
End User:
Procurement authority concentrates differently across settings—hospital groups negotiate enterprise contracts while surgical centers and clinics operate under more fragmented purchasing arrangements.
- Hospitals:Tertiary care facilities in Dubai's medical corridor generate the dominant share of spinal procedure volume, with MOHAP-affiliated institutions requiring full-procedure vendor contracts bundling devices, training, and technical support.
- Surgical Centers:Ambulatory facilities focused on same-day discharge protocols are gaining traction for select decompression procedures, driving demand for minimal invasive instrumentation with faster turnover characteristics.
- Orthopedic Clinics:Preoperative assessment and postoperative monitoring sites.
- Rehabilitation Facilities:Recovery and mobility restoration centers.
Hospitals command procurement volume leadership. Surgical centers are expanding most quickly.
Application:
Procedure reimbursement tiers and clinical complexity determine device selection—fusion and disc replacement carry higher device intensity than decompression alone.
- Decompression:Laminectomy and discectomy procedures relieving neural pressure represent high-frequency interventions with established minimal invasive alternatives. Dubai's largest hospital groups are standardizing navigation-assisted techniques to reduce revision rates.
- Fusion:Vertebral stabilization combining implants with bone grafting demands the most comprehensive device portfolios and carries the steepest MOHAP registration requirements for permanent hardware.
- Disc Replacement:Motion-preserving artificial disc procedures.
- Fracture Repair:Trauma-focused stabilization for vertebral compression injuries.
Fusion procedures lead device consumption. Disc replacement is climbing the fastest as motion-preserving alternatives gain surgeon acceptance.
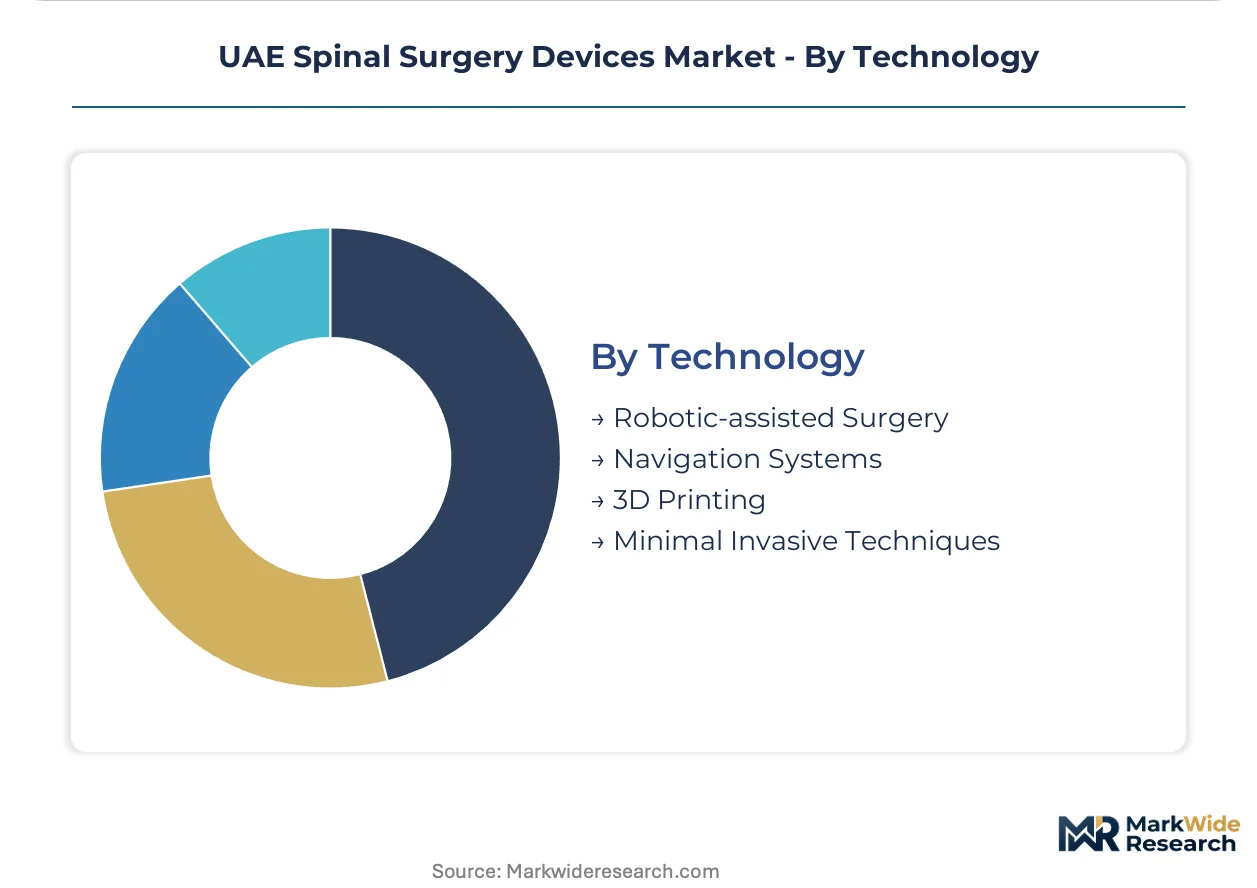
Technology:
Capital equipment requirements and software integration obligations create distinct competitive barriers—robotic platforms demand substantial infrastructure investment while 3D printing enables point-of-care customization.
- Robotic-assisted Surgery:Navigation-integrated platforms unifying preoperative imaging with intraoperative guidance are deploying in dedicated spine centers across Dubai, compressing operative timelines and improving placement precision.
- Navigation Systems:Image-guided surgical planning and real-time trajectory verification tools require costly interoperability upgrades with existing hospital information systems and imaging archives.
- 3D Printing:Patient-specific implant fabrication and surgical modeling.
- Minimal Invasive Techniques:Reduced-tissue-disruption approaches and specialized access instrumentation.
Minimal invasive techniques dominate procedure volume. Robotic-assisted surgery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for spinal surgery devices concentrates in Dubai and Abu Dhabi, where tertiary hospital networks generate the dominant share of procedure volume across the Emirates. Sharjah and the Northern Emirates follow with smaller but expanding orthopedic footprints.
Dubai
Dubai's medical corridor hosts the highest concentration of spinal procedures, driven by medical tourism flows and specialized orthopedic referrals from across the Gulf. Dubai Health Authority facility licensing requirements enforce stringent equipment standards for navigation-integrated surgical platforms. Dubai Healthcare City clusters private specialty centers deploying robotic-assisted surgery systems for complex fusion procedures.
Abu Dhabi
Abu Dhabi's Ministry of Health-affiliated hospitals anchor public sector demand for implantable spinal systems, with new orthopedic specialty centers expanding capacity in the capital. SEHA procurement frameworks mandate outcome guarantees and surgeon training commitments from device vendors. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City concentrate high-complexity spine surgery volumes.
Sharjah
Sharjah's healthcare infrastructure is expanding spinal service lines through university hospital networks and private specialty investments. MOHAP registration requirements apply uniformly, though procurement volumes remain below Dubai and Abu Dhabi tiers. University Hospital Sharjah anchors the emirate's orthopedic referral capacity.
Northern Emirates
Ras Al Khaimah, Fujairah, Ajman, and Umm Al Quwain present nascent demand characterized by patient referrals to Dubai and Abu Dhabi for complex interventions. Federal health insurance expansions are gradually building ambulatory surgical capacity for decompression procedures. RAK Hospital and Fujairah Hospital serve as the primary spine care access points.
UAE Spinal Surgery Devices Market Competitive Landscape
US and European multinationals anchor the premium implant tier; regional distribution specialists hold procurement relationships with Ministry-affiliated facilities. Market structure concentrates among five to seven established players with MOHAP-registered quality management systems. Two strategic archetypes dominate: full-procedure contract vendors bundling devices with training support, and technology-focused platforms competing on navigation integration. Competitive moves center on enterprise procurement consolidation and robotic platform deployment partnerships with tertiary hospital groups.
Within the multinational tier, Medtronic Meta FZ-LLC, Johnson & Johnson UAE, and Stryker ESCS BV occupy positions shaped by regulatory infrastructure depth and distribution reach. Medtronic Meta FZ-LLC represents the established registrant archetype with MOHAP-compliant adverse event registries. Johnson & Johnson UAE exemplifies the Ministry relationship anchor, while Stryker ESCS BV sits within the navigation-technology specialist category competing on surgical platform integration.
| Leading Market Players |
|---|
| Medtronic Meta FZ-LLC |
| Stryker ESCS BV |
| Johnson & Johnson UAE |
| Karl Storz UAE |
| Fujifilm Middle East FZE |
| Globus Medical |
| B. Braun Melsungen AG |
| NuVasive Inc. |
| Matrix Meditec |
| Others |
Value Network & Pricing Analysis
Robotic navigation platform deployment across Dubai's tertiary spine centers is simultaneously elevating capital equipment amortization costs and concentrating procurement power among hospital groups with enterprise-scale purchasing capacity. This technology shift compresses margins for standalone implant vendors while rewarding full-procedure contract suppliers capable of bundling hardware, software, and surgeon training.
Pricing Analysis
Volume concentrates in permanent titanium and PEEK implants while margins accrue to navigation-integrated platforms and imported biomaterials. Pricing stratifies across premium robotic systems, standard navigation-compatible instrumentation, and economy-tier consumables, with MOHAP registration tier and after-sales training commitments as primary differentiation drivers. Cost compression in economy-tier instrumentation intensifies as compulsory health insurance expansions tighten procedure reimbursement ceilings. Ambulatory surgical centers exhibit highest price sensitivity; Dubai's consolidated hospital groups leverage volume scale for steepest discounts.
Supply Chain Analysis
MOHAP's adverse event registry requirements and GCC harmonization standards act as certification gates that filter supplier eligibility before commercial access. Manufacturing concentrates in the United States, Germany, and Switzerland for precision-machined titanium implants; advanced PEEK polymers and bone graft matrices draw from limited production facilities in the United States and Ireland. Single-source vulnerability pervades biomaterial inputs, with currency volatility and trans-Atlantic shipping disruptions as persistent structural risks. Distribution runs through regional distribution subsidiaries holding MOHAP-registered quality management systems, with direct hospital contracting displacing traditional distributor intermediaries in Dubai and Abu Dhabi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where MOHAP's tightening registration requirements and procurement committee vendor panel reductions are systematically eliminating subscale competitors lacking regulatory infrastructure depth.
For Market Incumbents: Anticipate accelerated procurement consolidation by securing full-procedure contracts with outcome guarantees before competitor platforms achieve robotic navigation interoperability. Defend against emerging regional distribution specialists by deepening captive supply relationships with German and Swiss precision manufacturers. Prioritize CE marking and FDA 510(k) pathway maintenance as MOHAP increasingly recognizes foreign regulator approvals as registration shortcuts. For New Entrants and Emerging Players: Ambulatory surgical centers in Sharjah and the Northern Emirates represent the most penetrable buyer archetype, underserved by incumbent field service networks and receptive to minimal invasive instrumentation with rapid turnover characteristics. Target decompression procedure portfolios rather than fusion hardware to bypass MOHAP's steepest implant registration burdens. Pursue white-label manufacturing partnerships with established MOHAP registrants as the fastest go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by US and European multinationals seeking MOHAP-registered distribution infrastructure and hospital group procurement relationships. Long-term viability favors targets with active adverse event registries and software-enabled surgical platform integration capabilities. Watch for MOHAP localization incentive announcements as the critical inflection signal triggering domestic manufacturing joint ventures and supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Registration Acceleration | Compresses commercialization timelines by leveraging FDA and CE marking reciprocity pathways. |
| Robotic Platform Partnership | Secures preferred vendor status with Dubai's consolidated tertiary hospital procurement committees. |
| Biomaterial Supply Diversification | Reduces margin exposure to trans-Atlantic shipping disruptions and euro-dollar volatility. |
| Surgeon Training Academy Investment | Locks in procedural loyalty through fellowship-trained spine surgeon pipeline development. |
| Localization Joint Venture | Captures pending domestic manufacturing subsidies and reduces import duty burdens. |
Research Methodology
Document review covered MOHAP medical device registration databases, Dubai Health Authority facility licensing records, and SEHA procurement framework disclosures, complemented by interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from GCC harmonization standard documentation, customs import records for spinal implant classifications, and multinational medical device SEC filings. Bottom-up procedure volume modeling and top-down market sizing triangulated across hospital capacity data and device shipment patterns.
Cross-referencing historical surgical volume trends against specialist panel input established baseline demand parameters across the projection horizon. Segmentation modeling incorporated device type, end user setting, application complexity, and technology integration level as dimensional variables. CAGRs derived from surgical volume growth trajectories, technology substitution rates, and reimbursement policy evolution assumptions specific to UAE compulsory health insurance expansions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MOHAP localization policy implementation, neurosurgeon fellowship pipeline expansion, and GCC-wide procurement harmonization acceleration. A model refresh is warranted upon material change in MOHAP adverse event registry enforcement intensity or robotic navigation platform reimbursement tier classification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Spinal Implants and Devices Market