
 Industrial Radiography Testing Market | 2026-2036
Industrial Radiography Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Radiography Testing Market Foresight
A shortage of certified radiographic interpreters is redrawing competitive boundaries across the industrial radiography testing landscape. Waygate Technologies GmbH leverages its digital detector portfolio to capture replacement demand from aging film-based installations. Nikon Corporation anchors its position through high-resolution micro-focus X-ray systems serving semiconductor and electronics validation workflows. Fujifilm Holdings Corporation differentiates by sustaining hybrid service models that bridge analog film processing with digital archiving capabilities.
Industrial radiography testing employs ionizing radiation—X-ray tubes generating 10–450 kV or gamma isotopes such as iridium-192 and cobalt-60—to penetrate metallic substrates and reveal subsurface discontinuities without structural destruction. Digital radiography now dominates new equipment procurement because flat-panel detectors deliver real-time imaging at resolution thresholds below 50 micrometers, eliminating chemical processing delays. Pipeline inspection applications command premium pricing due to hazardous environment certification requirements and remote deployment complexity. Within equipment type segmentation, portable systems represent the fastest-growing category as field operators prioritize battery-powered units for offshore and construction site mobility.
ASME Section V and ISO 17636-1 govern weld inspection procedures across North American and European jurisdictions, while the EPA and national nuclear regulators enforce source security and exposure limit compliance. The FDA regulates medical-grade radiography equipment that occasionally cross-pollinates industrial detector designs, creating dual-use certification pathways for manufacturers. Stakeholders must monitor evolving drone-mounted radiography platforms and AI-assisted defect recognition algorithms that promise to reshape technician productivity benchmarks and training investment priorities.
Market Dynamics
The transition from film-based radiography to digital detector arrays under ASME and ISO standards is compressing equipment replacement cycles and redrawing procurement priorities across inspection service providers.
Growth Catalysts
- ASME Section V weld inspection mandates:North American aerospace manufacturers are expanding non-destructive testing programs for turbine blade integrity, creating sustained equipment demand.
- Digital detector array resolution thresholds:Flat-panel detectors now deliver real-time imaging below 50 micrometers, eliminating chemical processing delays and accelerating field adoption.
- German precision engineering clusters:Automotive supply chains in Baden-Württemberg and Bavaria require high-volume weld inspection protocols, concentrating equipment procurement.
Market Restraints
- Gamma isotope supply concentration:Iridium-192 and cobalt-60 sourcing depends on a limited number of nuclear fuel cycle facilities, creating radiotracer availability risk.
- EPA source security compliance costs:Exposure limit enforcement and radioactive material transport regulations impose capital-intensive shielding and tracking infrastructure.
- Certified interpreter scarcity:The shortage of qualified radiographic interpreters limits service capacity expansion regardless of equipment availability.
Strategic Opportunities
- Drone-mounted radiography platforms:Offshore pipeline inspection in the North Sea and Gulf of Mexico is adopting unmanned aerial deployment for hazardous environment access.
- AI-assisted defect recognition:Machine learning algorithms promise to reshape technician productivity benchmarks and reduce interpretation training investment.
- Hybrid service models:Bridge offerings combining analog film processing with digital archiving capture transitional demand from aging installations.
Industry Challenges
- Cross-certification complexity:FDA dual-use pathways for industrial detector designs create timeline friction when medical-grade components cross-pollinate equipment lines.
- Legacy system integration:Field operators face technical debt when retrofitting battery-powered portable units into existing film-based inspection workflows.
- Remote deployment logistics:Pipeline inspection applications require hazardous environment certification and complex mobilization protocols that strain operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Radiography Testing Market |
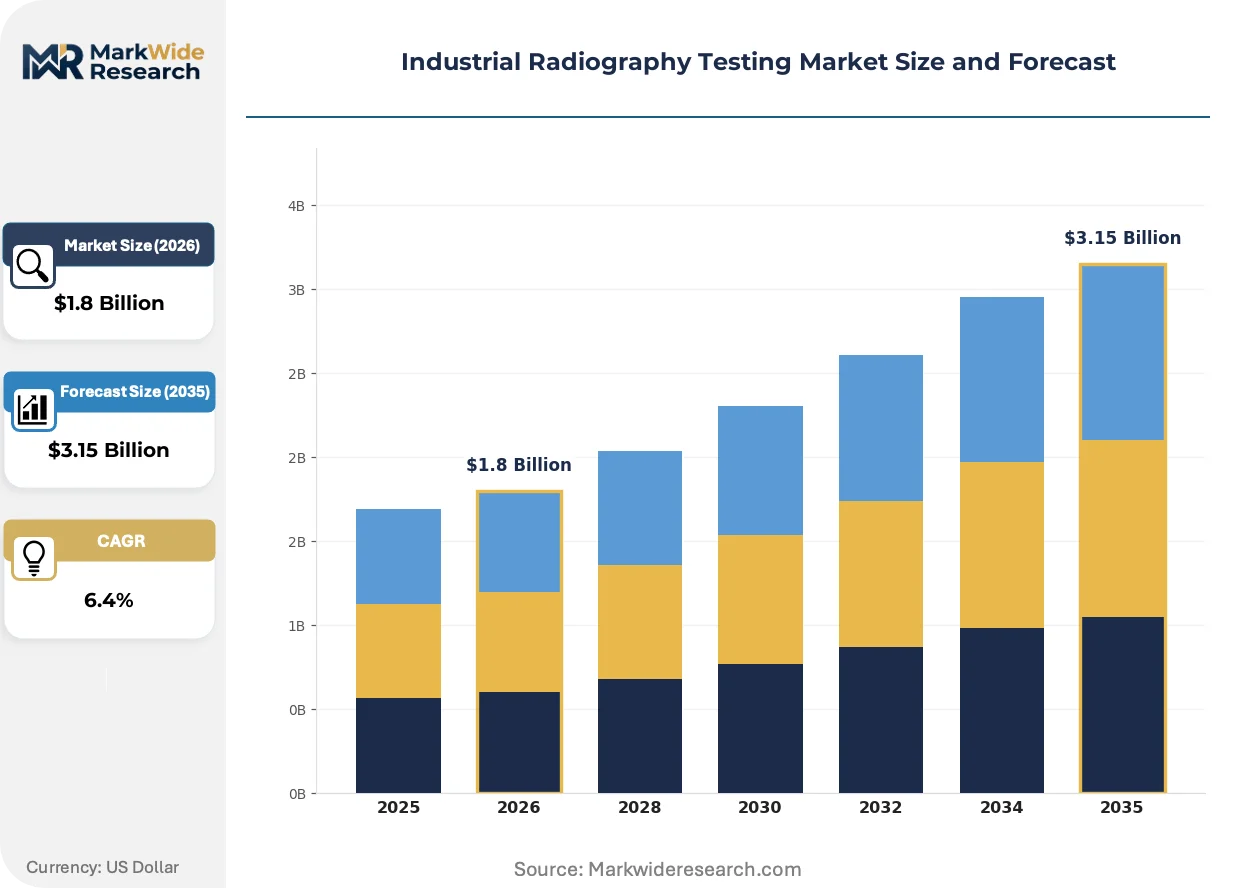
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-Ray, Gamma Ray, Computed Radiography, Digital Radiography Application: Weld Inspection, Casting Inspection, Pipeline Inspection, Aerospace Component Testing End User: Manufacturing, Oil & Gas, Aerospace, Construction Equipment Type: Film-Based Equipment, Digital Detectors, Portable Systems, Automated Systems |
| Companies Covered | COMET Holding AG, North Star Imaging Inc., Waygate Technologies GmbH, YXLON International GmbH, General Electric Company, Nikon Corporation, Baker Hughes Company, Shimadzu Corporation, Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Radiography Testing Market Shifts & Advancements
Real-time imaging capabilities and automated interpretation tools are compressing inspection timelines and reshaping how operators prioritize capital deployment across field and laboratory settings.
Portable X-ray generator technology is miniaturizing. Battery-powered units now achieve 300 kV output in sub-25 kg form factors. Offshore construction contractors in Norway and the United Kingdom are adopting these systems for platform weld verification. Equipment procurement is shifting toward field-mobility specifications over laboratory precision metrics.
EU AI Act algorithmic transparency requirements are reaching industrial imaging software. Automated defect recognition systems must now document training data provenance and decision thresholds. German inspection service providers are restructuring quality assurance protocols to meet conformity assessment obligations. This regulatory friction slows AI deployment but creates first-mover advantage for vendors with pre-certified platforms.
After-sales service unbundling is fragmenting long-term vendor relationships. Large aerospace contractors in France and the United States are separating hardware procurement from maintenance contracts and software licensing. Third-party calibration laboratories in Toulouse and Seattle are capturing recurring revenue previously retained by original equipment manufacturers. This disintermediation pressures vendor margin structures while expanding buyer negotiating leverage.
Industrial Radiography Testing Market Segmentation
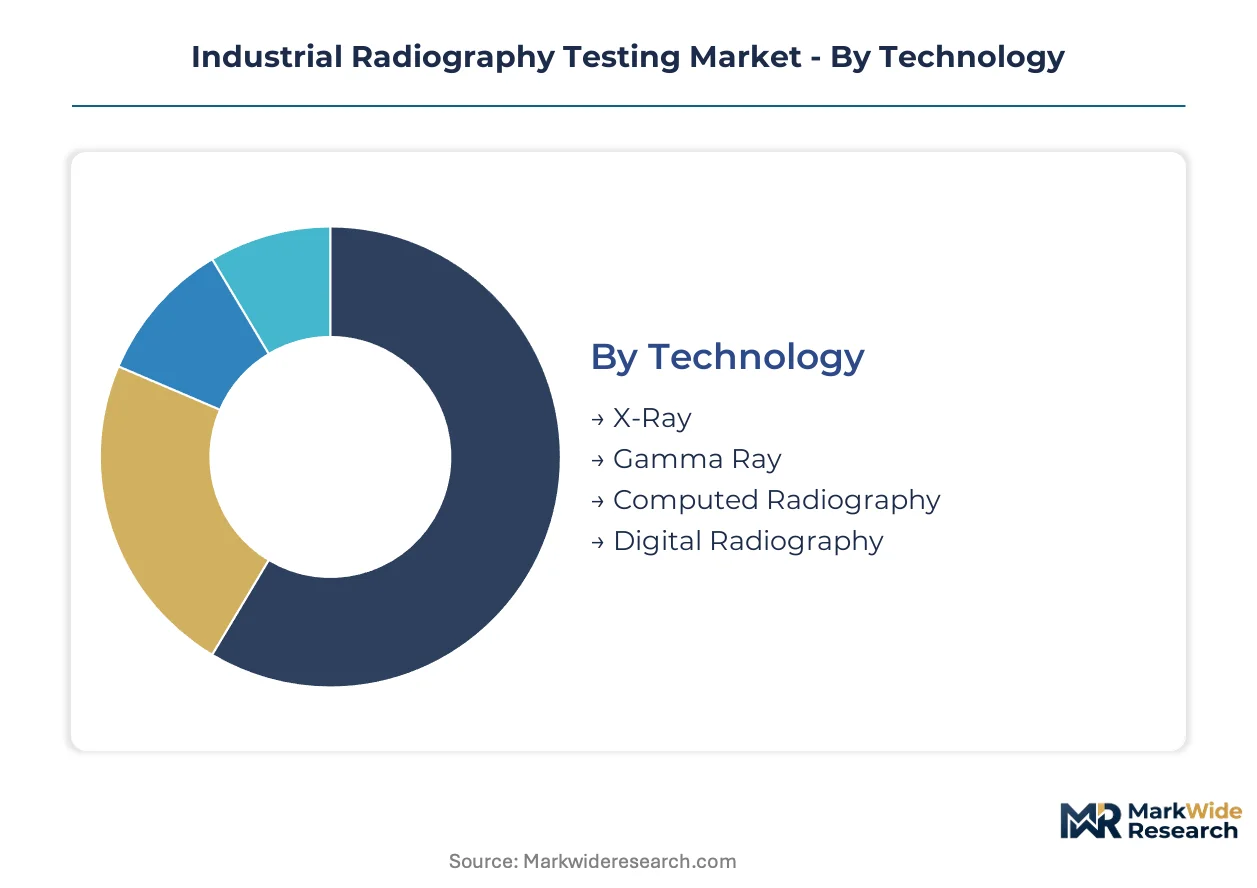
Technology and application boundaries in industrial radiography testing determine equipment procurement cycles, regulatory compliance pathways, and service provider specialization. Each segmentation axis reveals distinct margin structures and competitive dynamics that shape vendor positioning and buyer negotiation leverage.
Technology:
Channel mix varies sharply by technology type, with digital formats flowing through specialized NDT distributors while gamma sources require licensed radiotracer handlers with nuclear regulatory clearance.
- X-Ray:Tube-based systems generating 10–450 kV penetrate metallic substrates with adjustable energy levels for varying material thicknesses. Demand concentrates in German automotive supply chains where Baden-Württemberg precision engineering clusters require high-throughput weld verification protocols under ISO 17636-1.
- Digital Radiography:Flat-panel detectors deliver real-time imaging below 50 micrometers, eliminating chemical processing delays. Aerospace manufacturers in France and the United States are prioritizing this technology for turbine blade integrity programs, compressing replacement cycles for aging film installations.
- Gamma Ray:Iridium-192 and cobalt-60 isotopes penetrate thick-walled pipeline segments where X-ray tubes lack sufficient energy. Sourcing depends on concentrated nuclear fuel cycle facilities, creating radiotracer availability constraints.
- Computed Radiography:Photostimulable phosphor plates bridge analog and digital workflows, serving operators transitioning from film without full detector array investment. Construction contractors in Norway favor this intermediate tier for platform weld verification.
Digital radiography dominates installed base expansion. X-ray retains the largest legacy equipment population.
Application:
Cost tier stratification separates premium pipeline inspection from standard casting verification, with hazardous environment certification commanding substantial price premiums.
- Pipeline Inspection:Offshore and subterranean deployment requires EPA-compliant source security infrastructure and remote mobilization protocols. Gulf of Mexico operators are adopting drone-mounted platforms to access hazardous environments without technician exposure.
- Weld Inspection:ASME Section V mandates govern North American procedures, while European jurisdictions follow ISO 17636-1. German automotive suppliers in Bavaria drive high-volume procurement for supply chain quality assurance.
- Aerospace Component Testing:Turbine blade integrity programs demand resolution thresholds below 50 micrometers with full audit trails. FAA and EASA certification requirements create dual regulatory compliance burdens for multinational suppliers.
- Casting Inspection:Foundry applications prioritize throughput over resolution, favoring computed radiography for cost-sensitive volume operations. Italian and Spanish metal casting clusters represent concentrated demand pockets.
Pipeline inspection captures premium pricing tiers. Weld inspection represents the broadest volume base.
End User:
Customer type determines procurement authority concentration, with oil and gas majors centralizing NDT spend through integrated service contracts while manufacturing fragments across tiered supplier networks.
- Oil & Gas:Offshore platform operators in the United Kingdom and Norway specify battery-powered portable units for construction site mobility. North Sea decommissioning programs are expanding radiography deployment for structural integrity assessment.
- Aerospace:Turbine engine manufacturers in France and the United States maintain captive NDT capabilities with dedicated digital detector arrays. Supply chain qualification requirements extend radiography mandates to sub-tier forging suppliers.
- Manufacturing:Automotive and general fabrication demand spans portable and fixed installations, with German precision engineering clusters setting equipment specifications adopted across European supplier networks.
- Construction:Infrastructure and commercial building inspection favors rental and service models over capital purchase, with French and Spanish contractors outsourcing radiography to specialized NDT service providers.
Oil and gas concentrates capital expenditure authority. Manufacturing fragments across the largest number of discrete buyers.
Equipment Type:
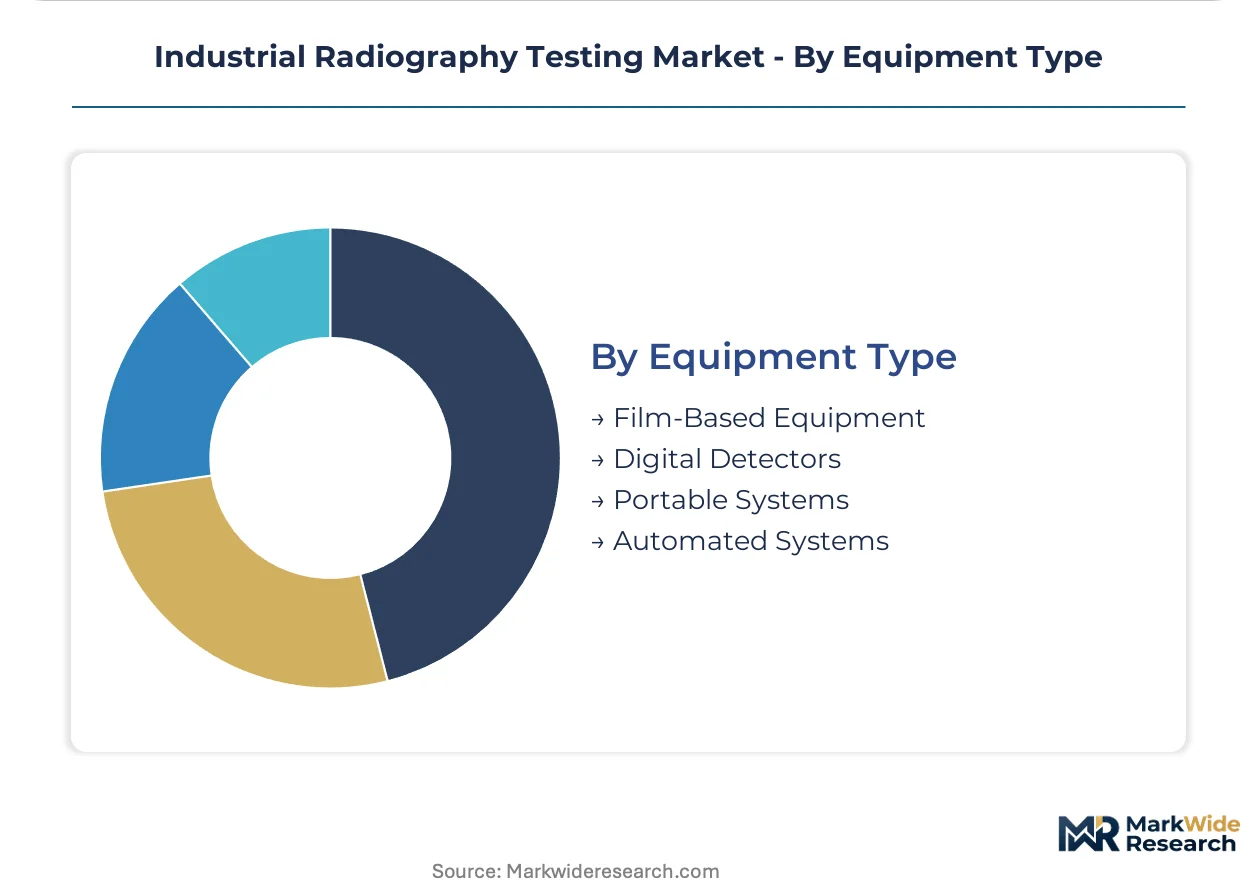
Supply concentration sits with digital detector manufacturers, while portable system assembly fragments across battery technology and X-ray tube integrators.
- Portable Systems:Battery-powered generators achieving 300 kV in sub-25 kg form factors enable offshore and construction site mobility. Norwegian platform contractors are specifying these units for platform weld verification in North Sea environments.
- Digital Detectors:Flat-panel arrays with real-time imaging below 50 micrometers displace film in new procurement. ASME and ISO standard transitions are accelerating replacement demand from aging analog installations.
- Film-Based Equipment:Analog processing persists in legacy infrastructure and regulatory-conservative jurisdictions, though procurement has shifted to maintenance and consumables rather than new system sales.
- Automated Systems:Robotic deployment and conveyor-integrated inspection serve high-volume manufacturing lines, with German automotive suppliers adopting these configurations for paint shop and body-in-white verification.
Portable systems are climbing the fastest. Digital detectors command the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters deploy digital radiography at higher penetration rates than North American aerospace facilities, while Gulf of Mexico offshore operators pioneer drone-mounted deployment for hazardous environment access.
Germany
Automotive supply chains in Baden-Württemberg and Bavaria drive high-volume weld inspection procurement under ISO 17636-1 mandates. The KBA enforces strict quality assurance protocols for supplier network certification. Stuttgart-based precision engineering clusters are transitioning entire inspection fleets from film-based systems to digital detector arrays.
United States
Aerospace manufacturers in Washington and California are expanding turbine blade integrity programs with ASME Section V compliance requirements. The FAA coordinates with EPA on source security for gamma isotope transport. Gulf of Mexico offshore contractors in Louisiana are adopting battery-powered portable units for platform construction verification.
France
Turbine engine manufacturers in Île-de-France maintain captive NDT capabilities with dedicated digital detector portfolios. The ANSM oversees dual-use certification pathways when medical-grade components cross-pollinate industrial designs. Toulouse-based aerospace suppliers are unbundling after-sales service contracts from hardware procurement.
United Kingdom
North Sea decommissioning programs in Aberdeen and Scottish coastal zones are expanding radiography deployment for structural integrity assessment. The country's nuclear regulator enforces exposure limit compliance for offshore gamma source operations. Norwegian-British joint ventures are specifying sub-25 kg portable generators for platform weld verification.
Japan
Semiconductor and electronics validation workflows in Tokyo and Osaka metropolitan areas demand high-resolution micro-focus X-ray systems. METI standards govern industrial detector performance benchmarks. Kyoto-based precision manufacturers are integrating automated defect recognition software under emerging algorithmic transparency requirements.
Industrial Radiography Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the industrial radiography testing equipment landscape. The upper tier commands pricing power through captive digital detector technology and established ASME certification pathways. Mid-scale specialists compete on field-mobility specifications and regional service density. Consolidation pressure is intensifying as equipment replacement cycles compress and after-sales service unbundling fragments long-term vendor relationships.
Among diversified industrial technology conglomerates, General Electric Company and Baker Hughes Company occupy positions spanning energy and aerospace inspection verticals. Nikon Corporation exemplifies the precision optics archetype, leveraging imaging heritage into micro-focus X-ray system development. Waygate Technologies GmbH represents the European specialist tier with concentrated presence in German automotive supply chain certification workflows.
| Leading Market Players |
|---|
| COMET Holding AG |
| North Star Imaging Inc. |
| Waygate Technologies GmbH |
| YXLON International GmbH |
| General Electric Company |
| Nikon Corporation |
| Baker Hughes Company |
| Shimadzu Corporation |
| Fujifilm Holdings Corporation |
| Others |
Supply & Pricing Matrix
Digital detector array substitution for analog film processing simultaneously concentrates supply geography among flat-panel manufacturers in Japan and Germany while compressing pricing power for legacy equipment vendors dependent on chemical consumables revenue streams. This technological displacement rewards ASME-certified system integrators with premium positioning while eroding margins for film processing service providers across North American and European inspection markets.
Pricing Analysis
Long-term offtake contracts dominate equipment procurement between aerospace manufacturers and digital detector suppliers, insulating premium tier pricing from spot-market volatility while project-based spot purchasing governs portable system rentals in construction and offshore segments. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified turbine blade inspection systems from ISO 17636-1 compliant weld verification units and non-certified foundry equipment. Cost compression in the standard tier is intensifying because battery technology commoditization enables new Asian entrants to undercut European incumbents on portable generator pricing. Oil and gas contractors demonstrate highest price sensitivity due to capital budget cyclicality, while aerospace captives show lowest sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Strait of Malacca transit underwrites rare earth element supply for scintillator crystals in flat-panel detectors, creating vulnerability to maritime disruption that ripples through German and Japanese detector assembly lines. Manufacturing concentrates in Japan, Germany, and the United States for precision X-ray tubes and digital detector arrays, while gamma isotope sourcing draws from Russian and South African nuclear fuel cycle facilities. Single-source vulnerability pervades iridium-192 supply given reactor concentration in limited jurisdictions. Distribution runs through specialized NDT equipment distributors with nuclear regulatory licensing rather than general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital radiography adoption represents a high-growth disruption justified by EU AI Act algorithmic transparency requirements that will disqualify non-compliant inspection software from European aerospace supply chains. This regulatory inflection compresses vendor consolidation timelines while elevating first-mover advantage for pre-certified platform developers.
For Market Incumbents: Consolidate digital detector technology portfolios through captive supply arrangements with Japanese scintillator manufacturers, defending against margin erosion from battery-powered portable system commoditization. Prioritize backward integration into AI-assisted defect recognition software to capture recurring licensing revenue as aerospace contractors unbundle after-sales service contracts. For New Entrants and Emerging Players: Differentiate on drone-mounted radiography deployment for North Sea and Gulf of Mexico offshore pipeline inspection, where hazardous environment access barriers protect pricing power from established terrestrial competitors. Target Norwegian platform decommissioning programs with unmanned aerial systems that eliminate technician exposure liability. Pursue direct contracting relationships with national oil companies rather than competing for integrated service provider vendor status. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors vertically integrated equipment manufacturers with captive detector technology and established ASME certification pathways. Long-term viability hinges on software-enabled recurring revenue streams rather than hardware shipment cyclicality. Monitor AI Act conformity assessment completion rates among German inspection service providers as the definitive inflection signal for platform consolidation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Detector Array Certification | ASME Section V compliance unlocks aerospace procurement pipelines in Washington and California manufacturing clusters. |
| AI-Assisted Defect Recognition Development | Machine learning algorithms reduce interpreter training investment while meeting EU algorithmic transparency mandates. |
| Drone-Mounted Radiography Deployment | Unmanned aerial platforms access hazardous offshore environments without EPA exposure limit compliance burdens. |
| After-Sales Service Unbundling | Third-party calibration laboratories in Toulouse and Seattle capture recurring revenue from OEM relationships. |
| Gamma Isotope Supply Security | Long-term offtake agreements with nuclear fuel cycle facilities mitigate iridium-192 availability constraints. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with NDT service provider operations directors, aerospace quality assurance managers, and nuclear regulatory compliance officers, alongside secondary validation through ASME Section V documentation, ISO 17636-1 technical standards, EPA source security filings, and EU AI Act regulatory texts. Bottom-up equipment shipment data triangulated against top-down inspection service revenue estimates across German automotive, United States aerospace, and United Kingdom oil and gas verticals.
Across the analysis window, the forecasting framework modeled technology substitution dynamics, application penetration rates, and end-user procurement authority concentration with segmentation across X-ray, digital radiography, gamma ray, and computed radiography modalities. CAGRs derived from equipment replacement cycle compression analysis and regulatory mandate implementation timelines, incorporating battery technology cost curves and AI software licensing trajectory assumptions specific to industrial imaging applications.
Forecasts assume regulatory continuity in EPA source security enforcement and EU AI Act algorithmic transparency regimes; material policy shifts would require re-modeling radiotracer availability and software deployment timelines. Practitioners should keep alternative scenarios live as gamma isotope supply geopolitics and semiconductor detector input cost volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Home Care Testing Market
Testing Services
Dengue Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Allergy Skin Test Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
Toxicity Testing Outsourcing Market