
 Companion Animal Ear Infection Treatment Market | 2026-2036
Companion Animal Ear Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Ear Infection Treatment Market Intelligence
The veterinary clinic channel is rewriting how ear infection treatments reach end users, with in-house dispensing displacing traditional retail pharmacy fulfillment. Zoetis Inc. leverages its direct-to-clinic logistics network to sustain refill loyalty among small animal practitioners. Dechra Pharmaceuticals PLC anchors its position through specialized otic formulation expertise that competes with broader-spectrum portfolios. Boehringer Ingelheim Vetmedica GmbH differentiates via integrated diagnostic-treatment protocols that extend clinician engagement beyond single prescriptions.
Companion animal ear infection treatment encompasses pharmaceutical and non-pharmaceutical interventions designed to resolve otitis externa, media, and interna in dogs and cats, typically formulated as low-viscosity aqueous or oil-based suspensions with pH buffers between 6.5 and 7.5 to preserve epithelial integrity. These products function therapeutically to eliminate microbial pathogens, reduce inflammatory mediators, and restore cerumen balance while serving prophylactically in breeds predisposed to recurrent disease. Topical solutions and ear drops dominate current volume due to established efficacy against Pseudomonas and Malassezia pathogens, though medicated wipes are gaining traction for maintenance protocols between acute episodes. Antibiotic treatments retain the largest margin pool where polymyxin-fluoroquinolone combinations command premium positioning, while herbal remedies occupy a nascent but expanding niche among owner-driven preventive care segments.
The FDA Center for Veterinary Medicine and the United States Pharmacopeia Veterinary Medicines Expert Committee jointly govern otic drug manufacturing standards, ingredient purity thresholds, and label claims that determine which formulations achieve commercial distribution. State veterinary practice acts further constrain retail channel access by restricting prescription fulfillment to licensed veterinarians or their supervised dispensaries. Stakeholders must monitor evolving compounding pharmacy enforcement priorities and telemedicine prescribing rules that could reroute demand between clinical and direct-to-consumer channels.
Market Dynamics
Veterinary clinics are consolidating dispensing power through in-house pharmacy expansion, redirecting ear infection treatment fulfillment away from retail channels and toward direct clinician-controlled distribution networks.
Growth Catalysts
- Pet insurance penetration:Rising coverage rates in the United States reduce out-of-pocket treatment costs, accelerating specialty referral uptake for recurrent otitis cases.
- FDA Center for Veterinary Medicine oversight:Stringent active ingredient standards elevate formulation quality, creating barriers that protect incumbent manufacturers with proven compliance records.
- Telemedicine prescribing frameworks:Evolving state veterinary practice acts enable remote consultation models that expand access to prescription otic therapies.
Market Restraints
- API supply concentration:Reliance on Chinese and Indian bulk pharmaceutical chemical manufacturers exposes formulators to import volatility and quality verification delays.
- Compounding pharmacy enforcement:FDA scrutiny of non-standardized otic preparations limits alternative sourcing options for cost-sensitive practitioners.
- Antimicrobial resistance protocols:Veterinary stewardship guidelines restrict fluoroquinolone utilization, compressing the addressable market for premium antibiotic combinations.
Strategic Opportunities
- Maintenance protocol segmentation:Medicated wipes and cerumenolytic cleaners for brachycephalic breeds represent an underdeveloped preventive care category.
- Specialty referral network density:Dermatology-focused veterinary clinics in metropolitan Texas and Florida clusters concentrate high-value recurrent case volume.
- Herbal formulation certification:NASC quality seals and state veterinary board endorsements create differentiation pathways for botanical ear care entrants.
Industry Challenges
- Formulation stability expertise:pH buffering and suspension viscosity optimization require specialized pharmaceutical development capabilities scarce in generic manufacturers.
- Multi-species label expansion:Feline otitis externa indications demand separate safety and efficacy trials, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Ear Infection Treatment Market |
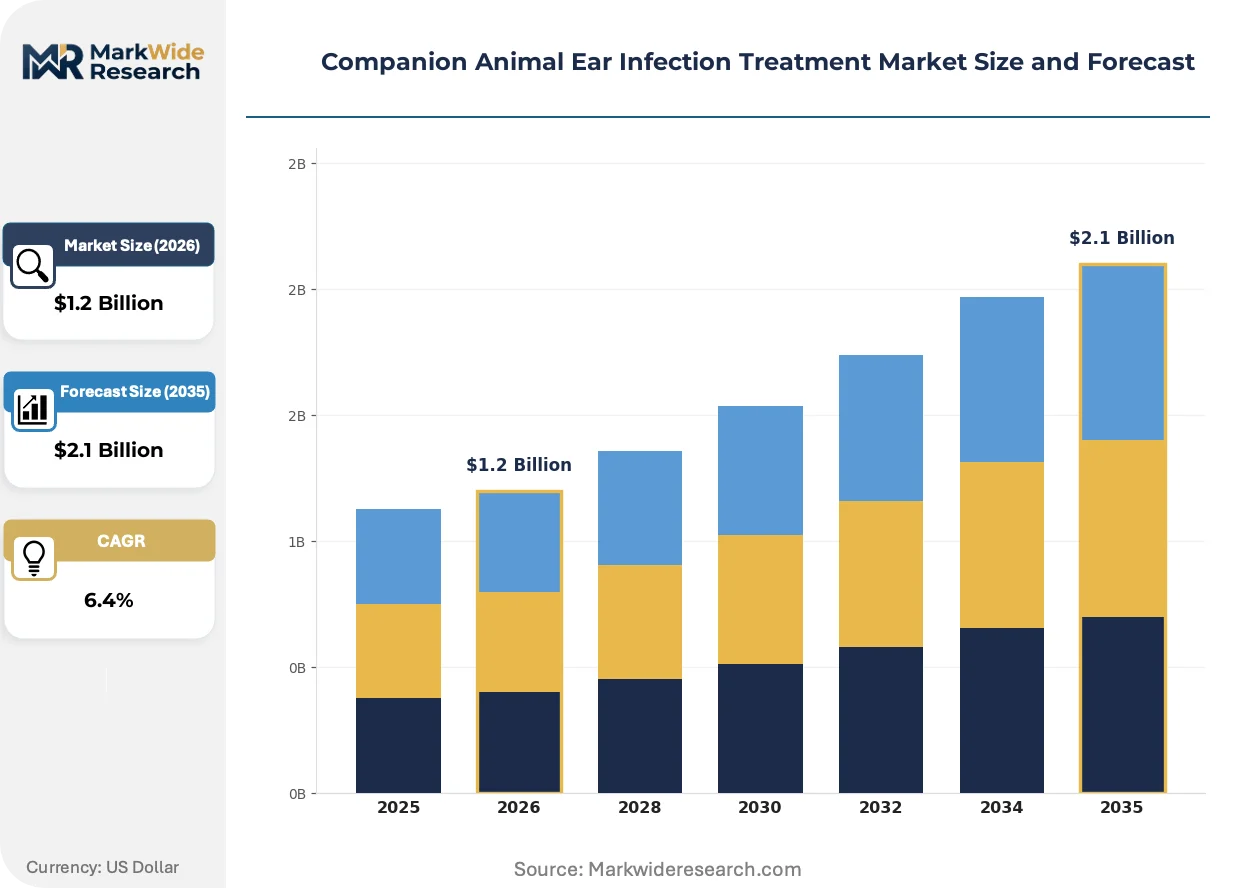
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solutions, Ear Drops, Ointments, Medicated Wipes Technology: Antibiotic Treatments, Antifungal Treatments, Antiseptic Solutions, Herbal Remedies Application: Veterinary Clinics, Pet Pharmacies, Online Retail, Animal Hospitals End User: Pet Owners, Veterinarians, Animal Shelters, Breeders |
| Companies Covered | Zoetis Inc., Dechra Pharmaceuticals PLC, Elanco Animal Health, Boehringer Ingelheim Vetmedica GmbH, Merck & Co., Inc., Virbac, Vetoquinol, Ceva Santé Animale, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Ear Infection Treatment Market Strategic Shifts & Innovations
Diagnostic integration is compressing the interval between pathogen identification and targeted therapy selection, reshaping how clinicians match antimicrobial spectra to culture results.
Polymerase chain reaction-based pathogen detection is rendering obsolete empiric broad-spectrum antibiotic prescribing in university-affiliated veterinary teaching hospitals. Specialist practices in California and New York are adopting rapid Malassezia speciation panels within eighteen months of commercial availability. This precision-matching capability is rendering obsolete the historical reliance on polymyxin-based cocktails as first-line therapy.
The FDA Center for Veterinary Medicine's revised otic drug bioequivalence guidance tightens comparability standards for generic entrants. Manufacturers must now demonstrate equivalent tissue distribution profiles rather than simple plasma pharmacokinetic matching. This regulatory elevation most affects mid-tier generic sponsors attempting entry against established fluoroquinolone-suspension franchises.
Subscription-based preventive care bundles are restructuring how pet owners budget for chronic ear maintenance. Veterinary clinic chains in the southeastern United States are unbundling acute treatment from ongoing cerumen management, replacing episodic purchase patterns with recurring revenue arrangements. This model shift concentrates lifetime value capture within clinic-operated dispensing channels.
Companion Animal Ear Infection Treatment Market Segmentation
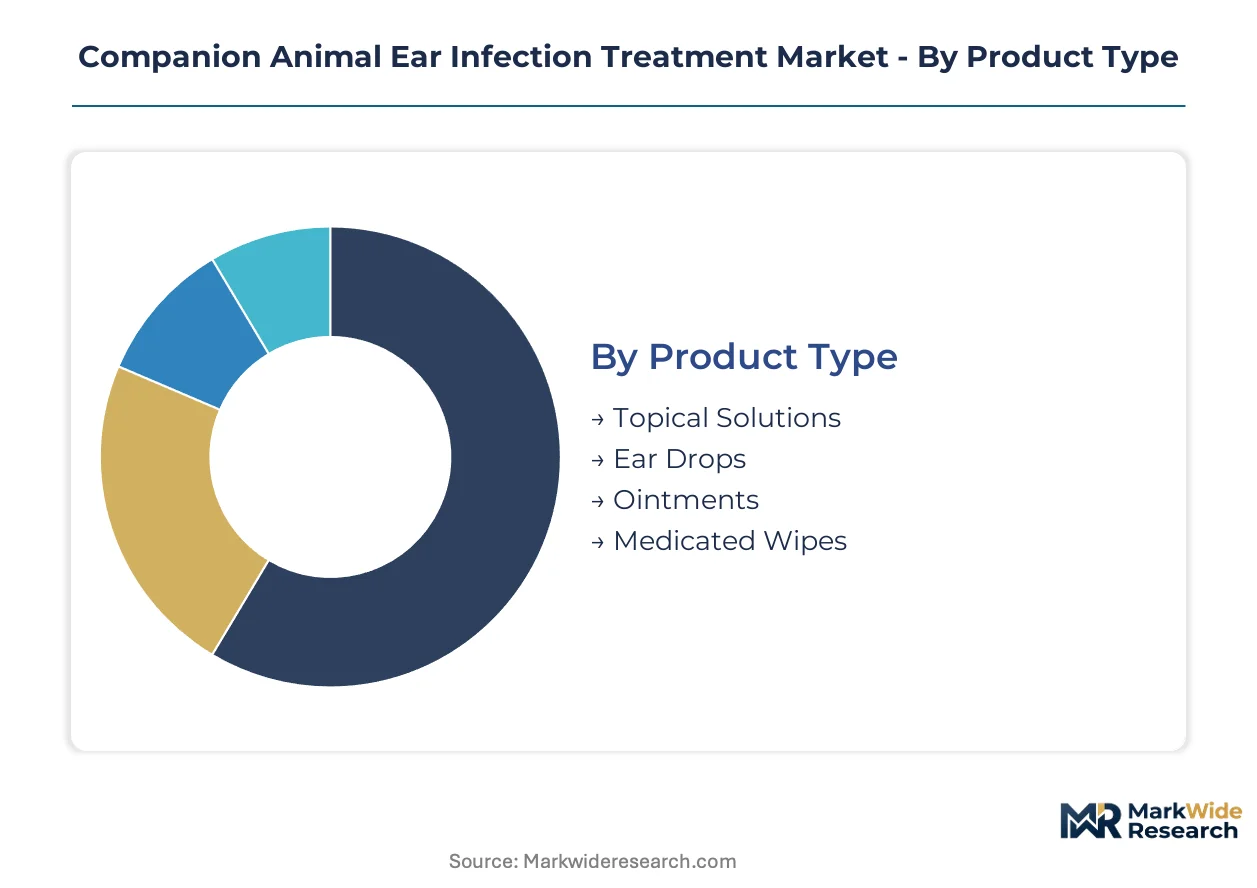
Ear infection treatment purchasing cycles vary dramatically across product formats, with acute therapies turning over weekly versus maintenance protocols stretching to quarterly replenishment. Understanding velocity differentials helps manufacturers align inventory positioning with channel-specific consumption patterns.
Product Type:
Cycle times compress from viscous ointments requiring monthly application through aqueous drops dosed twice daily, creating distinct replenishment rhythms that shape distributor stocking priorities.
- Topical Solutions:Low-viscosity aqueous or oil-based suspensions with pH buffers between 6.5 and 7.5 preserve epithelial integrity during repeated application. Veterinary clinics in Florida and Texas metropolitan clusters dispense these as first-line therapy for Pseudomonas-driven otitis externa, with refill frequency accelerating during humid summer months.
- Ear Drops:Precision-tip delivery systems enable deep canal penetration for media-level infections requiring antimicrobial concentration at the tympanic membrane. Demand concentrates in specialty dermatology referral practices where culture-directed therapy protocols mandate narrow-spectrum agent selection.
- Ointments:Semisolid petrolatum-based vehicles provide prolonged contact time for feline patients resistant to liquid instillation.
- Medicated Wipes:Pre-saturated pads for inter-episode maintenance in brachycephalic breeds extend treatment intervals to 60-90 days.
Topical solutions anchor the volume base while medicated wipes gain share at the steepest rate.
Technology:
Cost tiers separate patented combination therapies from commodity antiseptics, with reimbursement elasticity determining uptake across insured versus cash-pay patient populations.
- Antibiotic Treatments:Polymyxin-fluoroquinolone combinations command premium positioning through demonstrated efficacy against resistant Pseudomonas isolates. Pet insurance penetration in the United States reduces out-of-pocket friction for these high-margin prescriptions.
- Antifungal Treatments:Azole and polyene formulations target Malassezia pachydermatis overgrowth in allergic otitis cases. Rapid speciation panel adoption in California and New York specialist practices is displacing empiric broad-spectrum prescribing.
- Antiseptic Solutions:Chlorhexidine and acetic acid preparations serve as cost-conscious alternatives for initial cleansing protocols.
- Herbal Remedies:Botanical formulations with NASC quality seals occupy preventive care niches among owner-driven wellness segments.
Antibiotic treatments dominate margin capture while herbal remedies expand most quickly among preventive care adopters.
Application:
Customer type fragmentation splits between clinician-controlled dispensing and direct-to-consumer channels, with state veterinary practice acts determining prescription fulfillment access points.
- Veterinary Clinics:In-house pharmacy expansion captures recurring otitis cases through subscription-based preventive care bundles. Southeastern United States clinic chains unbundle acute treatment from ongoing cerumen management, converting episodic purchases to recurring revenue.
- Pet Pharmacies:Traditional retail fulfillment faces displacement as veterinarians retain dispensing control.
- Online Retail:Telemedicine prescribing frameworks enable remote consultation models that expand access to prescription therapies.
- Animal Hospitals:University-affiliated teaching hospitals adopt PCR-based pathogen detection, compressing intervals between diagnosis and targeted therapy.
Veterinary clinics concentrate lifetime value capture while online retail climbs the fastest as telemedicine regulations mature.
End User:
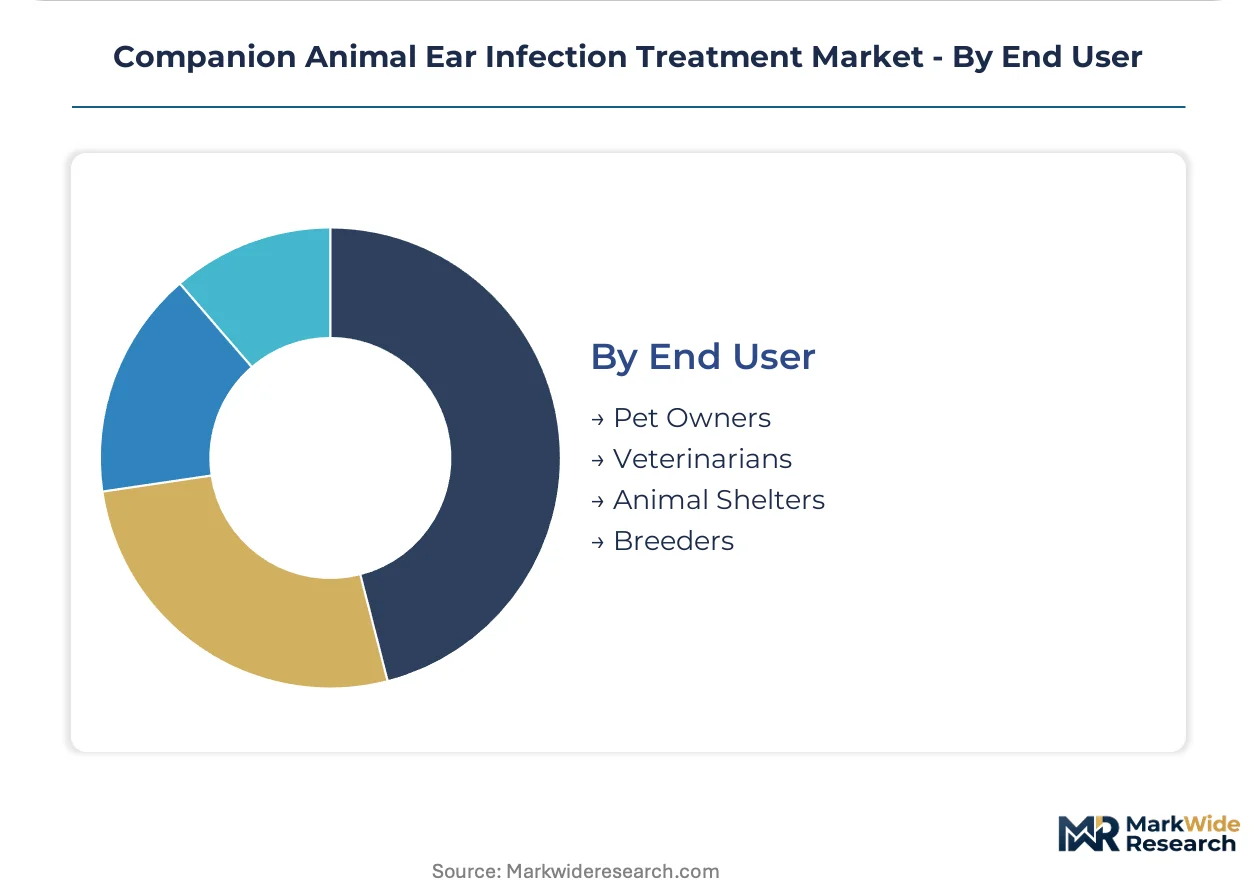
Volume concentration versus margin extraction diverges across professional and consumer purchasers, with clinical expertise mediating product selection complexity.
- Pet Owners:Insurance coverage reduces cost sensitivity for recurrent cases, enabling specialty referral uptake. Brachycephalic breed owners in metropolitan Texas and Florida drive maintenance protocol adherence.
- Veterinarians:Dermatology specialists command premium pricing for culture-directed therapy protocols.
- Animal Shelters:Cost constraints favor generic antiseptic solutions for intake screening protocols.
- Breeders:Prophylactic cerumenolytic use in predisposed lineages supports preventive care bundle adoption.
Pet owners provide the volume foundation while veterinarians extract the highest per-case value through specialist positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium treatment pricing in the United States exceeds reimbursement-adjusted rates in Germany by approximately forty percent, creating a transatlantic margin asymmetry that shapes manufacturer portfolio prioritization.
United States
Pet insurance penetration and specialty dermatology referral networks concentrate demand for culture-directed therapy protocols. The FDA Center for Veterinary Medicine maintains stringent active ingredient standards that elevate formulation quality barriers. Metropolitan Texas and Florida clusters anchor recurrent otitis case volume, with Houston and Miami dermatology practices driving premium antibiotic combination uptake.
Germany
Veterinary clinic consolidation and in-house pharmacy expansion redirect fulfillment toward clinician-controlled channels. The German Federal Institute for Drugs and Medical Devices enforces bioequivalence standards that protect incumbent manufacturers. Bavaria and North Rhine-Westphalia host the densest specialty referral networks, where PCR-based pathogen detection compresses diagnosis-to-treatment intervals.
United Kingdom
Telemedicine prescribing frameworks and evolving Royal College of Veterinary Surgeons guidelines expand remote consultation access to prescription otic therapies. The Veterinary Medicines Directorate oversees manufacturing standards and import verification protocols. Greater London and Southeast England concentrate dermatology specialist practices that command premium pricing for targeted antimicrobial selection.
France
Brachycephalic breed ownership in urban centers drives preventive care bundle adoption for maintenance protocols. ANSM maintains oversight of veterinary pharmaceutical ingredient purity and label claim verification. The Île-de-France region anchors both specialist referral density and pet insurance policy concentration, supporting recurring revenue arrangements for chronic ear management.
Japan
Feline otitis externa indications and multi-species label expansion requirements extend product development timelines for entrants. The Ministry of Agriculture, Forestry and Fisheries and PMDA jointly govern veterinary drug approval pathways. The Kanto region surrounding Tokyo concentrates university-affiliated teaching hospitals adopting rapid Malassezia speciation panels.
Companion Animal Ear Infection Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in formulation and active pharmaceutical ingredient supply. The market structure consolidates around diversified animal health conglomerates with direct-to-clinic logistics networks, while mid-tier generic sponsors face tightening bioequivalence barriers. Three archetypes dominate: integrated pharmaceutical platforms with veterinary-specific distribution, specialized otic formulation developers, and regional generic manufacturers with cost-positioned antiseptic portfolios. Competitive moves concentrate on M&A to capture clinic dispensing channels and strategic partnerships for diagnostic-therapy integration.
Within the integrated platform tier, Zoetis Inc. and Boehringer Ingelheim Vetmedica GmbH exemplify archetypes combining direct distribution infrastructure with broad-spectrum portfolios. Dechra Pharmaceuticals PLC occupies a position representing specialized otic formulation expertise that competes against more diversified offerings. These three entities anchor competitive dynamics through contrasting approaches to clinician engagement and channel control.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Dechra Pharmaceuticals PLC |
| Elanco Animal Health |
| Boehringer Ingelheim Vetmedica GmbH |
| Merck & Co., Inc. |
| Virbac |
| Vetoquinol |
| Ceva Santé Animale |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
API supply concentration in Chinese and Indian bulk pharmaceutical chemical manufacturers exposes formulators to import volatility that widens spreads between premium patented combinations and commodity antiseptic tiers while compressing margins for mid-tier generic sponsors lacking captive sourcing. This dependency structure forces pricing stratification across premium, standard, and economy tiers based on formulation complexity and regulatory certification depth rather than raw material cost alone.
Pricing Analysis
The customization-premium spread separates culture-directed polymyxin-fluoroquinolone combinations from empiric broad-spectrum cocktails, with pet insurance penetration reducing out-of-pocket friction for high-margin prescriptions. Price differentiation rests on FDA Center for Veterinary Medicine approval status and NASC quality certification for botanical entrants. Cost compression in generic antiseptic tiers is intensifying because compounding pharmacy enforcement limits alternative sourcing. Cash-pay pet owners in animal shelters exhibit highest price sensitivity; insured owners of brachycephalic breeds show lowest.
Supply Chain Analysis
Upstream feedstock for active pharmaceutical ingredients draws from China, India, and domestic United States fermentation facilities, with polymyxin and fluoroquinolone precursors exhibiting longest lead times. Formulation stability expertise and pH buffering chemistry rest on specialized pharmaceutical development capabilities concentrated among incumbent manufacturers. Single-source vulnerability for Pseudomonas-active APIs creates exposure to quality verification delays. Distribution runs through direct-to-clinic logistics networks displacing traditional retail pharmacy fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based preventive care bundles for brachycephalic breed maintenance expand faster than acute treatment hardware, converting episodic purchase patterns into recurring revenue arrangements that concentrate lifetime value within clinic-operated dispensing channels.
For Market Incumbents: Pre-empt generic antiseptic commoditization by securing captive API supply through backward integration into Indian and Chinese bulk chemical manufacturers. Invest in PCR-based diagnostic-therapy integration protocols before rapid Malassezia speciation panels render empiric prescribing obsolete. Channel control through in-house pharmacy expansion protects refill loyalty against telemedicine-enabled remote fulfillment. For New Entrants and Emerging Players: Establish a beachhead in medicated wipes and cerumenolytic cleaners for preventive maintenance protocols, the most penetrable segment where NASC quality seals create differentiation without FDA drug approval barriers. Target metropolitan Texas and Florida dermatology referral clusters where brachycephalic breed density supports premium pricing. Go-to-market through specialty veterinary clinic chains unbundling acute from chronic care management. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized otic formulation developers with proven FDA compliance records over diversified animal health conglomerates. Long-term viability across the projection horizon rests on diagnostic-therapy integration capabilities and direct-to-clinic logistics infrastructure. Watch for inflection when telemedicine prescribing frameworks mature sufficiently to reroute demand between clinical and direct-to-consumer channels.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapy Integration | PCR-based pathogen detection compresses diagnosis-to-treatment intervals in university-affiliated teaching hospitals. |
| Subscription Bundle Development | Preventive care arrangements convert episodic purchases to recurring revenue in southeastern United States clinic chains. |
| API Supply Backward Integration | Captive sourcing from Chinese and Indian bulk manufacturers insulates against import volatility and quality verification delays. |
| NASC Quality Certification | Botanical formulation seals differentiate herbal remedies in owner-driven wellness segments without full drug approval. |
| Telemedicine Channel Partnership | Remote consultation models expand prescription access as state veterinary practice acts evolve prescribing frameworks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine filings, state veterinary practice act amendments, and pet insurance penetration databases, combining interviews with veterinary dermatology specialists, clinic pharmacy directors, and animal health procurement managers. Secondary validation draws from United States Pharmacopeia standards documentation, compounding pharmacy enforcement records, and regional veterinary medical association prescribing surveys. Bottom-up demand modeling across product formats and top-down market sizing triangulate volume estimates.
Forecast inputs include treatment velocity differentials between acute and maintenance protocols, pet insurance policy growth trajectories, and regulatory enforcement priorities across the projection horizon. Segmentation dimensions span product type, technology tier, application channel, and end-user archetype with regional regulatory cluster overlays. CAGRs derive from weighted scenario analysis incorporating antimicrobial stewardship guideline adoption rates and telemedicine framework maturation.
Stress conditions across API import disruption, compounding pharmacy enforcement intensification, and fluoroquinolone restriction protocols were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about specialty referral network density and insurance penetration elasticity. Cross-checking against veterinary pharmaceutical distributor inventory data and clinic dispensing records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Cattle Health Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Animal Health Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Swine Health Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Companion Animal Medicine Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Animal Healthcare Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Cattle Healthcare Market
Animal Health
Swine Healthcare Market
Animal Health
Canada Animal Health Care Market
Animal Health
US Companion Animal Health Market
Animal Health
Global Companion Animal Health Market
Animal Health
Animal Blood Plasma Products and Derivatives Market