
 Bilateral Osteoarthritis Treatment Market | 2026-2036
Bilateral Osteoarthritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bilateral Osteoarthritis Treatment Market Analytics
Hyaluronic acid formulations is decoupling from corticosteroid dependency in knee osteoarthritis protocols, altering reimbursement economics for outpatient injections. Johnson & Johnson Services (DePuy Synthes) leverages its Synthes heritage to dominate orthopedic device integration. Novartis AG anchors its position through biosimilar depth in intra-articular therapy. Pfizer Inc. competes via oral NSAID portfolio breadth and chronic pain management positioning.
Bilateral osteoarthritis treatment encompasses pharmacological, interventional, and surgical modalities targeting symmetrical joint degeneration, typically involving hyaluronic acid injections with molecular weights ranging from 500 to 6,000 kDa for viscosupplementation, alongside arthroplasty systems designed for staged or simultaneous bilateral procedures. Pharmaceuticals command the largest revenue pool due to chronic prescribing patterns, while Biologics represent the fastest-expanding category as platelet-rich plasma and cell-based therapies gain procedural traction in ambulatory settings. Injectable delivery modes capture premium pricing relative to oral agents, though oral formulations sustain higher volume throughput across primary care networks.
FDA oversight of 510(k) orthopedic devices and EPA manufacturing standards for pharmaceutical production shape product development timelines and facility compliance costs. The IRA's Medicare drug pricing provisions are restructuring reimbursement expectations for chronic osteoarthritis medications. EMA's MDR requirements for implantable devices create parallel compliance obligations for multinational suppliers. Stakeholders must monitor how CMS value-based care pilots for joint replacement bundles redirect site-of-service economics toward outpatient and home-based rehabilitation models.
Market Dynamics
FDA's accelerated approval pathways for disease-modifying osteoarthritis therapies are compressing clinical development timelines and forcing hospital systems to reconfigure orthopedic service lines around earlier-stage interventions. This regulatory velocity is redistributing investment from device-centric portfolios toward pharmacological and biologic modalities.
Growth Catalysts
- IRA Medicare Pricing Provisions:The Inflation Reduction Act's drug pricing reforms are expanding patient access to chronic osteoarthritis medications, driving prescription volume through Medicare Part D channels.
- Hyaluronic Acid Molecular Engineering:Advanced viscosupplementation formulations spanning 500 to 6,000 kDa molecular weights are extending injection intervals and improving symptomatic outcomes in knee protocols.
- Ambulatory Surgery Center Expansion:United States outpatient facilities are capturing staged bilateral arthroplasty volume through CMS value-based care pilots for joint replacement bundles.
Market Restraints
- Biologic Raw Material Volatility:Platelet-rich plasma and cell-based therapy inputs face supply instability from donor variability and processing facility concentration in specific metropolitan clusters.
- EMA MDR Compliance Burden:The European Union's Medical Device Regulation imposes parallel certification obligations for implantable arthroplasty systems, extending market entry timelines for multinational suppliers.
- Oral NSAID Substitution Pressure:Chronic pain management protocols continue favoring generic oral anti-inflammatories over premium injectable modalities in primary care networks.
Strategic Opportunities
- Home-Based Rehabilitation Integration:Post-arthroplasty recovery protocols are shifting toward remote monitoring platforms, creating channel partnerships between orthopedic device manufacturers and telehealth infrastructure providers.
- Biosimilar Intra-Articular Expansion:Regulatory pathways for complex generic formulations present white space for manufacturers with biologics manufacturing depth to capture corticosteroid replacement demand.
- Simultaneous Bilateral Procedure Protocols:Anesthesia and blood management advances are enabling same-day bilateral knee replacement in select patient populations, compressing episode-of-care economics.
Industry Challenges
- Orthopedic Surgeon Workforce Constraints:Fellowship-trained joint replacement specialists remain concentrated in urban academic medical centers, limiting procedural capacity in secondary markets.
- 510(k) Predicate Device Navigation:FDA's evolving substantial equivalence standards for modified arthroplasty systems require iterative regulatory strategy adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bilateral Osteoarthritis Treatment Market |
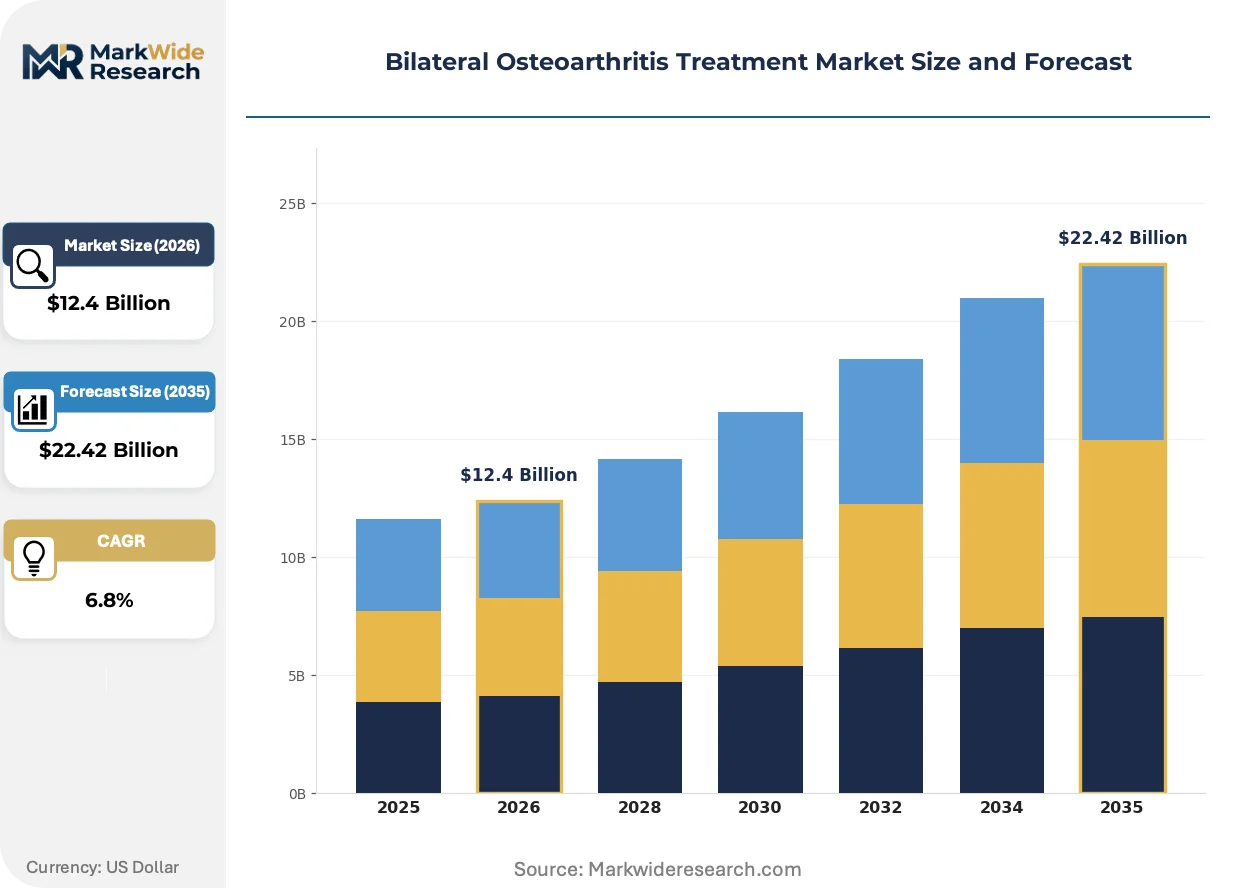
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Devices, Biologics, Supplements Therapy Area: Pain Management, Rehabilitation, Surgery, Emerging Therapies Delivery Mode: Topical, Injectable, Oral, Transdermal End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers |
| Companies Covered | Johnson & Johnson Services (DePuy Synthes), Novartis AG, GlaxoSmithKline Plc., Abbott Laboratories, Zimmer Biomet Holdings Inc., Pfizer Inc., Eli Lilly and Company, F-Hoffmann-La Roche Ltd., Amgen Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bilateral Osteoarthritis Treatment Market Evolving Landscape
Pharmacological, interventional, and surgical modalities for symmetrical joint degeneration are converging around patient-specific selection algorithms that match molecular therapy profiles to radiographic staging. This integration is dissolving traditional boundaries between rheumatology and orthopedic care pathways.
Next-generation hyaluronic acid crosslinking chemistry is unifying viscosupplementation durability with corticosteroid-level onset speed. Academic medical centers in the United States are piloting these formulations in mixed-injection protocols. The technology is unifying outpatient injection economics by reducing visit frequency while maintaining reimbursement capture.
EPA manufacturing standards for pharmaceutical production are tightening environmental release thresholds for active pharmaceutical ingredient synthesis. Facility compliance investments are restructuring supplier economics toward captive manufacturing or qualified contractor networks. Injectable hyaluronic acid and biologic processors face the steepest cost escalations under these requirements.
Patient selection for staged versus simultaneous bilateral arthroplasty is migrating toward algorithmic risk stratification tools. Hospital systems are deploying these platforms to optimize operating room block utilization and anesthesia staffing. This behavioral shift concentrates in United States integrated delivery networks with value-based contract exposure.
Bilateral Osteoarthritis Treatment Market Segmentation
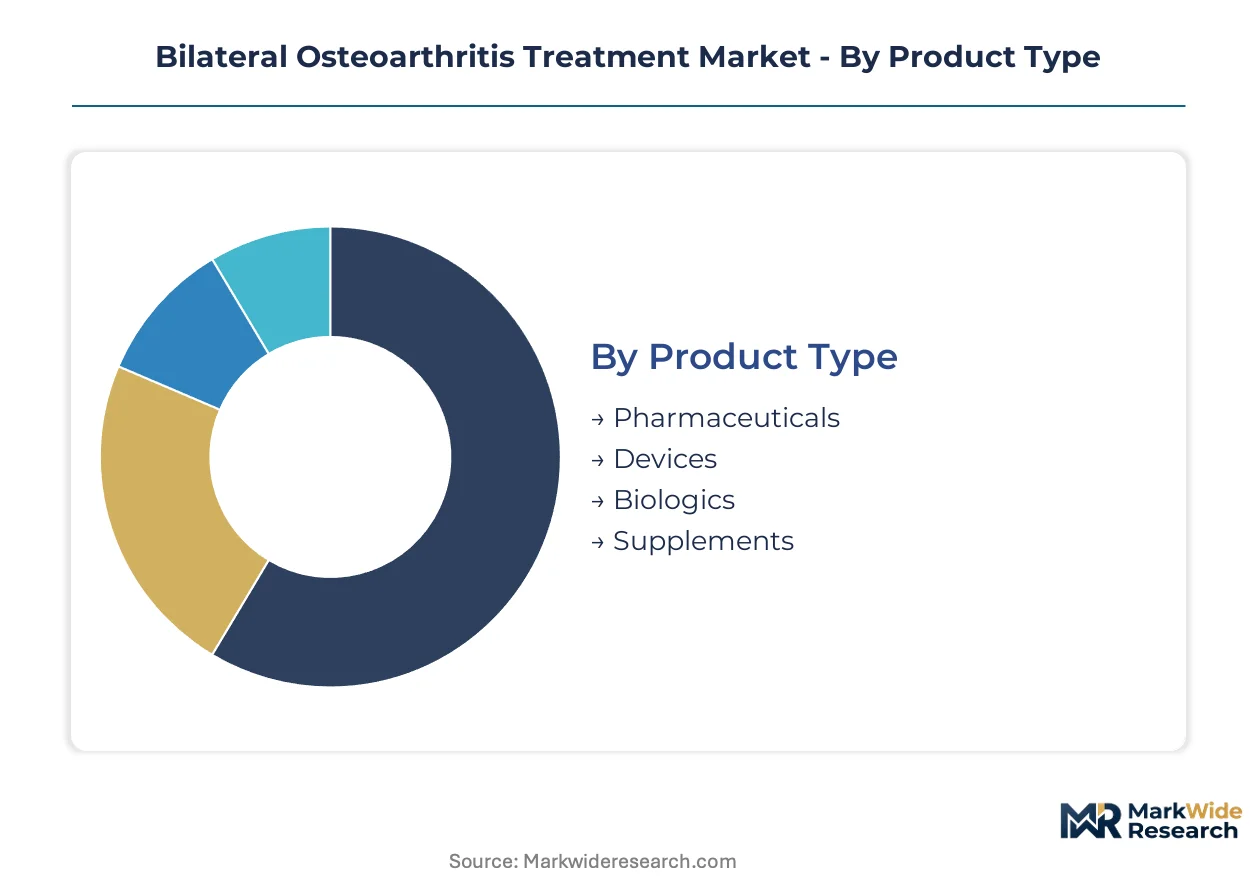
Segmentation in bilateral osteoarthritis treatment reveals how therapeutic modalities compete for episode-of-care economics across institutional and ambulatory settings. Product type and delivery mode configurations determine reimbursement capture, while therapy area specialization dictates site-of-service selection.
Product Type:
Upgrade cycles in osteoarthritis treatment are compressing as disease-modifying therapies displace legacy symptom management, forcing portfolio rebalancing across pharmaceutical, device, and biologic categories.
- Pharmaceuticals:Oral NSAIDs, corticosteroids, and analgesics dominate prescription volume through Medicare Part D channels. Chronic prescribing patterns in United States primary care networks sustain revenue concentration despite generic substitution pressure.
- Devices:Arthroplasty systems and viscosupplementation hardware command premium pricing in hospital outpatient departments. United States integrated delivery networks are consolidating procurement around single-source orthopedic device contracts to capture bundle savings.
- Biologics:Platelet-rich plasma and cell-based therapies are gaining procedural traction in ambulatory surgery centers.
- Supplements:Glucosamine and chondroitin formulations compete for over-the-counter shelf space in retail pharmacy.
Pharmaceuticals sits at the top of the volume ranking, with Biologics climbing the fastest.
Therapy Area:
Cost tier differentiation separates acute intervention from chronic management, with surgical episodes commanding tenfold reimbursement multiples over pharmacological maintenance.
- Pain Management:Multimodal protocols combining oral agents, topical formulations, and interventional injections target symptomatic relief. United States pain clinics are expanding hyaluronic acid injection capacity to capture Medicare reimbursement for viscosupplementation.
- Surgery:Arthroplasty and arthroscopy procedures concentrate in hospital systems with value-based joint replacement contracts. Staged bilateral procedures are migrating toward ambulatory surgery centers as anesthesia protocols advance.
- Rehabilitation:Post-operative physical therapy and occupational therapy extend episode-of-care economics.
- Emerging Therapies:Gene therapy and regenerative medicine approaches are entering early-phase clinical trials.
Surgery captures the highest reimbursement tier, with Emerging Therapies showing the steepest expansion trajectory.
Delivery Mode:
Application requirements vary sharply across acute versus chronic treatment contexts, with injectable modalities demanding specialized administration infrastructure that oral formulations bypass.
- Injectable:Intra-articular hyaluronic acid and corticosteroid injections require physician administration in clinic or ambulatory settings. Molecular weight engineering spanning 500 to 6,000 kDa is extending dosing intervals and improving patient compliance in United States knee osteoarthritis protocols.
- Oral:NSAIDs and analgesics sustain highest volume throughput across primary care networks. Generic substitution has compressed pricing, though Medicare Part D formulary positioning preserves manufacturer margin.
- Topical:Transdermal NSAID formulations target localized delivery with reduced systemic exposure.
- Transdermal:Patch-based delivery systems are expanding in chronic pain management.
Oral delivery sits at the top of the volume ranking, with Injectable climbing the fastest.
End User:
Customer type concentration reflects site-of-service economics, with hospital systems defending procedural revenue against ambulatory and home-based care migration.
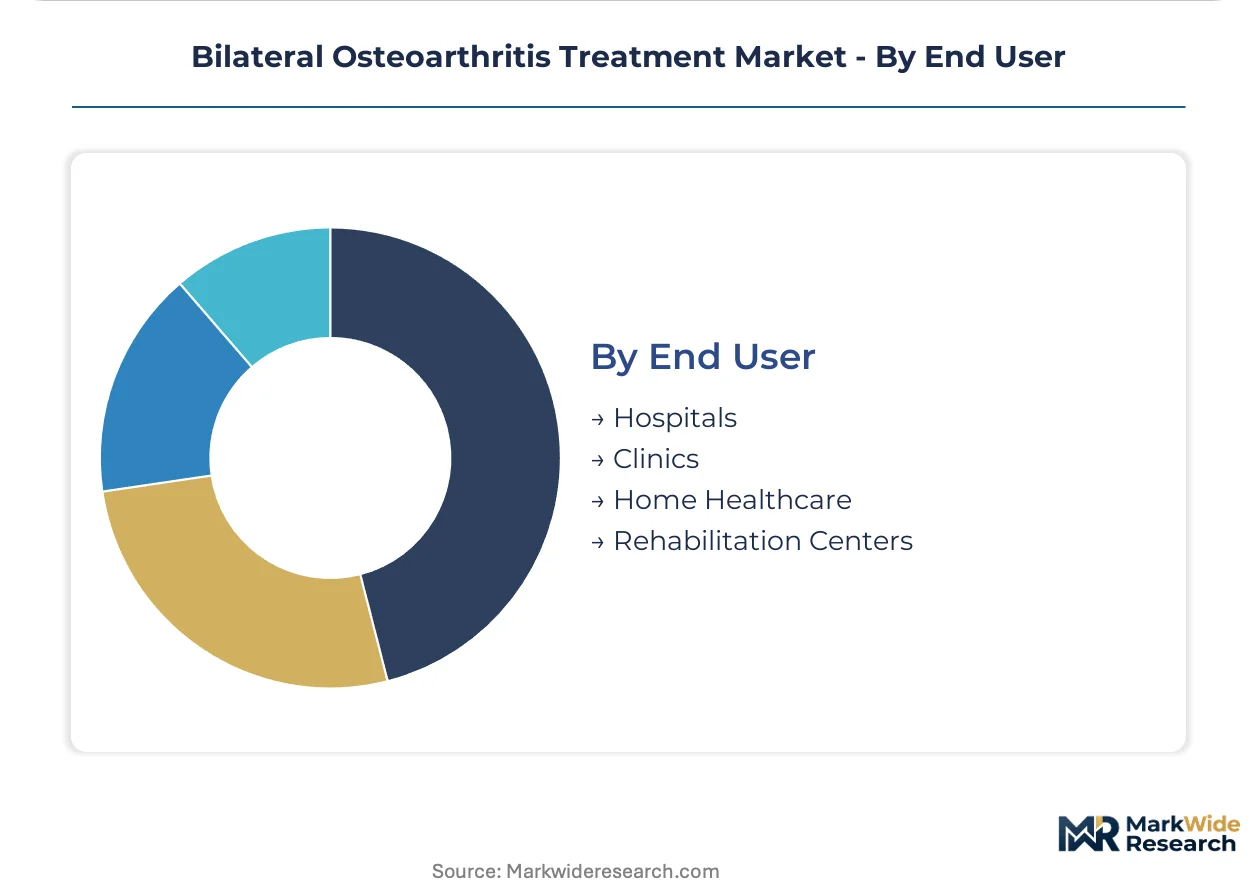
- Hospitals:Academic medical centers and community hospitals anchor arthroplasty volume through operating room block allocation. United States hospital systems are expanding orthopedic service lines to capture rising bilateral procedure demand from aging demographics.
- Clinics:Orthopedic and rheumatology clinics control injection therapy access and patient selection for surgical referral. Hyaluronic acid viscosupplementation protocols concentrate in specialty clinic settings with ultrasound guidance capability.
- Home Healthcare:Post-arthroplasty rehabilitation and medication administration are shifting toward remote monitoring platforms.
- Rehabilitation Centers:Dedicated physical therapy facilities manage post-surgical recovery protocols.
Hospitals sits at the top of the volume ranking, with Home Healthcare climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mayo Clinic's orthopedic campus in Rochester anchors procedural innovation for bilateral knee arthroplasty, attracting surgical volume from across the Midwest and establishing protocol standards that diffuse through United States hospital networks.
United States
Medicare Part D reimbursement expansion under IRA provisions is accelerating prescription volume for chronic osteoarthritis medications. FDA's accelerated approval pathways for disease-modifying therapies are compressing clinical development timelines for intra-articular biologics. The Texas Medical Center in Houston is consolidating ambulatory surgery capacity for staged bilateral procedures through value-based joint replacement bundles.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia are driving arthroplasty waiting list volumes in statutory health insurance networks. EMA's MDR compliance requirements for implantable devices are extending certification timelines for multinational suppliers seeking European market entry. The Berlin-Brandenburg medical technology cluster is specializing in crosslinked hyaluronic acid formulation manufacturing for viscosupplementation export.
Japan
PMDA's streamlined review pathways for regenerative medicine products are accelerating cell-based therapy commercialization for knee osteoarthritis. METI's healthcare cost containment policies are shifting reimbursement toward outpatient injection protocols versus surgical intervention. The Kansai region's Osaka-Kobe medical corridor is concentrating platelet-rich plasma processing facilities serving aging populations in western Honshu.
Switzerland
Swissmedic's stringent quality standards for biologic manufacturing are elevating compliance costs for intra-articular therapy producers targeting premium European markets. The country's mandatory health insurance framework guarantees reimbursement access for advanced osteoarthritis interventions. Basel's pharmaceutical manufacturing corridor hosts specialized facilities for hyaluronic acid molecular weight engineering spanning 500 to 6,000 kDa specifications.
United Kingdom
NHS England's elective recovery program is clearing pandemic-era backlogs for hip and knee replacement procedures, expanding bilateral arthroplasty capacity in acute trusts. The MHRA's post-Brexit regulatory autonomy is creating parallel certification tracks for orthopedic devices distinct from EU MDR pathways. London's academic hospital networks are piloting simultaneous bilateral knee replacement protocols enabled by enhanced recovery after surgery programs.
Bilateral Osteoarthritis Treatment Market Competitive Landscape
Global majors compete with regional champions across device integration and pharmaceutical formulation dimensions, creating a tiered structure where scale-driven conglomerates anchor high-volume segments while specialized boutiques capture premium niches. The market stratifies into three archetypes: diversified healthcare conglomerates with orthopedic device heritage, pharmaceutical incumbents with chronic pain management portfolios, and emerging biologic specialists with cell therapy platforms. Dominant competitive moves include strategic partnerships between device manufacturers and ambulatory surgery networks, plus portfolio diversification into home-based rehabilitation monitoring.
Within the diversified healthcare conglomerate tier, Johnson & Johnson Services (DePuy Synthes) and Zimmer Biomet Holdings Inc. exemplify integrated orthopedic device positioning. Novartis AG and Pfizer Inc. occupy pharmaceutical incumbent roles with distinct chronic therapy anchoring strategies. These named entities represent archetypal competitive positioning rather than exhaustive market coverage, with each exemplifying how heritage capabilities translate into bilateral osteoarthritis treatment segment presence.
| Leading Market Players |
|---|
| Johnson & Johnson Services (DePuy Synthes) |
| Novartis AG |
| GlaxoSmithKline Plc. |
| Abbott Laboratories |
| Zimmer Biomet Holdings Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| F-Hoffmann-La Roche Ltd. |
| Amgen Plc. |
| Others |
Value Network & Pricing Analysis
Performance-grade bifurcation between crosslinked hyaluronic acid formulations and commodity corticosteroid injections manifests in divergent procurement economics and manufacturing footprints across United States and European supply networks. Premium viscosupplementation commands threefold reimbursement multiples over generic intra-articular steroids, while EPA environmental compliance costs and EMA MDR certification burdens reshape supplier geographic concentration.
Pricing Analysis
Input-cost pass-through from biologic raw material volatility and EPA manufacturing standards is compressing margins for platelet-rich plasma processors while sustaining premium capture for crosslinked hyaluronic acid formulators. Three-tier pricing structure across premium, standard, and economy levels separates molecular-engineered viscosupplementation from conventional hyaluronic acid and generic corticosteroids. Pricing pressure stems from Medicare Part D formulary negotiations under IRA provisions, with oral NSAID substitution intensifying cost compression in primary care channels. Hospital systems exhibit lowest price sensitivity due to bundle economics, while independent ambulatory surgery centers face acute margin pressure.
Supply Chain Analysis
Domestic-content mandates in United States federal procurement and Buy American provisions for hospital system purchasing are redirecting arthroplasty device sourcing toward domestic manufacturing corridors in Indiana and Ohio. Supply concentration centers on United States, Germany, and Switzerland for implantable devices, with South Korea and Japan anchoring hyaluronic acid fermentation capacity. Raw material dependencies span pharmaceutical-grade sodium hyaluronate, titanium alloy forgings, and biologic growth factor concentrates. Single-source vulnerability concentrates in crosslinked polymer chemistry expertise held by Basel-region specialists. Distribution runs through integrated delivery network procurement consortia and orthopedic-focused GPOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bilateral osteoarthritis treatment market functions as a stable compounder anchored by irreversible demographic aging and chronic disease prevalence expansion. Reimbursement access through Medicare Part D and value-based joint replacement bundles provides predictable revenue visibility across pharmaceutical and device segments.
For Market Incumbents: Hedge against biosimilar displacement in intra-articular therapy by deepening manufacturing integration into hyaluronic acid fermentation capacity and securing exclusive hospital system contracts through bundled procedural offerings. FDA accelerated approval pathways for disease-modifying therapies threaten corticosteroid-centric portfolios, necessitating R&D redirection toward cell-based platforms. Vertical control over biologic raw material processing preserves margin architecture against donor variability risks.
For New Entrants and Emerging Players: IRA Medicare pricing provisions in the United States open a window for complex generic manufacturers to capture corticosteroid replacement demand through biosimilar intra-articular formulations. Ambulatory surgery center expansion presents the most penetrable channel for novel viscosupplementation delivery technologies, with ultrasound-guided injection protocols offering differentiated positioning. Target GPO contract penetration through outcomes-based pricing guarantees that align with CMS value-based care pilots.
For Investors and Strategic Acquirers: Consolidation pressure builds where orthopedic surgeon workforce constraints limit procedural capacity expansion in secondary United States markets. Five-to-ten-year viability favors platforms with simultaneous bilateral procedure protocols and home-based rehabilitation monitoring capabilities. Acquisition target archetype: mid-cap viscosupplementation formulators with crosslinked chemistry IP and established clinic channel relationships. Signal to monitor: CMS reimbursement rate adjustments for staged versus simultaneous bilateral arthroplasty.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Accelerated Approval Pathway | Compresses clinical timelines for disease-modifying intra-articular biologics entering United States markets. |
| Hospital System Partnership | Secures operating room block allocation and bundle participation for arthroplasty device manufacturers. |
| Manufacturing Scale-Up | Expands EPA-compliant fermentation capacity for hyaluronic acid molecular weight engineering. |
| Reimbursement Strategy | Aligns Medicare Part D formulary positioning with IRA pricing provision structures. |
| Software Companion Development | Enables remote monitoring platforms for post-arthroplasty rehabilitation protocol adherence. |
Research Methodology
Multiple input streams — orthopedic surgeon interviews, hospital procurement committee discussions, pharmaceutical regulatory affairs consultations, and GPO contract analysis — were reconciled against secondary validation from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare claims data, and hospital procurement databases. Primary fieldwork engaged formulary directors, ambulatory surgery center administrators, biomedical engineers, and payer access specialists across United States integrated delivery networks. Bottom-up procedure volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Cross-referencing historical utilization patterns against expert panel inputs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, therapy area, delivery mode, end user, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories, prescription pattern analysis, and reimbursement rate evolution. Industry-specific forecast inputs incorporated orthopedic surgeon workforce pipeline data and hyaluronic acid formulation approval timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA regulatory pathway disruptions, biologic raw material supply shocks, and CMS bundle reimbursement recalibrations. Forecasts reflect documented assumptions regarding demographic aging velocity and procedural migration to ambulatory settings. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Orthopedics Market
Orthopedics
Kyphosis Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Podiatry Services Market
Orthopedics
Septic Arthritis Market
Orthopedics
Rickets Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Genu Recurvatum Market