
 Bone Spur Market | 2026-2036
Bone Spur Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Spur Market Analysis
Post-operative maintenance subscriptions is broadening what orthopedic vendors monetize beyond the initial intervention. Stryker leverages its implant ecosystem to capture recurring revenue from follow-up monitoring protocols. Zimmer Biomet anchors its competitive stance through specialized instrumentation for revision procedures. Siemens Healthineers competes by integrating imaging hardware with AI-assisted pre-surgical planning modules.
Bone spurs, or osteophytes, are bony projections that form along joint margins through endochondral ossification, typically measuring 2-10 millimeters and composed of trabecular bone with a fibrocartilage cap. These formations develop as mechanical responses to joint instability, serving primarily to redistribute load across compromised articular surfaces. Surgical Solutions commands the deepest margin pools due to implant premiumization and procedure complexity, while Physical Therapy segments expand fastest among non-invasive alternatives as payors tighten surgical authorization criteria. Foot Care applications dominate procedure volumes given weight-bearing biomechanics, though Spine Care segments attract higher reimbursement intensity per intervention.
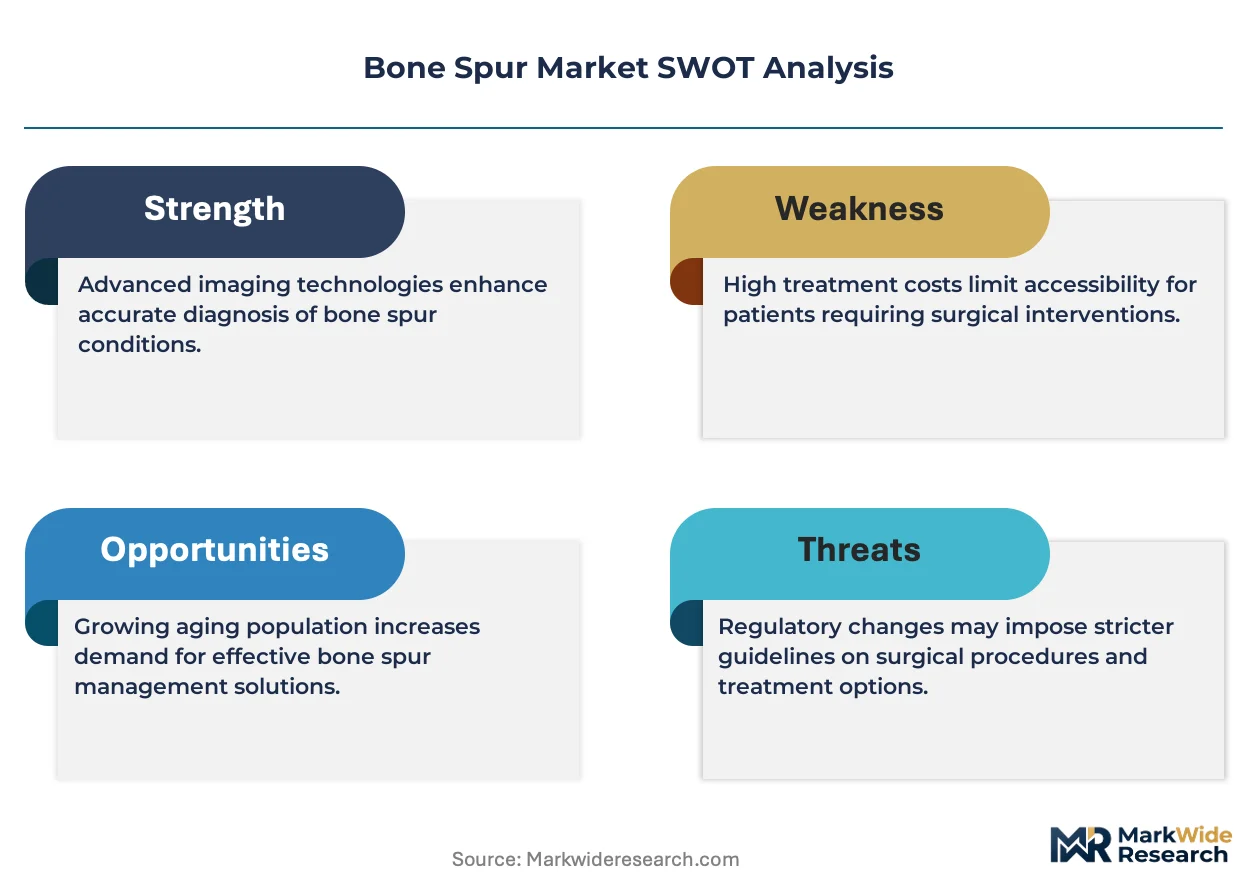
The FDA governs orthopedic device safety through 510(k) and PMA pathways, while ISO 13485 standards govern quality management systems for manufacturers targeting multiple jurisdictions. CMS reimbursement schedules directly influence provider adoption of advanced bone spur interventions versus conservative management protocols. Stakeholders must monitor how prior authorization algorithms reshape treatment method selection across hospital and home care channels.
Market Dynamics
The bone spur market pivots on CMS reimbursement schedules tightening surgical authorization criteria, forcing providers toward conservative management protocols and reshaping competitive positioning across intervention categories.
Growth Catalysts
- Aging Demographics:Germany's established rehabilitation infrastructure sustains elevated procedure volumes as its population ages, creating sustained demand for joint preservation interventions.
- 510(k) Pathway Efficiency:The FDA's streamlined orthopedic device clearance mechanisms compress commercialization timelines for novel implant designs targeting revision procedures.
- Sports Clinic Expansion:Athletic populations seeking preventive joint management are electrifying demand for outpatient diagnostic and therapeutic services outside traditional hospital settings.
Market Restraints
- Titanium Input Volatility:Fluctuations in aerospace-grade titanium pricing compress margin pools for implant manufacturers dependent on specialized alloy supply chains.
- Prior Authorization Friction:Algorithm-driven insurer gatekeeping extends patient wait times for surgical interventions, dampening conversion rates from diagnosis to procedure.
- Physical Therapy Substitution:Non-invasive alternatives capture cases previously routed to operative management as payor cost-containment intensifies.
Strategic Opportunities
- Home Care Channel Development:Remote monitoring subscriptions for post-operative maintenance create recurring revenue streams beyond initial device implantation.
- AI-Imaging Convergence:Integration of pre-surgical planning software with diagnostic hardware enables precision-guided interventions with reduced revision likelihood.
- Foot Care Segment Deepening:Weight-bearing biomechanics applications remain underpenetrated relative to spine interventions despite higher absolute procedure volumes.
Industry Challenges
- ISO 13485 Certification Timelines:Multi-jurisdictional quality management system audits delay market entry for manufacturers targeting both FDA and CE-marked territories.
- Revision Instrumentation Complexity:Specialized tool development for secondary procedures demands capital-intensive R&D with uncertain commercial uptake.
- Legacy EHR Integration:Post-operative monitoring protocols require data interoperability with hospital information systems that resist third-party connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Spur Market |
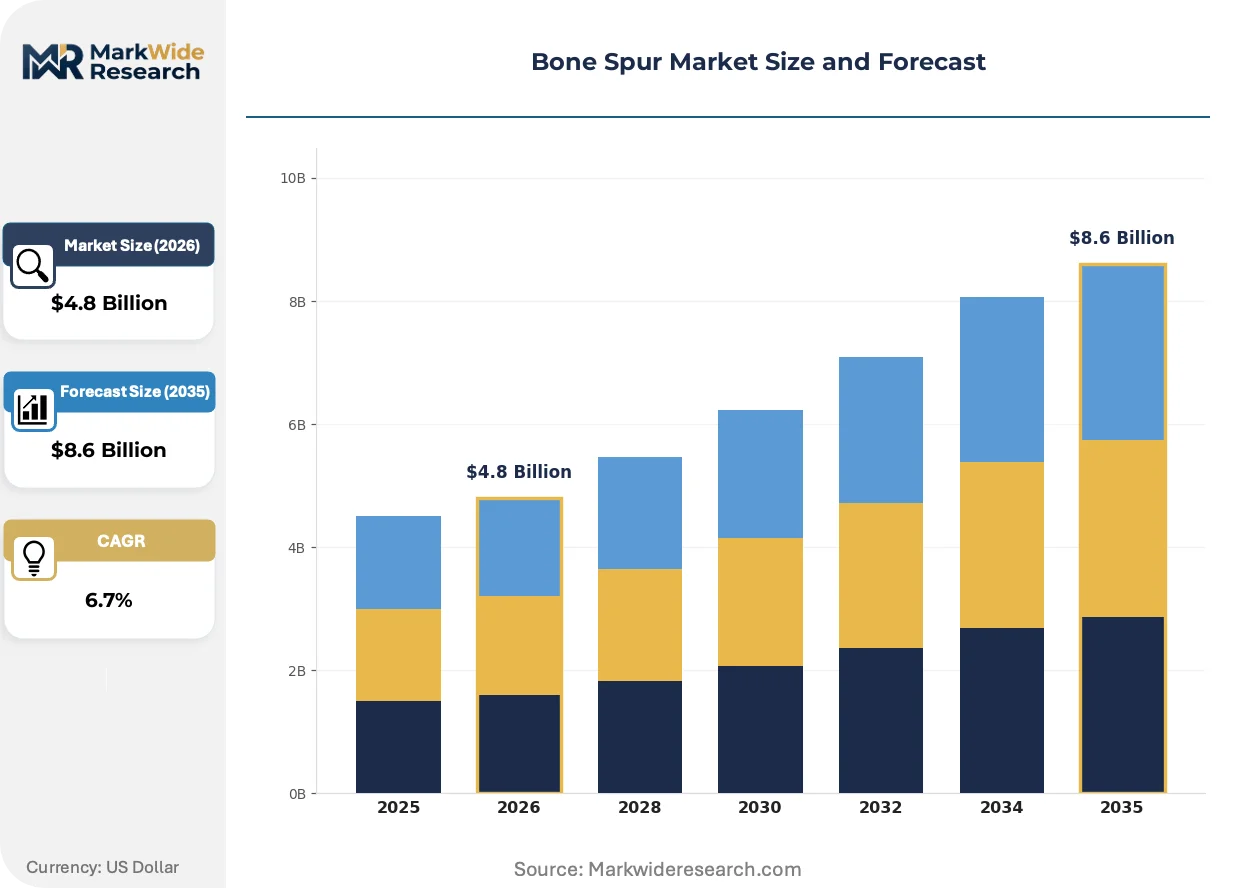
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotics, Medications, Physical Therapy, Surgical Solutions End User: Hospitals, Rehabilitation Centers, Home Care, Sports Clinics Treatment Method: Non-Surgical, Surgery, Injections, Alternative Therapies Application: Foot Care, Spine Care, Knee Care, Joint Care |
| Companies Covered | Pfizer Inc., Koninklijke Philips N.V., AbbVie Inc, Stryker, Siemens Healthineers, Eli Lilly and Company, General Electric Company, Zimmer Biomet, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Spur Market Emerging Trajectories
Orthopedic care delivery is electrifying around predictive analytics and remote patient engagement, compressing traditional episode-based reimbursement models toward continuous relationship economics.
Patient-specific instrumentation derived from 3D imaging is electrifying surgical planning workflows. Academic medical centers and high-volume orthopedic groups are adopting these platforms fastest, compressing operative time and implant waste while elevating reproducibility across surgeon experience levels.
The FDA's evolving 510(k) predicate device requirements are reshaping orthopedic innovation pathways. Manufacturers must now demonstrate substantial equivalence with greater clinical rigor, compressing development timelines for novel geometries while elevating documentation burdens for bone spur implant categories.
Athletic populations now demand preventive joint management before symptomatic degeneration. Sports clinics in the United States and Germany are capturing these cases through subscription-based movement screening and early intervention protocols, displacing reactive specialist referrals.
Bone Spur Market Segmentation
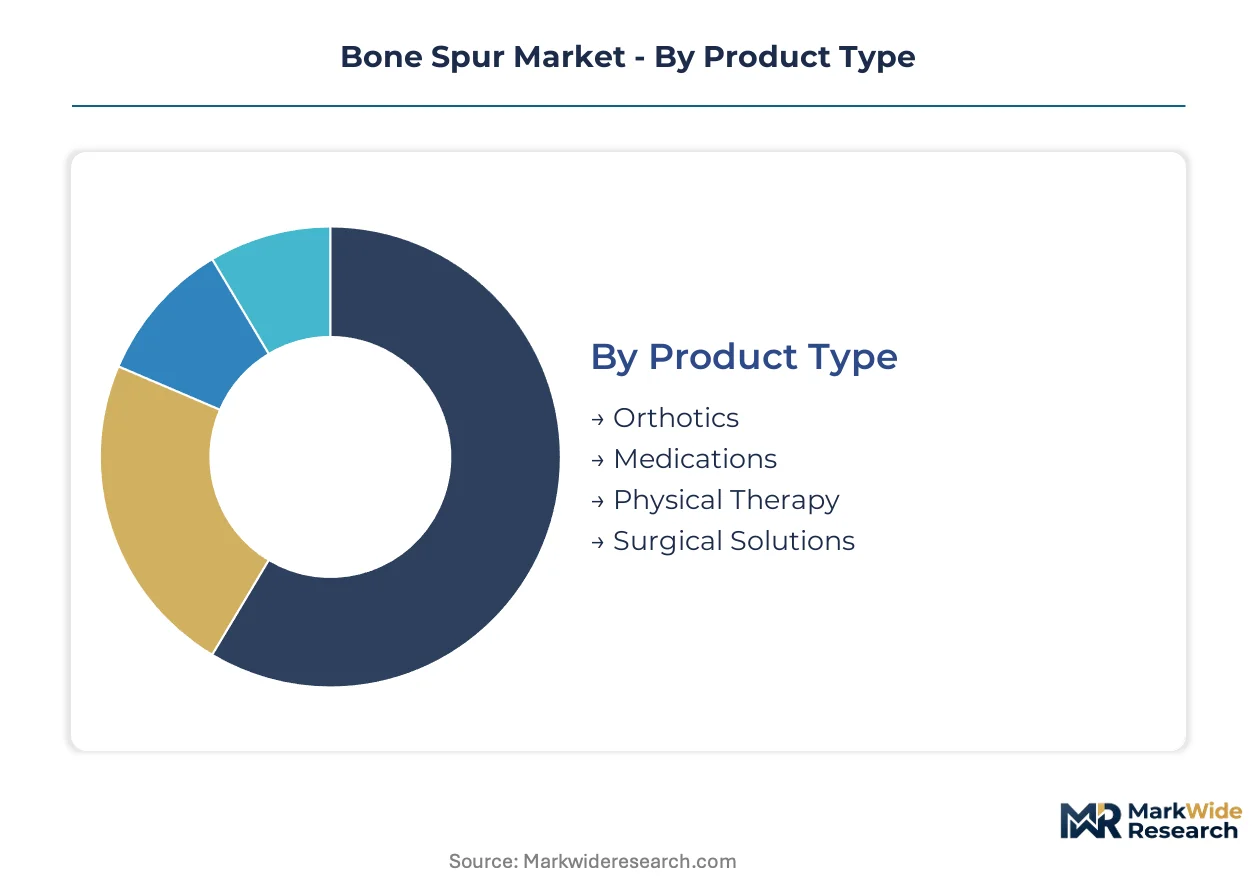
Orthopedic vendors structure their commercial strategies around four intersecting axes: product modality, care setting, intervention invasiveness, and anatomical target. Each axis carries distinct margin profiles and regulatory requirements that reshape competitive positioning.
Product Type:
Material composition and reimbursement intensity separate premium implant categories from consumable alternatives.
- Surgical Solutions:Titanium and polyetheretherketone implants command premium pricing through 510(k) clearance pathways. Demand clusters in academic medical centers performing revision procedures, where specialized instrumentation drives procedure economics.
- Physical Therapy:Protocol-based interventions expand most quickly as CMS prior authorization algorithms tighten surgical funnel conversion. Sports clinics in Germany and the United States capture preventive cases through subscription movement screening.
- Orthotics:Custom-molded foot and ankle devices serve weight-bearing biomechanics applications with lower regulatory burden than implantable categories.
- Medications:NSAID and corticosteroid formulations address symptomatic management without procedure-based revenue capture.
Mature deployment sits with Surgical Solutions. Newer deployment is concentrated in Physical Therapy.
End User:
Care setting determines capital equipment requirements and episode reimbursement structure.
- Sports Clinics:Outpatient diagnostic and therapeutic services electrify demand outside traditional hospital infrastructure. Athletic populations seeking preventive joint management drive volume in the United States and Germany.
- Hospitals:Inpatient surgical suites anchor high-acuity revision procedures requiring specialized instrumentation and post-operative monitoring integration.
- Rehabilitation Centers:Germany's established infrastructure sustains elevated procedure volumes through aging demographic demand for joint preservation protocols.
- Home Care:Remote monitoring subscriptions for post-operative maintenance create recurring revenue streams beyond initial device implantation.
Capital intensity peaks in Hospitals. Channel expansion concentrates in Sports Clinics.
Treatment Method:
Involuntary ossification severity and patient functional status determine intervention selection.
- Surgery:Arthroscopic and open reduction procedures address end-stage joint compromise with the highest reimbursement per episode.
- Non-Surgical:Activity modification and bracing protocols capture early-stage cases before structural degeneration accelerates.
- Injections:Corticosteroid and hyaluronic acid delivery provide intermediate symptom relief with ambulatory procedure economics.
- Alternative Therapies:Acupuncture and ultrasound modalities occupy regulatory gray zones with variable payer coverage.
Revenue concentration favors Surgery. Volume expansion trends toward Non-Surgical protocols.
Application:
Anatomical load-bearing characteristics reshape procedure complexity and revision likelihood.
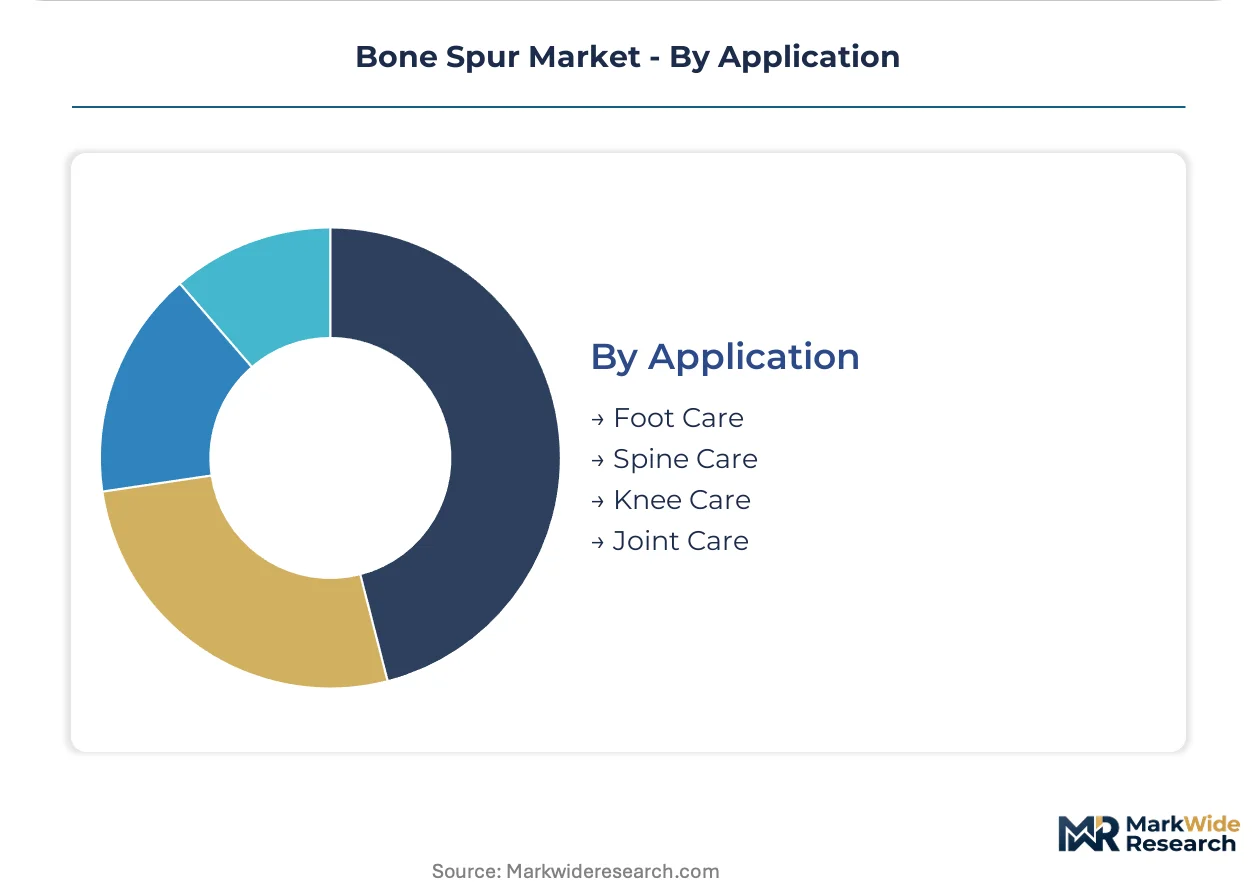
- Foot Care:Weight-bearing biomechanics drive absolute procedure volumes through hallux valgus and plantar fasciitis sequelae. The segment remains underpenetrated relative to spine interventions despite higher case counts.
- Spine Care:Cervical and lumbar osteophyte interventions attract elevated reimbursement intensity per procedure, with neural compression indications mandating surgical management.
- Knee Care:Tibiofemoral and patellofemoral compartment spurs respond to both arthroscopic debridement and unicompartmental replacement.
- Joint Care:Shoulder, hip, and elbow applications follow distinct degenerative trajectories with specialized implant requirements.
Procedure volume leadership belongs to Foot Care. Revenue intensity concentrates in Spine Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors orthopedic innovation density in the United States, hosting concentrated implant manufacturing and surgical robotics development that shapes bone spur intervention economics across North America and European export markets.
United States
FDA 510(k) clearance pathways compress commercialization timelines for novel implant geometries targeting revision procedures. The agency's evolving predicate device requirements elevate clinical documentation burdens for bone spur implant categories. Minneapolis-St. Paul and Warsaw, Indiana host the densest clusters of orthopedic device manufacturing and specialized instrumentation development.
Germany
Aging demographics sustain elevated procedure volumes through established rehabilitation infrastructure and statutory health insurance coverage for joint preservation interventions. The EU Medical Device Regulation (MDR) mandates notified body oversight for implantable orthopedic devices, extending certification timelines for manufacturers targeting CE-marked territories. Bavaria and Baden-Württemberg concentrate high-volume orthopedic centers and precision engineering suppliers serving revision instrumentation demand.
Japan
PMDA marketing authorization pathways govern orthopedic device entry, with reimbursement listings under the Ministry of Health, Labour and Welfare determining provider adoption rates. METI industrial policy supports domestic manufacturing of advanced biomaterials for implant applications. The Kansai region around Osaka hosts specialized metalworking clusters supplying aerospace-grade titanium alloys to orthopedic device fabricators.
United Kingdom
NICE technology appraisals influence NHS commissioning decisions for bone spur interventions, creating divergence between surgical and conservative management adoption across integrated care systems. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR implementation timelines. The Oxford-Cambridge arc concentrates academic medical centers pioneering patient-specific instrumentation derived from 3D imaging workflows.
Switzerland
Swissmedic device licensing maintains alignment with EU MDR standards while preserving independent market surveillance authority. The country's precision manufacturing heritage supports specialized contract manufacturers producing orthopedic instrumentation for global OEMs. The Basel-Zurich corridor hosts concentrated medical technology R&D and venture capital deployment targeting orthopedic digital health platforms.
Bone Spur Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the bone spur market, with integrated implant manufacturers maintaining foundry-like control over specialized alloy supply chains while surgical planning software vendors operate asset-light development models. The vendor base separates into three strategic archetypes: diversified orthopedic conglomerates with implant ecosystem breadth, precision imaging hardware specialists converging on AI-assisted surgical planning, and pharmaceutical incumbents addressing symptomatic management through NSAID and biologic formulations. Dominant competitive moves include M&A activity targeting revision instrumentation capabilities and strategic partnerships between implant manufacturers and remote monitoring platform developers.
Among diversified orthopedic device manufacturers, Stryker, Zimmer Biomet, and Siemens Healthineers occupy positions spanning implant hardware, surgical navigation, and post-operative monitoring integration. Stryker exemplifies the implant ecosystem archetype with recurring revenue capture from follow-up protocols. Zimmer Biomet represents specialized instrumentation development for complex revision procedures. Siemens Healthineers anchors the imaging-convergence vector through diagnostic hardware integration with pre-surgical planning modules.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Koninklijke Philips N.V. |
| AbbVie Inc |
| Stryker |
| Siemens Healthineers |
| Eli Lilly and Company |
| General Electric Company |
| Zimmer Biomet |
| Merck & Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up orthopedic specialists have consolidated implant manufacturing capacity across Warsaw, Indiana and Minneapolis-St. Paul, compressing supplier counts while hardening pricing discipline through captive distribution networks and long-term GPO contracts.
Pricing Analysis
Outcome-linked reimbursement anchors pricing for bone spur interventions, with CMS episode-based bundles rewarding reduced revision rates and shorter recovery windows. Three-tier pricing structure across premium, standard, and economy levels separates titanium-alloy implants from polyetheretherketone alternatives and commodity stainless hardware. Cost compression in standard-tier categories is intensifying because physical therapy protocols capture cases previously routed to operative management. Hospital purchasing committees exhibit highest price sensitivity, while academic medical centers performing complex revisions accept premium positioning for specialized instrumentation.
Supply Chain Analysis
Regional distribution centers in Warsaw, Indiana and Bavaria, Germany operate hub-and-spoke patterns feeding hospital systems and sports clinics across North America and Western Europe. Manufacturing concentrates in the United States, Germany, and Switzerland, with aerospace-grade titanium supply drawing from Japanese and Russian feedstock processed through Kansai-region metalworking clusters. Single-source vulnerability sits with specialized alloy suppliers serving FDA-cleared implant grades. Distribution runs through orthopedic-focused GPOs and direct-to-hospital contracts, with home care channels emerging for remote monitoring hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is forcing out capital-constrained instrument manufacturers as ISO 13485 certification timelines and AI-imaging convergence raise fixed-cost barriers beyond mid-tier reach.
For Market Incumbents: Anchor defensive positioning through backward integration into aerospace-grade titanium supply and captive production of patient-specific instrumentation in Minneapolis-St. Paul. Deepen vertical control over revision procedure workflows to offset margin erosion from physical therapy substitution. Prioritize FDA 510(k) pathway efficiency for novel implant geometries targeting complex secondary interventions. For New Entrants and Emerging Players: AI-assisted pre-surgical planning modules offer technology-first wedge into underserved sports clinic channels in Germany and the United States. Target preventive joint management subscriptions before symptomatic degeneration accelerates. Pursue white-label partnerships with established rehabilitation infrastructure rather than direct hospital sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-imaging hardware specialists with CE-marked European revenue and ISO 13485 quality systems already operational. Long-term viability hinges on convergence with remote monitoring platforms and AI-guided intervention workflows. Watch CMS prior authorization algorithm updates as inflection signals for surgical-to-conservative management mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accelerates multi-jurisdictional market entry for implant manufacturers targeting FDA and CE-marked territories simultaneously. |
| AI-Imaging Platform Integration | Enables Siemens Healthineers and imaging specialists to capture pre-surgical planning workflows from traditional implant vendors. |
| Remote Monitoring Subscription Launch | Creates recurring revenue streams for Stryker and ecosystem players beyond initial device implantation episodes. |
| Revision Instrumentation Development | Addresses underserved complex secondary procedures where Zimmer Biomet has established specialized tool dominance. |
| Sports Clinic Channel Partnership | Captures preventive joint management demand from athletic populations outside traditional hospital infrastructure. |
Methodological Framework
Multi-period observation of CMS reimbursement schedule revisions, FDA 510(k) clearance velocity, and sports clinic procedure volumes anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and EU MDR notified body certification records. Bottom-up demand modeling across product modality, care setting, intervention invasiveness, and anatomical target intersected with top-down macroeconomic triangulation.
Segment-weighting approaches distributed value and volume across surgical solutions, physical therapy, orthotics, and medications, with further stratification by end user and application. Growth projections across the analysis window derived from procedure volume elasticity to demographic aging, reimbursement policy shifts, and technology adoption curves. Forecast inputs included titanium alloy pricing volatility indices and prior authorization algorithm deployment timelines from major payors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS bundle restructuring or aerospace-grade titanium supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Orthopedic Pillow Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Orthopedics Market
Orthopedics
Costochondritis Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Osteoporosis Treatment Market