
 Osteonecrosis Treatment Market | 2026-2036
Osteonecrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Osteonecrosis Treatment Market Outlook
North American orthopedic implant manufacturing is restructuring around precision-machined patient-specific instrumentation. Zimmer Biomet leverages its scale in hip reconstruction systems to dominate hospital procurement channels. Stryker anchors its position through integrated navigation-assisted surgical platforms. Pfizer competes in the pharmaceutical segment with small-molecule bone remodeling agents.
Osteonecrosis treatment encompasses pharmacological interventions, surgical procedures, and biological therapies aimed at halting bone death progression and preserving joint function. Core decompression, the foundational surgical technique, involves drilling into the necrotic lesion to reduce intraosseous pressure and stimulate vascular ingrowth. Surgical implants and stem cell therapies command premium positioning due to their curative intent and technical complexity, while bisphosphonates occupy a mature, volume-driven maintenance role across outpatient settings. Intra-articular administration routes are gaining traction as delivery systems improve localized drug deposition.
The FDA regulates osteonecrosis biologics through its Center for Biologics Evaluation and Research, enforcing stringent safety benchmarks for autologous cell therapies. The EMA's Advanced Therapy Medicinal Products framework shapes European market entry requirements for novel regenerative interventions. Stakeholders must monitor evolving reimbursement thresholds for cell-based treatments as health technology assessment bodies recalibrate value metrics.
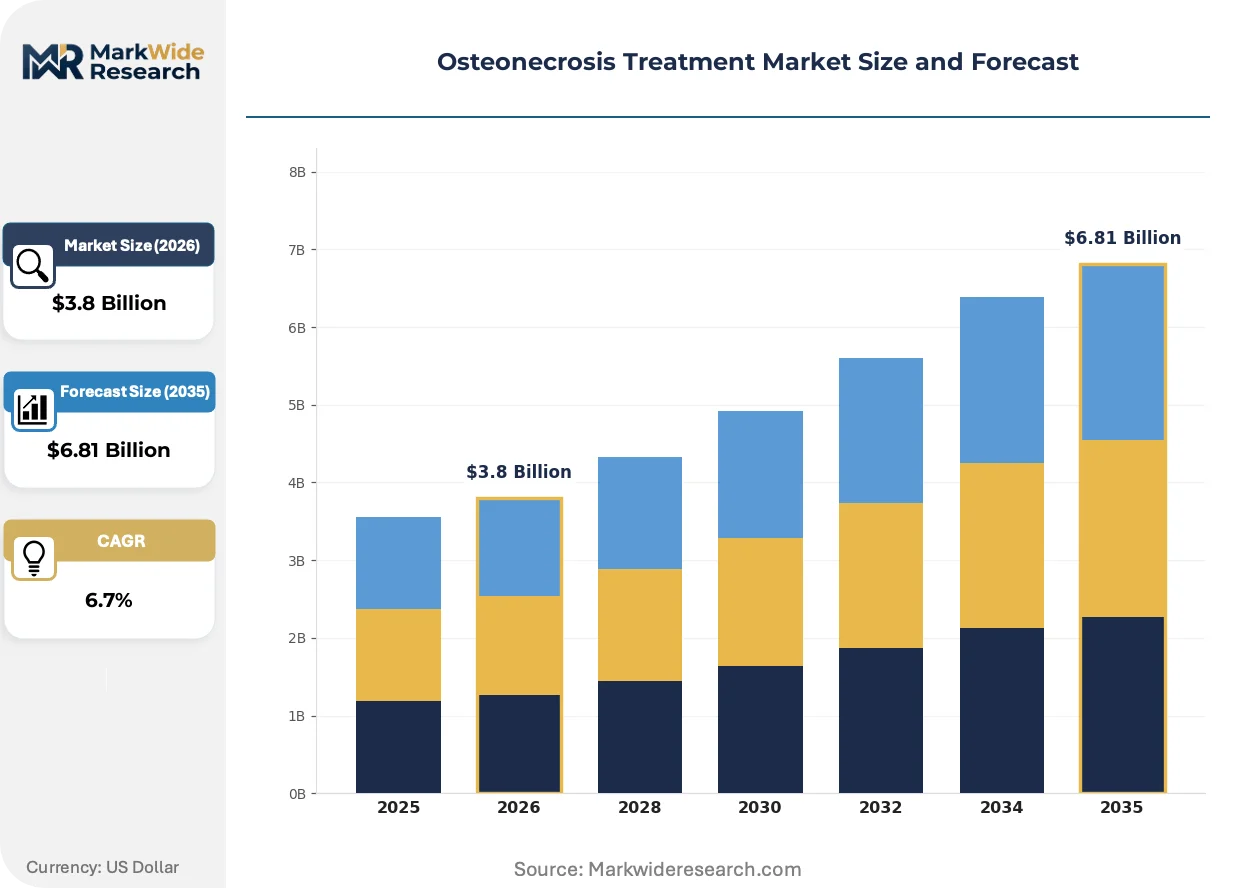
Market Dynamics
The FDA's accelerated approval pathways for regenerative medicine are compressing development timelines for stem cell-based osteonecrosis interventions, forcing traditional orthopedic implant manufacturers to recalibrate their R&D roadmaps around biologic integration.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:The streamlined European pathway for cell therapies reduces market entry barriers for autologous bone marrow concentrate treatments, stimulating investment in biologic manufacturing capacity across Germany and Switzerland.
- Hospital orthopedic unit expansion:Dedicated surgical units in major US health systems are consolidating procedural volumes and creating captive demand channels for precision-machined patient-specific instrumentation.
- Intra-articular drug delivery systems:Improved localized deposition technologies are extending the therapeutic window for bisphosphonate maintenance regimens in outpatient settings.
Market Restraints
- Biologic raw material concentration:Autologous cell therapy supply chains depend on concentrated bone marrow aspirate processing capabilities concentrated in a limited number of specialized US and European facilities.
- Reimbursement threshold rigidity:Health technology assessment bodies in major European markets maintain conservative value metrics that delay patient access to novel regenerative interventions.
- Technical limitation in early detection:MRI-based staging protocols lack standardization across clinical sites, delaying intervention until subchondral collapse becomes irreversible.
Strategic Opportunities
- Underpenetrated Japanese market:Japan's PMDA regenerative medicine framework offers expedited approval for combined cell-implant products, creating first-mover advantages for integrated therapeutic platforms.
- Navigation-assisted surgical platforms:Convergence of robotic positioning systems with 3D-printed patient-specific guides is enabling precision core decompression in previously non-surgical candidates.
- Centers of excellence networks:Specialized orthopedic institutes in South Korea and Singapore are emerging as referral hubs for complex revision procedures, concentrating high-value caseloads.
Industry Challenges
- Cell therapy manufacturing scale-up:Autologous biologic production requires GMP-compliant cleanroom infrastructure that demands substantial capital deployment with extended depreciation timelines.
- Cross-border regulatory divergence:Divergent FDA and EMA guidance documents on potency assays for mesenchymal stem cell products create redundant validation burdens for multi-territory sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteonecrosis Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Antioxidants, Surgical Implants, Stem Cell Therapy End User: Orthopedic Clinics, Rehabilitation Centers, Hospitals, Research Institutions Administration Route: Intravenous, Oral, Intra-articular, Topical Care Setting: Inpatient, Outpatient, Home Care, Specialty Clinics |
| Companies Covered | Zimmer Biomet, Merck & Co. Inc., Novartis AG, Bone Therapeutics SA, Viatris Inc., Pfizer Inc., Stryker, Enzo Biochem Inc., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteonecrosis Treatment Market Strategic Shifts
Orthopedic intervention paradigms are pivoting from joint replacement toward joint preservation, with biological augmentation of mechanical procedures emerging as the dominant technical trajectory across hospital systems and ambulatory surgical centers.
3D-printed porous titanium scaffolds are expanding into core decompression procedures to provide structural support while osteointegration proceeds. Academic medical centers in the United States are adopting these patient-matched implants at accelerating pace for Ficat stage II and III lesions. The technology is expanding into previously non-surgical patient populations by enabling load-bearing capacity during the extended vascular ingrowth period.
The FDA's regenerative medicine advanced therapy designation is compressing review timelines for combined device-biologic products. This regulatory flexibility is redirecting venture funding toward integrated therapeutic platforms rather than standalone mechanical or pharmaceutical interventions. Orthopedic device divisions are responding by acquiring cell processing capabilities and in-licensing autologous concentrate technologies.
Hospital procurement committees are consolidating vendor relationships around full-procedure contracts that bundle implants, biologics, and navigation systems. Independent ambulatory surgery centers are losing access to premium technologies as manufacturers prioritize volume commitments from integrated delivery networks. This concentration is most visible in the United States, where health system consolidation has reduced the number of independent orthopedic purchasing entities by half over the past decade.
Osteonecrosis Treatment Market Segmentation
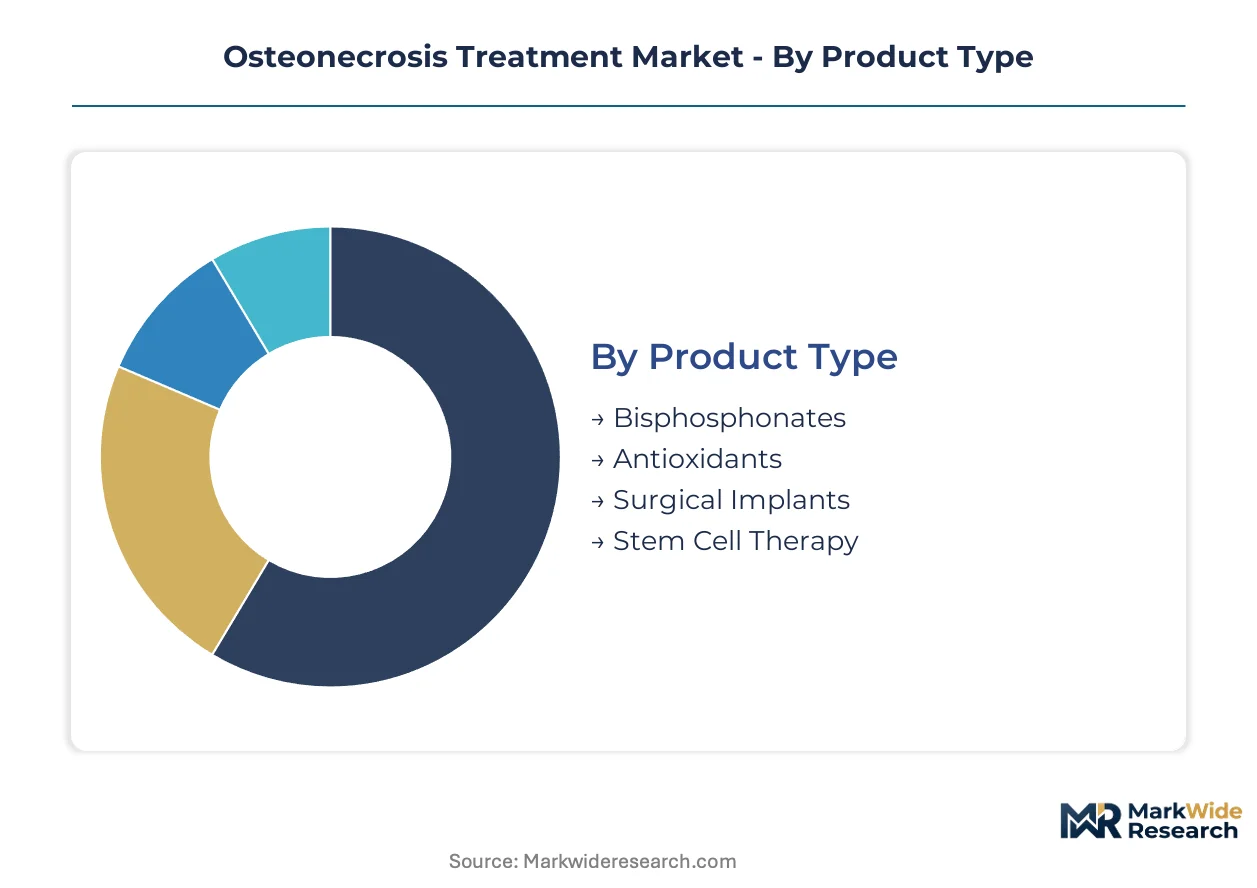
Osteonecrosis treatment segmentation reflects divergent clinical objectives across preservation versus replacement paradigms. Procurement patterns split between volume-driven pharmaceutical maintenance and premium surgical interventions requiring capital-intensive infrastructure.
Product Type:
Hospital procurement committees weight upfront cost against procedural complexity and reimbursement certainty when allocating budgets across therapeutic categories.
- Surgical Implants:Precision-machined patient-specific instrumentation and 3D-printed porous titanium scaffolds dominate Ficat stage II and III interventions. Demand concentrates in United States integrated delivery networks where bundled payment models reward joint preservation outcomes.
- Stem Cell Therapy:Autologous bone marrow concentrate and expanded mesenchymal stem cell products target early-stage lesions before subchondral collapse. Germany and Switzerland lead European manufacturing capacity expansion under the EMA Advanced Therapy Medicinal Products framework.
- Bisphosphonates:Alendronate and zoledronic acid formulations occupy mature outpatient maintenance protocols.
- Antioxidants:Vitamin E and pentoxifylline regimens address coagulopathy-associated osteonecrosis subtypes.
Volume sits with bisphosphonates; growth tilts toward stem cell therapy.
End User:
Site-of-care economics reshape vendor access, with consolidated health systems capturing premium technologies at the expense of independent facilities.
- Hospitals:Dedicated orthopedic surgical units within major United States health systems anchor procedural volumes for complex core decompression and combined device-biologic interventions. These institutions command full-procedure contracts bundling implants, navigation systems, and biologics.
- Orthopedic Clinics:Ambulatory settings concentrate early-stage diagnosis and pharmaceutical management. Independent clinics face narrowing access to premium technologies as manufacturers prioritize volume commitments from integrated delivery networks.
- Rehabilitation Centers:Post-surgical recovery protocols and mobility restoration programs.
- Research Institutions:Academic medical centers in the United States and South Korea drive clinical trial enrollment for novel regenerative interventions.
Revenue concentrates in hospitals; patient volume expands fastest in orthopedic clinics.
Administration Route:
Delivery technology innovation determines therapeutic index and reimbursement positioning across pharmaceutical and biologic segments.
- Intra-articular:Direct joint space deposition of bisphosphonates and biological agents extends localized drug concentration with reduced systemic exposure. Improved catheter and injection systems are expanding this route into outpatient maintenance regimens previously dominated by oral protocols.
- Intravenous:Zoledronic acid and other potent bisphosphonates require supervised infusion infrastructure.
- Oral:Alendronate and adjunctive antioxidant regimens dominate first-line pharmaceutical management.
- Topical:Transdermal delivery systems remain investigational for osteonecrosis indications.
Oral routes capture patient volume; intra-articular delivery gains share fastest.
Care Setting:
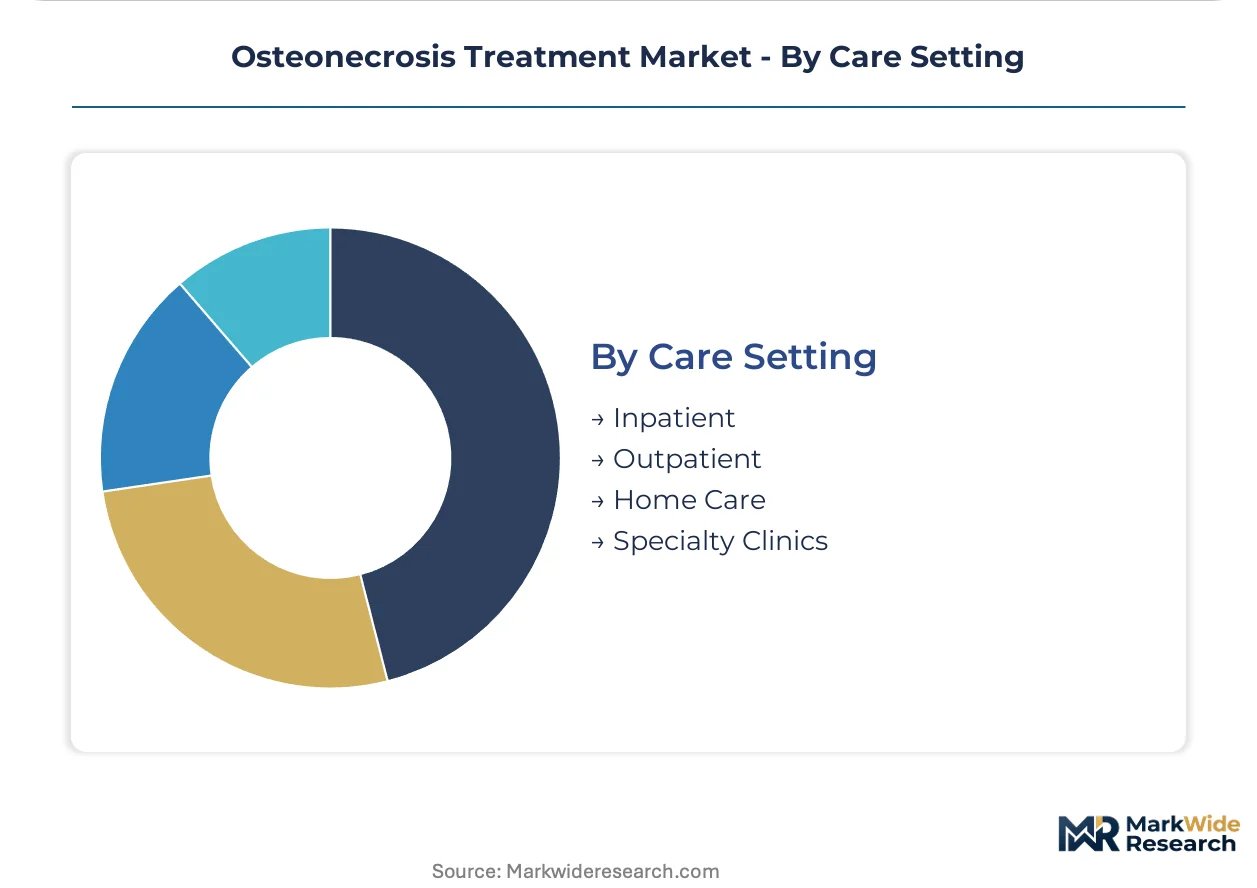
Reimbursement calibration and clinical risk stratification determine where each intervention modality resides across the care continuum.
- Inpatient:Surgical implants and combined device-biologic procedures requiring general anesthesia and post-operative monitoring. United States hospital systems capture these high-acuity cases through dedicated orthopedic units with navigation-assisted surgical platforms.
- Outpatient:Core decompression without biologic augmentation and pharmaceutical maintenance regimens. Ambulatory surgical centers in the United States perform select procedures under local anesthesia, though access to premium implants is narrowing.
- Specialty Clinics:Concentrated expertise in early-stage diagnosis and regenerative medicine protocols.
- Home Care:Oral bisphosphonate adherence monitoring and post-surgical rehabilitation compliance.
Procedural value concentrates inpatient; visit volume shifts outpatient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bone marrow aspirate processing facilities cluster in the American Midwest and German industrial corridors, anchoring autologous cell therapy supply chains for osteonecrosis interventions. Hospital consolidation and regulatory acceleration are reshaping patient access across major therapeutic markets.
United States
Aging demographics and trauma-related osteonecrosis incidence drive procedural volumes in dedicated orthopedic surgical units. The FDA's regenerative medicine advanced therapy designation compresses review timelines for combined device-biologic products. Academic medical centers in Rochester, Minnesota and Boston, Massachusetts anchor clinical trial enrollment for novel stem cell interventions.
Germany
The EMA Advanced Therapy Medicinal Products framework reduces market entry barriers for autologous bone marrow concentrate treatments. Manufacturing capacity expansion concentrates in Baden-Württemberg and Bavaria under stringent GMP compliance requirements. Stuttgart-based processing facilities supply concentrated biologics across Central European hospital networks.
Japan
The PMDA regenerative medicine framework offers expedited approval for combined cell-implant products, creating first-mover advantages for integrated therapeutic platforms. Kobe and Osaka clusters concentrate orthopedic device manufacturing alongside biologic processing capabilities. Domestic demand reflects higher corticosteroid-associated osteonecrosis incidence in hematology patient populations.
Switzerland
Precision machining capabilities in the Basel-Zurich corridor support patient-specific instrumentation for hip reconstruction systems. Swissmedic maintains alignment with EMA guidance while offering specialized pathways for innovative orthopedic biologics. The country's pharmaceutical heritage attracts venture funding for cell therapy manufacturing scale-up.
South Korea
Specialized orthopedic institutes in Seoul and Gyeonggi Province emerge as referral hubs for complex revision procedures, concentrating high-value caseloads. The MFDS accelerates review for navigation-assisted surgical platforms integrating robotic positioning with 3D-printed guides. Domestic health technology assessment bodies recalibrate reimbursement thresholds for cell-based treatments.
Osteonecrosis Treatment Market Competitive Environment
Global majors compete with regional champions across biologic manufacturing and precision instrumentation, creating a tiered structure where scale-driven implant manufacturers face specialized cell therapy developers. The market fragments across pharmaceutical maintenance, surgical hardware, and regenerative medicine segments with divergent capital requirements. Three archetypes dominate: diversified orthopedic conglomerates with full-procedure bundling capabilities, biotech specialists pursuing autologous cell platforms, and generic pharmaceutical manufacturers serving volume-driven bisphosphonate protocols. Competitive moves center on backward integration into cell processing capabilities and strategic partnerships to secure navigation system integration.
Within the diversified orthopedic tier, Zimmer Biomet and Stryker exemplify scale-driven competitors leveraging hospital procurement consolidation. Pfizer occupies a position in the pharmaceutical maintenance segment alongside Merck & Co. Bone Therapeutics SA represents the biotech specialist archetype pursuing regenerative medicine pathways.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Merck & Co. Inc. |
| Novartis AG |
| Bone Therapeutics SA |
| Viatris Inc. |
| Pfizer Inc. |
| Stryker |
| Enzo Biochem Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Bioprocessing engineer concentrations in the German Baden-Württemberg corridor and the American Midwest create labor-cost differentials that widen pricing-tier spreads between GMP-certified autologous cell therapies and standard orthopedic implants. Manufacturers in Switzerland's Basel-Zurich corridor absorb premium wage structures into patient-specific instrumentation pricing, while Asian processing facilities leverage technical workforce availability to compress margins on biologic raw materials.
Pricing Analysis
Service bundling separates premium positioning from unbundled commodity tiers. Three-tier pricing structure across premium, standard, and economy levels dominates: navigation-assisted surgical platforms with full-procedure contracts command premium positioning, precision-machined implants without biologic augmentation occupy standard tiers, and generic bisphosphonate protocols fill economy maintenance roles. Price differentiation hinges on GMP certification tier and after-sales technical support intensity. Cost compression in the standard implant tier is intensifying because hospital procurement committees consolidate vendor relationships around volume commitments. Independent ambulatory surgery centers exhibit highest price sensitivity; integrated delivery networks demonstrate lowest sensitivity due to bundled payment model insulation.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA regenerative medicine framework and South Korea's MFDS guidance are reshaping sourcing patterns for combined device-biologic products toward local manufacturing footprints. Bone marrow aspirate processing capabilities concentrate in the United States, Germany, and Switzerland. Raw material dependencies center on concentrated bone marrow aspirate, 3D-printable titanium alloys, and mesenchymal stem cell expansion media. Single-source vulnerability in autologous cell therapy supply chains stems from limited GMP-compliant cleanroom infrastructure. Distribution runs through integrated delivery network procurement committees that bundle implants, biologics, and navigation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Control over autologous cell processing capabilities has become the decisive upstream lever as FDA regenerative medicine pathways compress development timelines.
For Market Incumbents: To counter biotech specialists capturing regenerative medicine market share, orthopedic conglomerates must secure backward integration into cell processing capabilities through acquisition or in-licensing. Capacity addition in German and Swiss GMP manufacturing corridors anchors European supply security. Certification investment in FDA regenerative medicine advanced therapy designation accelerates combined device-biologic product timelines. For New Entrants and Emerging Players: Launch via specialty clinic partnerships targeting early-stage diagnosis and pharmaceutical management in underpenetrated Japanese and South Korean markets. The most penetrable segment is ambulatory core decompression without biologic augmentation, where independent surgery centers face narrowing access to premium technologies. A direct-to-clinic biologic concentrate distribution model bypasses hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: The window for entry favors biotech specialists with autologous cell platforms and GMP manufacturing scale-up capabilities over pure-play device manufacturers. Long-term viability hinges on regulatory approval velocity and reimbursement threshold negotiation success. The signal to watch is health technology assessment body recalibration of value metrics for cell-based treatments in major European markets.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Autologous cell therapy production requires cleanroom infrastructure that demands substantial capital deployment. |
| FDA Regenerative Medicine Advanced Therapy Designation | Compressed review timelines redirect venture funding toward integrated therapeutic platforms. |
| Hospital System Partnership | Full-procedure contracts bundling implants, biologics, and navigation systems consolidate vendor access. |
| CE Marking Pathway | EMA Advanced Therapy Medicinal Products framework reduces market entry barriers for European expansion. |
| Reimbursement Strategy | Health technology assessment body engagement determines patient access to novel regenerative interventions. |
Study Parameters
Document review covered FDA 510(k) filings, EMA Advanced Therapy Medicinal Products submissions, ClinicalTrials.gov enrollment data, and hospital procurement databases, complemented by interviews with orthopedic surgeons, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at biologic manufacturers. Secondary validation drew from CMS Medicare reimbursement data, SEC 10-K orthopedic segment disclosures, and formulary placement records. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates.
Segmented outputs across the projection horizon reflect treatment modality, Ficat disease stage, administration route, and care setting. CAGRs were derived from patient population epidemiology, procedural volume trends, and pricing trajectory assumptions. Industry-specific forecast inputs incorporated MRI-based staging protocol adoption rates and navigation-assisted surgical platform penetration curves.
Regulatory approval delays, reimbursement threshold rigidity, and cell therapy manufacturing scale-up failures are the dominant revision risks that could compress or extend forecast ranges. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Canine Orthopedics Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Costochondritis Market
Orthopedics
Orthopedics Market
Orthopedics
US Arthritis Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Athletic Knee Treatment Market