
 Rotator Cuff Arthropathy Repair Market | 2026-2036
Rotator Cuff Arthropathy Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Rotator Cuff Arthropathy Repair Market Analysis
Ambulatory surgical centers is expanding their share of rotator cuff arthropathy procedures as payors push same-day discharge protocols and minimally invasive techniques mature. Arthrex, Inc. leverages its broad suture anchor portfolio and surgeon education platforms to sustain loyalty among sports medicine specialists. Stryker Corporation anchors its position through integrated operating room systems that pair visualization with powered instrumentation. Smith & Nephew plc competes in the biologics augmentation segment with collagen-based repair matrices.
Rotator cuff arthropathy repair encompasses surgical and non-surgical interventions for degenerative shoulder conditions arising from chronic tendon insufficiency, including reverse total shoulder arthroplasty, superior capsular reconstruction, and patch augmentation using human dermal allograft or porcine submucosa. The primary purpose is restoring glenohumeral joint mechanics and pain-free range of motion in patients with irreparable tendon tears. Surgical Options command the largest revenue share due to implant intensity and OR utilization, while Rehabilitation Equipment represents the fastest-growing segment as bundled payment models extend accountability into post-acute recovery. Outpatient delivery mode is gaining structural share as anesthesia protocols and regional nerve blocks enable safe same-day discharge.
FDA 510(k) and PMA pathways govern device clearance, while ISO 13485 quality management standards shape supplier qualification for orthopedic manufacturers. The Centers for Medicare & Medicaid Services reimbursement thresholds directly determine site-of-service economics and physician practice patterns. Stakeholders must monitor how CMS site-neutral payment proposals and FDA biologics classification guidance reshape competitive positioning between synthetic implants and allograft-derived alternatives.
Market Dynamics
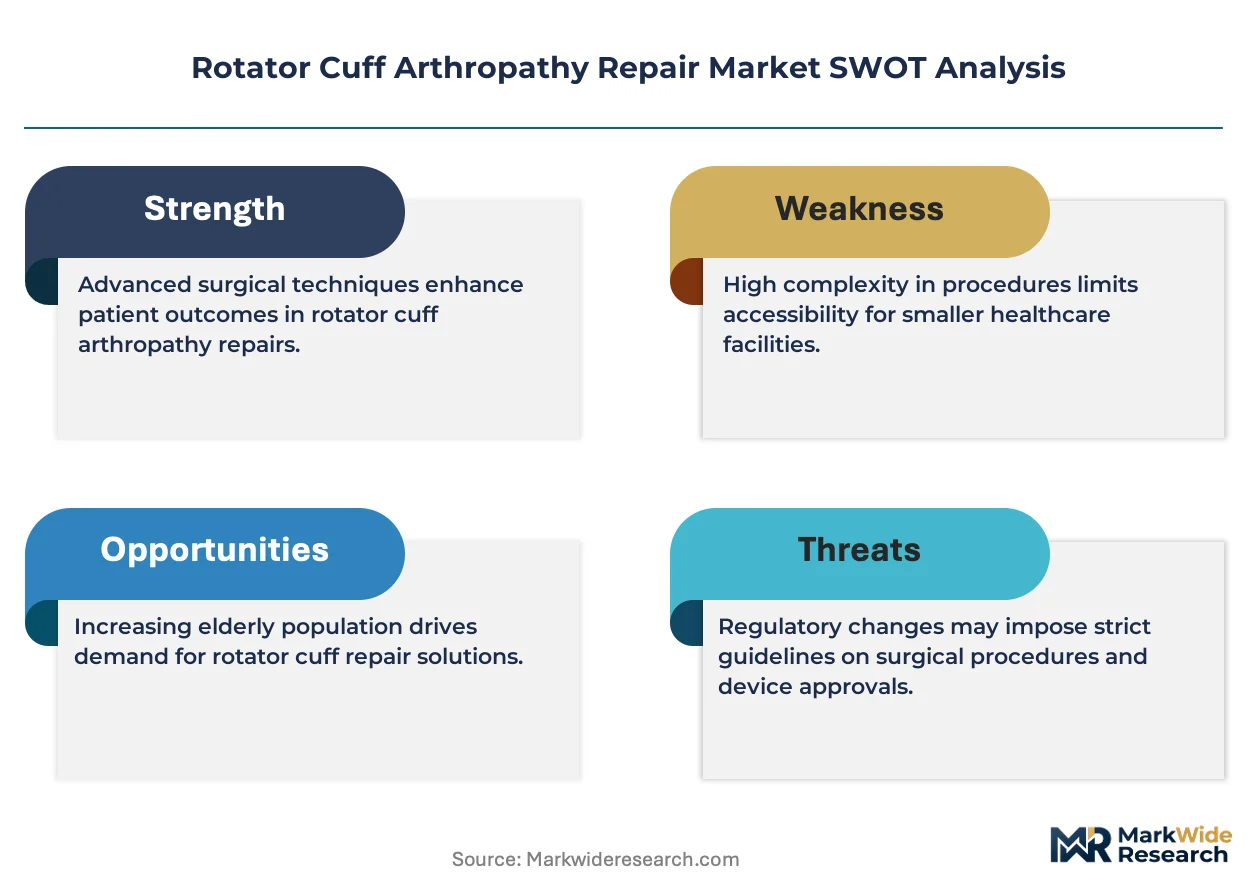
CMS site-neutral payment proposals are compressing reimbursement differentials between hospital outpatient departments and ambulatory surgical centers, forcing manufacturers to recalibrate pricing architectures across delivery settings.
Growth Catalysts
- Regional nerve block protocols:Advanced anesthesia techniques enable same-day discharge for reverse total shoulder arthroplasty, expanding procedural candidacy to higher-acuity patients previously requiring inpatient stays.
- FDA 510(k) clearance streamlining:Expedited pathways for biologic augmentation devices accelerate commercialization timelines for collagen-based repair matrices and human dermal allografts.
- Aging demographics in the United States:The 65-plus population concentration in Sun Belt states sustains procedural volume growth for degenerative shoulder conditions.
Market Restraints
- Allograft supply concentration:Human tissue processing depends on a limited network of accredited tissue banks, creating vulnerability to supply interruptions.
- Implant cost intensity:Reverse total shoulder arthroplasty systems require cobalt-chrome and titanium components subject to commodity price volatility.
- Technical limitation:Irreparable massive rotator cuff tears in patients with preserved active elevation remain contraindications for standard repair techniques.
Strategic Opportunities
- Underpenetrated geography:Rural United States markets lack sufficient orthopedic surgeon density, creating white space for telemedicine-enabled preoperative screening and mobile surgical units.
- Technology convergence:Patient-specific instrumentation derived from preoperative CT scanning is unifying with augmented reality navigation to reduce glenoid component malposition rates.
- Distribution innovation:Direct-to-ambulatory surgical center consignment models bypass traditional hospital supply chain markups.
Industry Challenges
- Surgeon training pipelines:Fellowship programs in shoulder and elbow surgery produce insufficient specialists to match procedural demand growth.
- Biologics classification uncertainty:FDA guidance ambiguity between device and biologic regulatory pathways delays product development timelines for patch augmentation materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotator Cuff Arthropathy Repair Market |
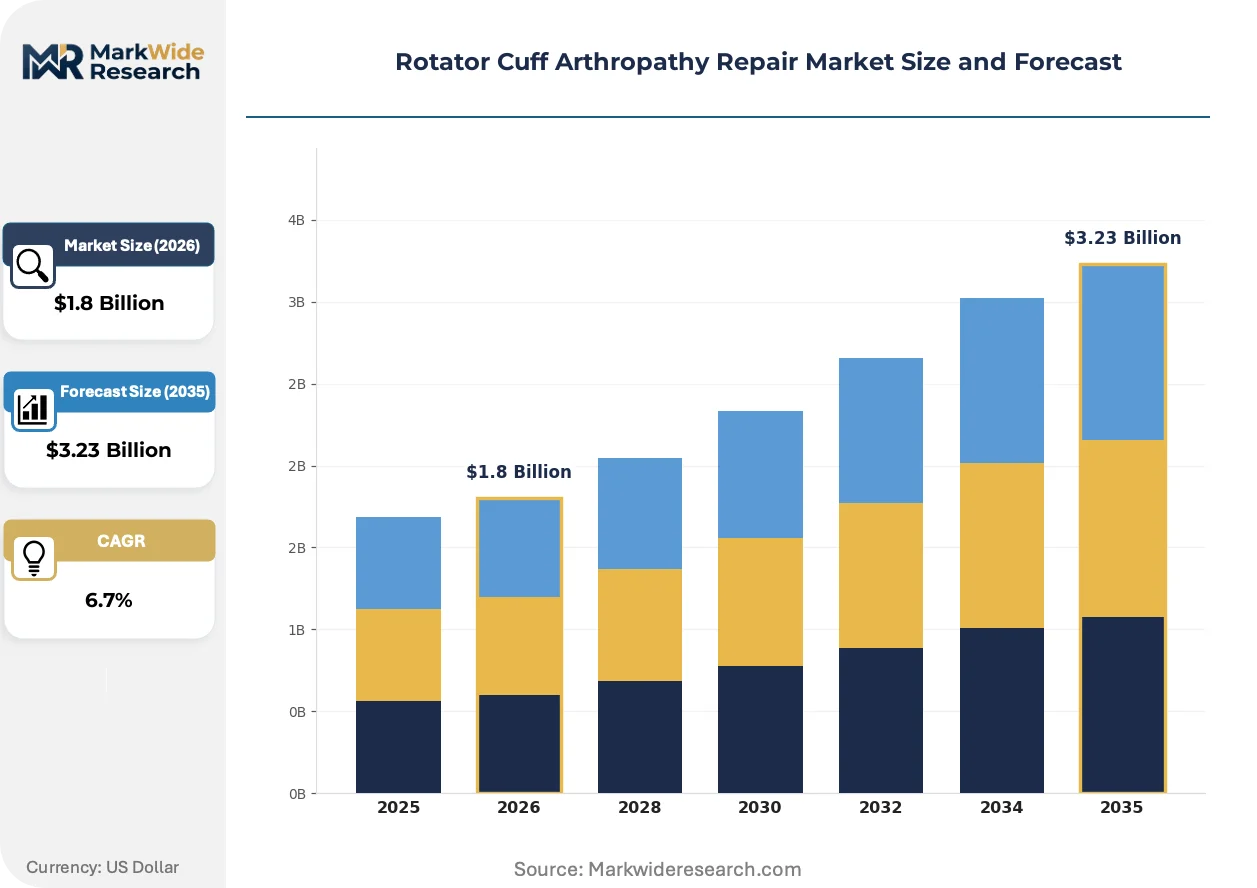
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Options, Non-surgical Methods, Rehabilitation Equipment, Diagnostic Tools Therapy Area: Orthopedic Surgery, Physical Therapy, Pain Management, Sports Medicine Delivery Mode: Inpatient, Outpatient, Home Care, Telehealth Services End User: Hospitals, Clinics, Rehabilitation Centers, Home Health Agencies |
| Companies Covered | Arthrex, Inc., Johnson & Johnson (DePuy Synthes), Zimmer Biomet Holdings, Inc., Stryker Corporation, Smith & Nephew plc, Wright Medical, Integra LifeSciences Corporation, DJO Global, Limacorporate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotator Cuff Arthropathy Repair Market Emerging Trajectories
Shoulder repair markets are experiencing convergence between implant engineering and biological augmentation, with procedural economics increasingly tied to post-acute recovery accountability rather than intraoperative device selection alone.
In situ tissue engineering through bioinductive collagen implants is unifying tendon-to-bone healing biology with arthroscopic delivery techniques. Sports medicine specialists at high-volume ambulatory centers are adopting these scaffolds for partial-thickness tears. The technology is unifying previously distinct surgical categories—debridement and repair—into single-procedure solutions.
EU Medical Device Regulation (MDR) transition deadlines are forcing recertification of suture anchor portfolios originally cleared under the Medical Device Directive. Notified body capacity constraints extend timeline uncertainty for manufacturers with legacy product lines. European orthopedic distributors are consolidating supplier relationships to reduce regulatory compliance fragmentation.
Bundle payment accountability is extending surgeon economic interest into postoperative physical therapy duration and outcomes. Hospital outpatient departments are unbundling implant costs from facility fees to compete with ambulatory surgical center pricing. This behavioral shift is most visible in Medicare Advantage plan networks across the United States, where episode-based contracts now cover 90-day recovery periods.
Rotator Cuff Arthropathy Repair Market Segmentation
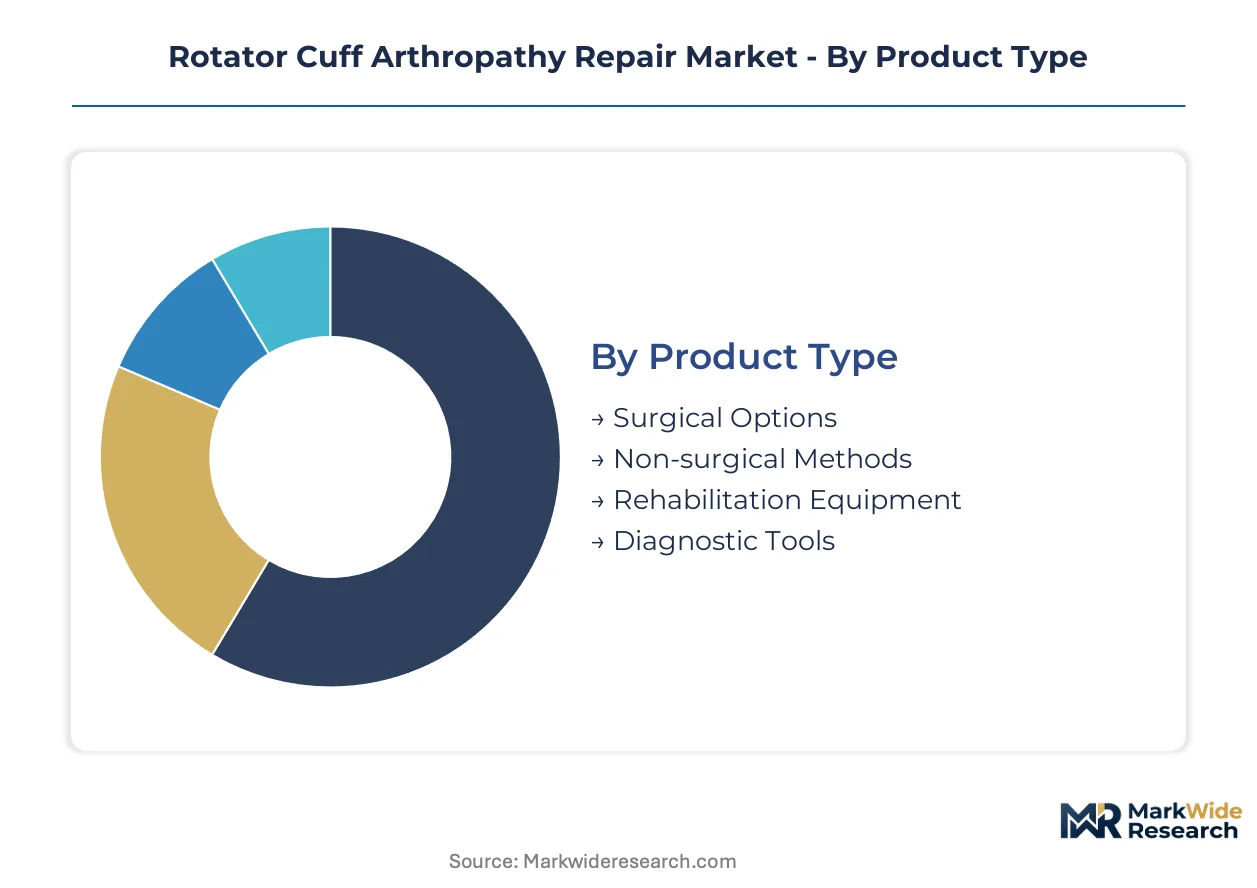
Segmentation in rotator cuff arthropathy repair reveals distinct procurement patterns across surgical versus conservative care pathways. Product type splits between implant-intensive procedures and equipment-driven rehabilitation, while delivery mode reflects site-of-service economics reshaping where procedures occur.
Product Type:
Volume concentration favors high-utilization surgical hardware, while premium pricing attaches to biologic augmentation and advanced rehabilitation systems.
- Surgical Options:Reverse total shoulder arthroplasty systems, suture anchors, and patch augmentation devices using human dermal allograft or porcine submucosa. Demand concentrates in ambulatory surgical centers across Florida, Texas, and Arizona as same-day discharge protocols expand procedural candidacy for aging populations.
- Rehabilitation Equipment:Continuous passive motion devices, resistance training systems, and cryotherapy units prescribed for postoperative recovery. This segment is expanding most quickly under bundled payment models that extend provider accountability into 90-day recovery periods.
- Non-surgical Methods:Corticosteroid injections, platelet-rich plasma therapies, and viscosupplementation for early-stage degeneration.
- Diagnostic Tools:MRI systems, ultrasound devices, and arthroscopic visualization equipment for preoperative planning.
Mature deployment sits with Surgical Options. Newer deployment is concentrated in Rehabilitation Equipment.
Therapy Area:
Application focus determines reimbursement coding complexity and specialist training requirements across the care continuum.
- Orthopedic Surgery:Arthroscopic and open procedures addressing irreparable tendon tears, including superior capsular reconstruction and tendon transfers. Demand clusters in metropolitan surgical corridors with fellowship-trained shoulder specialists.
- Sports Medicine:Arthroscopic repair techniques for partial-thickness tears in active populations, emphasizing biological augmentation and rapid return-to-play protocols. This segment is climbing the fastest as bioinductive collagen implants unify debridement and repair into single-procedure solutions.
- Physical Therapy:Structured protocols for range-of-motion restoration and rotator cuff strengthening.
- Pain Management:Interventional techniques including suprascapular nerve blocks and radiofrequency ablation.
Established practice patterns dominate Orthopedic Surgery. Emerging technique adoption centers on Sports Medicine.
Delivery Mode:
Customer type stratification separates institutional purchasers from direct-to-patient service models.
- Outpatient:Ambulatory surgical centers and hospital outpatient departments performing same-day arthroplasty and arthroscopy. Regional nerve block protocols enable discharge for procedures previously requiring overnight stays.
- Inpatient:Acute care hospitals managing complex revisions, infection complications, and patients with significant comorbidities requiring monitoring.
- Home Care:Visiting nurse services and home-based physical therapy for postoperative monitoring.
- Telehealth Services:Remote preoperative screening and postoperative follow-up consultations.
Structural share is shifting toward Outpatient as CMS site-neutral payment proposals compress reimbursement differentials.
End User:
Procurement scale separates high-volume integrated delivery networks from independent specialty practices.
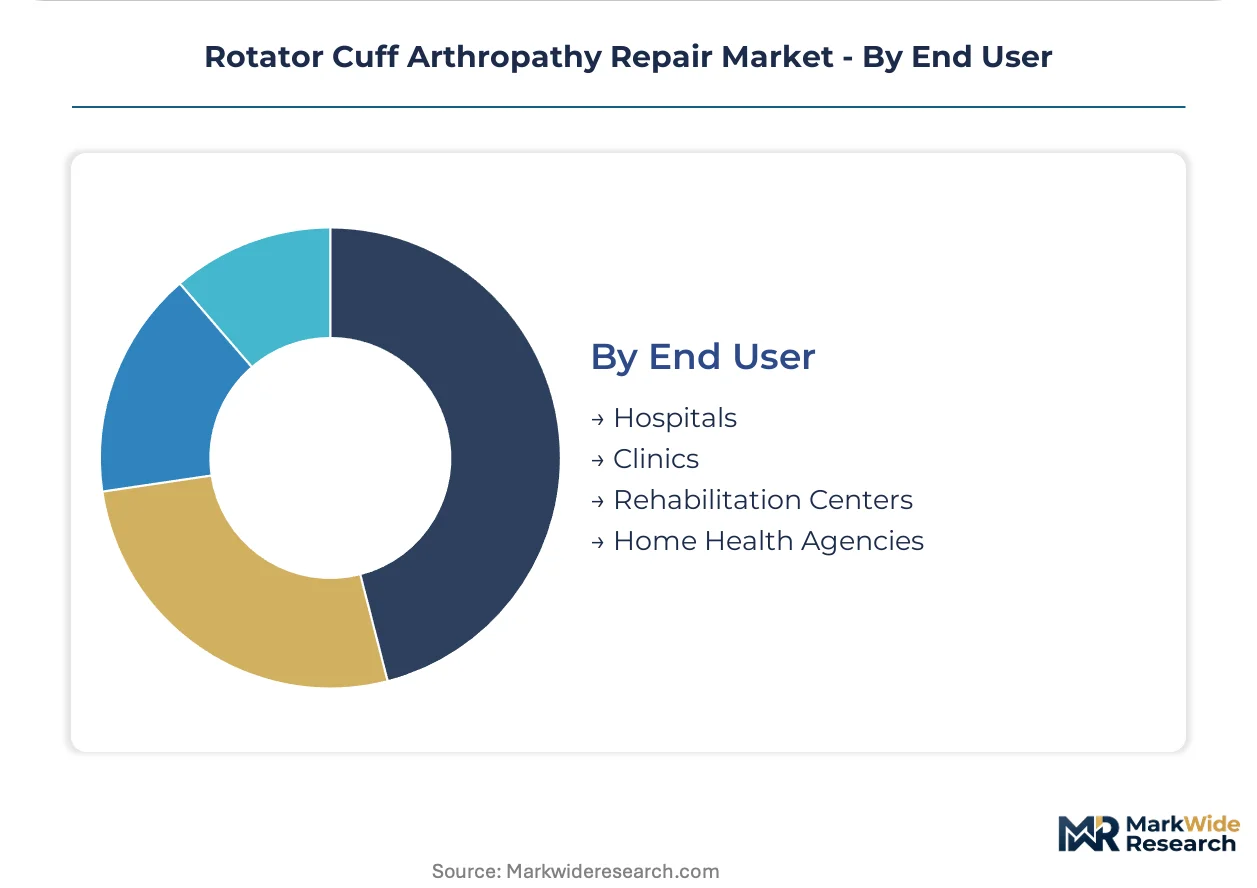
- Hospitals:Academic medical centers and community hospitals with inpatient orthopedic service lines. These facilities negotiate implant costs through group purchasing organizations and maintain emergency backup capacity for surgical complications.
- Clinics:Orthopedic specialty practices and multispecialty groups performing office-based injections and preoperative evaluations. Steepest expansion trajectory appears in clinic-based ultrasound-guided procedures that reduce referral leakage.
- Rehabilitation Centers:Dedicated physical therapy facilities and skilled nursing facilities with orthopedic rehabilitation units.
- Home Health Agencies:Medicare-certified agencies providing postoperative nursing and therapy in patient residences.
Capital-intensive infrastructure concentrates in Hospitals. Agile service expansion characterizes Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Florida and Arizona concentrate rotator cuff arthropathy repair demand through tax-advantaged manufacturing clusters and aging population corridors. These zones attract orthopedic device assembly operations while Sun Belt retirement migration sustains procedural volume growth.
United States
FDA 510(k) clearance pathways accelerate biologic augmentation device commercialization for collagen-based repair matrices. CMS site-neutral payment proposals compress reimbursement differentials between hospital outpatient departments and ambulatory surgical centers. The Tampa-Orlando corridor in Florida hosts high-volume shoulder surgery centers performing same-day reverse total shoulder arthroplasty.
Germany
EU Medical Device Regulation transition deadlines force recertification of suture anchor portfolios under stricter notified body oversight. The country's statutory health insurance system maintains fixed procedure tariffs that constrain implant pricing flexibility. The Baden-Württemberg medical technology cluster around Tuttlingen concentrates arthroscopic instrument manufacturing.
Japan
PMDA regulatory timelines for novel biologic devices extend commercialization cycles compared to Western markets. The aging population in Kansai and Kanto regions drives degenerative shoulder condition prevalence. Osaka-based orthopedic distributors consolidate supplier relationships to reduce EU MDR compliance fragmentation.
Australia
TGA approval requirements for human dermal allografts create regulatory bottlenecks for patch augmentation materials. Medicare reimbursement schedules favor conservative management before surgical intervention. Sydney and Melbourne surgical corridors concentrate fellowship-trained shoulder specialists performing superior capsular reconstruction.
Brazil
ANVISA medical device registration pathways for imported orthopedic implants extend market entry timelines. Private health insurance penetration in São Paulo and Rio de Janeiro determines access to reverse total shoulder arthroplasty. Southeastern metropolitan surgical centers adopt regional nerve block protocols to enable same-day discharge.
Rotator Cuff Arthropathy Repair Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with implant-intensive surgical options consolidating around integrated device portfolios while rehabilitation equipment remains fragmented among regional fabricators. The vendor base organizes into three archetypes: full-line orthopedic conglomerates with arthroscopy-to-arthroplasty portfolios, biologics-focused augmentation specialists, and regional equipment manufacturers serving post-acute recovery. M&A activity concentrates on biologics capabilities and ambulatory surgical center distribution networks, while strategic partnerships target patient-specific instrumentation and augmented reality navigation convergence.
Within the full-line orthopedic tier, Arthrex, Inc. and Stryker Corporation occupy positions exemplifying divergent competitive vectors—suture anchor breadth versus integrated operating room system dominance. Smith & Nephew plc represents the biologics augmentation specialist archetype, anchoring collagen-based repair matrix development.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Johnson & Johnson (DePuy Synthes) |
| Zimmer Biomet Holdings, Inc. |
| Stryker Corporation |
| Smith & Nephew plc |
| Wright Medical |
| Integra LifeSciences Corporation |
| DJO Global |
| Limacorporate |
| Others |
Supply Flow & Price Mechanics
Cobalt-chrome and titanium commodity price indices cascade through rotator cuff arthropathy repair supply chains, compressing margins on reverse total shoulder arthroplasty systems while concentrating pricing power among manufacturers with captive alloy sourcing. This raw material volatility stratifies procurement tiers, with hospital systems absorbing cost pass-throughs and ambulatory surgical centers demanding consignment models that shift inventory risk upstream.
Pricing Analysis
Lead-time premiums attach to expedited delivery of patient-specific instrumentation and bioinductive collagen implants, while spot inventory of standard suture anchors trades at modest discounts. A three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biologic augmentation matrices from unbranded allograft alternatives and commodity fixation hardware. Price differentiation hinges on ISO 13485 certification tier and surgeon training bundling. Cost compression in economy-tier anchors is intensifying because group purchasing organizations consolidate contract volumes. Ambulatory surgical centers exhibit highest price sensitivity due to CMS site-neutral payment compression, while academic medical centers prioritize outcomes data over unit cost.
Supply Chain Analysis
Regional distribution centers in Florida, Arizona, and Texas operate hub-and-spoke patterns serving Sun Belt ambulatory surgical corridors with same-day implant availability. Manufacturing concentrates in the United States, Germany, and Switzerland for precision-machined arthroplasty components, while human tissue processing draws from a limited network of accredited tissue banks in the United States and Netherlands. Raw material dependencies span cobalt-chrome alloys, titanium forgings, and processed human dermal matrix. Single-source vulnerability in allograft supply creates interruption risk during tissue bank accreditation cycles. Distribution runs through orthopedic specialty distributors with consignment inventory at high-volume surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotator cuff arthropathy repair operates as a supply-constrained market where accredited tissue bank capacity limits allograft-derived patch augmentation availability, propping pricing for synthetic biologic alternatives. This bottleneck sustains margin structures despite CMS reimbursement compression.
For Market Incumbents: Deepen backward integration into cobalt-chrome and titanium alloy sourcing to buffer commodity volatility eroding arthroplasty system margins. Expand surgeon education platform investments to defend loyalty against bioinductive collagen implant substitutes. Add capacity in Arizona and Florida distribution nodes to capture ambulatory surgical center volume shifting from hospital outpatient departments. For New Entrants and Emerging Players: The premium-to-economy tier price gap in suture anchors offers entry space for mid-priced synthetic augmentation scaffolds with 510(k) clearance efficiency. Target rural United States markets lacking orthopedic surgeon density through telemedicine-enabled preoperative screening partnerships. Pursue direct-to-ambulatory surgical center consignment models that bypass hospital supply chain markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor biologics augmentation specialists with EU MDR recertification progress in Germany and Switzerland manufacturing clusters. Long-term viability across the projection horizon rests on convergence between patient-specific instrumentation and augmented reality navigation capabilities. Monitor FDA biologics classification guidance clarity as the inflection signal for patch augmentation material development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited biologic augmentation device entry accelerates collagen-based repair matrix commercialization timelines. |
| Surgeon Education Platform Investment | Arthrex-style training loyalty programs defend market position against integrated operating room competitors. |
| Direct-to-ASC Consignment Model | Bypassing hospital supply chain markups captures volume shifting to same-day discharge protocols. |
| Patient-Specific Instrumentation Development | CT-derived surgical guides reduce glenoid component malposition rates in reverse total shoulder arthroplasty. |
| EU MDR Recertification Acceleration | Notified body capacity constraints favor early filers with legacy suture anchor portfolios. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, and EU MDR notified body filings, complemented by interviews with orthopedic surgeons, ambulatory surgical center administrators, group purchasing organization contract managers, and biomedical engineers. Secondary validation drew from hospital procurement databases, GPO pricing benchmarks, and accredited tissue bank supply reports. Bottom-up procedure volume estimates triangulated against top-down implant manufacturer revenue attribution across product categories.
Segment-level outputs across surgical options, rehabilitation equipment, and biologic augmentation categories were generated through the analysis window using procedure volume projections, implant intensity coefficients, and site-of-service shift assumptions. Modeled dimensions included product type, therapy area, delivery mode, and end user procurement scale. CAGRs were derived from regression analysis of historical procedural growth rates adjusted for demographic and reimbursement scenario variables. Forecast inputs incorporated regional nerve block protocol adoption curves and bundled payment penetration assumptions.
Inputs from CMS, FDA, and EU notified body databases were available through the study window; gaps in real-time allograft supply chain transparency introduce uncertainty bands around biologic augmentation segment projections. Forecasts reflect documented assumptions regarding anesthesia protocol maturation and site-neutral payment implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Osteoporosis Treatment Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Tendon Repair Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Kyphosis Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Podiatry Services Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
United States Orthopedic Braces and Support Market