
 Cancer Immunotherapy Drug Discovery Outsourcing Market | 2026-2036
Cancer Immunotherapy Drug Discovery Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Immunotherapy Drug Discovery Outsourcing Market Intelligence
Modular service bundling is hardening as the dominant procurement pattern in cancer immunotherapy outsourcing. Buyers now package preclinical immunogenicity assessment with companion biomarker development under single master agreements. Covance, Inc. leverages its integrated toxicology and clinical pharmacology footprint to anchor these bundled relationships. GenScript Biotech Corporation competes through specialized gene-editing reagent supply chains that feed directly into client CRISPR workflows.
Cancer immunotherapy drug discovery outsourcing encompasses the contracted execution of target validation, lead optimization, and regulatory-enabling studies for immune-modulating therapeutics, typically involving humanized mouse models, multi-parameter flow cytometry panels, and GMP-compliant cell banking. Its commercial purpose is to compress development timelines for biologics and cell therapies while transferring fixed-cost laboratories to variable-fee partners. Preclinical services command the largest revenue share given the complexity of syngeneic and humanized tumor model development, while artificial intelligence segments attract the fastest expansion as machine learning reshapes epitope prediction and patient stratification algorithms. Cell therapy application work concentrates margin pools due to the specialized cleanroom infrastructure and vector manufacturing expertise required.
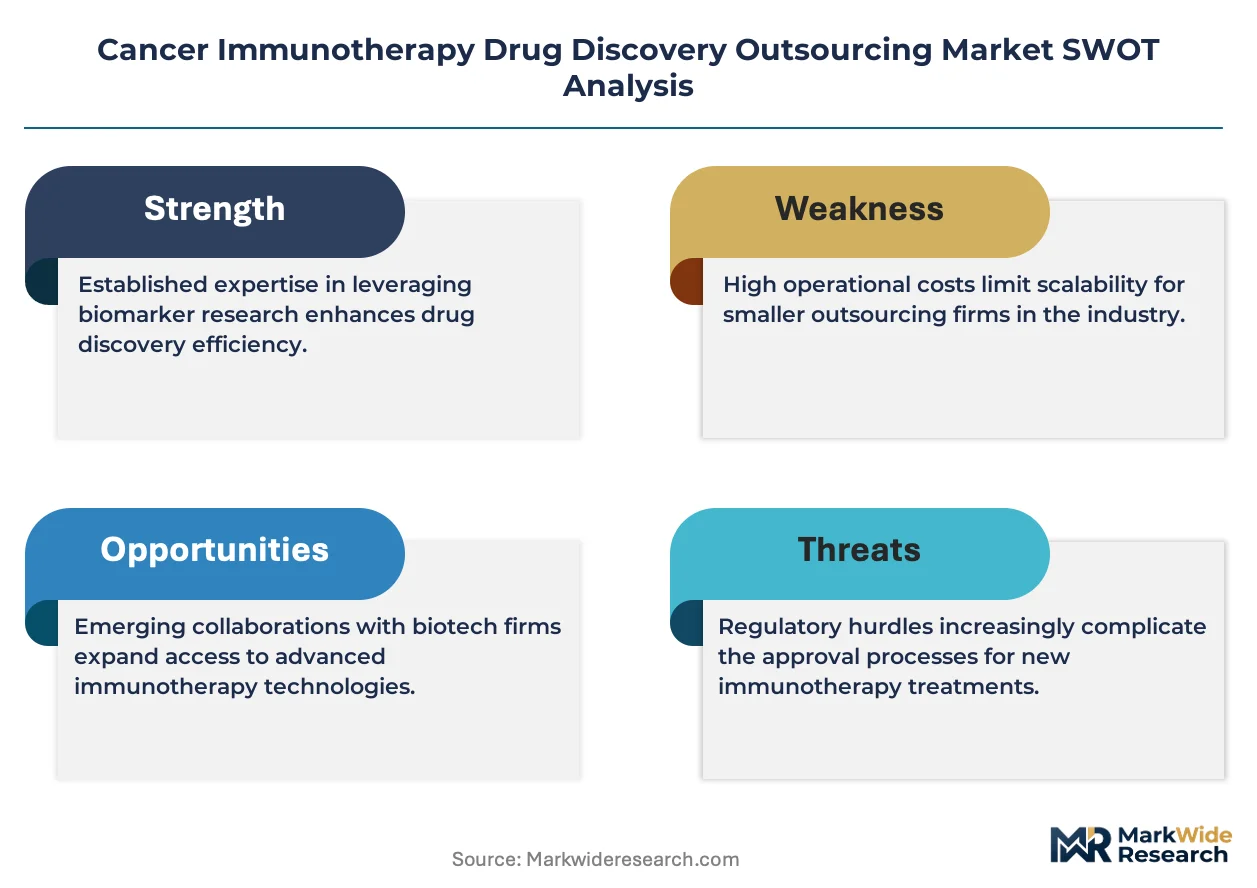
FDA guidelines on chimeric antigen receptor T-cell therapy development and EMA's ATMP classification framework shape trial design standards and CMC documentation requirements across outsourced programs. ISO 15189 accreditation and OECD GLP principles further govern laboratory quality systems that determine market access for contract providers. Stakeholders must weigh captive investment in automated cell culture platforms against the flexibility of multi-vendor outsourcing networks as pipeline modalities diversify beyond monoclonal antibodies into T-cell engagers and allogeneic cell products.
Market Dynamics
Modular service bundling now hardens procurement patterns as biotech firms compress development timelines for CAR-T and bispecific antibody programs. FDA's Project Optimus reshapes dose-optimization requirements, forcing contract providers to integrate toxicology and biomarker capabilities under single master agreements.
Growth Catalysts
- FDA Project Optimus:Oncology dose-optimization mandates drive demand for integrated pharmacology and biomarker development services under unified outsourcing contracts.
- CRISPR workflows:Gene-editing reagent supply chains feed directly into client discovery pipelines, accelerating target validation timelines for immuno-oncology programs.
- Boston-San Francisco corridor:Biotech firm concentration in these clusters generates sustained outsourcing volume for specialized cell therapy infrastructure.
Market Restraints
- GMP cleanroom scarcity:Limited qualified manufacturing space for viral vectors and allogeneic cell products concentrates supply risk among specialized providers.
- ISO 15189 compliance costs:Laboratory accreditation requirements impose fixed-cost burdens that disadvantage smaller contract research organizations.
- Humanized mouse model complexity:Syngeneic and patient-derived xenograft development requires extended timelines and specialized breeding facilities.
Strategic Opportunities
- Artificial intelligence integration:Machine learning convergence with epitope prediction and patient stratification algorithms opens new service revenue streams.
- T-cell engager modalities:Bispecific antibody programs beyond monoclonal antibodies create demand for novel immunogenicity assessment capabilities.
- EMA ATMP framework alignment:Advanced therapy medicinal product classification standards enable cross-border trial design standardization for European sponsors.
Industry Challenges
- Vector manufacturing expertise gap:Lentiviral and retroviral production requires scarce talent pools with GMP gene therapy experience.
- Multi-parameter flow cytometry standardization:Panel design variability across contract providers complicates cross-study data integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Immunotherapy Drug Discovery Outsourcing Market |
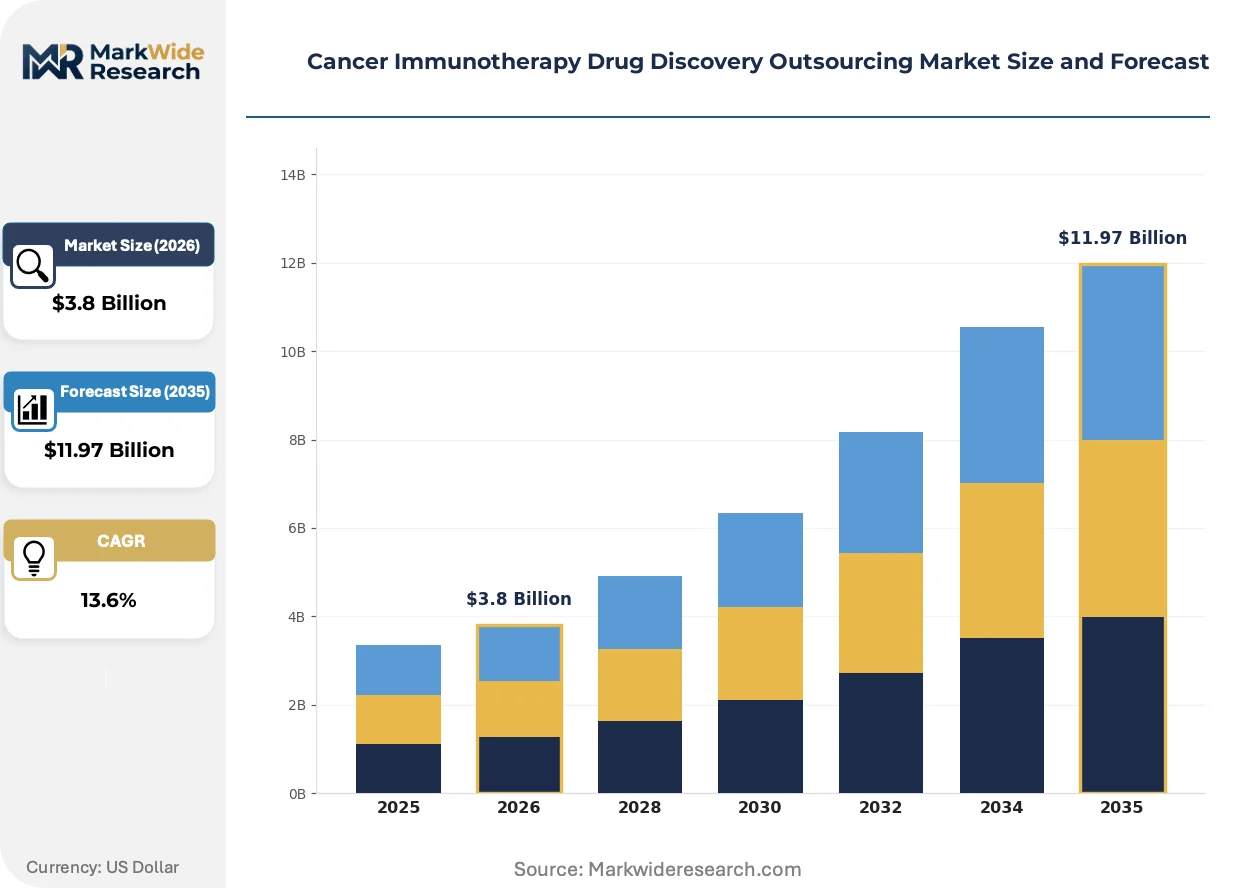
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preclinical Services, Clinical Trial Management, Data Analysis, Regulatory Support Application: Monoclonal Antibodies, Cell Therapy, Oncolytic Virus Therapy, Vaccine Development Technology: CRISPR, Artificial Intelligence, Bioinformatics, Genomics End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Contract Research Organizations |
| Companies Covered | Covance, Inc., STC Biologics, Personalis, Inc., ImmunXperts SA, Celentyx Ltd., GenScript Biotech Corporation, BPS Bioscience, Inc., Crown Bioscience, Inc., Horizon Discovery Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Immunotherapy Drug Discovery Outsourcing Market Strategic Shifts & Innovations
Artificial intelligence is compressing discovery timelines while regulatory frameworks force tighter integration between preclinical and clinical service modules. Three developments reshape competitive positioning.
Machine learning platforms are decentralizing epitope prediction and patient stratification workflows. Mid-tier biotech firms adopt cloud-based immunoinformatics tools at accelerating pace. This technology is decentralizing analytical capabilities previously concentrated at large pharmaceutical captive labs.
EMA's ATMP classification framework tightens chemistry-manufacturing-controls documentation requirements for cell and gene therapy sponsors. Contract providers must reconfigure quality systems to support modular trial submissions. European oncology programs face the steepest compliance ramps as they adapt to combined advanced therapy and oncology guidelines.
Buyers now unbundle after-sales technical support from core discovery contracts. Specialized bioinformatics consulting and regulatory strategy services separate from wet-laboratory execution. This pattern concentrates most visibly among Boston-area immuno-oncology startups with lean internal teams.
Cancer Immunotherapy Drug Discovery Outsourcing Market Segmentation
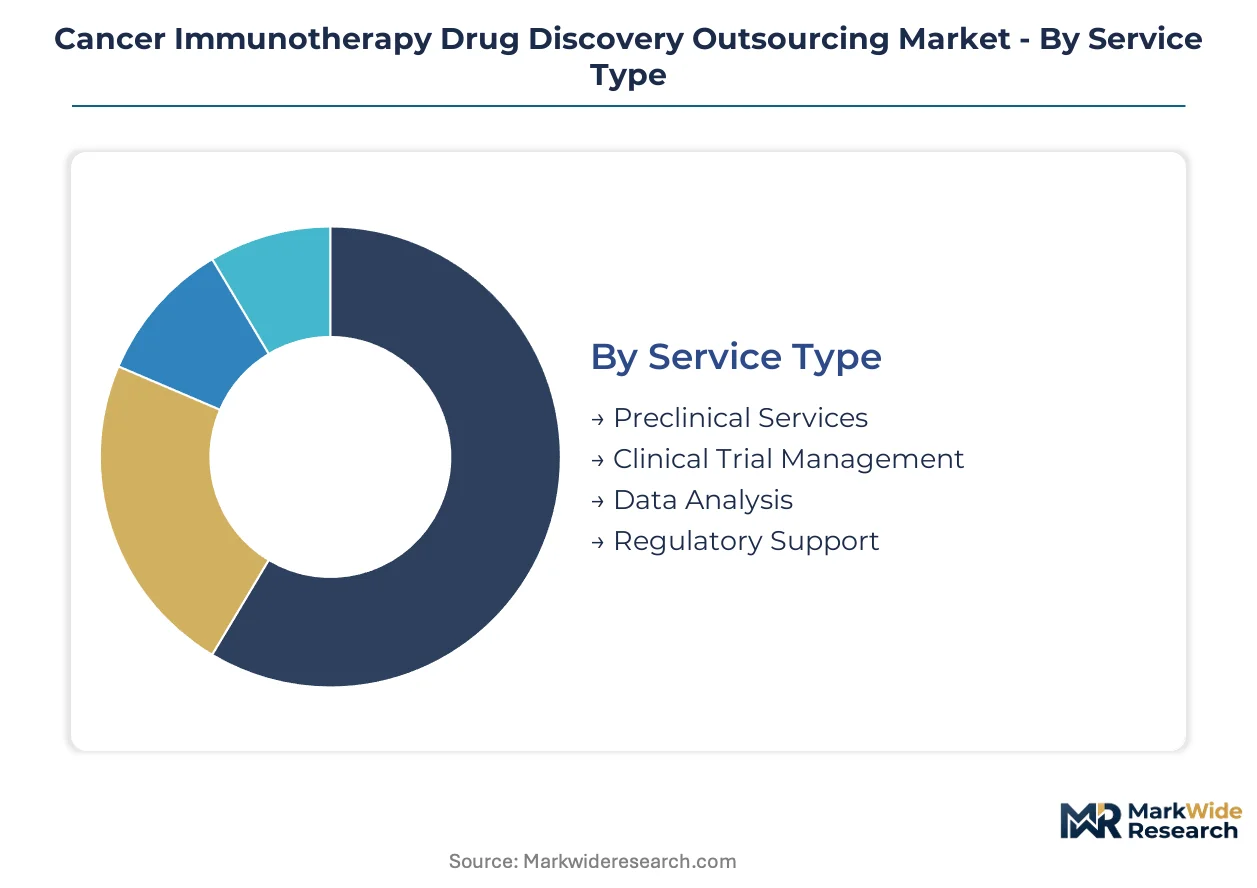
Segmentation in cancer immunotherapy outsourcing reveals how service complexity, modality diversity, and buyer sophistication create distinct procurement patterns. Contract providers must align capabilities with the technical depth and regulatory intensity each segment demands.
Service Type:
Buyers differentiate primarily by internal capability gaps versus timeline pressure, with preclinical-heavy biotechs seeking end-to-end partnerships while larger pharmas unbundle specific functions.
- Preclinical Services:Syngeneic tumor model development, humanized mouse engineering, and immunogenicity assessment form the technical core. Demand concentrates among Boston and San Francisco biotech corridors where CAR-T programs require specialized cleanroom infrastructure and GMP-compliant cell banking capabilities.
- Clinical Trial Management:Dose-optimization protocol design under FDA Project Optimus mandates integrates pharmacology and biomarker workflows. Sponsors in the United States contract these as unified modules to compress IND-to-Phase I timelines.
- Data Analysis:Multi-parameter flow cytometry panel interpretation and immunoinformatics pipeline execution support regulatory submissions.
- Regulatory Support:CMC documentation for EMA ATMP classification and FDA gene therapy guidance navigates modular trial submissions.
Volume sits with Preclinical Services; growth tilts toward Clinical Trial Management.
Application:
Modality maturity shapes outsourcing intensity, with established antibody platforms using selective contracting while novel cell and viral therapies demand captive infrastructure partnerships.
- Cell Therapy:Allogeneic and autologous CAR-T programs require lentiviral vector manufacturing, patient-specific cell processing, and cryopreservation logistics. Scarcity of qualified GMP cleanroom space in the United States concentrates supply risk among specialized providers serving academic medical centers and venture-backed startups.
- Monoclonal Antibodies:Humanization, affinity maturation, and Fc engineering follow standardized workflows. Large pharmaceutical sponsors in the United States retain these capabilities in-house or source selectively.
- Oncolytic Virus Therapy:Replication-competent viral vector production and potency assay development demand biosafety level containment expertise.
- Vaccine Development:Neoantigen prediction and personalized cancer vaccine manufacturing integrate bioinformatics with cell therapy infrastructure.
Revenue concentrates in Cell Therapy; expansion accelerates fastest in Oncolytic Virus Therapy.
Technology:
Adoption velocity separates segments, with cloud-deployed tools penetrating mid-tier biotechs faster than capital-intensive laboratory automation.
- Artificial Intelligence:Machine learning platforms for epitope prediction and patient stratification decentralize capabilities previously held at large pharmaceutical captive labs. United States-based immuno-oncology startups adopt these tools at accelerating pace to compress target validation timelines.
- CRISPR:Gene-editing reagent supply chains and guide RNA design services feed directly into client discovery workflows. Specialized providers compete on turnaround time for knock-in cell line generation.
- Bioinformatics:Immunopeptidome analysis and T-cell receptor repertoire sequencing support biomarker development.
- Genomics:Single-cell RNA sequencing and spatial transcriptomics enable mechanism-of-action studies for combination therapy design.
Investment flows heaviest into Artificial Intelligence; capability gaps persist in CRISPR manufacturing scale-up.
End User:
Organizational scale and pipeline diversity determine whether buyers seek full-service partnerships or specialized niche providers.
- Biotech Firms:Lean internal teams in the United States drive outsourcing volume for CAR-T and bispecific antibody programs, packaging preclinical immunogenicity assessment with companion biomarker development under single master agreements. These sponsors unbundle after-sales technical support from core discovery contracts.
- Pharmaceutical Companies:Integrated toxicology and clinical pharmacology capabilities anchor bundled relationships for late-stage assets, though early discovery increasingly shifts to external partners.
- Research Institutions:Academic medical centers access GMP infrastructure through fee-for-service arrangements for investigator-initiated trials.
- Contract Research Organizations:Mid-tier CROs subcontract specialized functions such as vector manufacturing or AI-driven target identification to niche providers.
Transaction volume originates with Biotech Firms; contract value peaks with Pharmaceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of specialized immunotherapy services concentrates in established biotech clusters, while consumption spreads across emerging research hubs seeking outsourced discovery capabilities. The United States dominates both supply and demand, though European and Asian markets are deepening their service ecosystems.
United States
FDA Project Optimus mandates reshape dose-optimization protocols for oncology trials, driving demand for integrated pharmacology services. Boston and San Francisco biotech corridors generate sustained outsourcing volume for CAR-T and bispecific antibody programs. Academic medical centers in these clusters access GMP cleanroom infrastructure through fee-for-service arrangements with specialized providers.
Germany
EMA's ATMP classification framework tightens chemistry-manufacturing-controls documentation for cell and gene therapy sponsors. The country's national pharmaceutical regulator enforces modular trial submission standards that contract providers must navigate. Heidelberg and Munich biotech clusters host specialized vector manufacturing capabilities serving European oncology programs.
Switzerland
Swissmedic oversees advanced therapy medicinal product approvals with standards converging toward EMA frameworks. Basel's pharmaceutical ecosystem anchors demand for regulatory support and CMC documentation services. Local contract research organizations align quality systems with combined oncology and gene therapy guidelines.
China
NMPA guidelines on cell therapy development create compliance ramps for domestic biotech firms expanding discovery pipelines. Shanghai and Beijing biotech parks concentrate demand for CRISPR reagent supply chains and gene-editing workflows. Local providers compete on turnaround time for knock-in cell line generation serving immuno-oncology programs.
United Kingdom
MHRA post-Brexit regulatory pathways require contract providers to reconfigure submission strategies for advanced therapies. London and Cambridge biotech clusters drive outsourcing for biomarker development and companion diagnostic workflows. Academic medical centers access specialized immunogenicity assessment through modular service agreements.
Cancer Immunotherapy Drug Discovery Outsourcing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across service tiers, creating a bifurcated vendor base. Large integrated research organizations anchor bundled master agreements spanning toxicology through clinical pharmacology. Boutique cell therapy specialists capture margin pools through scarce GMP cleanroom infrastructure. Strategic moves concentrate on modular service expansion and AI-driven capability integration.
Within the integrated service tier, Covance, Inc. exemplifies the diversified archetype with footprint across preclinical and clinical execution. GenScript Biotech Corporation occupies a specialist position in gene-editing reagent supply chains feeding client CRISPR workflows. Crown Bioscience, Inc. represents the model-development specialist tier focused on humanized tumor platforms.
| Leading Market Players |
|---|
| Covance, Inc. |
| STC Biologics |
| Personalis, Inc. |
| ImmunXperts SA |
| Celentyx Ltd. |
| GenScript Biotech Corporation |
| BPS Bioscience, Inc. |
| Crown Bioscience, Inc. |
| Horizon Discovery Group plc |
| Others |
Cost & Logistics Intelligence
Lentiviral vector production cost indices cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margins for GMP cleanroom providers while concentrating bargaining power among Boston and San Francisco biotech clusters with bundled master agreements.
Pricing Analysis
Cost-down pressure on preclinical immunogenicity assessment accelerates because ISO 15189 compliance burdens disadvantage smaller contract research organizations. Project-based pricing dominates clinical trial management services, with FDA Project Optimus mandates driving premium-mid-economy pricing differentiation based on biomarker integration depth. Price differentiation hinges on GMP certification tier and vector manufacturing expertise scarcity. Mid-tier biotech firms exhibit highest price sensitivity, while pharmaceutical companies prioritize timeline compression over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for CRISPR reagent supply chains mandate multi-supplier qualification across United States, China, and Germany gene-editing workflow providers. Raw material dependencies center on synthetic guide RNA, lentiviral packaging plasmids, and humanized mouse breeding stock. Single-source vulnerability concentrates in qualified GMP cleanroom infrastructure for allogeneic cell products. Distribution runs through specialized logistics networks serving academic medical centers and venture-backed immuno-oncology startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated service bundling as ISO 15189 compliance costs force sub-scale contract research organizations toward acquisition or exit.
For Market Incumbents: Deploy automated cell culture platform investments to anchor bundled master agreements spanning toxicology through clinical pharmacology. Acquire boutique vector manufacturing specialists to capture margin pools from lentiviral production scarcity. Counter emerging AI-driven target identification entrants by integrating cloud-based immunoinformatics tools into existing preclinical workflows. For New Entrants and Emerging Players: Cloud-based regulatory strategy consulting offers the lowest barrier entry path for lean teams serving Boston-area immuno-oncology startups. Target biomarker development and companion diagnostic workflows as the most penetrable segment given unbundling trends from core discovery contracts. Pursue fee-for-service GMP infrastructure access models for academic medical centers as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier preclinical service providers with ISO 15189 accreditation gaps in the United States and United Kingdom. Five-to-ten year viability hinges on artificial intelligence integration depth and EMA ATMP framework alignment capabilities. Watch FDA Project Optimus enforcement intensity as the critical inflection signal for integrated pharmacology service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cell Culture Platform Investment | Covance anchors bundled relationships through integrated toxicology and clinical pharmacology footprint. |
| AI-Driven Target Identification Acquisition | Machine learning convergence with epitope prediction reshapes competitive positioning for mid-tier biotech sponsors. |
| GMP Cleanroom Infrastructure Expansion | Scarcity of qualified manufacturing space for viral vectors concentrates supply risk among specialized providers. |
| EMA ATMP Framework Alignment | Advanced therapy medicinal product classification standards enable cross-border trial design standardization. |
| CRISPR Reagent Supply Chain Integration | GenScript competes through specialized gene-editing workflows feeding directly into client discovery pipelines. |
Research Approach
Multi-period observation of CAR-T program outsourcing volumes and GMP cleanroom utilization rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, and formulary directors. Primary fieldwork combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and SEC 10-K disclosures. Bottom-up service provider revenue aggregation and top-down biotech R&D spend allocation enabled triangulation across the analysis window.
Input-output matrices modeled relationships between preclinical service demand, clinical trial management intensity, and artificial intelligence adoption velocity across the projection horizon. Segmentation dimensions included service type complexity, application modality maturity, technology adoption velocity, and end-user organizational scale. CAGRs derived from regression analysis of historical outsourcing penetration rates against pipeline stage advancement timelines, with vector manufacturing capacity constraints and ISO 15189 accreditation expansion serving as key forecast inputs.
The model holds under stable FDA Project Optimus enforcement and EMA ATMP framework continuity; deviation in gene therapy regulatory pathways or GMP cleanroom construction permitting would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Pregabalin Market