
 Chemotherapy Induced Anemia Market | 2026-2036
Chemotherapy Induced Anemia Market Size, Share, and Industry Trends Forecast 2026-2036
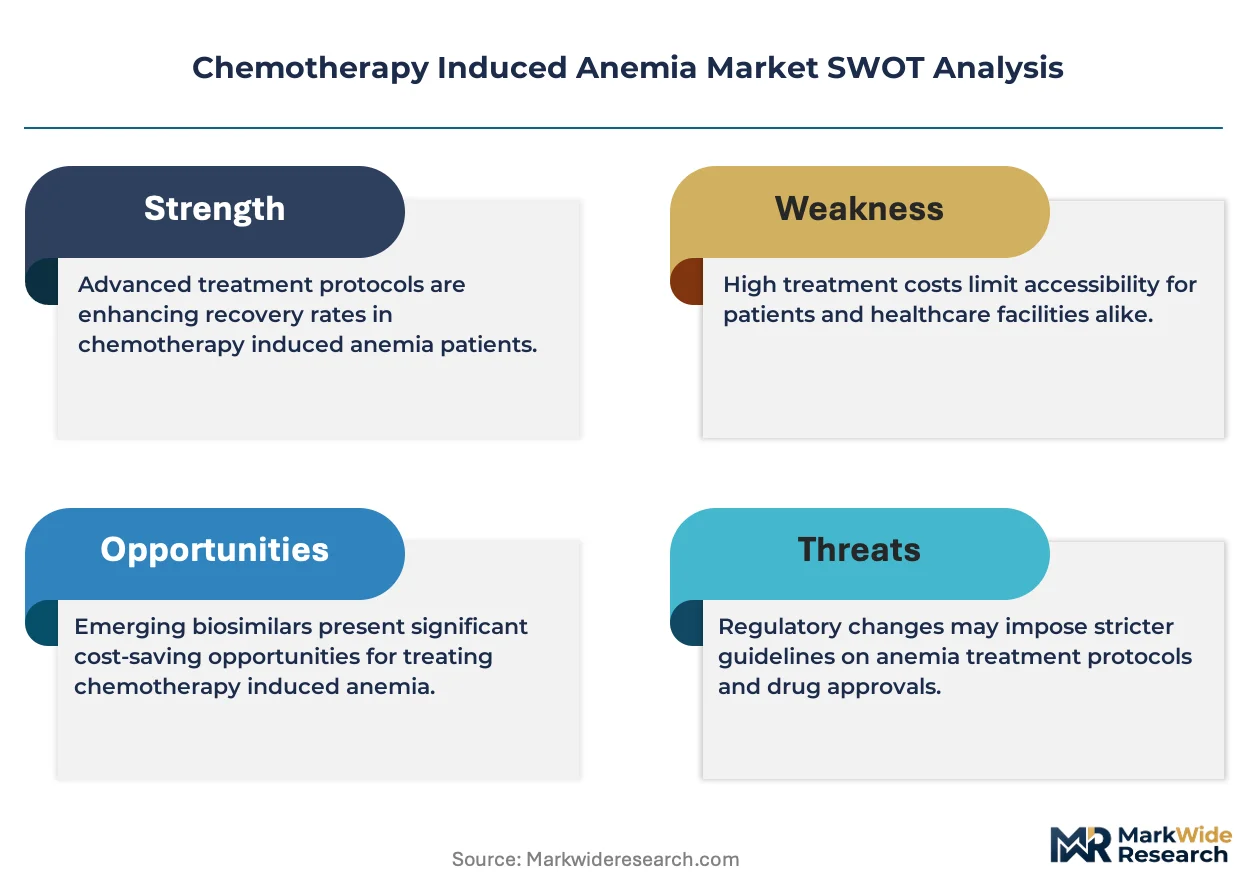
Chemotherapy Induced Anemia Market Analysis
Modular dosing regimens is shifting how physicians configure anemia management protocols around chemotherapy cycles. Amgen Inc. leverages its legacy ESA portfolio to sustain hospital formulary presence across major oncology centers. FibroGen, Inc. anchors its position through hypoxia-inducible factor prolyl hydroxylase inhibitor development, while Dr. Reddy's Laboratories Ltd. competes on biosimilar erythropoietin access in cost-sensitive markets.
Chemotherapy induced anemia describes a hemoglobin-depleting condition arising from myelosuppressive cytotoxic regimens, typically quantified by grade thresholds in Common Terminology Criteria for Adverse Events and managed through iron repletion, ESAs, or transfusion support. Erythropoiesis-Stimulating Agents retain the largest revenue share among product types but face margin compression from biosimilar entry, whereas Iron Supplements represent the fastest-expanding category as IV ferric carboxymaltose protocols displace oral ferrous salts in hospital infusion centers. Home Healthcare channels within the end-user dimension are capturing disproportionate growth as subcutaneous ESA administration and remote hemoglobin monitoring reduce inpatient dependency.
FDA REMS programs for ESAs, EMA oncology guideline updates on hemoglobin targets, and WHO transfusion safety standards collectively constrain product positioning while elevating evidence requirements for new entrants. These frameworks compel manufacturers to generate cardiovascular outcome data and differentiate on safety profiles rather than efficacy alone. Stakeholders must monitor evolving iron deficiency biomarker thresholds and biosimilar interchangeability rulings to anticipate reimbursement shifts and formulary tier changes.
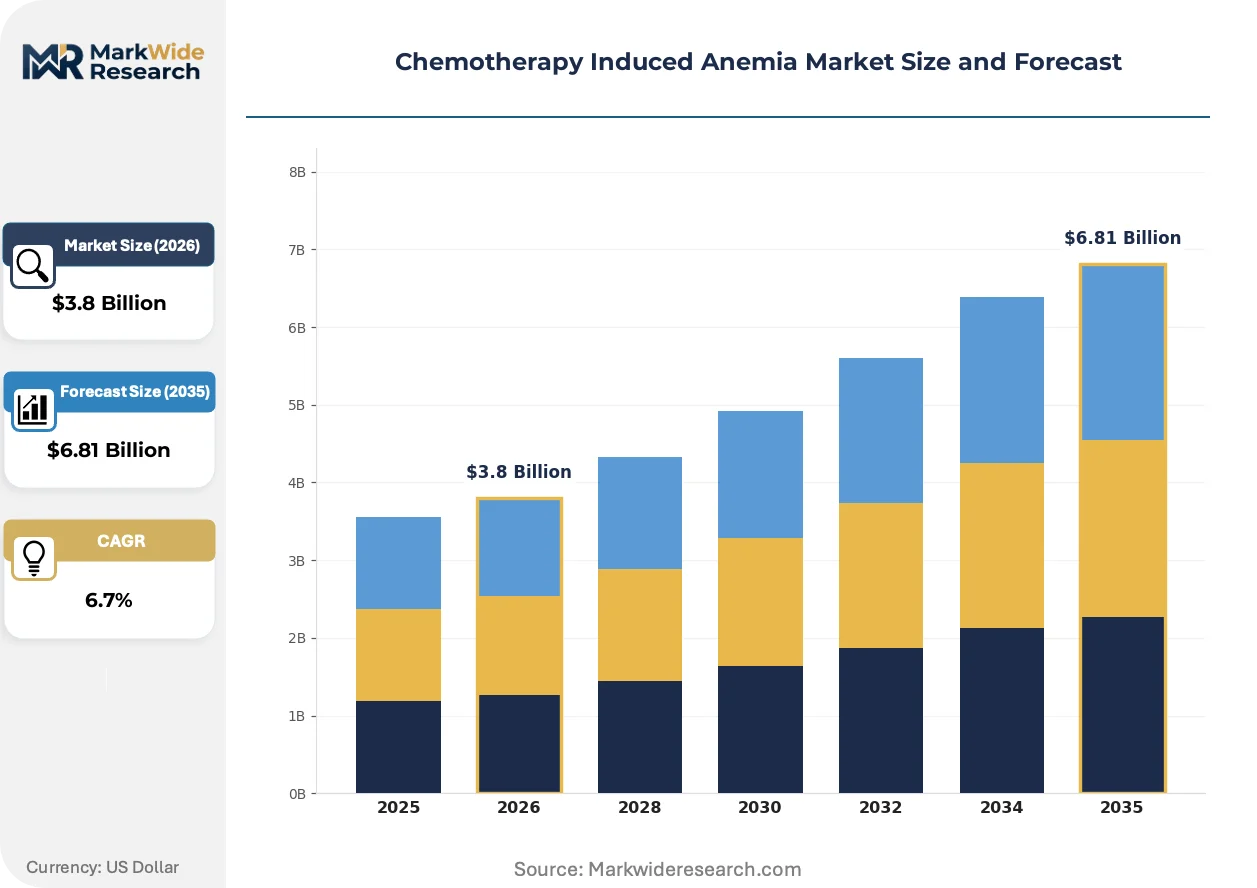
Market Dynamics
The FDA REMS tightening for erythropoiesis-stimulating agents has triggered a wholesale reconfiguration of anemia management protocols in oncology centers, forcing physicians to rebalance ESA dependence against iron repletion and transfusion alternatives.
Growth Catalysts
- EMA oncology guideline updates:The European Medicines Agency's hemoglobin target revisions in Germany are accelerating IV ferric carboxymaltose adoption in hospital infusion centers.
- Home Healthcare channel expansion:Subcutaneous ESA administration protocols are reducing inpatient dependency across United States oncology networks.
- Biosimilar ESA interchangeability:FDA rulings on erythropoietin biosimilars are expanding formulary access in cost-sensitive United States markets.
Market Restraints
- Cardiovascular outcome data requirements:FDA REMS mandates for ESAs compel manufacturers to generate expensive safety evidence beyond efficacy endpoints.
- Iron deficiency biomarker threshold uncertainty:Evolving ferritin and transferrin saturation cutoffs create reimbursement friction for IV iron protocols.
- Transfusion safety standard compliance:WHO guidelines elevate blood banking infrastructure costs in emerging market treatment centers.
Strategic Opportunities
- Remote hemoglobin monitoring integration:Wearable biosensor convergence with telehealth platforms opens ambulatory care capture in United States home settings.
- Modular dosing regimen software:Algorithm-driven anemia management tools align iron and ESA timing with chemotherapy cycles in German hospital systems.
- IV iron protocol standardization:EMA formulary controls in European oncology centers create demand for single-infusion ferric carboxymaltose formulations.
Industry Challenges
- Legacy ESA inventory transition:Hospital pharmacies face complex formulary tier reconfiguration as biosimilars displace originator products.
- Multidisciplinary care coordination:Medical oncologists, hematologists, and infusion nurses require aligned training on hypoxia-inducible factor prolyl hydroxylase inhibitor protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy Induced Anemia Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythropoiesis-Stimulating Agents, Iron Supplements, Blood Transfusion, Antibiotics Application: Oncology, Hematology, Clinical Trials, Symptom Management End User: Hospitals, Outpatient Clinics, Home Healthcare, Research Institutions Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Novartis AG, Astellas Pharma Inc., Amgen Inc., Dr. Reddy’s Laboratories Ltd., FibroGen, Inc., F. Hoffmann-La Roche Ltd., Johnson & Johnson, Bristol-Myers Squibb Company, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy Induced Anemia Market Emerging Trajectories
Hypoxia-inducible factor prolyl hydroxylase inhibitor mechanisms are overtaking erythropoiesis-stimulating agents as the dominant innovation vector in anemia management, reshaping clinical trial priorities and manufacturing investment patterns across oncology therapeutics.
IV ferric carboxymaltose protocols are overtaking oral ferrous sulfate in United States hospital infusion centers as physicians prioritize rapid hemoglobin recovery and reduced gastrointestinal toxicity. Oncology clinics in major metropolitan health systems have compressed oral iron trial periods from twelve weeks to four-week IV completion windows. This shift is enabling same-cycle anemia correction that aligns with myelosuppressive chemotherapy scheduling.
REACH compliance frameworks in European Union member states are tightening traceability requirements for iron-containing pharmaceuticals, compelling manufacturers to implement batch-level serialization across supply chains. German hospital formulary committees now mandate cobalt and nickel impurity documentation for all IV iron products. EMA-certified manufacturers are responding by retrofitting production lines with inductively coupled plasma mass spectrometry quality control stations.
Subscription-based anemia management platforms are consolidating previously fragmented ESA procurement, remote monitoring, and nursing support into bundled per-patient contracts. United States oncology practice networks are displacing fee-for-service transfusion and infusion billing with capitated anemia care agreements. This restructuring is most visible in Medicare Advantage-covered populations where risk-adjusted reimbursement rewards hemoglobin stability metrics.
Chemotherapy Induced Anemia Market Segmentation
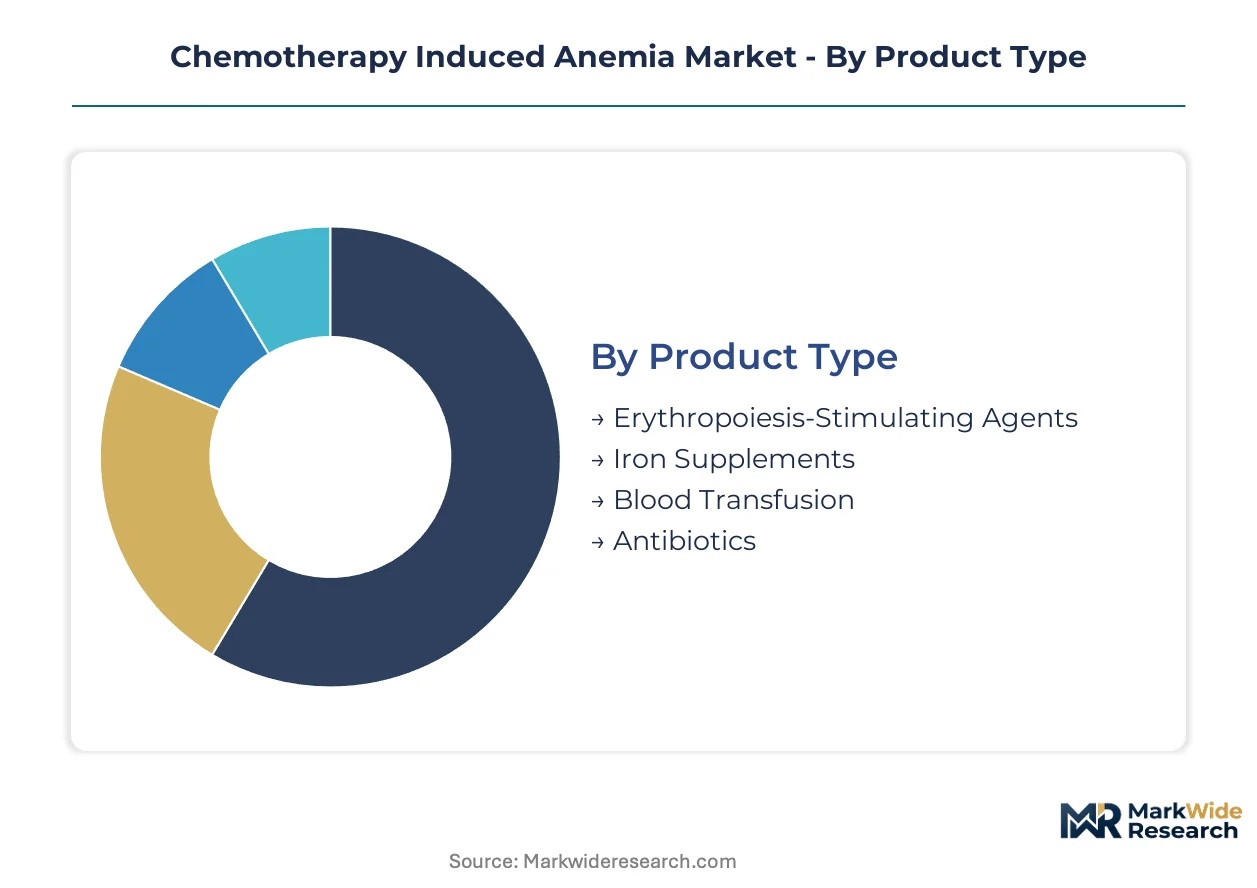
Anemia management protocols fragment across product mechanisms, care settings, and procurement channels. Each segmentation dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning.
Product Type:
Supply concentration in parenteral formulations is reshaping manufacturing investment and hospital formulary tier placement.
- Erythropoiesis-Stimulating Agents:Recombinant erythropoietin and darbepoetin alfa formulations dominate revenue concentration despite biosimilar margin compression. United States oncology clinics are rebalancing ESA dependence against transfusion alternatives under FDA REMS tightening.
- Iron Supplements:IV ferric carboxymaltose displaces oral ferrous salts through rapid hemoglobin recovery aligned with chemotherapy cycles. German hospital infusion centers prioritize single-infusion protocols to compress treatment windows from twelve weeks to four.
- Blood Transfusion:Leukocyte-reduced and irradiated blood components serve refractory anemia cases with hemoglobin thresholds below transfusion triggers.
- Antibiotics:Prophylactic and therapeutic agents address infection risks in neutropenic patients with concurrent anemia.
Erythropoiesis-Stimulating Agents absorb the bulk of installed capacity; Iron Supplements are expanding most quickly.
Application:
Clinical workflow integration determines reimbursement coding and procurement contract structure across therapeutic areas.
- Oncology:Myelosuppressive chemotherapy regimens drive protocol standardization around hemoglobin monitoring and intervention timing. United States practice networks bundle anemia management into episode-based oncology payments.
- Hematology:Specialized units manage complex anemia cases with underlying marrow dysfunction requiring coordinated transfusion and pharmacologic support.
- Clinical Trials:Investigational sites require calibrated hemoglobin endpoints and standardized adverse event grading per Common Terminology Criteria protocols.
- Symptom Management:Palliative care settings prioritize fatigue reduction and quality-of-life metrics over hemoglobin normalization targets.
Oncology commands the deepest formulary integration; Clinical Trials are climbing the fastest on protocol complexity.
End User:
Site-of-care migration is redistributing revenue between inpatient infusion centers and ambulatory channels.
- Hospitals:Inpatient hematology-oncology units manage acute anemia with transfusion capabilities and intensive monitoring infrastructure.
- Outpatient Clinics:Community oncology practices in United States metropolitan markets perform IV iron and subcutaneous ESA administration without admission.
- Home Healthcare:Subcutaneous ESA self-administration and remote hemoglobin monitoring are reducing inpatient dependency across Medicare Advantage populations.
- Research Institutions:Academic medical centers conduct hypoxia-inducible factor prolyl hydroxylase inhibitor trials with specialized biomarker laboratories.
Hospitals retain the largest procedure volume; Home Healthcare is gaining share fastest on risk-adjusted reimbursement incentives.
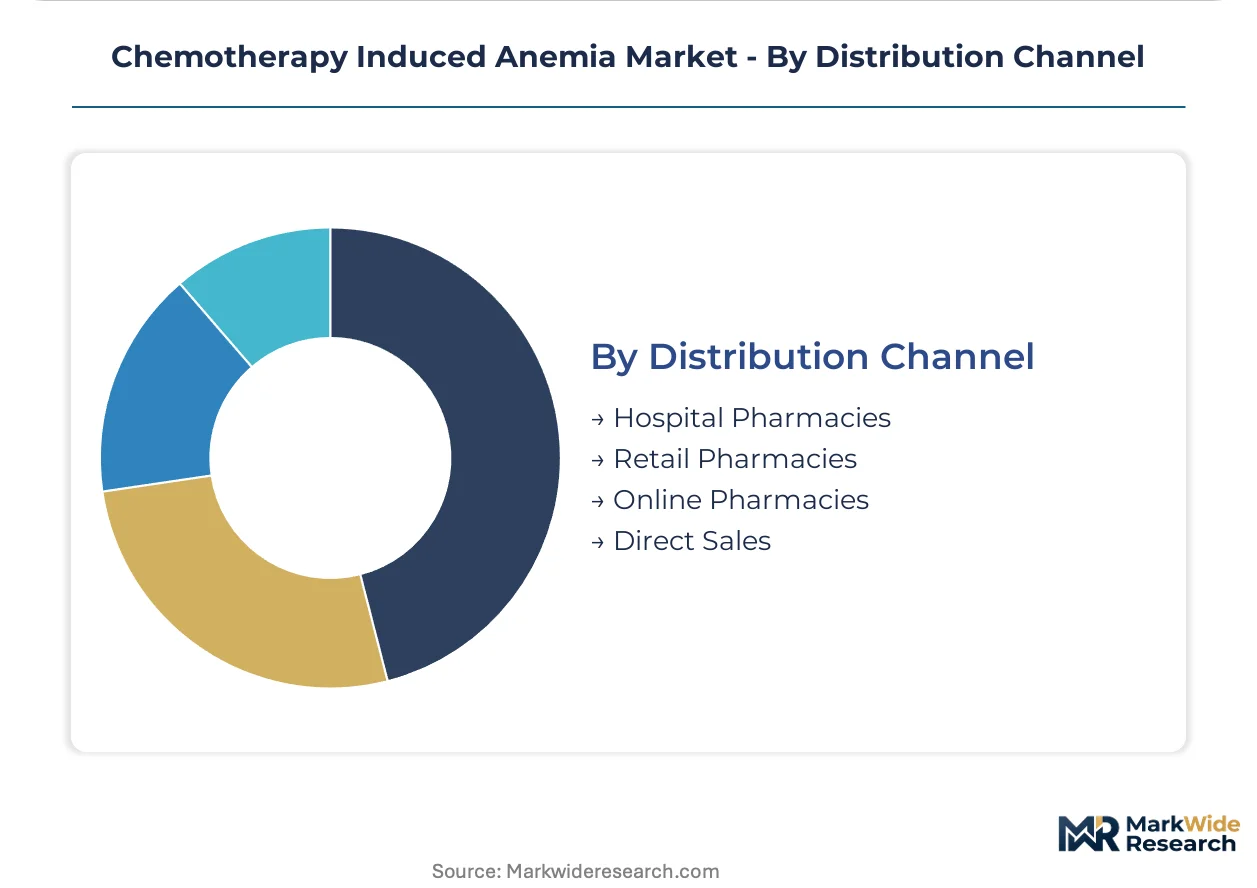
Distribution Channel:
Procurement centralization through group purchasing organizations is compressing margin structures for non-specialized products.
- Hospital Pharmacies:Formulary committees in German and United States health systems control ESA and IV iron access through tiered authorization protocols.
- Retail Pharmacies:Oral iron supplements and supportive care medications flow through community pharmacy networks with prescription benefit management constraints.
- Online Pharmacies:Direct-to-patient delivery platforms are capturing oral iron and medical supply volume in United States home healthcare segments.
- Direct Sales:Specialty distributors handle cold-chain biologics and clinical trial materials with batch-level traceability documentation.
Hospital Pharmacies anchor procurement volume; Online Pharmacies show steepest expansion trajectory on patient convenience preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of erythropoiesis-stimulating agents concentrates in Swiss and German biologics clusters, while consumption tilts toward United States oncology networks and German hospital systems where reimbursement density supports premium pricing.
United States
Oncology clinics in metropolitan health systems are expanding subcutaneous ESA administration and remote hemoglobin monitoring to reduce inpatient dependency. FDA REMS tightening for erythropoiesis-stimulating agents is forcing physicians to rebalance ESA dependence against iron repletion alternatives. Major practice networks in California and Texas are piloting subscription-based anemia management platforms that bundle procurement, monitoring, and nursing support.
Germany
Hospital formulary committees in Bavaria and North Rhine-Westphalia are mandating single-infusion ferric carboxymaltose protocols to compress treatment windows from twelve weeks to four. EMA oncology guideline updates on hemoglobin targets are accelerating IV iron adoption in hospital infusion centers. REACH compliance frameworks are compelling manufacturers to implement batch-level serialization with cobalt and nickel impurity documentation.
Japan
PMDA review pathways for hypoxia-inducible factor prolyl hydroxylase inhibitors are shaping clinical trial priorities among domestic and multinational sponsors. The Kanto region around Tokyo anchors specialized biomarker laboratories conducting HIF-PHI development programs. METI industrial policy is incentivizing domestic manufacturing capacity for parenteral iron formulations to reduce import dependency.
India
CDSCO regulatory pathways for biosimilar erythropoietin are expanding access in cost-sensitive markets as domestic manufacturers scale production. Maharashtra and Telangana host contract manufacturing organizations supplying IV iron formulations to Middle East and African markets. Government procurement programs for oncology supportive care are consolidating demand through centralized hospital purchasing.
United Kingdom
NICE technology appraisals are conditioning reimbursement for novel anemia agents on cardiovascular outcome data beyond efficacy endpoints. The Greater London and Southeast cluster concentrates specialized hematology-oncology units managing complex anemia cases. NHS England is piloting capitated anemia care agreements within oncology pathways to align provider incentives with hemoglobin stability metrics.
Chemotherapy Induced Anemia Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the anemia management landscape, producing a tiered structure where scale-driven pharmaceutical incumbents anchor hospital formulary presence while biotechnology innovators pursue mechanism-based differentiation. The vendor base separates into three archetypes: legacy ESA portfolio holders defending institutional relationships, HIF-PHI developers capturing clinical trial investment, and biosimilar manufacturers competing on procurement cost. Consolidation pressure is intensifying through strategic partnerships for combination therapy development and capacity expansion for parenteral iron manufacturing.
Within the innovation-focused tier, FibroGen, Inc. and Amgen Inc. occupy positions representing divergent strategic bets on anemia mechanism—oral HIF-PHI inhibition versus established injectable erythropoiesis stimulation. Among diversified pharmaceutical conglomerates, Novartis AG and F. Hoffmann-La Roche Ltd. exemplify scale-driven players with institutional presence across multiple oncology supportive care categories. Dr. Reddy's Laboratories Ltd. represents the biosimilar-focused archetype competing on cost-access in emerging markets.
| Leading Market Players |
|---|
| Novartis AG |
| Astellas Pharma Inc. |
| Amgen Inc. |
| Dr. Reddy's Laboratories Ltd. |
| FibroGen, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into parenteral iron manufacturing anchors both supply security and pricing power for manufacturers competing on EMA-certified IV ferric carboxymaltose protocols. Captive production of high-purity iron carbohydrate complexes insulates German and United States suppliers from raw material volatility while supporting premium positioning against oral ferrous salt alternatives.
Pricing Analysis
Margin tightening in erythropoiesis-stimulating agents reflects biosimilar entry compressing originator pricing across United States hospital formularies. Three-tier pricing structure across originator biologics, interchangeable biosimilars, and non-interchangeable alternatives segments buyer archetypes by formulary tier access and cardiovascular outcome data requirements. Cost-down pressure on oral iron accelerates as IV single-infusion protocols displace twelve-week oral courses in Medicare Advantage networks. Community oncology practices exhibit highest price sensitivity; academic medical centers with risk-adjusted contracts prioritize hemoglobin stability metrics over per-unit cost.
Supply Chain Analysis
Returns and expiry management of cold-chain erythropoiesis-stimulating agents drive reverse-logistics infrastructure investment across specialty distributor networks. Manufacturing concentrates in Switzerland, Germany, and India for parenteral iron and biosimilar erythropoietin production. Active pharmaceutical ingredient supply rests on Chinese and Indian fermentation capacity for recombinant protein production. Single-source vulnerability in high-purity iron ore processing for pharmaceutical-grade carbohydrates elevates supply risk. Distribution runs through hospital pharmacy procurement committees and group purchasing organizations with formulary tier controls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into parenteral iron API manufacturing represents the decisive upstream lever as EMA REACH compliance and cobalt impurity documentation requirements harden. Manufacturers securing captive carbohydrate complex production gain both cost control and formulary tier advancement.
For Market Incumbents: Lock in hospital formulary presence through cardiovascular outcome data generation that satisfies FDA REMS tightening and differentiates against interchangeable biosimilars. Expand backward integration into high-purity iron carbohydrate manufacturing to secure EMA-certified supply for German hospital procurement. Prioritize subscription-based anemia management platform deployment across Medicare Advantage networks to displace fee-for-service transfusion billing. For New Entrants and Emerging Players: Launch via direct-to-patient home healthcare channels with remote hemoglobin monitoring and subcutaneous ESA self-administration support. Target underpenetrated community oncology practices in United States metropolitan markets lacking integrated anemia management protocols. Pursue white-space positioning in IV iron protocol software that aligns dosing with chemotherapy cycle timing. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmaceutical acquisitions of HIF-PHI developers with phase III cardiovascular safety datasets. Long-term viability hinges on mechanism differentiation beyond erythropoiesis-stimulating agents as hypoxia-inducible factor inhibition displaces injectable biologics. Watch FDA biosimilar interchangeability rulings as inflection signal for formulary tier reconfiguration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | HIF-PHI cardiovascular outcome studies satisfy FDA REMS requirements beyond efficacy endpoints. |
| Manufacturing Scale-Up | Parenteral iron capacity expansion meets German hospital single-infusion protocol demand. |
| Regulatory Approval Pathway | EMA-certified cobalt impurity documentation enables REACH-compliant European formulary access. |
| Strategic Partnership | Remote hemoglobin monitoring alliances with telehealth platforms capture Medicare Advantage risk contracts. |
| Reimbursement Strategy | Capitated anemia care agreements align provider incentives with hemoglobin stability metrics. |
Methodological Framework
FDA REMS documentation, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone for regulatory pathway and safety evidence mapping. Primary interviews with drug development executives, formulary directors at German hospital systems, hospital procurement managers in United States oncology networks, and payer access specialists validated commercial assumptions. Bottom-up and top-down triangulation cross-referenced patient volume estimates with manufacturer capacity disclosures and reimbursement coding analysis.
Bottom-up modeling anchored patient population projections by chemotherapy regimen and myelosuppressive risk stratification across the projection horizon. Segmentation dimensions included product mechanism, administration route, care setting, and regional regulatory cluster. CAGRs derived from elasticity-adjusted pricing trajectories and volume penetration curves. Forecast inputs incorporated EMA guideline revision timing and FDA biosimilar interchangeability ruling schedules.
The model assumes a particular technology adoption path; alternative pathways for hypoxia-inducible factor prolyl hydroxylase inhibitor dominance would alter the outlook. Forecasts reflect assumptions on hemoglobin target threshold stability and IV iron reimbursement parity. Material deviation in FDA REMS enforcement intensity or EMA formulary control expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Antiepileptic Drugs (AED) Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
HIV Antivirals Market