
 US Generic Injectables Pharmaceutical Contract Manufacturing Market | 2026-2036
US Generic Injectables Pharmaceutical Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
US Generic Injectables Pharmaceutical Contract Manufacturing Market Insights
The US generic injectables contract manufacturing base is pivoting along a sharp split between high-complexity sterile formulations and commoditized volume generics. Fresenius Kabi leverages its European parent company's aseptic technology portfolio to dominate complex oncology injectables. Hikma Pharmaceuticals plc anchors its position through backward integration into active pharmaceutical ingredients. Pfizer Inc. sustains scale advantages across ready-to-use formats with dedicated capacity for hospital-system contracts.
Generic injectables pharmaceutical contract manufacturing encompasses the outsourced production of bioequivalent sterile drug products, including parenteral solutions, suspensions, and lyophilized powders requiring ISO 5 cleanroom environments and terminal sterilization or aseptic processing. Its primary purpose is to supply healthcare institutions with affordable alternatives to branded injectables while mitigating drug shortage risks through redundant manufacturing networks. Ready-to-use and pre-filled syringe formats command expanding share as hospitals prioritize medication safety and reduced compounding burden. Oncology and infectious disease therapy areas represent the deepest margin pools, driven by chronic shortages in chemotherapy agents and anti-infective cocktails.
FDA current Good Manufacturing Practice enforcement, USP Chapter 797 sterile compounding standards, and the Drug Supply Chain Security Act collectively elevate barriers to market entry while channeling demand toward validated contract partners. The country's national pharmaceutical regulator inspects foreign and domestic facilities with intensifying frequency, compressing capacity at marginal operators. Stakeholders must monitor how FDA quality metrics and shortage notification requirements reshape supplier qualification timelines and contract renewal premiums.
Market Dynamics
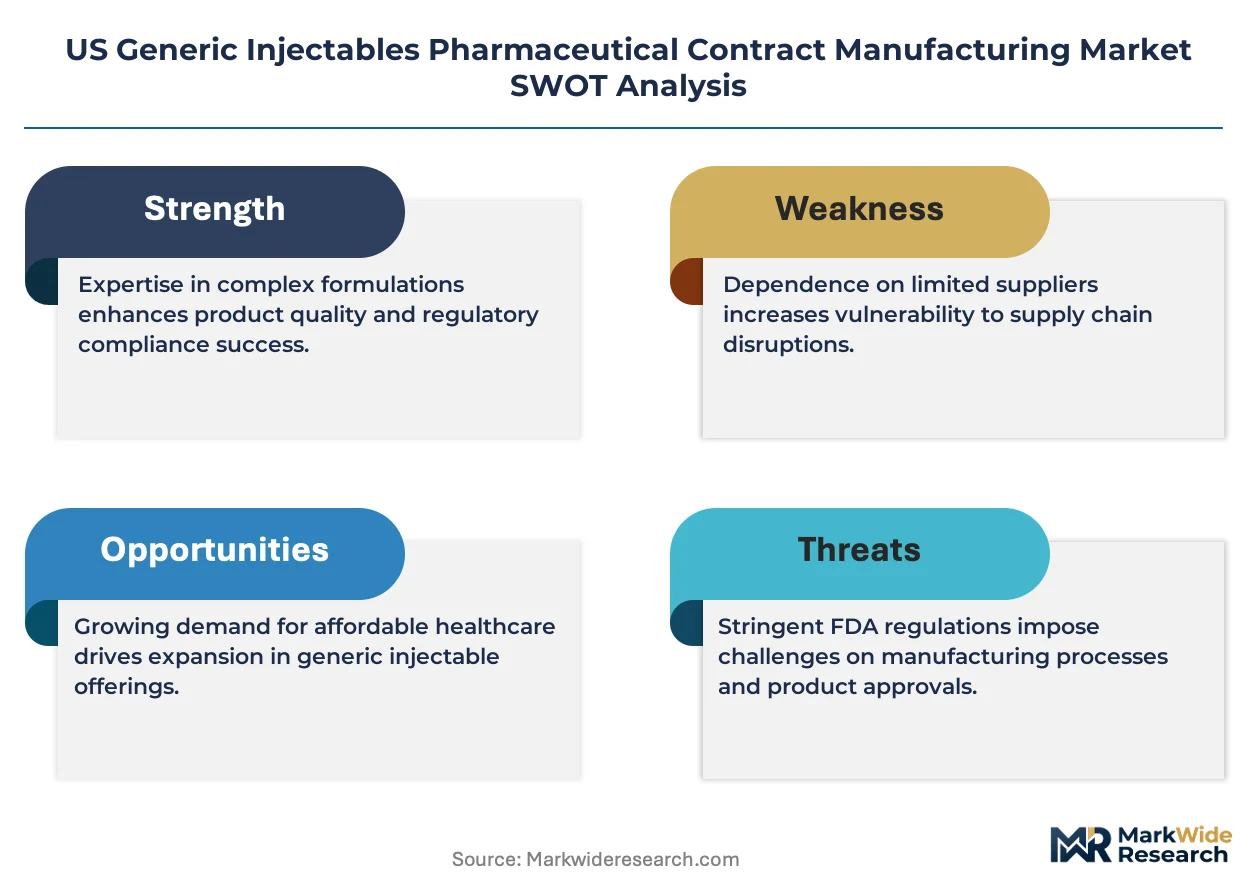
FDA intensification of aseptic facility inspections and USP Chapter 797 sterility standard revisions are compressing capacity at marginal operators while channeling hospital procurement toward validated contract partners with redundant sterile networks.
Growth Catalysts
- Drug Shortage Mitigation Mandates:Hospital systems facing chronic chemotherapy and anti-infective shortages are expanding sole-source contracts with multi-site sterile injectable manufacturers to secure supply continuity.
- Ready-to-Use Formats:Pre-filled syringes and premixed infusion bags are displacing traditional vial-and-ampoule compounding in acute care settings, reducing medication errors and pharmacy labor burden.
- Northeast Procurement Clustering:Integrated delivery networks in Massachusetts, New York, and Pennsylvania are consolidating purchasing power through group purchasing organizations, anchoring regional contract manufacturing demand.
Market Restraints
- API Supply Concentration:Backward integration into active pharmaceutical ingredients remains limited among US-based contract manufacturers, creating dependency on Indian and Chinese API suppliers subject to FDA import alerts.
- Cleanroom Construction Costs:ISO 5 classified aseptic suites require capital expenditure intensity exceeding standard pharmaceutical manufacturing by factors of three to four, constraining capacity expansion at mid-scale operators.
- Terminal Sterilization Limitations:Heat-sensitive biologics and complex oncology formulations cannot tolerate standard steam sterilization, restricting batch throughput and elevating contamination risk profiles.
Strategic Opportunities
- Specialty Pharmacy Networks:Home infusion and ambulatory oncology clinics in Florida and Texas represent underpenetrated channels demanding patient-ready injectable formats with extended stability profiles.
- 503B Compounding Outsourcing:FDA enforcement against non-compliant hospital compounding facilities is redirecting sterile preparation volume toward registered 503B outsourcing facilities and their contract manufacturing partners.
- Lyophilization Capacity Expansion:Freeze-dried powder formulations for unstable oncology APIs offer margin premiums over liquid presentations, with demand outpacing domestic lyophilization suite availability.
Industry Challenges
- Aseptic Processing Technician Scarcity:ISO 5 cleanroom operators require specialized training in gowning, environmental monitoring, and contamination control, with certification timelines extending six to nine months and turnover rates elevated versus standard pharmaceutical manufacturing.
- Legacy System Integration:Electronic batch record systems and environmental monitoring platforms at established sterile facilities require costly validation protocols when interfacing with modern manufacturing execution systems demanded by hospital-system customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Generic Injectables Pharmaceutical Contract Manufacturing Market |
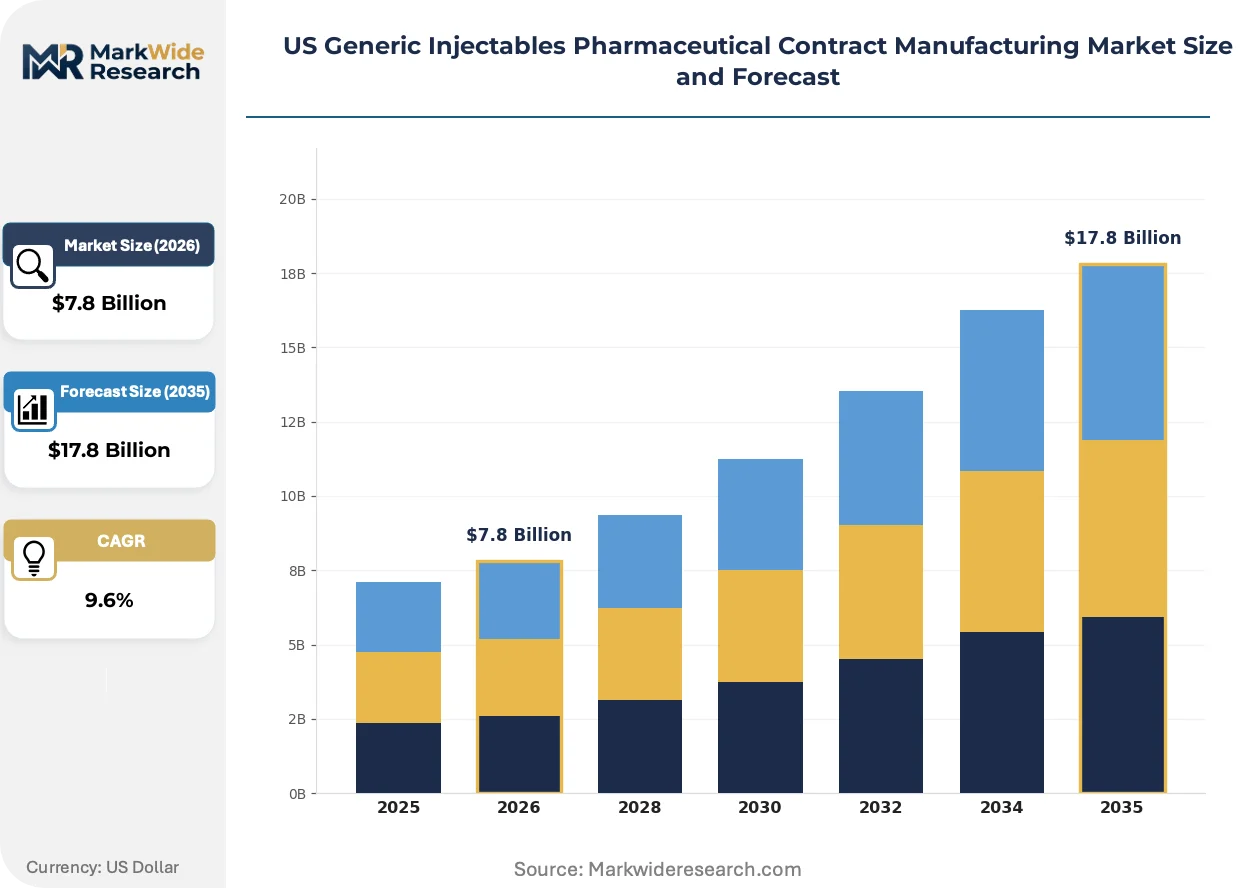
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Use, Pre-filled Syringes, Vials, Ampoules Therapy Area: Oncology, Infectious Diseases, Cardiovascular, Pain Management End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Distribution Channel: Direct Sales, Wholesalers, Online, Retail Pharmacies |
| Companies Covered | Hikma Pharmaceuticals plc, Fresenius Kabi, Pfizer Inc., Sandoz AG, Jubilant Pharma Limited, Baxter, PCI Pharma Services, Gland Pharma Limited (USA), Grand River Aseptic Manufacturing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Generic Injectables Pharmaceutical Contract Manufacturing Market Trends and Innovations
Continuous manufacturing technologies and single-use aseptic systems are displacing traditional batch processing in sterile injectable production, compressing changeover times and reducing cross-contamination risk profiles across the contract manufacturing base.
Isolator-based filling lines are converging with restricted access barrier systems to create hybrid aseptic environments that reduce human intervention during critical filling operations. Large hospital systems and specialty pharmacy chains are specifying isolator technology in contract qualification requirements. This convergence is compressing competitive differentiation between mid-tier and top-tier sterile manufacturers, forcing capital reinvestment across the supplier base.
FDA quality metrics guidance and intensified pre-approval inspection protocols are extending supplier qualification timelines for new contract manufacturing relationships. The agency's foreign facility inspection program has compressed capacity at offshore sterile injectable sites, redirecting procurement toward domestic validated partners. Oncology and anti-infective therapy categories face the most severe qualification bottlenecks, with hospital-system customers accepting contract renewal premiums to secure redundant supply.
Hospital pharmacy directors are consolidating supplier relationships from fragmented multi-vendor portfolios toward single-source or dual-source sterile injectable contracts with integrated service components. Group purchasing organizations in the Midwest and Northeast are facilitating this consolidation through pre-negotiated master service agreements. Texas and California health systems exhibit the most advanced procurement centralization, with integrated delivery networks managing formulary decisions across fifty-plus affiliated facilities.
US Generic Injectables Pharmaceutical Contract Manufacturing Market Segmentation
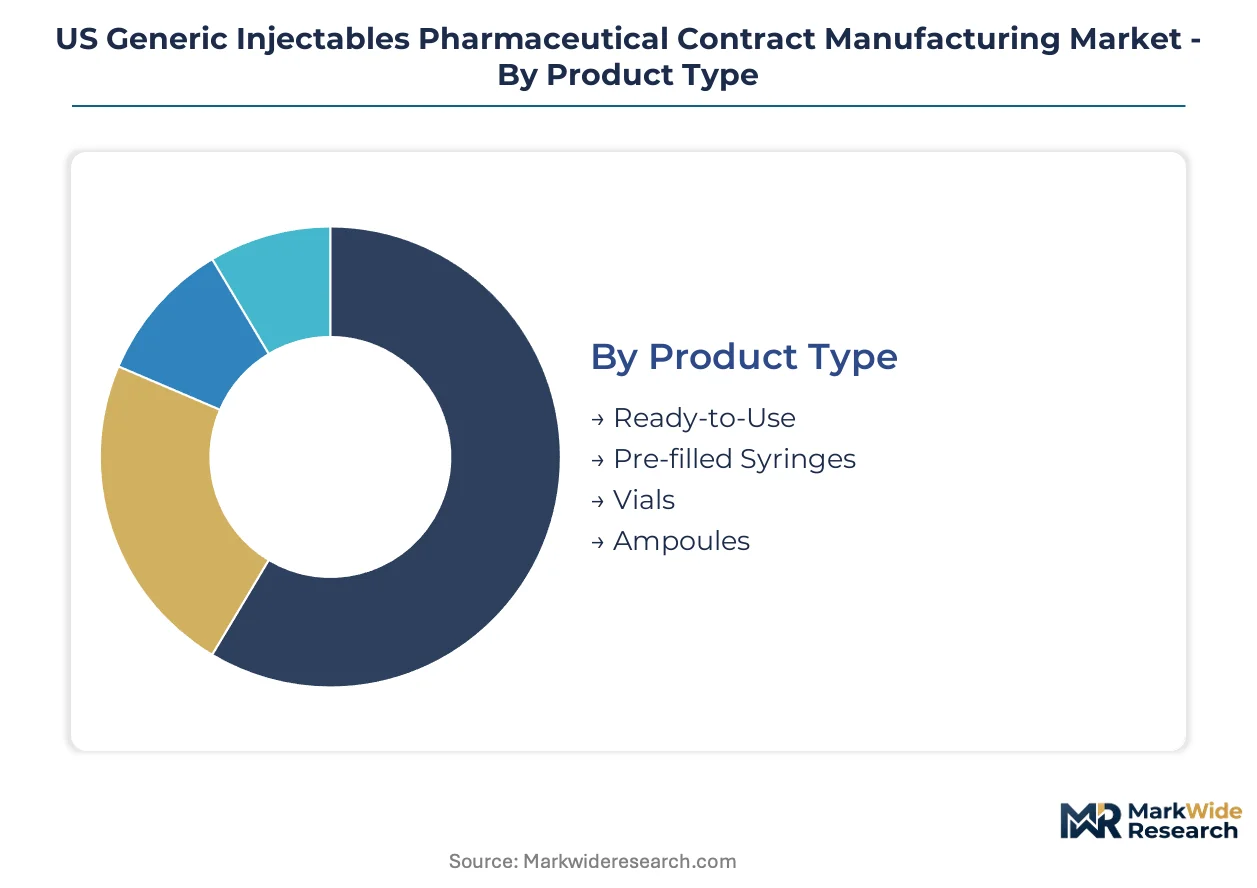
Segmentation in US generic injectables contract manufacturing reveals how formulation complexity, clinical setting requirements, and procurement channel structures shape supplier selection criteria and contract value pools. Hospital-system customers segment their sourcing strategies across technology readiness, therapeutic criticality, and care setting logistics.
Product Type:
Ready-to-use formats command specification premiums based on sterility assurance levels and compounding burden reduction.
- Ready-to-Use:Premixed infusion bags and preconstituted solutions eliminate hospital pharmacy compounding steps. Northeast integrated delivery networks specify these formats for high-risk chemotherapy protocols to reduce medication errors and USP Chapter 797 compliance exposure.
- Pre-filled Syringes:Unit-dose sterile presentations with integrated needle safety systems. Ambulatory oncology clinics in Texas and Florida are expanding procurement of these formats for same-day infusion protocols requiring minimal preparation time.
- Vials:Multi-dose glass or polymer containers requiring reconstitution or dilution prior to administration.
- Ampoules:Single-dose glass containers requiring breaking and transfer for compounding.
Mature deployment sits with Vials. Newer deployment is concentrated in Ready-to-Use.
Therapy Area:
Margin concentration follows therapeutic criticality and shortage vulnerability rather than prescription volume alone.
- Oncology:Cytotoxic and biologic sterile injectables with complex stability profiles and narrow therapeutic indices. FDA shortage notifications concentrate in platinum-based chemotherapies and supportive care agents, driving hospital-systems toward multi-source contracting with validated sterile manufacturers.
- Infectious Diseases:Anti-infective cocktails and antimicrobial combinations facing chronic supply interruptions. The country's national pharmaceutical regulator has intensified inspection frequency at offshore API suppliers for these categories, compressing domestic manufacturing capacity.
- Cardiovascular:Emergency injectables including anticoagulants and antiarrhythmics for acute care protocols.
- Pain Management:Opioid and non-opioid parenteral analgesics with controlled substance scheduling requirements.
Contracting sophistication clusters in Oncology. Volume scale concentrates in Infectious Diseases.
End User:
Care setting migration is reshaping format specifications and stability requirements across the customer base.
- Hospitals:Acute care institutions with 24-hour pharmacy operations and compounding infrastructure. Massachusetts and New York health systems anchor procurement volumes through group purchasing organization consolidation, prioritizing redundant supply networks for critical care injectables.
- Home Care:Infusion nursing services and patient self-administration settings requiring extended stability at ambient conditions. Florida's specialty pharmacy networks are expanding home-based oncology and anti-infective protocols, demanding patient-ready formats with simplified storage requirements.
- Clinics:Ambulatory settings with limited compounding capabilities and same-day turnaround requirements.
- Specialty Pharmacies:Focused distribution channels for complex sterile products with cold chain or hazardous handling protocols.
Regulatory qualification investment is deepest with Hospitals. Channel expansion is climbing the fastest with Home Care.
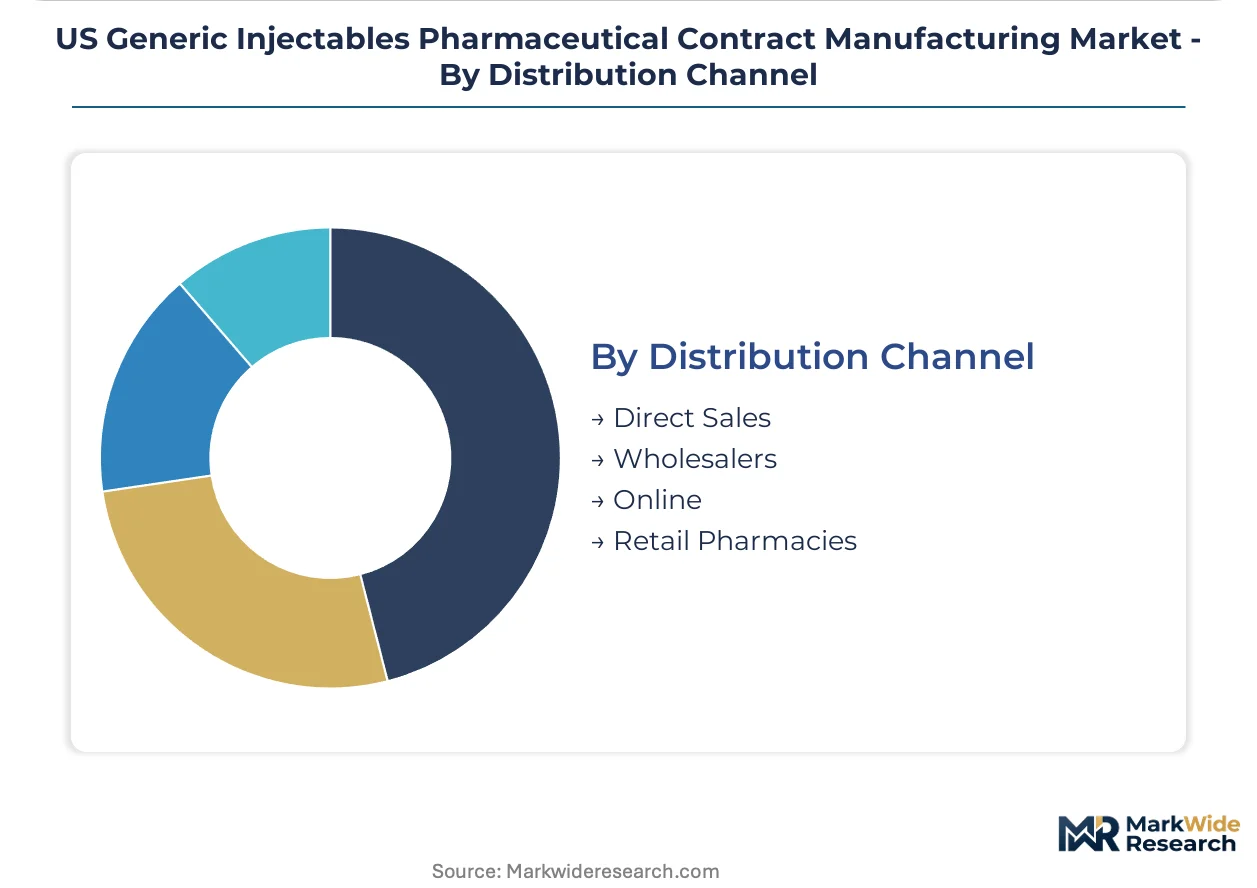
Distribution Channel:
Channel structure determines traceability requirements and shortage response velocity for contract manufacturers.
- Direct Sales:Manufacturer-to-institution contracts with integrated service components including inventory management and shortage notification protocols. Large Midwest health systems favor direct relationships for oncology injectables, accepting price premiums for supply continuity guarantees.
- Wholesalers:Three primary distributors handling logistics, credit, and shortage allocation for standard volume generics. FDA Drug Supply Chain Security Act serialization requirements flow through these channels, elevating systems integration costs for contract manufacturers.
- Online:Emerging procurement platforms for non-acute injectables with standardized handling requirements.
- Retail Pharmacies:Limited role in sterile injectables due to compounding license and storage infrastructure constraints.
Contract value concentration remains with Direct Sales. Systems investment is expanding most quickly in Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast Corridor from Boston through New York City anchors procurement concentration for sterile injectable contract manufacturing, with integrated delivery networks driving multi-site contracting strategies.
Northeast
Massachusetts and New York hospital systems cluster procurement through group purchasing organizations, prioritizing redundant supply networks for oncology and anti-infective injectables. FDA intensification of aseptic facility inspections compresses capacity at marginal operators while channeling demand toward validated contract partners. Greater Boston's specialty pharmacy networks expand home infusion protocols, demanding patient-ready formats with extended stability profiles.
Midwest
Illinois and Ohio health systems anchor volume demand through consolidated formulary management across fifty-plus affiliated facilities. USP Chapter 797 sterility standard revisions accelerate compliance investments among regional contract manufacturers. The Chicago metropolitan area concentrates lyophilization capacity expansion for unstable oncology APIs, with freeze-dried powder formulations commanding margin premiums over liquid presentations.
Southeast
Florida's specialty pharmacy networks drive underpenetrated channel expansion for home-based oncology and anti-infective protocols. FDA enforcement against non-compliant hospital compounding facilities redirects sterile preparation volume toward registered 503B outsourcing facilities. Miami and Tampa ambulatory oncology clinics expand procurement of pre-filled syringe formats for same-day infusion protocols.
Southwest
Texas health systems exhibit the most advanced procurement centralization among integrated delivery networks managing formulary decisions across expansive facility footprints. The state's national pharmaceutical regulator maintains intensified inspection frequency at sterile injectable sites, compressing capacity at marginal operators. Houston and Dallas medical centers prioritize ready-to-use premixed infusion bags for high-risk chemotherapy protocols.
West Coast
California health systems face chronic chemotherapy and anti-infective shortages, expanding sole-source contracts with multi-site sterile injectable manufacturers. The state's environmental monitoring requirements for ISO 5 cleanroom operations exceed federal baselines, elevating operational costs for contract manufacturers. San Francisco and Los Angeles specialty pharmacies drive demand for patient-ready formats with simplified storage requirements.
US Generic Injectables Pharmaceutical Contract Manufacturing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sterile injectable contract manufacturing base. The market structure consolidates around three tiers: global pharmaceutical conglomerates with captive sterile networks, mid-scale specialists with dedicated aseptic suites, and emerging 503B outsourcing facilities. Strategic archetypes include backward-integrated API-to-finished-dose operators, technology-licensed aseptic specialists, and hospital-system-aligned service integrators. Dominant competitive moves center on lyophilization capacity expansion and isolator-based filling line upgrades.
Among European-parented operators, Fresenius Kabi exemplifies the technology-licensed aseptic specialist archetype through its parent's sterile processing portfolio. Hikma Pharmaceuticals plc occupies a position within the backward-integrated tier, with its corporate structure suggesting captive API sourcing capabilities. Pfizer Inc. anchors the hospital-system-aligned service integrator segment, with its scale position supporting dedicated capacity for institutional contracts. These three entities represent distinct competitive vectors rather than direct substitutes, with procurement patterns splitting across complexity requirements and supply continuity priorities.
| Leading Market Players |
|---|
| Hikma Pharmaceuticals plc |
| Fresenius Kabi |
| Pfizer Inc. |
| Sandoz AG |
| Jubilant Pharma Limited |
| Baxter |
| PCI Pharma Services |
| Gland Pharma Limited (USA) |
| Grand River Aseptic Manufacturing |
| Others |
Pricing and Supply Chain Analysis
API import price indices from Indian and Chinese suppliers cascade through US generic injectables contract manufacturing into three distinct pricing tiers. Hospital-system buyers absorbing supply continuity premiums anchor the premium tier, while volume-driven infectious disease contracts compress margins at the economy tier.
Pricing Analysis
Yield-guarantee pricing anchors hospital-system contracts, with multi-source oncology agreements commanding premiums for sterility assurance and shortage mitigation. Three-tier pricing structure across premium, standard, and economy levels separates validated isolator-based manufacturers from legacy batch operators and commodity volume producers. Cost compression in standard-tier liquid injectables is intensifying because FDA import alerts on offshore API facilities are compressing domestic capacity. Group purchasing organizations in the Northeast exhibit the highest price sensitivity, while Texas integrated delivery networks prioritize supply continuity over per-unit cost.
Supply Chain Analysis
Direct-to-hospital contracts handle high-complexity sterile demand, with dedicated capacity agreements bypassing wholesale allocation mechanisms. Active pharmaceutical ingredient supply draws from India, China, and limited US captive production, creating concentrated dependency on FDA-inspected offshore facilities. USP Chapter 797 compliance materials, specialized aseptic equipment, and validated cold chain logistics constitute critical input dependencies. Single-source vulnerability in platinum-based chemotherapy APIs represents the dominant structural risk, with Indian supplier concentration exposing buyers to import alert disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US generic injectables contract manufacturing operates as a capacity-constrained market where ISO 5 cleanroom scarcity props pricing power for validated operators. Hospital procurement consolidation is accelerating supplier qualification bottlenecks.
For Market Incumbents: Deploy lyophilization capacity expansion as the primary defensive lever. Add freeze-dried powder suites in Midwest manufacturing clusters to capture oncology margin premiums. Backward integration into unstable API sourcing mitigates Indian supplier concentration risk from FDA import alerts.
For New Entrants and Emerging Players: Begin with 503B outsourcing facility partnerships in Florida and Texas home infusion markets. Specialty pharmacy networks in these states represent the most penetrable channel, with patient-ready format demand outpacing domestic supply. Pursue isolator technology licensing from European parent companies to shortcut FDA qualification timelines.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale aseptic specialists with underutilized ISO 5 capacity in the Northeast. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than commodity scale. Watch FDA foreign facility inspection frequency as the inflection signal for supply redirection toward domestic assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Freeze-dried oncology formulations command margin premiums over liquid presentations. |
| Isolator Technology Licensing | European parent company portfolios compress FDA qualification timelines for US entrants. |
| 503B Outsourcing Facility Partnership | Florida home infusion demand redirects hospital compounding volume toward registered facilities. |
| Backward API Integration | Captive sourcing of unstable chemotherapy inputs reduces Indian supplier concentration exposure. |
| Group Purchasing Organization Consolidation | Northeast GPO master service agreements anchor multi-site sterile injectable procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital pharmacy directors, GPO contracts managers, sterile manufacturing executives, and regulatory affairs leads combined with FDA 483 observation databases, USP Chapter 797 guidance documents, and Drug Shortage Database entries. Bottom-up capacity modeling and top-down procurement flow analysis triangulated market sizing.
Granularity-level modeling deployed treatment line, dosage form, and regional regulatory cluster dimensions at the segment level. CAGRs derived from capacity expansion timelines, FDA approval velocity, and hospital procurement contract renewal patterns across the analysis window. Sterile processing technician training pipeline constraints and isolator equipment lead times fed industry-specific forecast inputs.
Underlying measurement precision varies by segment; oncology and anti-infective therapy areas carry tighter precision than cardiovascular and pain management categories. Forecasts reflect assumptions regarding FDA inspection intensity, API import alert frequency, and hospital consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market