
 Carbetocin Injection Market | 2026-2036
Carbetocin Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Carbetocin Injection Market Analysis
Hospital procurement consortiums is reshaping how carbetocin injection reaches end users across emerging markets. Ferring Pharmaceuticals leverages its peptide synthesis heritage to sustain premium positioning in European institutional channels. Intas Pharmaceuticals anchors Indian public-sector tenders through cost-optimized vial formats. Chengdu Shengnuo Biotechnology dominates domestic distribution networks within China's tier-one city hospital systems.
Carbetocin injection is a synthetic long-acting oxytocin analog, typically formulated as a 100 microgram per milliliter sterile solution for parenteral administration, manufactured through solid-phase peptide synthesis followed by aseptic filling. Its primary clinical purpose is preventing uterine atony and postpartum hemorrhage following cesarean section, where prolonged receptor activation reduces the need for repeat dosing. Pre-filled syringe formats command attention where medication safety protocols prioritize dose accuracy and reduced preparation error in operating theaters. Intravenous administration routes lead in surgical settings due to rapid onset, though intramuscular delivery retains share in resource-limited clinics lacking infusion infrastructure. Hospital end users represent the mature volume base, while ambulatory surgical centers emerge as a faster-growing channel where same-day discharge protocols expand.
FDA and EMA standards govern active pharmaceutical ingredient purity and endotoxin limits for carbetocin injection marketed in the United States and European Union, while WHO prequalification programs shape eligibility for donor-funded procurement in low-income countries. India's CDSCO enforces batch-release testing that determines market access for domestic manufacturers and import licensees alike. Stakeholders must monitor evolving pharmacopeial harmonization between ICH regions and WHO norms, as divergence in stability-indicating assay requirements could fragment registration pathways and complicate multi-territory supply strategies.
Market Dynamics
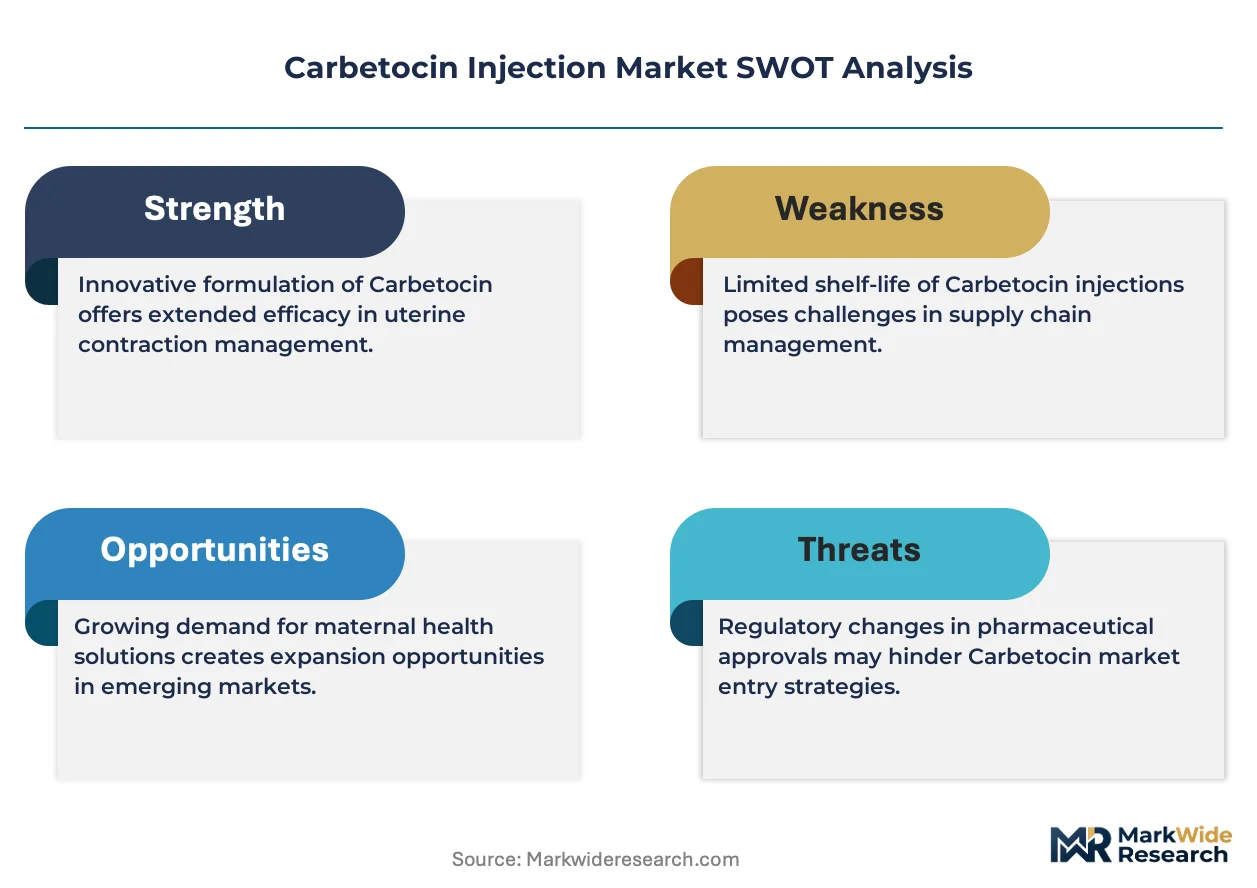
WHO prequalification requirements for postpartum hemorrhage prevention medicines are compressing registration timelines and forcing manufacturers to harmonize stability protocols across ICH and non-ICH pharmacopeias simultaneously.
Growth Catalysts
- India's Janani Suraksha Yojana:Conditional cash transfers for institutional deliveries are channeling carbetocin procurement through state-level tender systems in Uttar Pradesh and Bihar.
- EMA's MDR alignment:Updated medical device regulations for combination products are accelerating pre-filled syringe adoption in European tertiary maternity units.
- Solid-phase peptide synthesis:Advances in resin chemistry and coupling efficiency are reducing batch-to-batch variability for long-acting oxytocin analogs.
Market Restraints
- Cold-chain dependency:Carbetocin's thermal stability requirements limit distribution to facilities with verified 2-8°C storage in sub-Saharan Africa and rural South Asia.
- Oxytocin substitution:Heat-stable carbetocin formulations remain priced at multiples of conventional oxytocin in donor-funded procurement pools, constraining volume uptake.
- API concentration:Peptide synthesis capabilities cluster among European and Indian contract manufacturers, creating single-source vulnerability for non-integrated injectable developers.
Strategic Opportunities
- Indonesia's Jaminan Kesehatan Nasional expansion:Universal health coverage enrollment is extending cesarean coverage to district hospitals previously reliant on ergometrine.
- Ambulatory surgical centers:Same-day discharge protocols for elective cesarean sections are creating demand for single-dose uterotonics with reduced monitoring requirements.
- WHO Expert Committee on Selection and Use of Essential Medicines:Listings updates for heat-stable uterotonics are unlocking Gavi and Global Fund co-financing mechanisms.
Industry Challenges
- Peptide analytical chemistry expertise:Shortages of specialists capable of validating stability-indicating HPLC methods for cyclic peptide analogs are extending analytical development timelines.
- Multi-territory registration divergence:Misalignment between FDA's peptide impurity thresholds and WHO prequalification acceptance criteria forces parallel dossier construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbetocin Injection Market |
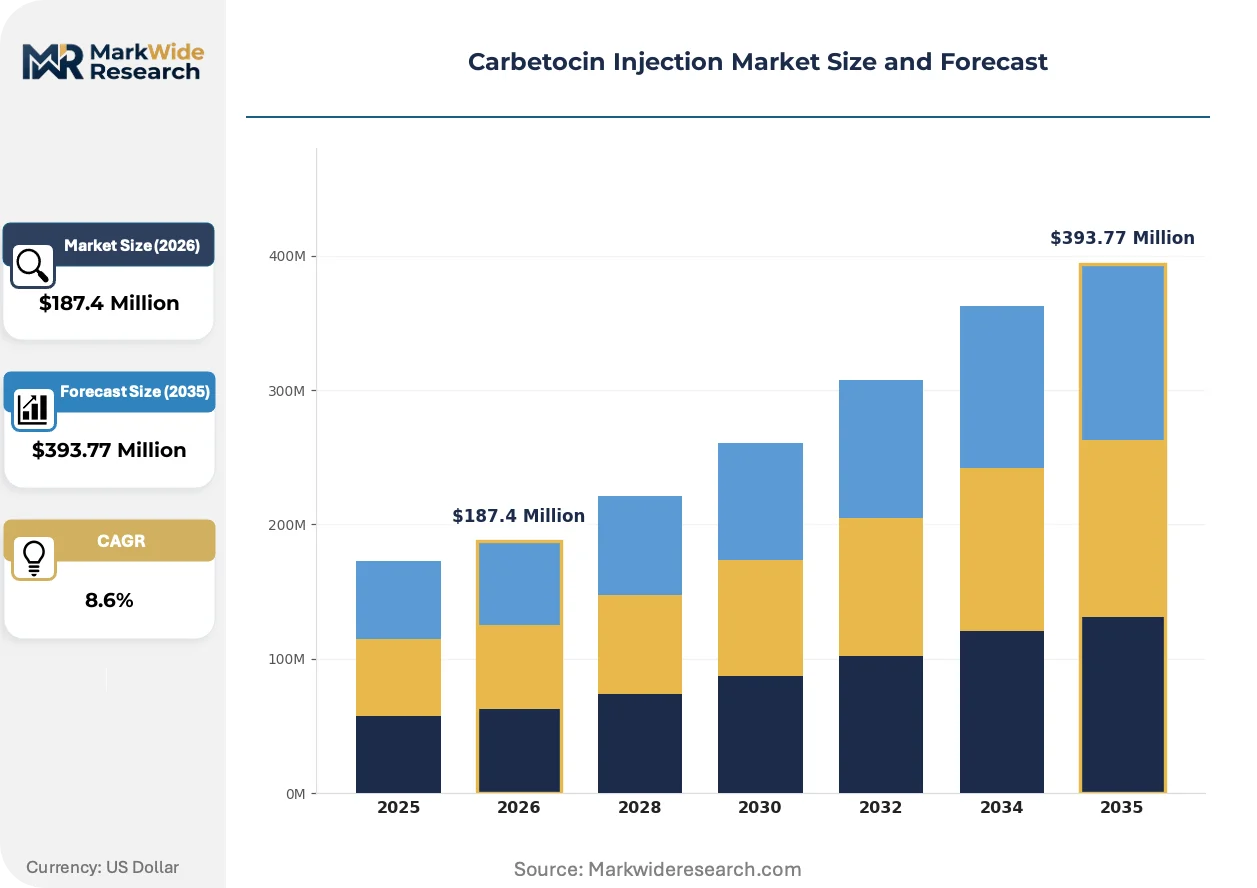
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringe, Vial, Pre-filled Syringe, Ampoule Administration Route: Intravenous, Intramuscular, Subcutaneous, Oral End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Packaging Type: Blister Pack, Bulk Containers, Eco-friendly Packaging, Secondary Packaging |
| Companies Covered | Intas Pharmaceuticals, Chengdu Shengnuo Biotechnology, Ferring Pharmaceuticals, PolyPeptide Laboratories, Suzhou Tianma Pharmaceutical, Alembic Pharmaceuticals, Hetero Biopharma, Incepta Pharmaceuticals, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbetocin Injection Market Emerging Trajectories
Formulation science and distribution infrastructure are converging to redefine how long-acting uterotonics reach surgical settings, with thermal stability and dose precision now competing as primary value drivers.
Pre-filled syringe presentation is migrating from glass barrel systems to polymer-based alternatives with integrated needle safety mechanisms. Operating theater nurses in European and North American hospitals are selecting these formats to reduce dosing errors and sharps injuries. This technology is migrating from premium private-sector channels toward public procurement specifications, compressing demand for conventional vial-and-needle configurations.
EMA's updated guidelines on excipient qualification for parenteral peptides are requiring manufacturers to document leachable profiles for elastomeric closures and lubricants. The industrial consequence is a wave of forced reformulation among legacy products using non-compliant rubber formulations. Indian and Chinese exporters targeting EU institutional channels are most affected, with several CDSCO-registered products requiring supplemental stability studies.
Hospital procurement consortiums are consolidating uterotonic purchasing through centralized tender platforms with mandated quality certification tiers. Group purchasing organizations in Germany and France are displacing direct manufacturer relationships for individual maternity units. This consolidation is most visible in Western European markets where hospital network mergers have reduced the number of independent contracting entities by half over the past decade.
Carbetocin Injection Market Segmentation
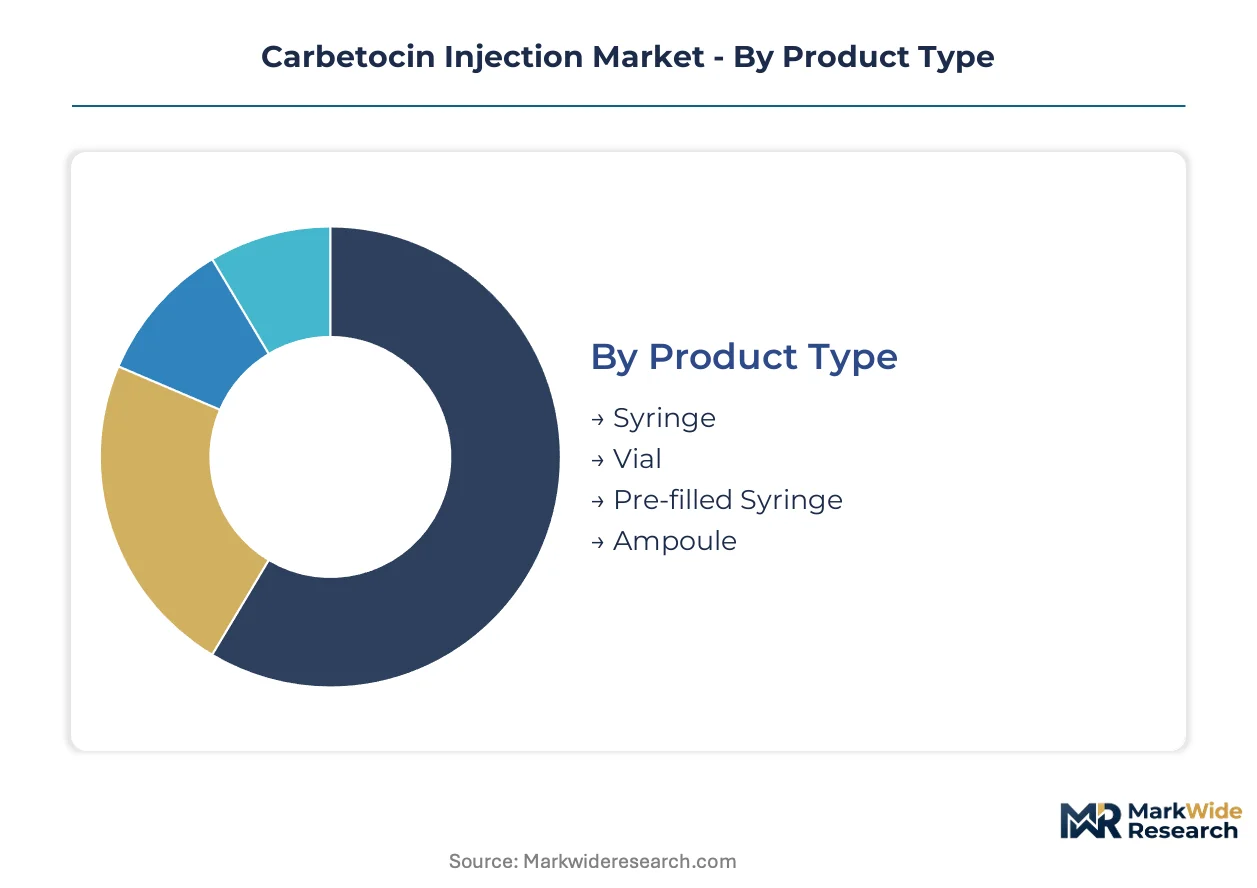
Segmentation in the carbetocin injection market reveals how clinical workflow requirements, storage infrastructure, and procurement economics fragment demand across product formats. Understanding these divisions illuminates where manufacturers must prioritize formulation investments versus distribution partnerships.
Product Type:
Cycle times vary dramatically across presentation formats, with pre-filled syringes turning over fastest in high-throughput surgical settings while bulk vials linger in procurement inventories for months.
- Pre-filled Syringe:Integrated needle-safety systems eliminate preparation steps in operating theaters. European tertiary maternity units under EMA's MDR alignment are mandating these formats for dose accuracy compliance.
- Vial:Multi-dose glass containers with rubber stoppers dominate Indian state tender systems through cost-optimized unit economics. Uttar Pradesh and Bihar procurement channels favor this format for centralized hospital dispensing.
- Syringe:Conventional Luer-lock designs persist in resource-limited clinics where nurses perform manual drawing. These retain share where cold-chain verification infrastructure is unreliable.
- Ampoule:Single-use glass ampoules with score-break necks serve emergency field kits in sub-Saharan Africa. WHO prequalification programs include this format for humanitarian stockpiles.
Vial formats dominate installed base across South Asian public procurement. Pre-filled syringe is where expansion concentrates in European institutional channels.
Administration Route:
Route selection tracks directly against facility infrastructure tiers, with intravenous delivery commanding premium pricing in surgical suites while intramuscular options penetrate lower-resource settings.
- Intravenous:Rapid onset through peripheral or central venous access makes this standard for cesarean sections in tier-one city hospital systems. Chengdu Shengnuo Biotechnology distribution networks prioritize IV-compatible presentations.
- Intramuscular:Gluteal or deltoid injection suits clinics lacking infusion pumps. India's Janani Suraksha Yojana channel funds this route for district-level facilities.
- Subcutaneous:Abdominal or thigh administration appears in ambulatory surgical center protocols where same-day discharge minimizes monitoring duration.
- Oral:Bioavailability limitations restrict this route to investigational or combination therapy contexts. No major commercial volume flows through oral presentations currently.
Intravenous delivery anchors revenue concentration. Intramuscular is gaining share fastest where universal health coverage extends cesarean access to previously underserved hospitals.
End User:
Customer type segmentation exposes a bifurcation between consolidated hospital procurement and fragmented clinic purchasing power.
- Hospitals:Tertiary maternity units with centralized pharmacy operations generate volume through annual tender cycles. Group purchasing organizations in Germany and France aggregate demand across merged hospital networks.
- Ambulatory Surgical Centers:Same-day discharge protocols for elective cesarean sections create demand for simplified dosing regimens. These facilities represent the steepest expansion trajectory among end-user categories.
- Clinics:Primary care and rural health centers rely on intramuscular formats where cold-chain infrastructure is intermittent. Indonesia's Jaminan Kesehatan Nasional expansion targets these facilities for coverage extension.
- Homecare:Postpartum monitoring in residential settings remains minimal due to injection safety requirements and thermal stability concerns. This segment captures negligible current volume.
Hospitals dominate installed base. Ambulatory surgical centers concentrate expansion activity where same-day protocols proliferate.
Packaging Type:
Packaging economics stratify across sustainability mandates, with eco-friendly formats commanding procurement premiums in European markets while bulk containers minimize per-unit costs in donor-funded programs.
- Secondary Packaging:Carton and insert combinations carrying batch records and temperature indicators satisfy CDSCO batch-release documentation requirements for Indian export shipments.
- Eco-friendly Packaging:Recyclable or biodegradable materials align with EU Green Deal procurement specifications. French hospital consortiums now mandate environmental impact scoring in tender evaluations.
- Blister Pack:Individual cavity protection for pre-filled syringes prevents damage during tropical distribution. WHO prequalification stability protocols favor this configuration for heat-zone deployment.
- Bulk Containers:Multi-unit shipping cases reduce per-dose freight costs for Gavi and Global Fund co-financed procurement pools. These minimize packaging waste where waste management infrastructure is limited.
Bulk containers dominate installed base in donor-funded channels. Eco-friendly packaging is where expansion concentrates as European procurement environmental criteria tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European institutional channels where EMA's MDR alignment commands premium positioning, while South Asian tender systems compress margins through volume-scale procurement. This asymmetry shapes divergent competitive strategies across geographies.
Germany
Group purchasing organizations aggregate uterotonic demand across merged hospital networks in North Rhine-Westphalia and Bavaria. EMA's updated medical device regulations for combination products accelerate pre-filled syringe adoption in tertiary maternity units. Frankfurt and Munich hospital consortiums now mandate environmental impact scoring in tender evaluations under EU Green Deal specifications.
India
Janani Suraksha Yojana conditional cash transfers channel carbetocin procurement through state-level tender systems in Uttar Pradesh and Bihar. CDSCO batch-release testing determines market access for domestic manufacturers and import licensees alike. Ahmedabad and Hyderabad pharmaceutical clusters anchor cost-optimized vial production for public-sector distribution.
China
Rising cesarean deliveries in tier-one city hospital systems expand prophylactic uterotonic use in the Yangtze River Delta and Pearl River Delta. NMPA stability-indicating assay requirements govern synthetic oxytocin analog registration pathways. Chengdu and Shanghai distribution networks prioritize IV-compatible presentations for surgical suite integration.
France
Hospital network mergers have reduced independent contracting entities by half over the past decade, consolidating uterotonic purchasing through centralized tender platforms. ANSM excipient qualification guidelines for parenteral peptides force reformulation among legacy products using non-compliant rubber formulations. Paris and Lyon maternity units under EMA MDR alignment mandate dose accuracy compliance through integrated needle-safety systems.
Indonesia
Jaminan Kesehatan Nasional universal health coverage expansion extends cesarean access to district hospitals previously reliant on ergometrine in Java and Sumatra. The national pharmaceutical regulator enforces cold-chain verification for 2-8°C storage compliance in tropical distribution. Jakarta and Surabaya procurement channels favor intramuscular formats where infusion infrastructure remains limited.
Carbetocin Injection Market Vendor Landscape
Peptide synthesis specialists and regional formulation houses split the market between premium institutional channels and cost-optimized public procurement. European manufacturers leverage solid-phase synthesis heritage for quality-tier positioning, while South Asian producers capture volume through tender-optimized unit economics. Three archetypes dominate: integrated peptide API developers, regional injectable formulators, and multinational hospital suppliers. Competitive moves concentrate on pre-filled syringe portfolio expansion and WHO prequalification dossier harmonization.
Among European peptide synthesis specialists, Ferring Pharmaceuticals occupies a position exemplifying premium-tier institutional positioning through heritage manufacturing capabilities. Intas Pharmaceuticals and Chengdu Shengnuo Biotechnology represent the regional formulator archetype, anchoring cost-optimized supply for South Asian and Chinese public procurement channels respectively. These three entities illustrate how geographic origin and company structure shape divergent strategic postures across pricing-power asymmetries.
| Leading Market Players |
|---|
| Intas Pharmaceuticals |
| Chengdu Shengnuo Biotechnology |
| Ferring Pharmaceuticals |
| PolyPeptide Laboratories |
| Suzhou Tianma Pharmaceutical |
| Alembic Pharmaceuticals |
| Hetero Biopharma |
| Incepta Pharmaceuticals |
| Abbott |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across carbetocin injection supply tiers, with container freight volatility amplifying price spreads between European institutional buyers and South Asian tender systems. Peptide API concentration in Swiss and Indian manufacturing clusters enables premium positioning where EMA MDR compliance commands configured-to-order pricing, while bulk vial formats face margin compression in Uttar Pradesh state procurement channels.
Pricing Analysis
Configured-to-order pre-filled syringes with integrated needle-safety systems command spreads of 40-60% above standard multi-dose vial formats across European tertiary maternity units. Pricing stratifies across WHO prequalification tier, EMA MDR certification grade, and volume scale commitments in Gavi co-financed procurement pools. Cost compression in Indian state tender systems intensifies as Janani Suraksha Yojana channels consolidate annual volumes, with district-level facilities exhibiting highest price sensitivity and Swiss hospital consortiums least.
Supply Chain Analysis
Export-control restrictions on solid-phase peptide synthesis equipment limit technology transfer to non-ICH pharmacopeia jurisdictions, constraining API manufacturing expansion beyond established European and Indian hubs. Raw material dependencies center on Fmoc-protected amino acids, specialized resins, and aseptic filling isolators sourced from Switzerland, Germany, and the United States. Single-source vulnerability concentrates in cyclic peptide analytical chemistry expertise, with distribution running through hospital procurement consortiums in Western Europe and state-level tender platforms in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbetocin injection procurement is approaching a platform-economics inflection as WHO prequalification harmonization with EMA MDR standards creates interoperability requirements across donor-funded and institutional channels.
For Market Incumbents: Pre-empt heat-stable formulation substitution threats by accelerating backward integration into peptide API manufacturing and securing exclusive distribution through Jakarta and Surabaya hospital networks. Prioritize CDSCO batch-release certification investments to defend position in Indian state tender systems against emerging Chinese entrants.
For New Entrants and Emerging Players: Indonesia's district hospital tier offers underpenetrated access where Jaminan Kesehatan Nasional expansion extends cesarean coverage beyond Jakarta's tier-one facilities. Target intramuscular format penetration in Java and Sumatra clinics lacking infusion infrastructure, leveraging cost-optimized vial economics against incumbent pre-filled syringe positioning.
For Investors and Strategic Acquirers: Carve-out targets emerge from European mid-cap peptide synthesis houses with stranded WHO prequalification dossiers and underutilized solid-phase manufacturing capacity. Long-term viability hinges on heat-stable uterotonic platform transitions; monitor WHO Expert Committee Essential Medicines listings updates as inflection signal for Gavi and Global Fund co-financing unlock.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Dossier Harmonization | Unlocks Gavi and Global Fund procurement eligibility for heat-stable formulations across sub-Saharan Africa. |
| Pre-filled Syringe Manufacturing Scale-Up | Addresses EMA MDR compliance requirements in German and French hospital consortium tender specifications. |
| Peptide API Backward Integration | Reduces batch-to-batch variability exposure from European and Indian contract manufacturer concentration. |
| Cold-Chain Distribution Partnership | Extends 2-8°C verified storage reach to Indonesia's district hospitals and rural South Asian clinics. |
| Heat-Stable Formulation Development | Aligns with WHO guidelines on postpartum hemorrhage prevention in tropical distribution environments. |
Methodological Framework
A standing panel of hospital procurement managers, regulatory affairs leads at CDSCO-registered manufacturers, and formulary directors at European tertiary maternity units provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA filings, EMA MDR submission databases, WHO prequalification assessment reports, and Indian state tender documentation. Bottom-up volume modeling triangulated against top-down pharmaceutical market sizing from customs trade data and hospital procurement consortium contract disclosures.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated WHO Essential Medicines listing trajectories. Segmentation dimensions spanned presentation format, administration route, end-user facility tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical cesarean delivery rates and uterotonic prophylaxis penetration patterns, with peptide synthesis capacity expansion and cold-chain infrastructure buildout as key forecast inputs across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese peptide manufacturers or accelerated heat-stable carbetocin approvals would shift outcomes. Material shifts in WHO prequalification stability protocol harmonization or EMA excipient qualification enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Capecitabine Market