
 Immunoglobulin Market | 2026-2036
Immunoglobulin Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoglobulin Market Intelligence
The expansion of specialty pharmacy networks is reconfiguring immunoglobulin delivery from traditional hospital settings to homecare. This shift puts new emphasis on logistics and patient support services. CSL Behring leverages its extensive plasma collection infrastructure to ensure supply stability for its broad portfolio. Grifols competes on the basis of its global manufacturing scale, while Takeda Pharmaceutical Company Limited differentiates through its focus on rare disease therapies, including primary immunodeficiency.
Immunoglobulins are highly purified antibody proteins, primarily IgG, derived from pooled human plasma. These biologics function to replace or modulate the immune system in patients with specific disorders. Intravenous Immunoglobulin (IVIg) remains the dominant product type by volume, but Subcutaneous Immunoglobulin (SCIg) represents the fastest-growing segment due to its suitability for home administration. Within therapy areas, applications in neurological disorders are expanding, adding to the established demand from primary immunodeficiency treatment.
Market access is governed by stringent regulatory frameworks for plasma-derived medicines. The U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) enforce rigorous standards for plasma collection and product safety. These regulations, alongside those from bodies like China's NMPA, dictate manufacturing protocols and clinical evidence needed for approval. Navigating the complex plasma supply chain to meet demand for both existing and emerging therapeutic indications remains a critical strategic challenge.
Market Dynamics
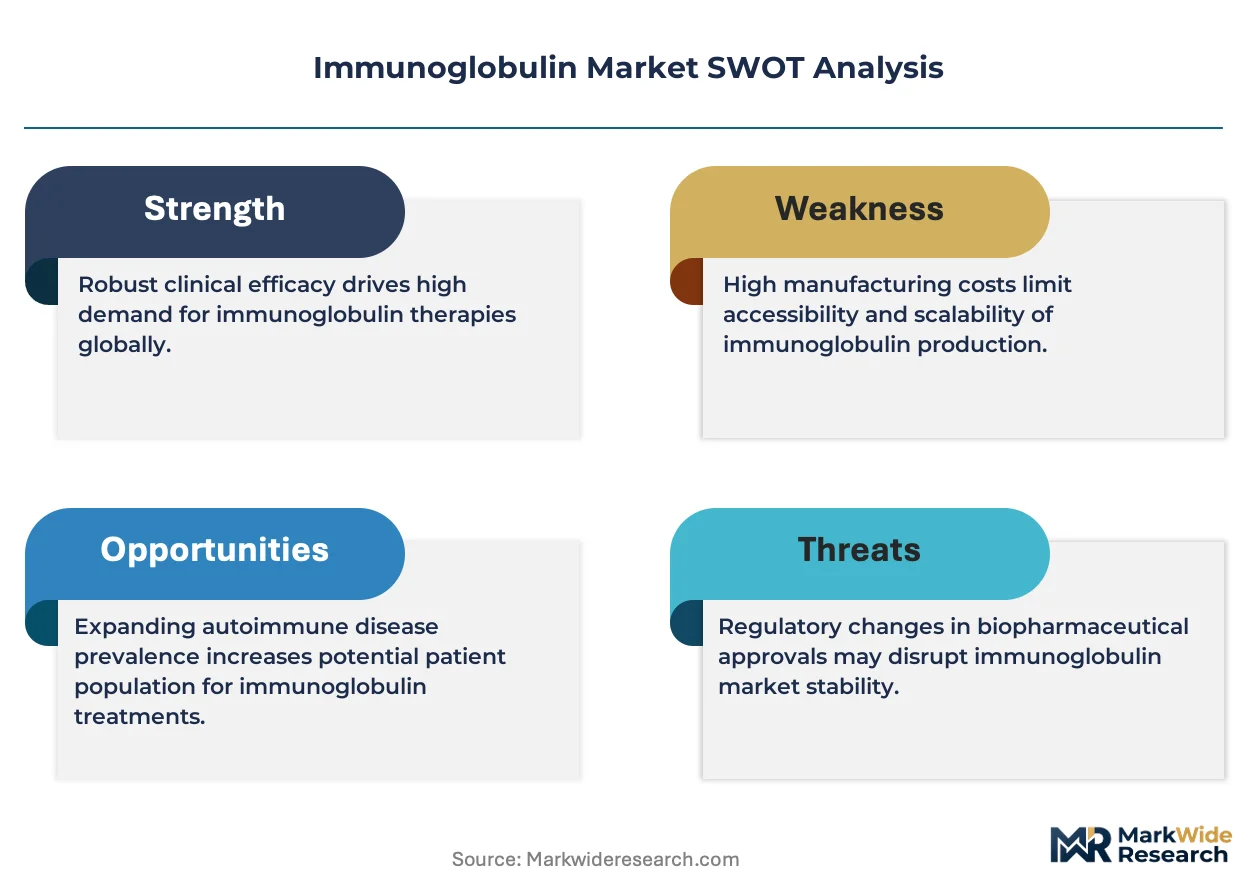
The immunoglobulin market's core dynamic is the structural tension between a constrained, highly regulated human plasma supply chain and expanding clinical demand. This is driven by an increasing number of approved therapeutic indications, particularly in neurology, which strains finite plasma collection capacity.
Growth Catalysts
- Expanding Therapeutic Applications:Regulatory approvals from bodies like the U.S. FDA for immunoglobulins in treating neurological conditions, such as chronic inflammatory demyelinating polyneuropathy (CIDP), are opening new, high-value patient populations beyond primary immunodeficiency.
- Demographic Shifts in Asia:An aging population and rising diagnoses of autoimmune diseases in countries like China are fueling substantial demand for plasma-derived therapies, supported by expanding public and private healthcare access.
- Subcutaneous Formulation Adoption:The development of high-concentration subcutaneous immunoglobulin (SCIg) products facilitates home-based administration, improving patient quality of life and reducing the burden on hospital infusion centers, which drives uptake.
Market Restraints
- Plasma Supply Dependency:The entire market is fundamentally constrained by the volume of source plasma collected from human donors, creating inherent supply-side volatility and susceptibility to disruptions from public health events or regulatory changes.
- Stringent Regulatory Hurdles:The rigorous safety and manufacturing protocols enforced by the EMA and other national regulators create high barriers to entry and lengthen product development timelines, limiting the number of producers.
- Competition from Targeted Biologics:For specific autoimmune indications, newer monoclonal antibodies and small molecule drugs offer more targeted mechanisms of action, posing a long-term substitution threat to immunoglobulin therapies in select disease areas.
Strategic Opportunities
- Underpenetrated Geographic Markets:Expanding into Latin American and Southeast Asian markets, where healthcare spending is rising and access to advanced biologics is improving, presents a significant avenue for volume growth.
- Secondary Immunodeficiency Treatment:There is a growing clinical need for immunoglobulin therapy to manage secondary immunodeficiencies (SID) that arise from hematological malignancies or immunosuppressive treatments, representing a nascent application area.
- Development of Recombinant Products:Investing in recombinant immunoglobulin technologies offers a long-term strategy to mitigate dependence on the human plasma supply chain, potentially creating a more stable and scalable manufacturing model.
Industry Challenges
- Cold Chain Logistics Complexity:The shift to homecare for SCIg products necessitates a more complex and decentralized cold chain infrastructure to ensure product stability and efficacy from the pharmacy to the patient's residence.
- Navigating Plasma Collection Regulations:Manufacturers face significant operational challenges in managing plasma collection centers across different national regulatory frameworks, such as those in the United States and Germany, which have varying donor compensation and screening rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoglobulin Market |
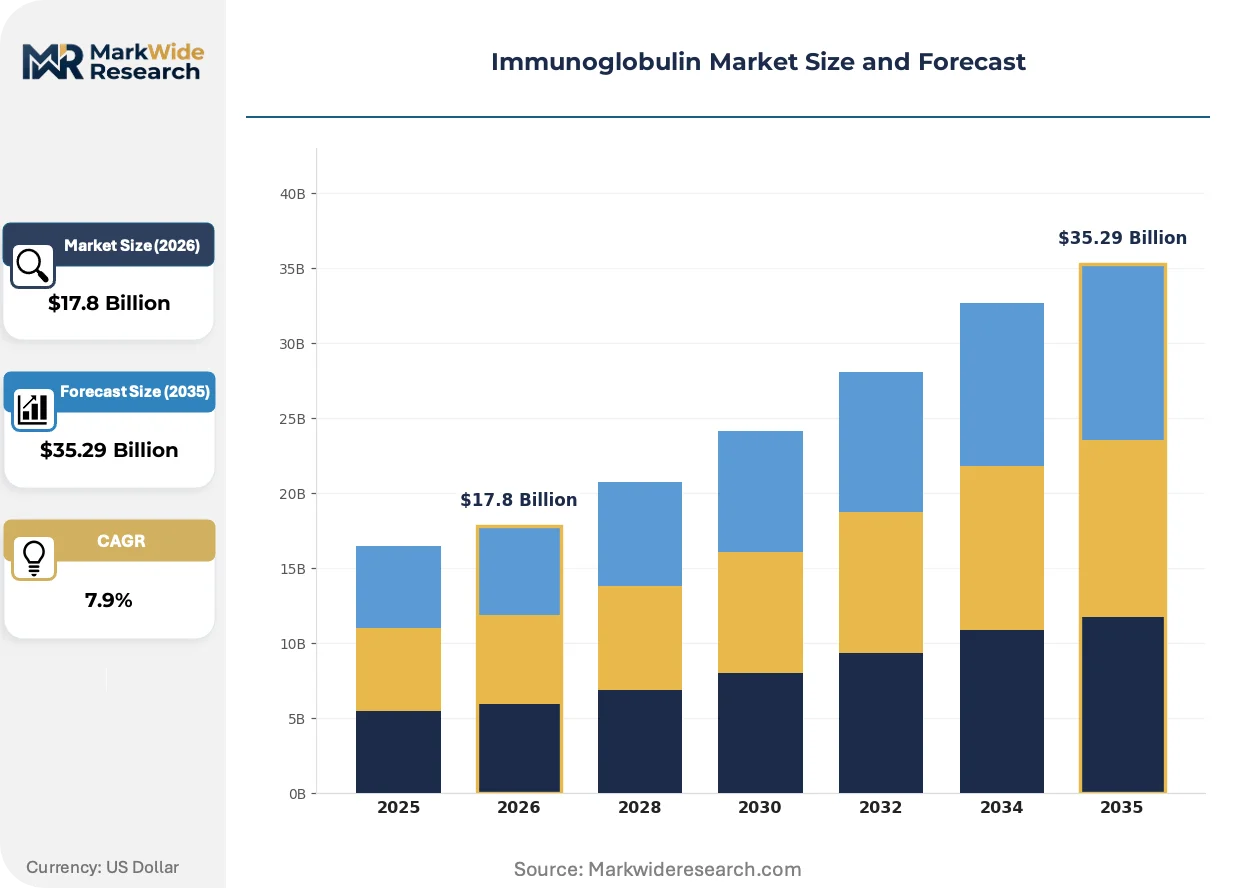
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $35.29 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Immunoglobulin, Subcutaneous Immunoglobulin, Recombination Immunoglobulin, Hyperimmune Globulin Therapy Area: Autoimmune Disorders, Infectious Diseases, Immunodeficiency Disorders, Neurological Disorders End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Distribution Channel: Direct Sales, Wholesale, Online, Retail Pharmacies |
| Companies Covered | CSL Behring, Grifols, Takeda Pharmaceutical Company Limited, Octapharma AG, Kedrion Biopharma, Biotest AG, ADMA Biologics, LFB Group, Bio Products Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoglobulin Market Strategic Shifts & Innovations
Patient-centric care models are fundamentally altering the immunoglobulin market's structure, with innovations in-home administration and digital support systems gaining prominence. This evolution is supported by regulatory frameworks adapting to new delivery methods and advanced manufacturing techniques aimed at improving product efficacy.
Digital health platforms that integrate with infusion pumps are a key product evolution. Patients with chronic conditions like primary immunodeficiency are adopting these systems to track their subcutaneous immunoglobulin (SCIg) infusions and report outcomes from home. This technology is virtualizing aspects of patient monitoring and support, reducing the need for frequent in-person clinic visits and empowering self-management of therapy.
The European Medicines Agency's (EMA) continuous review of guidelines for plasma-derived medicinal products influences manufacturing protocols across the continent. These regulations mandate stringent donor screening, plasma testing, and viral inactivation steps, which increases the compliance burden for plasma fractionators. The intravenous immunoglobulin (IVIg) segment is most impacted, as producers must validate their processes against these evolving pan-European safety standards.
A significant behavioral change is the formalization of home infusion services through specialty pharmacy networks. This model disrupts the traditional hospital outpatient channel by providing end-to-end services, including medication delivery, nursing support, and reimbursement assistance directly to patients. This service-centric approach is most advanced in the United States, where it aligns with payer objectives to shift care to lower-cost settings.
Immunoglobulin Market Segmentation
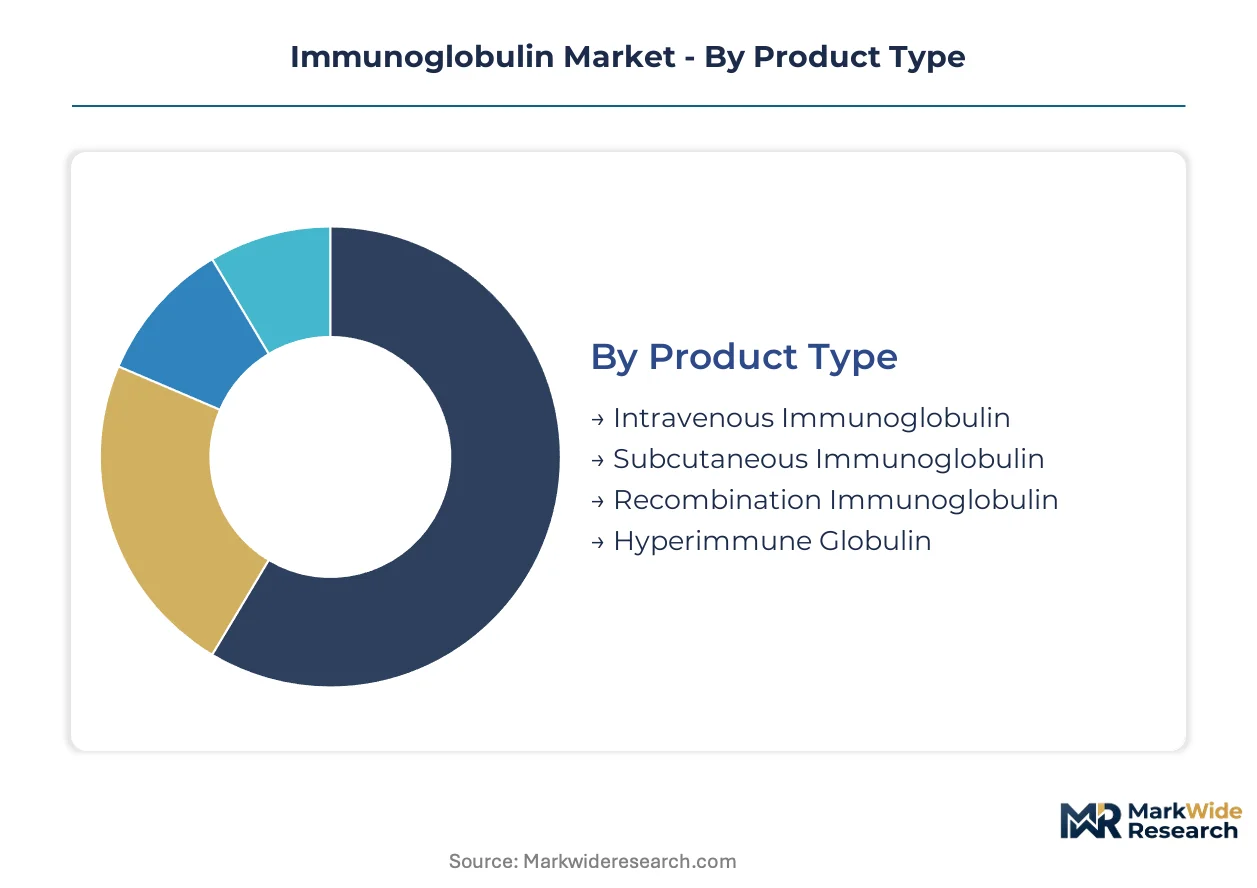
The Immunoglobulin market's segmentation reveals the diverse pathways through which these critical biologics reach patients, highlighting the varying levels of service intensity required for different product types and end-use environments. Understanding these distinct segments is crucial for manufacturers to optimize their distribution strategies and tailor patient support programs.
Product Type:
The after-sales service intensity varies significantly across immunoglobulin product types, influenced by administration route and patient self-management capabilities.
- Intravenous Immunoglobulin (IVIg):This product type consists of highly purified IgG antibodies administered directly into a patient's vein, typically requiring clinical oversight for infusion. IVIg remains the dominant product by volume, serving established demand for primary immunodeficiency treatment in hospital settings globally.
- Subcutaneous Immunoglobulin (SCIg):SCIg formulations deliver IgG antibodies under the skin, enabling self-administration at home and reducing the need for frequent clinic visits. This segment represents the fastest-growing product type, driven by enhanced patient convenience and the shift towards homecare settings in countries like the United States.
- Recombination Immunoglobulin:These are genetically engineered antibody proteins, offering a potential long-term alternative to plasma-derived products by mitigating supply chain dependencies. Development is focused on achieving stable, scalable manufacturing without human plasma.
- Hyperimmune Globulin:This segment comprises specialized immunoglobulin products with high titers of specific antibodies, used for prophylaxis or treatment of particular infectious diseases. Demand arises from targeted interventions against specific pathogens.
Intravenous Immunoglobulin holds the largest share; momentum sits with Subcutaneous Immunoglobulin.
Therapy Area:
Different therapy areas dictate specific application requirements and patient populations, influencing product development and market access strategies for immunoglobulin therapies.
- Neurological Disorders:This application area involves the use of immunoglobulins to treat conditions such as chronic inflammatory demyelinating polyneuropathy (CIDP) and multifocal motor neuropathy. Regulatory approvals from bodies like the U.S. FDA are expanding patient populations and driving high-value demand in these indications.
- Immunodeficiency Disorders:Immunoglobulins replace deficient antibodies in patients with primary or secondary immunodeficiencies, restoring immune function. This established application forms a foundational demand segment, with consistent patient needs for lifelong therapy.
- Autoimmune Disorders:Immunoglobulins modulate immune responses in various autoimmune conditions, such as systemic lupus erythematosus or certain vasculitides. Research continues to explore new indications, potentially expanding the therapeutic scope.
- Infectious Diseases:Immunoglobulins provide passive immunity against specific pathogens or offer broad-spectrum immune support in severe infections. This application often involves hyperimmune globulins for targeted protection.
The dominant segment is Immunodeficiency Disorders, with Neurological Disorders showing significant expansion.
End User:
The end-user landscape for immunoglobulins is undergoing a structural shift, moving from centralized care to more decentralized, patient-centric models.
- Hospitals:Hospitals serve as traditional sites for IVIg administration, particularly for complex cases, initial treatments, or patients requiring close medical supervision. These institutions manage a substantial volume of immunoglobulin infusions globally.
- Homecare:Homecare settings facilitate the self-administration of SCIg products, improving patient quality of life and reducing healthcare system burden. This segment benefits from advanced digital health platforms for patient monitoring and support.
- Specialty Pharmacies:Specialty pharmacies provide end-to-end services for immunoglobulin patients, including medication delivery, nursing coordination, and reimbursement assistance. This model supports the formalization of home infusion services, particularly in the United States.
- Clinics:Clinics, including infusion centers, offer an intermediate setting for immunoglobulin administration, balancing convenience with professional oversight. They cater to patients who require clinical support but do not necessitate full hospital admission.
A notable shift is occurring towards Homecare, while Hospitals remain foundational for complex treatments.
Distribution Channel:
The distribution channels for immunoglobulins must navigate complex cold chain logistics and evolving patient access models to ensure product integrity and timely delivery.
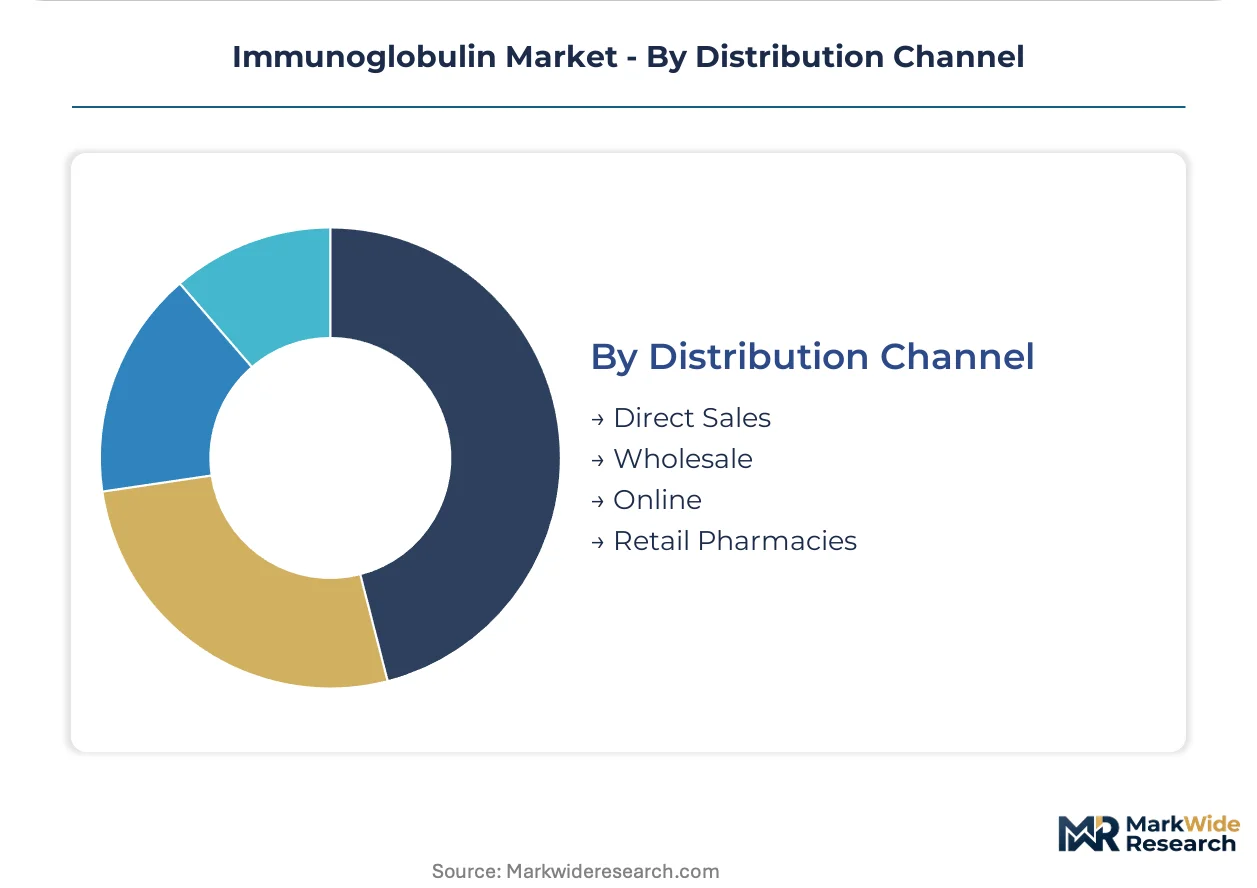
- Wholesale:The wholesale channel manages the large-scale distribution of immunoglobulin products from manufacturers to hospitals, clinics, and pharmacies. This channel is critical for ensuring broad market availability and efficient inventory management across healthcare systems.
- Specialty Pharmacies:Specialty pharmacies are increasingly vital for distributing high-cost, complex biologics like immunoglobulins, especially for home-based therapies. These pharmacies offer specialized handling, patient education, and coordination of care services.
- Direct Sales:Manufacturers utilize direct sales channels to supply large institutional buyers or specific government programs, often involving direct contracts and managed logistics. This channel allows for direct engagement and service provision.
- Online:The online channel, while nascent for direct immunoglobulin sales, supports patient education, prescription management, and coordination of home delivery services through integrated digital platforms. It complements physical distribution networks.
Wholesale channels manage the largest volume, with Specialty Pharmacies driving new service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global immunoglobulin market's regional dynamics are underwritten by disparate healthcare infrastructure and regulatory frameworks. This shapes patient access and supply chain efficiency across continents. Specialized plasma collection networks and advanced manufacturing capabilities determine geographic leadership in this critical biologics sector.
United States
The United States market benefits from expanding therapeutic applications in neurology and high adoption of homecare solutions. U.S. Food and Drug Administration (FDA) approvals for new indications consistently drive demand. The Boston-Cambridge biotech cluster remains a hub for advanced research and development in plasma-derived therapies.
Germany
Germany's robust healthcare infrastructure supports a significant demand for immunoglobulins, particularly from its aging population. European Medicines Agency (EMA) standards heavily influence manufacturing and product safety protocols. Frankfurt, a key biopharma manufacturing center, hosts major plasma fractionators ensuring supply.
China
China's expanding public and private healthcare access, coupled with an aging population, fuels substantial demand for plasma-derived therapies. The China National Medical Products Administration (NMPA) rigorously regulates plasma collection and product approval. The Yangtze River Delta region is witnessing significant investment in biopharmaceutical production and market access expansion.
Japan
Japan exhibits a high standard of medical care, driving demand for advanced immunoglobulin therapies, especially for rare diseases. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent quality and safety standards for all biologics. Major pharmaceutical companies in Tokyo and Osaka focus on research and development for new therapeutic solutions.
India
India's rising healthcare spending and growing awareness of immunodeficiency disorders are increasing the need for immunoglobulin products. The Central Drugs Standard Control Organization (CDSCO) oversees the approval and distribution of these critical medicines. Hyderabad, a prominent biotech hub, is developing manufacturing capabilities for complex biologics.
Immunoglobulin Market Key Industry Players
On the supply side, the industry is characterized by a high degree of consolidation among a few global players with extensive plasma collection and fractionation capabilities. These companies leverage their vertically integrated operations to manage complex supply chains. Dominant strategic archetypes include large-scale manufacturers, specialized rare disease innovators, and regional providers. Key competitive moves involve capacity expansion and strategic partnerships to secure plasma supply.
Within the large-scale manufacturer archetype, CSL Behring and Grifols anchor global supply with their vast plasma collection networks. These entities operate extensive manufacturing footprints across multiple continents. Takeda Pharmaceutical Company Limited occupies a position as a specialized innovator, focusing its immunoglobulin portfolio on rare disease therapies and primary immunodeficiency. These companies collectively demonstrate the industry's strategic emphasis on secure plasma sourcing and advanced product development.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols |
| Takeda Pharmaceutical Company Limited |
| Octapharma AG |
| Kedrion Biopharma |
| Biotest AG |
| ADMA Biologics |
| LFB Group |
| Bio Products Laboratory |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints in plasma collection determine both pricing tier spreads and the highly concentrated supply chain shape for immunoglobulin products. These stringent requirements ensure product safety but also limit the number of producers, influencing market dynamics.
Pricing Analysis
Volume-discount tiering structures characterize the procurement of immunoglobulins by large healthcare systems and specialty pharmacies. Price differentiation stems from the high quality grade of purified IgG and the specialized cold chain logistics required for delivery. Pricing softness exists for established indications due to the emergence of targeted biologics, while rare disease therapies command premium pricing. Hospitals and large volume buyers exhibit higher price sensitivity compared to patients requiring specialized, life-saving treatments.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common in the immunoglobulin market, reflecting the high value and long production cycles of these biologics. Geographic supply concentrates in the United States, which is a major plasma collection hub, and in Germany, a key biopharmaceutical manufacturing center. The market relies heavily on human plasma as its primary raw material. Single-source vulnerability due to the finite nature of human plasma presents a significant structural risk. Distribution runs through wholesale channels for hospitals and increasingly via specialty pharmacies for homecare settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunoglobulin market is experiencing high-growth disruption, driven by the technological inflection point of subcutaneous formulations enabling home administration.
For Market Incumbents: Build regulatory compliance moats by investing in advanced plasma collection and fractionation technologies. Expand manufacturing capacity in strategic regions to mitigate plasma supply volatility. This strategy helps secure market share against emerging threats from targeted biologics. Strengthen channel control through partnerships with specialty pharmacy networks, ensuring seamless product delivery and patient support.
For New Entrants and Emerging Players: Underpenetrated geographic markets in Latin America and Southeast Asia represent accessible entry points. Focus on the nascent application area of secondary immunodeficiency treatment, which offers a growing clinical need. A viable go-to-market angle involves developing recombinant immunoglobulin technologies, offering a long-term alternative to plasma-derived products and mitigating supply chain dependencies.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors vertically integrated specialists with robust plasma collection and fractionation capabilities. Sustained demand for chronic conditions and expanding neurological applications ensure long-term viability for these assets. Acquisition targets should include companies with established plasma collection networks or advanced recombinant product pipelines. Regulatory approvals for new neurological indications or recombinant product launches are key signals to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures future supply for neurological disorders and primary immunodeficiency patients. |
| Regulatory Approval Pathway | Broadens market access for new indications like CIDP in the United States. |
| Manufacturing Scale-Up | Supports the shift to homecare and increased demand for SCIg formulations. |
| Strategic Partnership | Ensures stable plasma sourcing amidst global supply chain volatility. |
| Pipeline Diversification | Reduces reliance on human plasma through recombinant immunoglobulin technologies. |
Research Approach
Desk research of regulatory filings, medical journals, industry reports, and company disclosures preceded structured interviews with plasma fractionators, specialty pharmacy executives, hospital administrators, and patient advocacy group leaders. This approach combined primary insights with secondary validation, utilizing both bottom-up and top-down triangulation methods for comprehensive data synthesis.
Assumed stable regulatory environments and consistent healthcare spending across the analysis window. The analytical framework integrated market drivers, restraints, and opportunities. Segmentation dimensions modeled included product type, therapy area, end user, distribution channel, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected future demand, considering inputs like plasma collection volumes and new neurological disorder diagnoses.
Stress conditions across plasma supply disruptions and major policy changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Unforeseen public health crises or significant shifts in reimbursement policies represent key risk factors that could revise the forecast. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Short-Acting Beta-Agonists Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market