
 Intensive Care Beds Market | 2026-2036
Intensive Care Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Intensive Care Beds Market Intelligence
Post-pandemic consolidation among European component suppliers is recalibrating the supply chain for specialized bed actuators and control systems. This environment benefits large-scale manufacturers like Stryker Corporation, which leverages its global procurement network for production stability. Linet Group SE differentiates through a focus on innovative features like lateral tilt and integrated scales. Getinge AB sustains its position via strong relationships with large hospital networks.
Intensive care beds are specialized medical devices engineered to support critically ill patients in acute care settings. They feature multi-hinge electric adjustment capabilities and surfaces designed for pressure ulcer prevention. The electric adjustment feature segment dominates due to its necessity for patient repositioning and caregiver ergonomics. While standard ICU beds form the market's core, demand for bariatric ICU beds is expanding rapidly to address rising obesity rates.
Product design and market access are governed by stringent medical device regulations, including the FDA's 510(k) clearance process in the United States and the EU's Medical Device Regulation (MDR). These frameworks mandate rigorous testing for electrical safety, biocompatibility, and mechanical durability under standards like IEC 60601. Consequently, manufacturers must prioritize investment in regulatory compliance and quality management systems to compete effectively in major developed markets.
Market Dynamics
The convergence of advanced patient monitoring with medical device hardware defines the central dynamic in the intensive care beds market. This integration is pressuring manufacturers to innovate beyond mechanical functionality, embedding digital capabilities while navigating a supply chain marked by post-pandemic consolidation.
Growth Catalysts
- Public Health Investment:Government-led initiatives to expand and modernize hospital infrastructure, particularly in countries like India and Brazil, are creating substantial demand for new critical care equipment.
- Smart Bed Integration:The incorporation of features like integrated scales, patient turn-assist, and connectivity with Electronic Health Record (EHR) systems enhances patient safety and workflow efficiency, justifying premium pricing.
- Bariatric Care Expansion:Rising global obesity rates are expanding the need for specialized bariatric ICU beds designed to safely manage and reposition heavier patients, creating a distinct and growing product segment.
Market Restraints
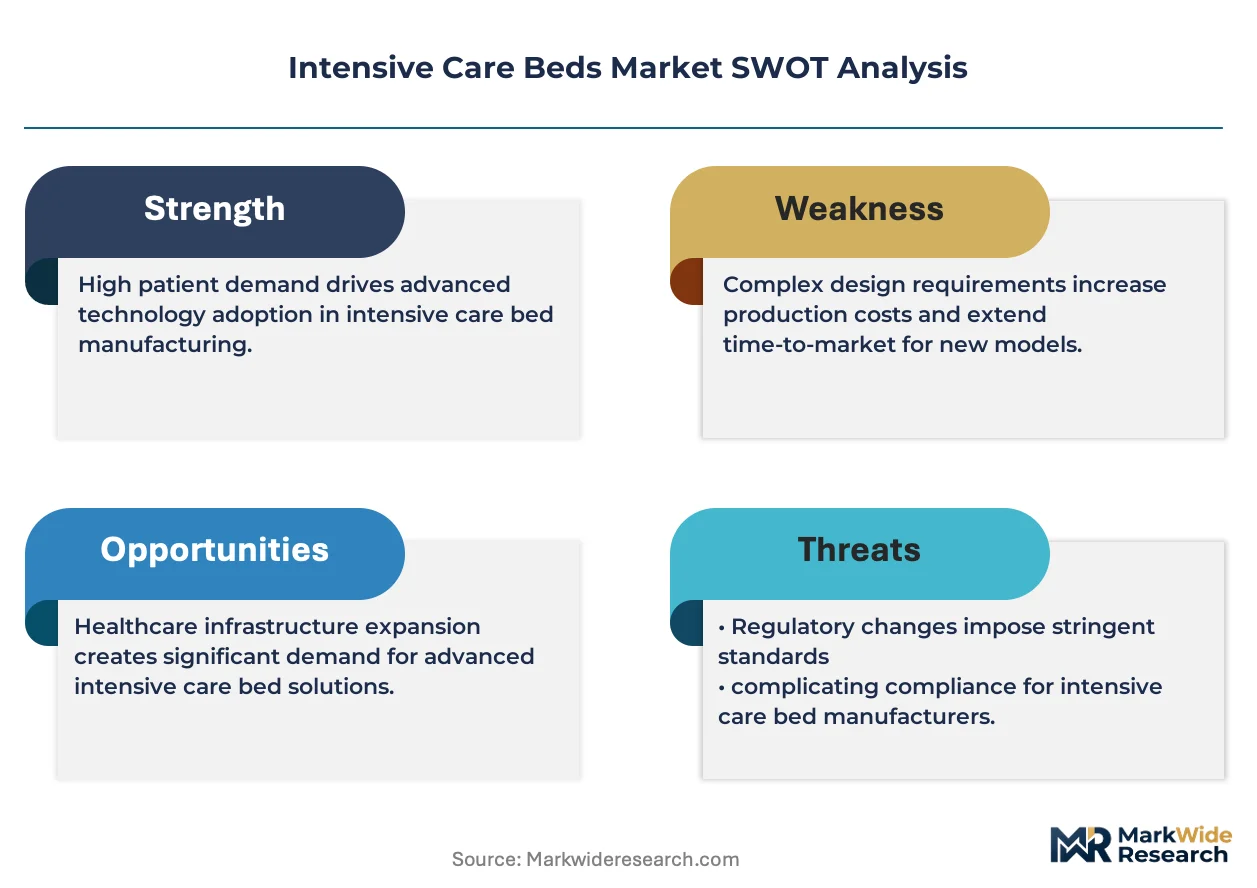
- High Capital Outlay:The significant acquisition cost of advanced ICU beds, coupled with ongoing maintenance expenses for their electronic components, presents a major budget constraint for healthcare facilities, especially in resource-limited settings.
- Stringent Regulatory Hurdles:Navigating complex and lengthy approval pathways, such as the FDA 510(k) clearance process and the EU's Medical Device Regulation (MDR), delays product launches and increases development costs.
- Component Supply Concentration:A dependency on a limited number of European manufacturers for critical components like specialized actuators and control systems creates vulnerability to supply chain disruptions and price volatility.
Strategic Opportunities
- Emerging Market Penetration:Significant white space exists in Latin American and Southeast Asian healthcare markets, where expanding private hospital chains represent a key customer base for modern ICU bed systems.
- Modular and Adaptable Designs:Developing beds with modular features that allow hospitals to scale capabilities up or down based on patient acuity offers a flexible solution that can serve both ICU and step-down units.
- Telehealth Integration:Embedding remote monitoring and telehealth functionalities directly into the bed platform can transform it into a connected care hub, supporting remote consultations and continuous patient oversight.
Industry Challenges
- Legacy System Interoperability:Ensuring seamless integration and data exchange between new smart beds and a hospital's existing, often outdated, IT infrastructure and EMR systems is a significant technical hurdle.
- Specialized Technician Scarcity:A shortage of biomedical engineers and technicians with the requisite software and electronics expertise to service and maintain complex, software-driven ICU beds challenges hospital operations.
- Compliance with Evolving Standards:Manufacturers face the ongoing challenge of updating product designs and quality systems to adhere to changing electrical safety and performance standards, including the IEC 60601 series.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intensive Care Beds Market |
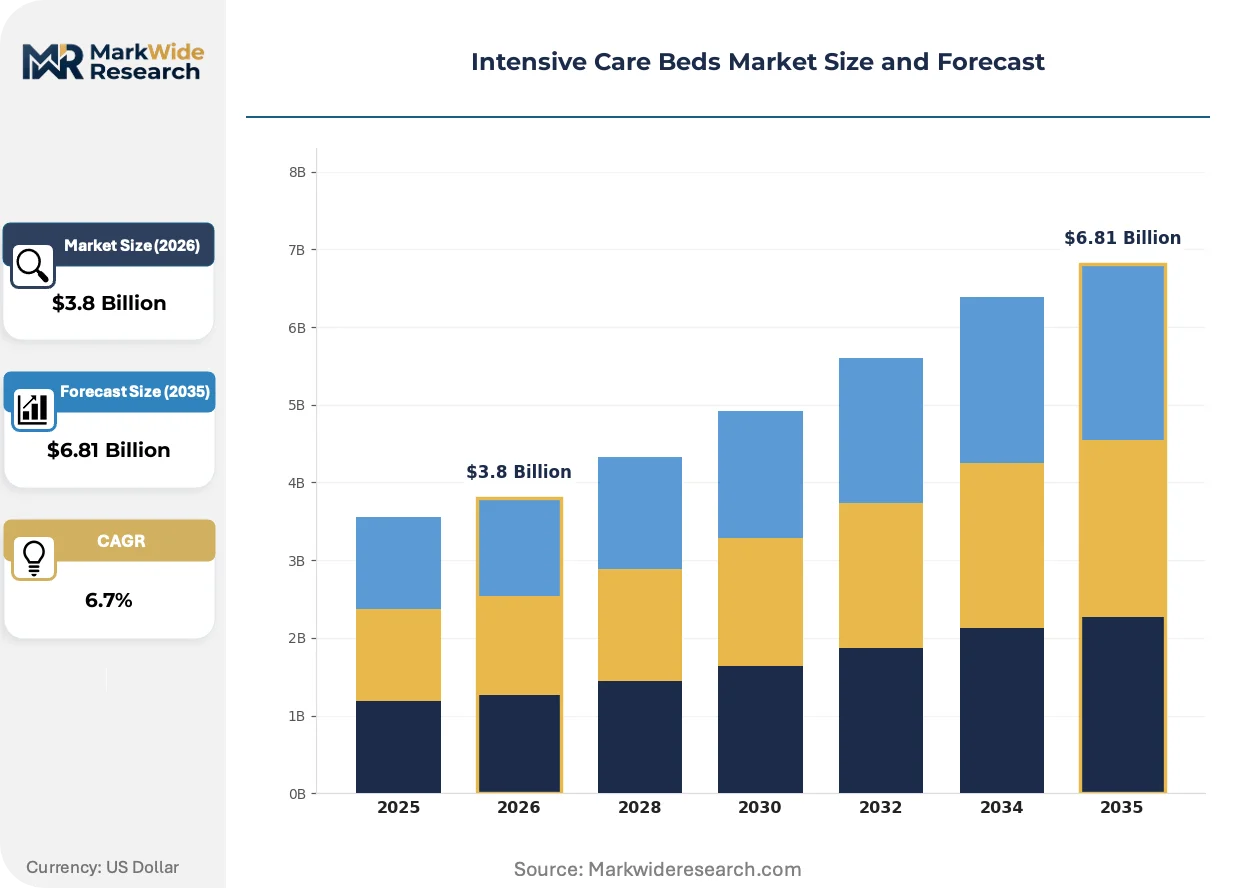
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard ICU Beds, Bariatric ICU Beds, Pediatric ICU Beds, Neuro ICU Beds, Trauma ICU Beds Feature: Electric Adjustment, Manual Adjustment, Radiolucent Mattress, Pressure Relief Surface, Cardiac Chair Function Application: Critical Care, Post-Operative Recovery, Respiratory Support, Neurological Monitoring, Trauma Support End User: Specialty Clinics, Rehabilitation Centers, Emergency Care Units, Surgical Centers |
| Companies Covered | Getinge AB, Baxter (Hill-Rom), Stryker Corporation, Invacare Corporation, Linet Group SE, Malvestio S.P.A., Medline Industries, Merivaara Corp., Stiegelmeyer GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intensive Care Beds Market Strategic Shifts & Innovations
The evolution of the ICU bed into a connected data-centric platform is the defining theme. This transformation is a direct response to clinical demands for improved patient outcomes, reduced caregiver strain, and greater operational efficiency within high-acuity environments.
Integrated IoT sensors and embedded software are becoming standard in premium ICU beds, enabling continuous tracking of patient movement and vital signs. Large hospital networks are adopting these systems to improve patient safety protocols. This integration of diverse data streams from the bed itself **is unifying** patient status, turn schedules, and pressure injury risk into a single clinical dashboard, enabling proactive care.
The European Union's Medical Device Regulation (MDR) is setting a higher bar for product certification. This framework mandates more rigorous clinical evidence and post-market surveillance for all medical devices, including their software components. Manufacturers of smart beds with integrated monitoring software are most affected, as they must now invest more heavily in clinical validation and risk management to secure and maintain CE marking for market access in Europe.
A notable behavioral change involves a move away from outright capital purchases toward long-term leasing and managed equipment service contracts. This shift disrupts the traditional direct-sales model, elevating the role of third-party medical asset management firms. The trend is most prominent in developed healthcare systems like those in the United States and Germany, as hospitals seek to manage technology obsolescence and shift capital costs to predictable operational expenses.
Intensive Care Beds Market Segmentation
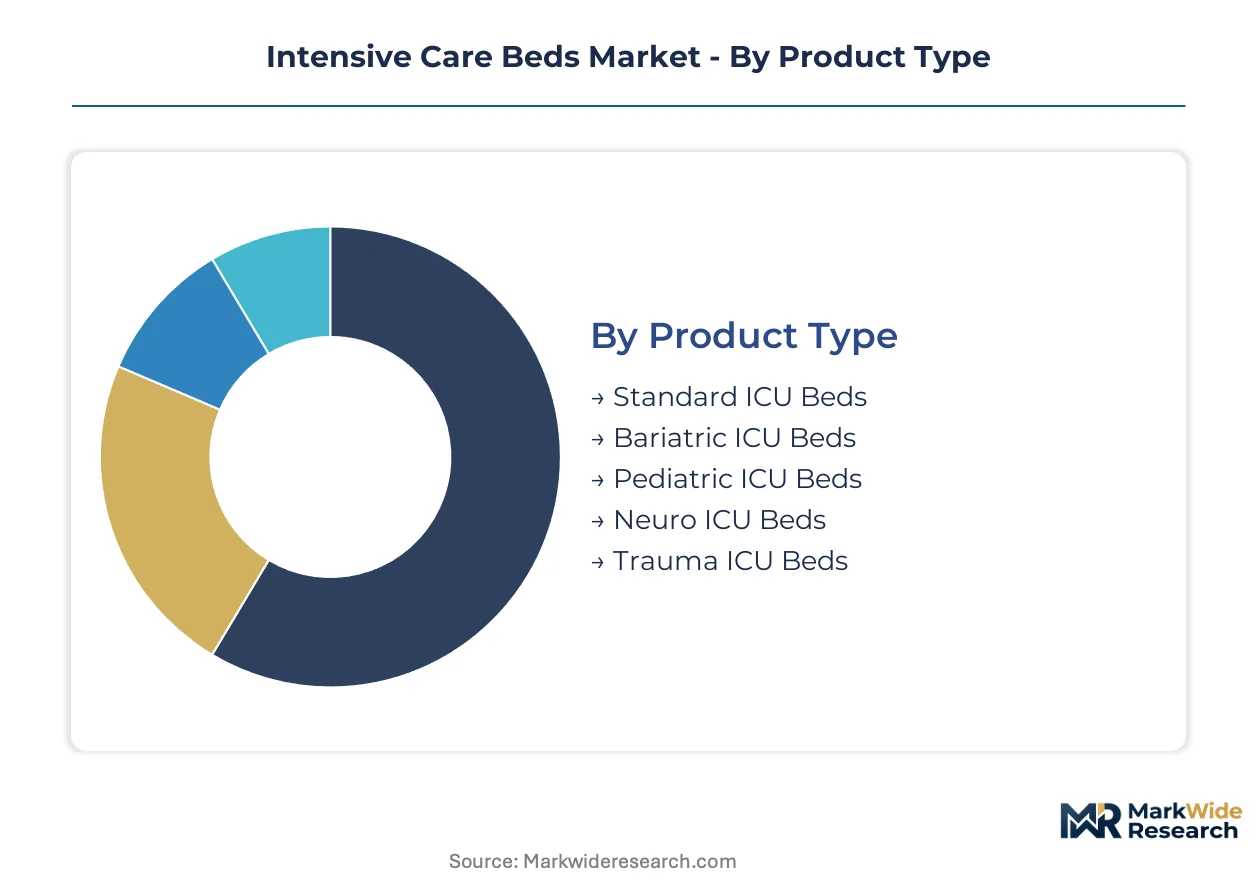
The intensive care beds market is segmented to reflect the diverse clinical requirements and operational priorities across various healthcare settings. Understanding these distinct segments helps manufacturers tailor product development and market strategies to specific patient populations and facility needs, ensuring optimal resource allocation.
Product Type:
Buyers in this category differentiate their procurement decisions based on the specific patient demographics and medical conditions served by their critical care units.
- Standard ICU Beds:These versatile beds provide essential support for a broad range of critically ill patients, featuring multi-hinge electric adjustments and pressure-redistributing surfaces. They form the foundational equipment in most intensive care units globally.
- Bariatric ICU Beds:Engineered with reinforced frames and wider dimensions, these specialized beds safely accommodate patients weighing over 400 pounds, often integrating advanced repositioning and mobility features. Rising obesity rates in countries like the United States are expanding demand for these robust units.
- Pediatric ICU Beds:Designed for younger patients, these beds feature smaller dimensions and specialized safety rails to ensure secure and comfortable care for children in critical condition.
- Neuro ICU Beds:These beds are optimized with specific features for neurological monitoring and patient positioning to support recovery from brain and spinal cord injuries.
- Trauma ICU Beds:Built for durability and rapid patient access, these beds facilitate quick interventions and provide stable support for patients with severe injuries.
Volume sits with Standard ICU Beds; growth tilts toward Bariatric ICU Beds, which represents the fastest-growing trajectory.
Feature:
The operational efficiency and caregiver ergonomics within critical care environments are significantly influenced by the advanced features integrated into intensive care beds.
- Electric Adjustment:This feature enables effortless repositioning of the patient and bed frame via electronic controls, crucial for caregiver safety and patient comfort. Its necessity for patient repositioning and caregiver ergonomics drives its dominance.
- Pressure Relief Surface:These specialized mattresses are designed to distribute pressure evenly across the patient's body, significantly reducing the risk of pressure ulcers and improving patient outcomes. This technology is a standard requirement in high-acuity settings.
- Manual Adjustment:Basic beds offering height and position changes through hand cranks or levers are typically found in lower-acuity settings or as backup units due to their lower cost.
- Radiolucent Mattress:These mattresses allow for X-ray imaging directly through the bed surface without moving the patient, streamlining diagnostic procedures in critical situations.
- Cardiac Chair Function:This feature allows the bed to articulate into a chair-like position, facilitating patient mobilization and supporting respiratory function.
Electric Adjustment remains a fundamental requirement, while Pressure Relief Surface technology sees consistent innovation and demand across all market segments.
Application:
Different clinical needs within a hospital dictate the specific types of intensive care beds required, reflecting the diverse care pathways patients undergo.
- Critical Care:This core application covers the most acutely ill patients requiring continuous monitoring and life support, driving demand for beds with integrated patient monitoring systems. These units are deployed in general intensive care and high-dependency units.
- Post-Operative Recovery:Beds used in this application support patients immediately following surgery, focusing on pain management, wound care, and early mobilization. Specialty clinics globally prioritize these beds for enhanced patient comfort.
- Respiratory Support:Beds designed for respiratory support often feature specialized positioning capabilities to optimize lung function and facilitate ventilator weaning for patients with pulmonary conditions.
- Neurological Monitoring:This application demands beds that can facilitate frequent neurological assessments and accommodate specialized monitoring equipment without disturbing the patient.
- Trauma Support:Beds configured for trauma patients are built to withstand frequent patient transfers and offer robust support for complex injury management.
Demand for Critical Care beds forms the market's foundation, with Post-Operative Recovery applications demonstrating expanding utilization in specialized facilities.
End User:
The institutional characteristics and service offerings of healthcare providers directly influence their procurement of intensive care beds, shaping market distribution.
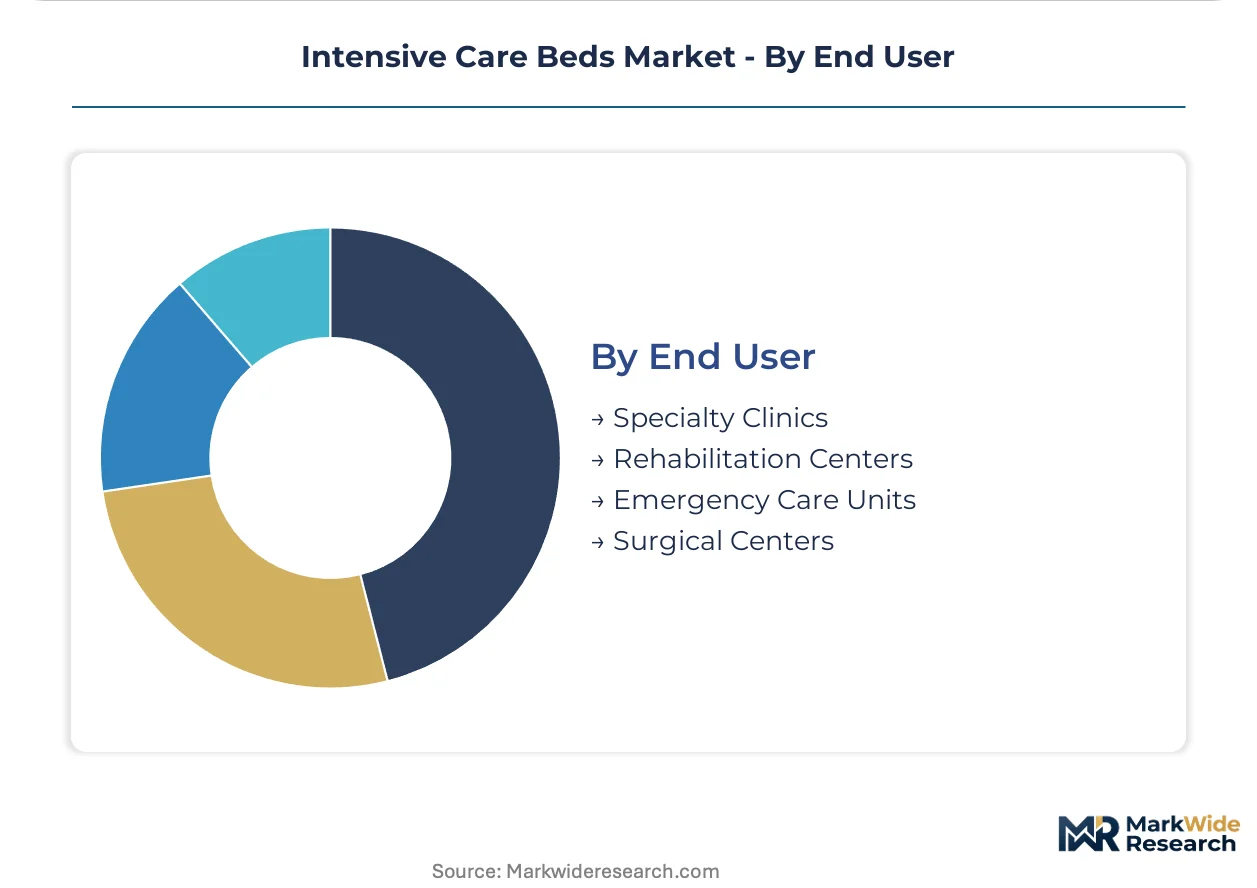
- Specialty Clinics:These facilities, often focusing on specific medical areas like cardiology or orthopedics, invest in beds tailored for post-operative recovery and specialized patient needs. Their expansion in countries like Brazil contributes significantly to overall market growth.
- Emergency Care Units:Requiring rapid setup and robust functionality, these units procure beds that can handle high patient turnover and urgent medical interventions. The beds must be durable and easily maneuverable.
- Rehabilitation Centers:These centers utilize beds designed to support patient mobility and therapeutic interventions, aiding in the recovery process after acute illness or injury.
- Surgical Centers:Beds in surgical centers are typically used for pre-operative preparation and immediate post-operative observation, prioritizing patient comfort and accessibility for medical staff.
Large hospital networks remain the primary purchasers, yet specialty clinics and emergency care units are increasingly expanding their intensive care bed inventories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global intensive care beds market sees significant demand concentrated in regions with robust healthcare infrastructure and expanding medical tourism. Public health investment initiatives in developing economies are also creating substantial procurement opportunities for advanced critical care equipment. This market expansion is particularly evident in countries modernizing their hospital networks.
United States
Demand for advanced ICU beds in the United States stems from technological integration and high healthcare spending. The FDA's 510(k) clearance process mandates rigorous testing for all medical devices, including smart beds. Major medical device manufacturing hubs in states like California and Massachusetts drive innovation in patient monitoring systems.
Germany
Germany's market for intensive care beds benefits from an aging population and strong emphasis on patient safety standards. The EU's Medical Device Regulation (MDR) sets stringent requirements for product certification and post-market surveillance. North Rhine-Westphalia, a key industrial region, hosts numerous specialized medical equipment manufacturers.
India
Large-scale public and private hospital infrastructure development in India fuels substantial demand for critical care equipment. Government initiatives like the Ayushman Bharat scheme expand access to healthcare services, increasing bed capacity. Cities such as Chennai and Hyderabad are emerging as medical tourism hubs, requiring modern ICU facilities.
Brazil
Brazil's intensive care bed market expands due to rising chronic disease prevalence and expanding private hospital chains. ANVISA, the national health surveillance agency, regulates medical device market access and quality. São Paulo, a major economic center, leads in healthcare investment and advanced medical technology adoption.
Japan
Japan experiences consistent demand for high-quality ICU beds driven by its rapidly aging demographic and advanced healthcare system. The PMDA oversees strict regulatory approvals for medical devices, ensuring product reliability. Tokyo's medical technology cluster focuses on integrating robotics and AI into patient care solutions.
Intensive Care Beds Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated digital health solutions and specialized bariatric care. The intensive care beds market exhibits a tiered structure, with a few large manufacturers holding significant share alongside numerous niche players. Companies often differentiate through technological innovation in patient monitoring and pressure relief surfaces. Dominant competitive moves include strategic partnerships for technology integration and geographic expansion into high-growth emerging markets.
Specialists in advanced patient monitoring and integrated features include Getinge AB, which sustains its position via strong relationships with large hospital networks, emphasizing digital connectivity. Stryker Corporation exemplifies a large-scale manufacturer leveraging its global procurement network for production stability and broad market reach across diverse product types. Linet Group SE occupies a position focused on innovative features like lateral tilt and integrated scales, catering to premium segment demands for enhanced patient comfort and caregiver ergonomics. These companies collectively anchor the market's innovation and quality benchmarks, driving advancements in critical care technology.
| Leading Market Players |
|---|
| Getinge AB |
| Baxter (Hill-Rom) |
| Stryker Corporation |
| Invacare Corporation |
| Linet Group SE |
| Malvestio S.P.A. |
| Medline Industries |
| Merivaara Corp. |
| Stiegelmeyer GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Specialized biomedical engineering talent concentration in developed markets like Germany influences the cost structure for advanced ICU beds, impacting price differentiation across technology tiers. This labor cost factor directly affects manufacturing expenses and subsequent market pricing.
Pricing Analysis
Warranty and long-term service contracts often bundle with premium ICU bed purchases, influencing the total cost of ownership for hospitals. Pricing stratifies across premium, standard, and economy tiers, driven by integrated technology features like advanced patient monitoring and EU MDR certification levels. Pricing softness runs through standard ICU beds due to increased competition from regional manufacturers. Resource-limited healthcare facilities exhibit the highest price sensitivity, prioritizing basic functionality over advanced digital integration.
Supply Chain Analysis
Rising global freight costs for specialized components impact the final price of intensive care beds, particularly for manufacturers sourcing from distant regions. The supply chain for critical components like specialized actuators and control systems centers on European manufacturers, including those in Germany. This dependency on a limited number of suppliers creates single-source vulnerability. Distribution typically runs through direct sales channels to large hospital networks, complemented by third-party medical asset management firms for leasing models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intensive care beds market is undergoing a technology-transition phase, as integrated smart bed systems displace traditional mechanical beds. This shift demands strategic adaptation from all market participants.
For Market Incumbents:To counter component supply chain vulnerabilities, large-scale manufacturers should deepen in-house production for critical actuators and control systems. This strategy ensures production stability and mitigates price volatility. Incumbents must also invest significantly in software development to embed advanced patient monitoring and AI-driven insights directly into bed platforms, maintaining technological leadership against digital-first entrants. Prioritizing EU MDR and FDA 510(k) compliance for these integrated systems secures market access.
For New Entrants and Emerging Players:Launch specialized bariatric ICU beds via direct sales to expanding private hospital chains in Latin America. Significant white space exists in these emerging markets, particularly for modular and adaptable designs that cater to varying patient acuity levels. New entrants can gain traction by offering flexible leasing and managed service contracts, appealing to facilities with high capital outlay constraints. Integrating telehealth functionalities directly into the bed platform provides a distinct value proposition.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized software providers for smart bed integration given the increasing demand for connected care hubs. Long-term viability for the intensive care beds market is strong, driven by aging populations and global hospital infrastructure modernization. Acquisition targets include niche manufacturers focusing on bariatric solutions or those with proven intellectual property in AI-driven patient monitoring. A key signal to watch is the accelerated adoption of managed equipment service contracts by large hospital networks, indicating a shift in procurement patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | This pathway is essential for market access in the United States, validating product safety and efficacy for medical devices. |
| Hospital System Partnership | Securing these partnerships provides long-term procurement contracts and critical clinical feedback for product refinement. |
| Software Companion Development | Developing software enhances bed functionality with integrated patient monitoring and advanced data analytics capabilities. |
| Bariatric Product Line Expansion | Expanding this product line addresses the growing demand for specialized beds catering to an increasing obese patient population. |
| Managed Equipment Service Offering | This offering shifts capital expenditure to operational expenditure for hospitals, providing flexible procurement options. |
Research Approach
Document review covered FDA filings, EU MDR documentation, and hospital procurement databases, complemented by interviews with industry stakeholders. This primary research included clinicians, biomedical engineers, and GPO contracts managers. Secondary data was rigorously validated through these expert insights. The analysis employed both bottom-up and top-down triangulation to ensure comprehensive market sizing and forecasting.
The quantitative model produced detailed volume and value projections across the analysis window. Segmentation dimensions included product type, feature, application, end user, and regional healthcare spending. Compound Annual Growth Rates were derived from historical data, current market dynamics, and expert consensus. Key inputs included global hospital bed capacity expansion plans and evolving bariatric patient demographics.
Evolving medical device regulations, supply chain disruptions, and public health investment fluctuations are the dominant revision risks for market forecasts. These projections reflect assumptions at the time of publication. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Global Medical Furniture Market
Medical Furniture
Asia-Pacific Hospital Bed Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Medical Walker Market
Medical Furniture
Clinical Chairs Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Infusion Chair Market
Medical Furniture
Medical Bed Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Global Automated Hospital Beds Market