
 Antispasmodics Drugs Market | 2026-2036
Antispasmodics Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antispasmodics Drugs Market Insights
Prescription-grade anticholinergic formulations is bifurcating the antispasmodics landscape into originator and high-barrier generic tiers. Sanofi leverages its European hospital network to sustain formulary dominance for established muscarinic antagonists. Teva Pharmaceuticals anchors the North American generic segment through vertically integrated API-to-tablet manufacturing for dicyclomine and hyoscyamine variants.
Antispasmodics drugs are pharmacological agents that suppress involuntary smooth muscle contractions through muscarinic receptor antagonism, calcium channel modulation, or direct myotropic action, typically formulated as oral tablets containing 10–20 mg active compound or sustained-release capsules for twelve-hour coverage. Their primary purpose is to relieve cramping in gastrointestinal, biliary, and urogenital tracts without disrupting normal peristaltic function. The gastrointestinal disorders therapy area leads volume consumption due to high irritable bowel syndrome prevalence, while combination therapy products capture expanding margin pools by pairing anticholinergics with proton pump inhibitors or prokinetics in single-dose regimens. Injectable delivery modes serve acute colic and surgical recovery settings where rapid onset overrides oral bioavailability concerns.
The FDA's bioequivalence standards for abbreviated new drug applications shape generic antispasmodics entry economics, while the EMA's pharmacovigilance requirements for anticholinergic burden metrics influence prescriber behavior across EU member states. India's CDSCO enforces dissolution profile conformity for export-bound dicyclomine formulations, filtering substandard manufacturers from international supply chains. Stakeholders must monitor evolving anticholinergic risk labeling in major jurisdictions, as regulatory shifts toward cognitive safety warnings will redirect R&D investment toward peripherally selective muscarinic antagonists with reduced blood-brain barrier penetration.
Market Dynamics
Antispasmodics development is splitting between peripherally selective muscarinic antagonists with reduced blood-brain barrier penetration and legacy anticholinergic formulations facing cognitive safety scrutiny. The FDA's evolving anticholinergic risk labeling is compressing R&D investment timelines while redirecting formulation priorities toward safer molecular profiles.
Growth Catalysts
- Streamlined ANDA Pathway:The FDA's abbreviated new drug application review process for generic anticholinergics is accelerating competitive entry timelines and expanding patient access to lower-cost alternatives.
- Outpatient Clinic Expansion:Germany's gastroenterology clinics are embedding direct-acting spasmolytics into first-line irritable bowel syndrome protocols, driving volume concentration in reimbursed prescription channels.
- Combination Formulation Innovation:Fixed-dose regimens pairing anticholinergics with proton pump inhibitors are capturing expanded margin pools through simplified dosing adherence.
Market Restraints
- API Supply Concentration:Dicyclomine and hyoscyamine active pharmaceutical ingredient production clusters in Indian export zones, creating single-point vulnerability for international formulation manufacturers.
- Cognitive Safety Labeling:EMA pharmacovigilance requirements for anticholinergic burden metrics are constraining prescriber willingness to initiate therapy in elderly populations.
- Dissolution Profile Conformity:India's CDSCO export standards for dicyclomine formulations are filtering substandard manufacturers from supply chains, reducing viable supplier bases.
Strategic Opportunities
- Injectable Acute Care Expansion:Surgical recovery and acute colic settings represent underpenetrated demand for rapid-onset delivery modes where oral bioavailability constraints limit competition.
- Peripherally Selective R&D:Blood-brain barrier exclusion technology is opening white space for muscarinic antagonists with reduced central nervous system penetration.
- Hospital Formulary Integration:North American and European hospital pharmacy networks are expanding irritable bowel syndrome patient access, creating channel consolidation opportunities.
Industry Challenges
- Formulation Scientist Scarcity:Specialized expertise in sustained-release capsule engineering for twelve-hour coverage is concentrating among legacy manufacturers, constraining new entrant capability building.
- Bioequivalence Study Complexity:FDA abbreviated new drug application requirements for anticholinergic pharmacokinetic matching are extending generic development timelines and capital requirements.
- Legacy System Integration:Established hospital pharmacy inventory management systems require extensive reconfiguration to accommodate combination therapy product coding and reimbursement pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antispasmodics Drugs Market |
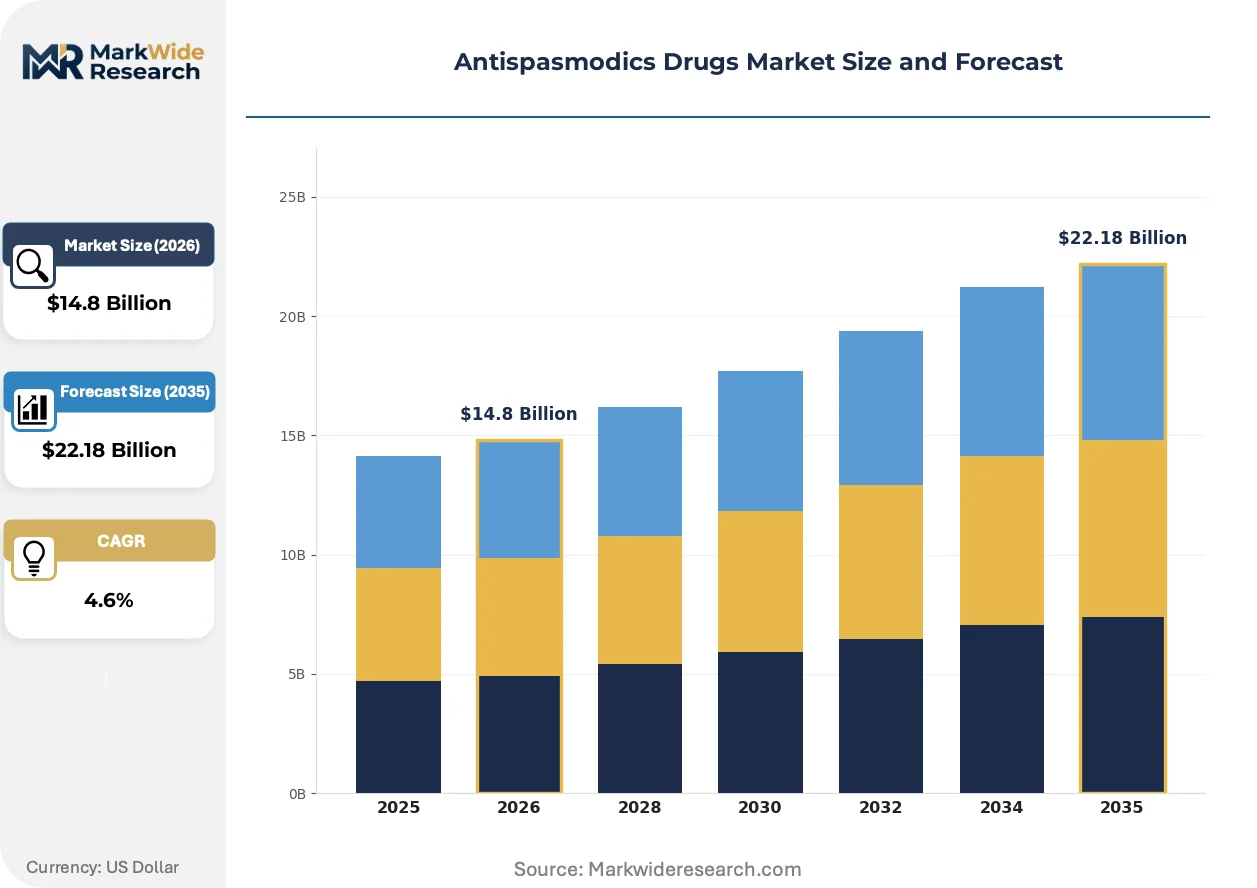
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticholinergic, Muscle Relaxants, Direct-acting Agents, Combination Therapy Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Gastrointestinal Disorders, Urological Disorders, Neurological Disorders, Others |
| Companies Covered | Sanofi, Teva Pharmaceuticals, Sun Pharmaceuticals, Aurobindo Pharma, Johnson & Johnson, Pfizer, Hikma Pharmaceuticals, Novartis, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antispasmodics Drugs Market Trends and Innovations
Formulation science is diverging toward targeted receptor selectivity while regulatory pressure on cognitive safety accelerates molecular redesign. These forces are compressing traditional development cycles and reshaping competitive positioning around clinical differentiation rather than me-too replication.
Peripherally selective muscarinic antagonists with engineered blood-brain barrier exclusion are advancing through late-stage pipelines. Gastroenterology specialists in German and US academic medical centers are prioritizing these candidates for elderly irritable bowel syndrome populations. This technology is bifurcating the antispasmodics landscape into originator and high-barrier generic tiers based on cognitive safety profiles.
The FDA's anticholinergic risk labeling evolution is mandating enhanced cognitive safety warnings for established muscarinic antagonists. This regulatory pressure is compressing commercial viability timelines for legacy formulations and redirecting prescriber behavior toward newer alternatives. Hospital pharmacy and therapeutics committees across the United States are revising formulary placement criteria to incorporate these emerging safety metrics.
Hospital procurement committees are unbundling after-sales clinical support from product pricing negotiations. Large integrated delivery networks in North America are replacing traditional volume-based purchasing with outcome-linked contracts that tie reimbursement to patient-reported cramping relief metrics. This behavioral shift is most visible in US health systems participating in CMS alternative payment models for gastrointestinal disorders.
Antispasmodics Drugs Market Segmentation
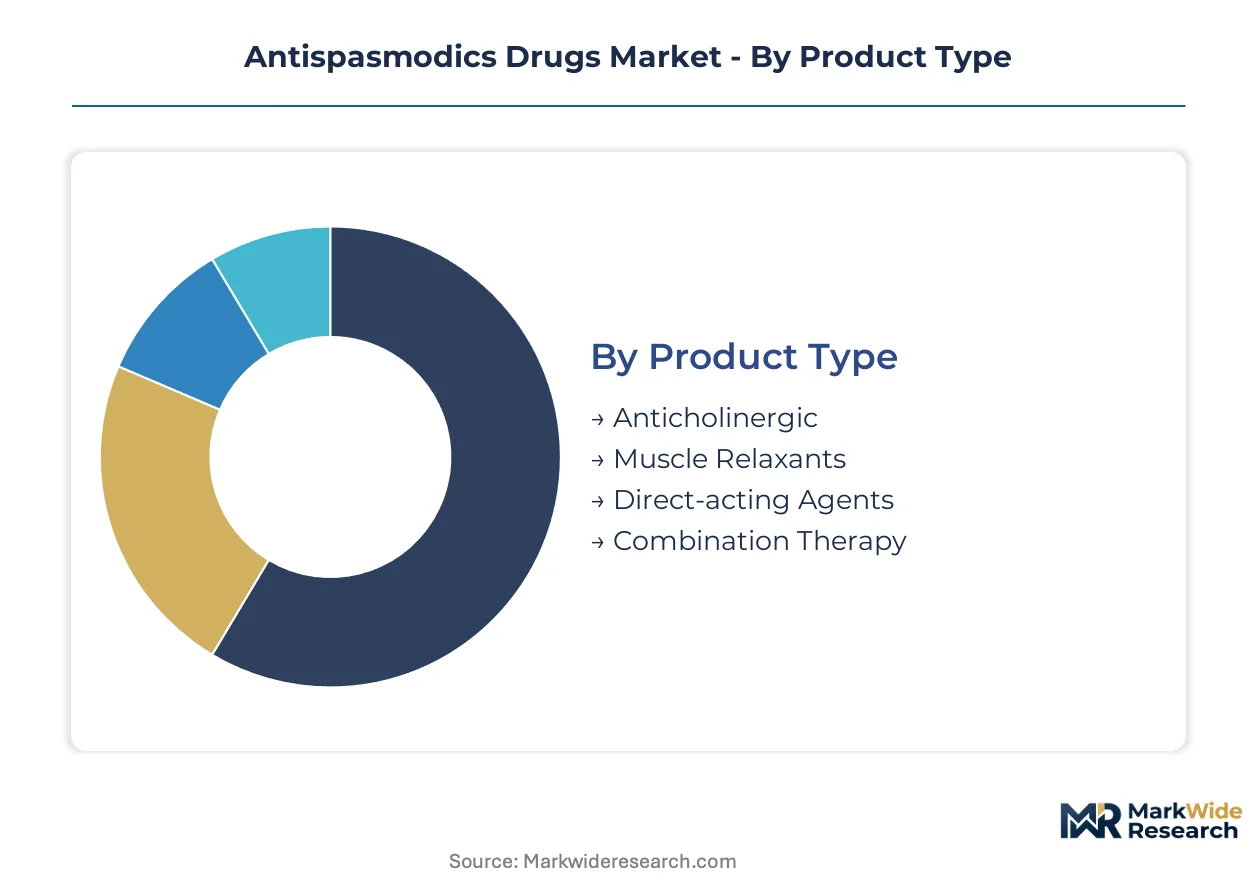
Antispasmodics drugs flow through distinct channel configurations depending on molecular class and urgency of administration. Each product type, delivery mode, and end-user setting imposes unique formulation requirements and reimbursement pathways that shape commercial strategy.
Product Type:
Hospital pharmacies in Germany and the United States channel anticholinergic volumes through formulary tiers, while outpatient clinics favor direct-acting agents for rapid symptom relief without cognitive burden.
- Anticholinergic:Muscarinic receptor antagonists such as dicyclomine and hyoscyamine block acetylcholine binding to M3 receptors in smooth muscle. Demand concentrates in North American hospital systems where irritable bowel syndrome protocols prioritize established efficacy profiles despite emerging cognitive safety warnings from the FDA.
- Direct-acting Agents:Spasmolytics like mebeverine and pinaverium modulate calcium channels directly without anticholinergic activity. Germany's outpatient gastroenterology clinics embed these into first-line therapy protocols for elderly populations where blood-brain barrier penetration concerns limit anticholinergic prescribing.
- Muscle Relaxants:Benzodiazepine derivatives and related compounds target central pathways to reduce spasticity.
- Combination Therapy:Fixed-dose pairings of anticholinergics with proton pump inhibitors or prokinetics simplify adherence.
Anticholinergic formulations dominate installed base through legacy hospital contracts. Direct-acting agents are where expansion concentrates as prescribers seek peripherally selective alternatives.
Delivery Mode:
Cost tiers separate acute intervention from chronic maintenance, with injectable formats commanding premium pricing in surgical recovery settings and oral tablets serving routine outpatient management.
- Oral:Tablets containing 10–20 mg active compound and sustained-release capsules for twelve-hour coverage constitute the volume base. India's CDSCO enforces dissolution profile conformity for export-bound formulations, filtering substandard manufacturers from international supply chains serving European and North American markets.
- Injectable:Intravenous and intramuscular formulations deliver rapid onset for acute colic and postoperative ileus. Surgical recovery units in US academic medical centers prioritize this delivery mode where oral bioavailability constraints limit therapeutic alternatives.
- Transdermal:Patch-based delivery bypasses first-pass metabolism for continuous plasma levels.
- Inhalation:Nebulized formulations target bronchospasm with antispasmodic crossover applications.
Oral delivery anchors volume economics through manufacturing scale. Injectable formats are climbing the fastest as acute care protocols expand.
End User:
Customer type determines procurement sophistication, with integrated delivery networks negotiating outcome-linked contracts and retail pharmacies processing reimbursed prescriptions for chronic conditions.
- Hospitals:Inpatient pharmacy and therapeutics committees manage formulary placement for acute and surgical applications. Large US health systems participating in CMS alternative payment models for gastrointestinal disorders are replacing volume-based purchasing with patient-reported cramping relief metrics.
- Clinics:Outpatient gastroenterology practices in Germany drive prescription concentration for direct-acting spasmolytics through reimbursed first-line protocols.
- Home Care:Self-administered oral regimens for chronic irritable bowel syndrome management.
- Pharmacies:Retail and hospital outpatient dispensaries handle reimbursed prescription fulfillment.
Hospitals dominate formulary control. Clinics are gaining share fastest as site-of-care shifts toward ambulatory settings.
Therapy Area:
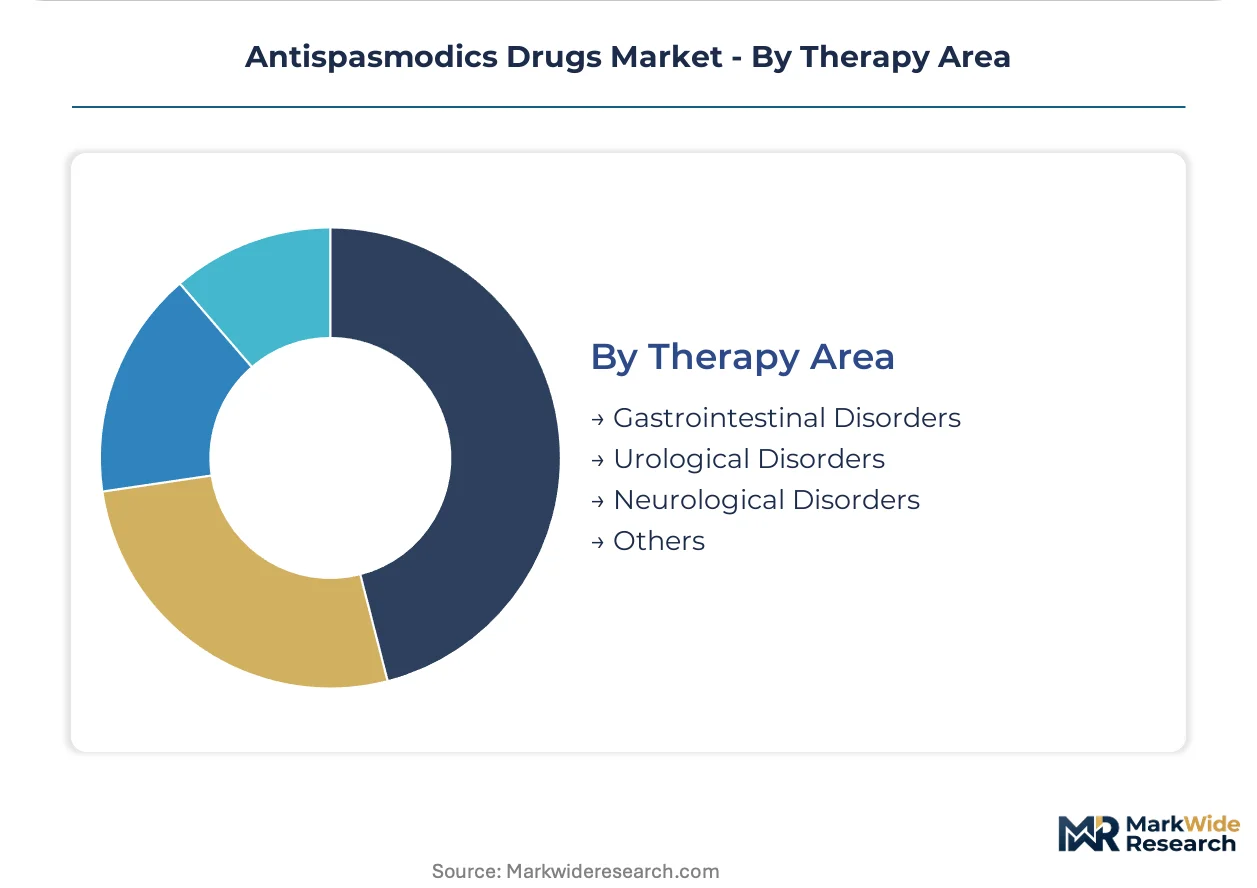
Application maturity varies by disorder prevalence and treatment algorithm evolution, with gastrointestinal conditions offering established pathways and neurological indications requiring specialized prescriber engagement.
- Gastrointestinal Disorders:Irritable bowel syndrome, functional dyspepsia, and biliary colic generate the highest prescription volumes. The EMA's pharmacovigilance requirements for anticholinergic burden metrics are constraining prescriber willingness to initiate therapy in elderly European populations with these conditions.
- Urological Disorders:Overactive bladder and interstitial cystitis applications leverage smooth muscle relaxation in detrusor muscle. US urology practices are expanding off-label utilization of peripherally selective muscarinic antagonists originally developed for gastrointestinal indications.
- Neurological Disorders:Spasticity management in multiple sclerosis and cerebral palsy.
- Others:Gynecological and ophthalmological applications with limited approved indications.
Gastrointestinal disorders anchor the installed base. Urological applications represent the steepest expansion trajectory as bladder-targeted formulations advance through development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for dicyclomine and hyoscyamine concentrates in Indian export zones, creating supply dependencies that shape formulation economics across destination markets. Hospital pharmacy procurement in Germany and the United States drives demand concentration, while regulatory divergence between FDA and EMA pathways fragments competitive entry timelines.
United States
Hospital pharmacy and therapeutics committees manage formulary placement for irritable bowel syndrome protocols, with CMS alternative payment models reshaping procurement toward patient-reported outcome metrics. FDA's streamlined ANDA review pathway accelerates generic anticholinergic entry. Academic medical centers in Boston and the Research Triangle prioritize peripherally selective muscarinic antagonists for elderly populations.
Germany
Outpatient gastroenterology clinics embed direct-acting spasmolytics into first-line therapy protocols, driving prescription concentration in reimbursed channels. EMA pharmacovigilance requirements for anticholinergic burden metrics constrain prescriber willingness to initiate legacy formulations in elderly patients. Berlin and Munich hospital networks are expanding formulary access for irritable bowel syndrome management.
India
CDSCO enforces dissolution profile conformity for export-bound dicyclomine formulations, filtering substandard manufacturers from international supply chains. API production clusters in Hyderabad and Ahmedabad supply global formulation manufacturers. Domestic demand for antispasmodics concentrates in metropolitan hospital pharmacies managing functional gastrointestinal disorders.
Switzerland
Swissmedic's regulatory framework for anticholinergic cognitive safety warnings influences prescriber behavior across adjacent EU markets. Basel and Zurich hospital systems participate in cross-border formulary harmonization initiatives. Specialty pharmaceutical development for peripherally selective muscarinic antagonists concentrates in the Basel biotech cluster.
Japan
PMDA's evolving standards for anticholinergic risk labeling redirect R&D investment toward blood-brain barrier exclusion technologies. Tokyo and Osaka academic medical centers prioritize cognitive safety profiles in elderly irritable bowel syndrome populations. Domestic formulation manufacturers face API import dependency for hyoscyamine derivatives.
Antispasmodics Drugs Market Competitive Landscape
Concentration sits with vertically integrated pharmaceutical conglomerates controlling API-to-tablet manufacturing and legacy hospital formulary contracts. The market structure bifurcates between originator-tier players with established muscarinic antagonist portfolios and high-barrier generic specialists. Three archetypes dominate: European hospital network operators, North American generic manufacturers with captive API supply, and Indian export-oriented formulation houses. Competitive moves center on portfolio diversification into combination therapies and regulatory pathway optimization for peripherally selective candidates.
Among European-based originators, Sanofi sustains formulary dominance through hospital network relationships, while Novartis and AbbVie occupy positions in specialty gastrointestinal therapeutics. Teva Pharmaceuticals anchors the North American generic segment through integrated manufacturing capabilities for dicyclomine and hyoscyamine variants. Sun Pharmaceuticals and Aurobindo Pharma represent Indian formulation exporters navigating CDSCO conformity standards for international market access.
| Leading Market Players |
|---|
| Sanofi |
| Teva Pharmaceuticals |
| Sun Pharmaceuticals |
| Aurobindo Pharma |
| Johnson & Johnson |
| Pfizer |
| Hikma Pharmaceuticals |
| Novartis |
| AbbVie Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Indian API manufacturers and North American formulation houses lock in dicyclomine supply access while anchoring price visibility for generic anticholinergic production cycles. These arrangements buffer international buyers against spot market volatility in hyoscyamine precursor chemicals sourced from concentrated export zones.
Pricing Analysis
FDA bioequivalence standards dictate the pricing tier structure across generic antispasmodics, separating originator-grade formulations from high-barrier ANDA entrants. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales clinical support bundling. Cost compression in economy-tier oral tablets is intensifying because CDSCO conformity requirements filter substandard Indian suppliers. Hospital procurement committees exhibit lowest price sensitivity due to formulary lock-in, while retail pharmacies face highest pressure from reimbursed prescription margin constraints.
Supply Chain Analysis
Inventory buffers for dicyclomine API stretch to six-month coverage as Hyderabad and Ahmedabad production clusters face intermittent export clearance delays. Active pharmaceutical ingredient manufacturing concentrates in India, with formulation finishing spread across Germany and the United States. Supply chains draw from hyoscyamine botanical extracts, synthetic dicyclomine precursors, and specialized capsule shell polymers. Single-source vulnerability sits with Indian API zones subject to DGFT export licensing fluctuations. Distribution runs through hospital procurement consortiums and specialty pharmaceutical wholesalers serving outpatient gastroenterology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antispasmodics demand follows a cyclical recovery pattern as post-pandemic gastroenterology clinic visit rates normalize and delayed irritable bowel syndrome diagnoses convert to prescription volumes.
For Market Incumbents: Compound formulary dominance through peripherally selective muscarinic antagonist R&D pipelines that address FDA cognitive safety labeling pressures. Secure backward integration into hyoscyamine API production to offset Indian supply concentration risks. Expand clinical support bundling for hospital pharmacy and therapeutics committees evaluating outcome-linked contracts.
For New Entrants and Emerging Players: Differentiate on blood-brain barrier exclusion technology for elderly patient populations in German outpatient clinics where EMA pharmacovigilance constrains legacy anticholinergic prescribing. Target injectable acute care segments in US surgical recovery units as the most penetrable white space. Pursue 505(b)(2) regulatory pathways that leverage existing safety databases to compress development timelines.
For Investors and Strategic Acquirers: Indian export-oriented formulation houses with captive API relationships and established CDSCO compliance records represent priority acquisition archetypes. Long-term viability hinges on portfolio diversification into combination therapies and peripherally selective candidates with reduced central nervous system penetration. Monitor FDA anticholinergic risk labeling evolution as the critical inflection signal for legacy formulation valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Peripherally Selective R&D Investment | Blood-brain barrier exclusion technology redirects portfolios away from FDA cognitive safety scrutiny. |
| API Manufacturing Scale-Up | Captive dicyclomine production in Hyderabad clusters buffers against DGFT export licensing volatility. |
| Hospital Formulary Partnership | Academic medical center alliances in Boston secure placement for elderly-targeted muscarinic antagonists. |
| Combination Therapy Development | Fixed-dose pairings with proton pump inhibitors capture expanded margin pools through adherence simplification. |
| Injectable Format Expansion | Intravenous formulations penetrate US surgical recovery units where oral bioavailability constraints limit competition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA ANDA filings, EMA pharmacovigilance databases, and Indian CDSCO export registration records. Drug development executives, regulatory affairs leads, hospital formulary directors, and gastroenterology clinic administrators provided qualitative input across North America, Europe, and India. Bottom-up prescription volume modeling triangulates against top-down market sizing from customs data and pharmaceutical trade flows.
Segmentation dimensions modeled span product type, delivery mode, end-user setting, and therapy area across the analysis window. CAGRs derive from patient population epidemiology, treatment algorithm evolution, and reimbursement pathway expansion. Forecast inputs incorporate irritable bowel syndrome prevalence trajectories, anticholinergic burden metric adoption rates, and generic entry timelines under streamlined ANDA review.
Material uncertainties — regulatory labeling revisions, API supply disruptions, and prescriber behavior shifts toward peripherally selective alternatives — sit outside the modeled envelope. Forecasts reflect documented assumptions about formulary placement trajectories and cognitive safety warning implementations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Gemcitabine HCL Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market