
 Biomarker Discovery Outsourcing Services Market | 2026-2036
Biomarker Discovery Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Biomarker Discovery Outsourcing Services Market Analytics
The gap between premium biomarker platforms and commodity screening services is realigning competitive dynamics across the outsourcing landscape. Labcorp leverages its integrated diagnostic and drug development infrastructure to anchor high-complexity proteomics workflows for oncology sponsors. Eurofins Scientific differentiates through distributed laboratory capacity across multiple regulatory jurisdictions, while WuXi AppTec dominates chemistry-manufacturing-controls adjacent biomarker services for biotech clients seeking Asian-Pacific access.
Biomarker discovery outsourcing services encompass contract research activities that identify, validate, and characterize measurable biological indicators using genomic sequencing, mass spectrometry-based proteomics, and computational bioinformatics pipelines, typically requiring GLP-compliant laboratories and validated assay thresholds. These services enable pharmaceutical and biotech sponsors to de-risk clinical development by linking molecular signatures to patient stratification, efficacy endpoints, and safety monitoring. Clinical trial services command the largest revenue share among service types due to Phase II-III biomarker integration mandates, while bioinformatics represents the fastest-expanding technology segment as multi-omics datasets outpace in-house analytical capacity. Oncology applications absorb the greatest contract value, though autoimmune biomarker programs are gaining traction as precision medicine targets expand beyond solid tumors.
FDA biomarker qualification guidelines, EMA's ICH E16 harmonization standards, and China's NMPA clinical trial data integrity requirements collectively elevate compliance burdens for outsourced discovery programs. Sponsors now prioritize CRO partners with dual US-EU regulatory track records and established quality management systems. Stakeholders must evaluate whether their outsourcing strategy balances speed-to-qualification against the emerging requirement for longitudinal biomarker data repositories that support post-market surveillance obligations.
Market Dynamics
The convergence of multi-omics data generation with FDA biomarker qualification mandates is compressing sponsor timelines while elevating technical requirements for contract partners. This structural pressure favors CROs with integrated bioinformatics-to-clinical validation pipelines over fragmented service providers.
Growth Catalysts
- FDA Biomarker Qualification Program:Sponsors accelerate outsourcing to partners with established qualification track records, reducing internal regulatory risk.
- Mass spectrometry proteomics:Platform sensitivity advances enable discovery of low-abundance circulating biomarkers previously undetectable in plasma samples.
- Boston-Cambridge biocluster concentration:Geographic proximity of pharma headquarters to specialized CROs shortens program initiation cycles.
Market Restraints
- GLP laboratory capacity scarcity:Validated facilities for regulated biomarker assays concentrate in the United States and Western Europe, limiting sponsor geographic flexibility.
- PhD-level bioinformatics talent shortage:Multi-omics data integration requires specialized computational biologists whose supply trails demand expansion.
- Longitudinal sample storage costs:Post-market surveillance obligations mandate biorepository maintenance that strains sponsor operating budgets.
Strategic Opportunities
- Autoimmune disease biomarker expansion:Precision medicine targets beyond oncology create new contract volume for fibrosis and inflammatory bowel programs.
- China NMPA clinical trial data integrity requirements:Western sponsors seek Asian-Pacific CRO partners with dual US-China regulatory expertise.
- Artificial intelligence and liquid biopsy convergence:Machine learning classification of circulating tumor DNA signatures reduces validation cohort sizes.
Industry Challenges
- Cross-platform data harmonization:Integrating genomics, proteomics, and metabolomics outputs from different instrument vendors requires standardization protocols that remain immature.
- IP fragmentation in biomarker panels:Patent thickets around specific gene signatures complicate freedom-to-operate analyses for composite diagnostic tests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomarker Discovery Outsourcing Services Market |
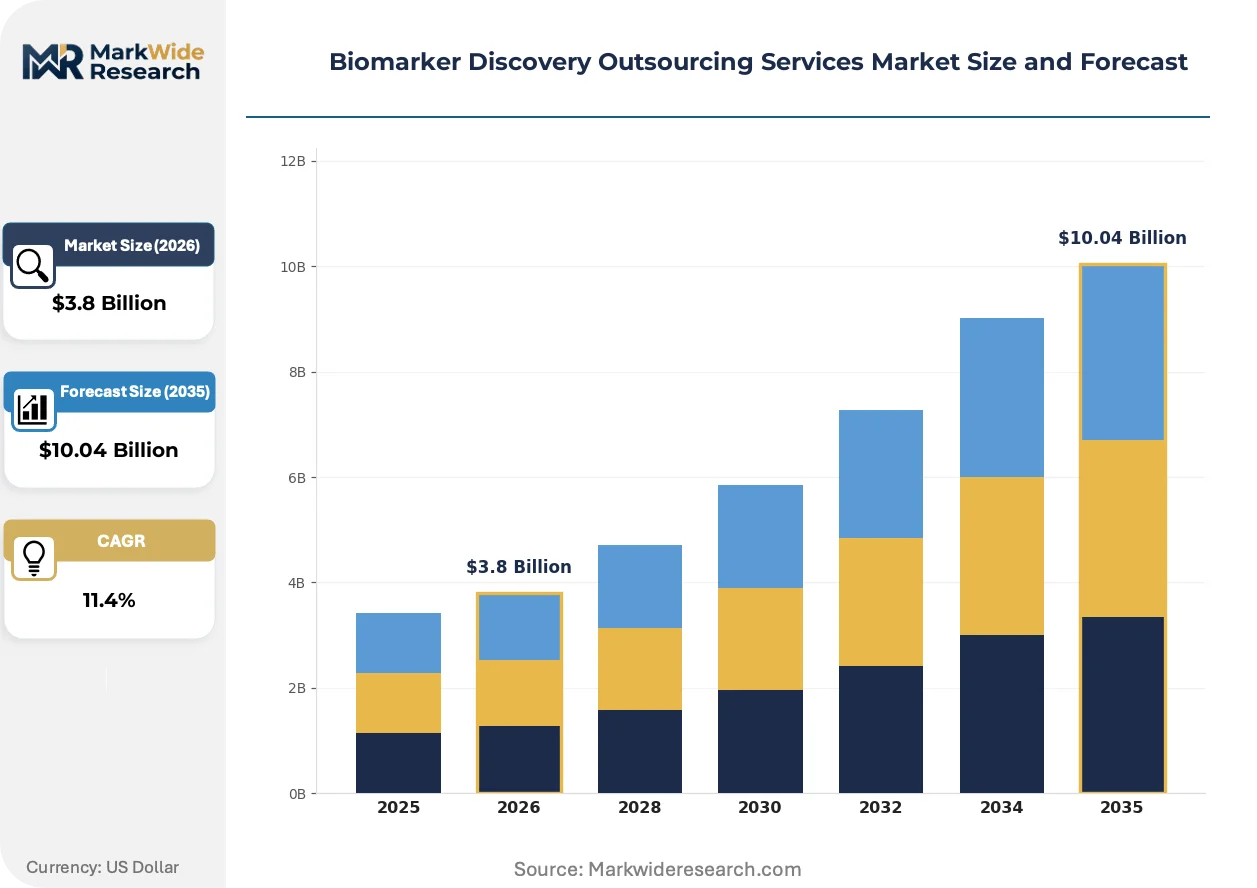
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Clinical Trials, Preclinical Studies, Data Analysis Technology: Genomic Sequencing, Proteomics, Imaging, Bioinformatics Application: Oncology, Cardiovascular, Neurology, Autoimmune End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotech Firms |
| Companies Covered | Laboratory Corporation of America Holdings (Labcorp), Charles River Laboratories International, Inc., Eurofins Scientific, Thermo Fisher Scientific Inc., ICON plc, Parexel International Corporation, Evotec, WuXi AppTec, Celerion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomarker Discovery Outsourcing Services Market Evolving Landscape
Biomarker discovery workflows are undergoing platform-level automation that restructures how sponsors configure internal versus external capabilities. Three developments dominate this transformation.
Cloud-native bioinformatics pipelines are automating the preprocessing of raw sequencing and mass spectrometry outputs into analysis-ready matrices. Mid-size biotech sponsors lacking in-house computational infrastructure adopt these platforms fastest, compressing the traditional six-month analytical setup phase into weeks. This automation is automating the manual curation steps that previously consumed half of discovery program timelines.
EMA's parallel scientific advice pathways now permit simultaneous biomarker qualification consultation across multiple jurisdictions. Sponsors leverage this regulatory convergence to design single validation studies satisfying both FDA and EMA requirements, reducing redundant clinical sample collection. Oncology programs with companion diagnostic ambitions utilize this mechanism most intensively, restructuring CRO selection criteria around multi-regulatory track records.
Fixed-fee biomarker discovery contracts are displacing traditional time-and-materials arrangements for well-characterized target classes. Sponsors with mature target biology knowledge now demand outcome-based pricing tied to assay validation milestones rather than labor hours. This shift concentrates contract awards among CROs with standardized platform workflows capable of predictable cost estimation.
Biomarker Discovery Outsourcing Services Market Segmentation
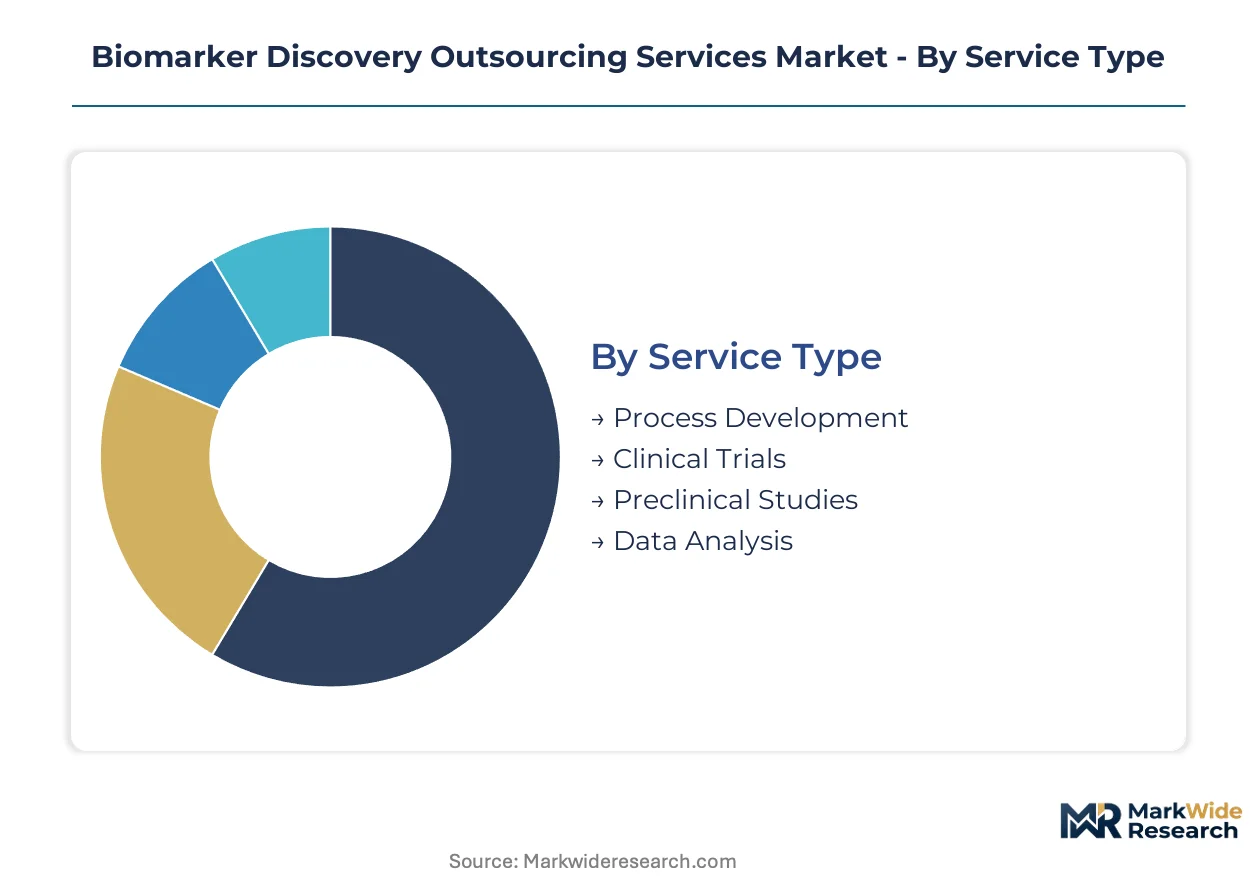
Biomarker discovery outsourcing services fragment across four dimensions that determine technical requirements, regulatory pathways, and pricing structures. Sponsors configure vendor portfolios differently depending on whether they prioritize speed-to-IND, biomarker qualification, or companion diagnostic development.
Service Type:
Service selection tracks the maturity of a sponsor's biomarker program, with established pipelines upgrading from exploratory data analysis toward GLP-validated clinical deployment.
- Clinical Trials:Phase II-III biomarker integration mandates from FDA and EMA drive contract volume here. Pharmaceutical sponsors in the United States concentrate demand for patient stratification and efficacy endpoint validation, particularly in oncology programs requiring companion diagnostic co-development.
- Process Development:Assay optimization for regulated environments consumes significant analytical resources. Biotech firms without captive GLP infrastructure outsource platform transfer and validation to CROs with established quality management systems.
- Preclinical Studies:Early target engagement biomarker identification for IND-enabling toxicology programs.
- Data Analysis:Multi-omics integration and statistical modeling for biomarker signature refinement.
Volume placements concentrate in Clinical Trials; the faster expansion belongs to Process Development.
Technology:
Technology adoption correlates with target class complexity, with protein-level measurements displacing genomic screening where post-translational modifications govern disease mechanisms.
- Proteomics:Mass spectrometry sensitivity advances now detect low-abundance circulating biomarkers in plasma samples previously below detection thresholds. Boston-Cambridge biocluster sponsors drive contract concentration for oncology protein signature discovery.
- Bioinformatics:Cloud-native pipelines automate preprocessing of raw sequencing and mass spectrometry outputs into analysis-ready matrices. Mid-size biotech sponsors lacking computational infrastructure adopt these platforms most aggressively, compressing analytical setup timelines from months to weeks.
- Genomic Sequencing:Whole-exome and targeted panel sequencing for germline and somatic variant identification.
- Imaging:Radiomic and digital pathology biomarker extraction for spatial biology applications.
Revenue concentration sits with Proteomics; Bioinformatics gains share fastest as dataset complexity outstrips in-house analytical capacity.
Application:
Application demand reflects precision medicine pipeline priorities, with solid tumor programs commanding initial contract volume and inflammatory conditions emerging as expansion targets.
- Oncology:Companion diagnostic development and patient stratification biomarkers absorb the greatest contract value. FDA biomarker qualification program participation concentrates here, with sponsors seeking CRO partners with established oncology validation track records.
- Autoimmune:Fibrosis and inflammatory bowel disease biomarker programs are gaining traction as precision medicine targets expand beyond solid tumors. EMA parallel scientific advice utilization is accelerating for these indications.
- Cardiovascular:Risk stratification and therapeutic response biomarkers for heart failure and atherosclerosis programs.
- Neurology:CNS penetration and neurodegenerative progression biomarkers for Alzheimer's and Parkinson's drug development.
Contract value concentrates in Oncology; Autoimmune shows the steepest expansion trajectory as pipeline diversification accelerates.
End User:
End-user configuration determines contract structure, with pharmaceutical sponsors demanding integrated bioinformatics-to-clinical validation pipelines and academic users prioritizing discovery-stage flexibility.
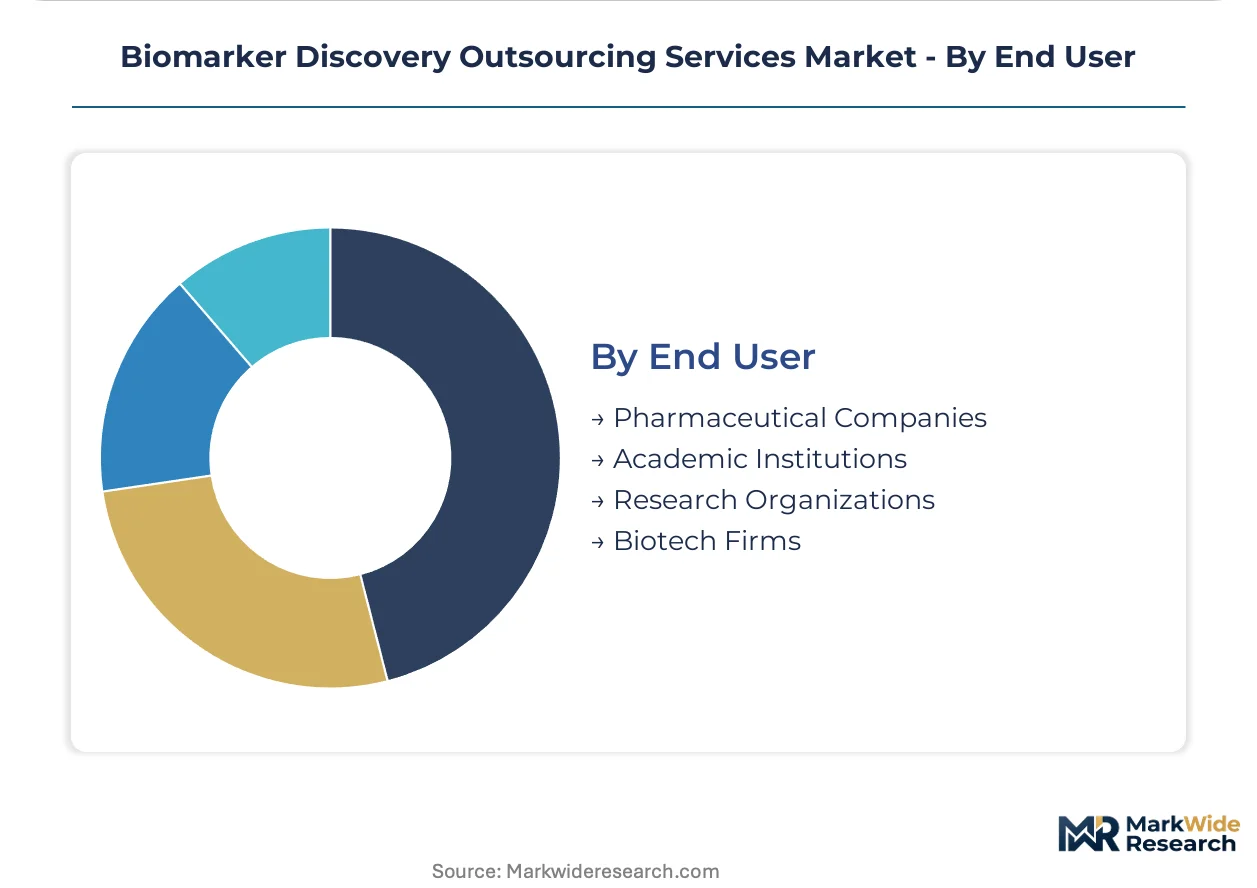
- Pharmaceutical Companies:Pipeline complexity and FDA qualification mandates drive the fastest-growing demand segment. Large sponsors favor fixed-fee arrangements tied to assay validation milestones rather than time-and-materials pricing.
- Biotech Firms:Asian-Pacific market access requirements and chemistry-manufacturing-controls adjacent services shape vendor selection. WuXi AppTec and comparable regional CROs capture disproportionate share here.
- Academic Institutions:Exploratory biomarker discovery with publication-driven timelines and flexible deliverables.
- Research Organizations:Government-funded multi-omics initiatives and consortium-based biomarker validation programs.
Pharmaceutical Companies anchor contract volume; Biotech Firms are climbing fastest as venture-funded precision medicine pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge generates the highest contract volume for discovery-stage biomarker programs, anchoring United States demand through concentrated pharma headquarters and specialized CRO proximity. Geographic proximity shortens program initiation cycles for sponsors seeking rapid assay validation.
United States
FDA biomarker qualification program participation and Phase II-III integration mandates drive sponsor outsourcing to GLP-validated partners. The agency's qualification guidelines elevate compliance burdens for multi-omics discovery programs. Boston-Cambridge and San Diego bioclusters concentrate contract awards among CROs with established oncology validation track records.
Germany
EMA parallel scientific advice utilization accelerates for autoimmune and fibrosis biomarker programs seeking simultaneous FDA-EMA qualification. EMA's ICH E16 harmonization standards reshape sponsor engagement with contract research partners. Munich and Heidelberg biotech corridors attract fixed-fee discovery contracts from mid-size European sponsors.
China
NMPA clinical trial data integrity requirements push Western sponsors toward Asian-Pacific CRO partners with dual US-China regulatory expertise. The regulator's evolving standards for multi-omics dataset submission elevate technical requirements for outsourced partners. Shanghai and Suzhou bioclusters dominate chemistry-manufacturing-controls adjacent biomarker services for regional biotech access.
Switzerland
Swissmedic's alignment with EMA qualification pathways positions Basel and Zurich as strategic locations for European biomarker validation. Precision medicine pipeline priorities from Roche and Novartis headquarters concentrate demand for proteomics and companion diagnostic co-development. The country's quality management infrastructure supports GLP-compliant assay transfer from discovery into regulated clinical deployment.
United Kingdom
MHRA post-Brexit regulatory convergence efforts with FDA and EMA create dual-track qualification opportunities for London and Cambridge-based sponsors. Academic research organization partnerships with CRUK and the Francis Crick Institute generate exploratory biomarker discovery volume. The Oxford-Cambridge arc sustains bioinformatics talent pools for multi-omics data integration services.
Biomarker Discovery Outsourcing Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integrated bioinformatics-to-clinical validation capabilities. The vendor base separates into three tiers: full-service CROs with diagnostic infrastructure, specialized proteomics laboratories, and distributed multi-jurisdictional testing networks. Consolidation pressure favors partners with longitudinal sample storage and post-market surveillance data repositories. Dominant competitive moves include strategic partnerships for AI-liquid biopsy convergence and fixed-fee contract structures displacing time-and-materials arrangements.
Within the integrated infrastructure tier, Laboratory Corporation of America Holdings and Charles River Laboratories International occupy positions anchoring high-complexity proteomics workflows. Eurofins Scientific exemplifies the distributed laboratory archetype across multiple regulatory jurisdictions. WuXi AppTec represents the Asian-Pacific access specialist for chemistry-manufacturing-controls adjacent services.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings (Labcorp) |
| Charles River Laboratories International, Inc. |
| Eurofins Scientific |
| Thermo Fisher Scientific Inc. |
| ICON plc |
| Parexel International Corporation |
| Evotec |
| WuXi AppTec |
| Celerion |
| Others |
Value Network & Pricing Analysis
PhD-level bioinformatics talent costs cascade from upstream recruitment markets through fixed-fee discovery contracts, compressing margins for CROs without automated cloud-native pipelines while concentrating pricing power among integrated platform providers with validated GLP infrastructure.
Pricing Analysis
Outcome-based pricing tied to assay validation milestones anchors contract structures for pharmaceutical sponsors with mature target biology. Three-tier pricing structure across premium, standard, and economy levels separates integrated bioinformatics-to-clinical validation providers from commodity screening services. Cost compression in the mid-tier intensifies because mid-size biotech sponsors adopt cloud-native pipelines aggressively. Academic institutions exhibit highest price sensitivity; large pharma sponsors with companion diagnostic ambitions demonstrate lowest sensitivity due to qualification timeline risks.
Supply Chain Analysis
Longitudinal sample storage and biorepository refurbishment flows create reverse-logistics complexity for post-market surveillance obligations. GLP-validated laboratory capacity concentrates in the United States, Germany, and Switzerland, drawing from specialized equipment vendors and cryogenic logistics providers. Single-source vulnerability sits with Massachusetts and California biocluster concentration for high-complexity proteomics workflows. Distribution runs through sponsor-direct CRO partnerships rather than intermediary channels, reflecting regulatory accountability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native bioinformatics pipelines are displacing legacy manual curation workflows, restructuring how sponsors configure internal versus external analytical capabilities across discovery programs.
For Market Incumbents: To counter fixed-fee contract displacement of time-and-materials arrangements, deepen automation of platform workflows and add captive biorepository capacity in Boston-Cambridge and San Diego corridors. Certification investment in dual US-EU quality management systems protects against sponsor migration to distributed multi-jurisdictional competitors. For New Entrants and Emerging Players: Launch via outcome-based pricing models targeting autoimmune disease biomarker expansion in Munich and Heidelberg biotech corridors. White-space concentration sits with fibrosis and inflammatory bowel programs seeking EMA parallel scientific advice. PhD-level computational biology talent scarcity creates entry opportunity through academic partnership channels. For Investors and Strategic Acquirers: FDA biomarker qualification program participation acceleration is the leading indicator that integrated diagnostic infrastructure will command premium multiples over fragmented service providers. Long-term viability frames toward CROs with longitudinal sample storage and post-market surveillance data repositories. Target acquisition archetype: mid-size proteomics laboratories with validated oncology track records and cloud-native pipeline integration.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Program Enrollment | FDA qualification track records reduce sponsor regulatory risk and accelerate contract awards. |
| Cloud-Native Bioinformatics Platform Integration | Automation compresses analytical setup timelines from months to weeks for mid-size biotech sponsors. |
| Dual US-EU Regulatory Certification Investment | EMA parallel scientific advice utilization requires established quality management systems across jurisdictions. |
| Longitudinal Biorepository Capacity Expansion | Post-market surveillance obligations mandate sample storage that strains sponsor operating budgets. |
| Autoimmune Disease Application Diversification | Precision medicine pipeline expansion beyond oncology creates new contract volume for fibrosis programs. |
Research Methodology
Document review covered FDA biomarker qualification guidelines, EMA ICH E16 harmonization standards, and ClinicalTrials.gov biomarker integration protocols, complemented by interviews with drug development executives, regulatory affairs leads, CRO program directors, and academic principal investigators. Secondary validation drew from SEC 10-K CRO disclosures, EMA parallel scientific advice records, and NMPA clinical trial data integrity circulars. Bottom-up service-type demand modeling and top-down end-user spending analysis enabled triangulation.
Segmentation outputs across service type, technology platform, therapeutic application, and end-user category were generated through structured elicitation with sponsor procurement teams. CAGRs were derived from regression analysis of historical contract value trajectories against biomarker qualification program participation rates and multi-omics dataset complexity indices. Forecast inputs incorporated mass spectrometry sensitivity advancement curves and cloud-native pipeline adoption rates across sponsor size tiers.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence-liquid biopsy convergence would alter the outlook for validation cohort size requirements and discovery timeline compression. Forecasts reflect sponsor budget allocation assumptions and regulatory pathway convergence between FDA and EMA. Material deviation in biomarker qualification program enrollment rates or GLP laboratory capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
India CRO Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
AI in Clinical Trials Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Global Clinical Trial Support Services Market